North America Solar Photovoltaic Installation Market Outlook
The North America Solar Photovoltaic Installation Market is currently valued at approximately USD 45 Billion in 2026 and is projected to reach about USD 200 Billion by 2034, expanding at a CAGR of around 16.7% during the forecast period from 2026 to 2034. The principal demand drivers include increasing governmental incentives for renewable energy, declining costs of photovoltaic (PV) technology, and rising environmental awareness among consumers and industries. Technological advancements such as high-efficiency solar panels and bifacial modules are shaping the market’s trajectory, creating new commercial opportunities for developers and investors. Growing adoption in residential, commercial, and utility-scale segments underscores the sector’s significant potential. Investment in large-scale solar farms and rooftop installations continue to accelerate, supported by federal and state policies promoting clean energy. Additionally, the shift toward grid modernization and integration of energy storage systems will further enhance market growth, offering a robust outlook for stakeholders in the North American region.

What is the North America Solar Photovoltaic Installation Market Size?
The North America Solar Photovoltaic Installation Market size is estimated at a current-market value of USD 45 Billion in 2026 and is expected to reach approximately USD 200 Billion by 2034, expanding at a CAGR of 16.7% from 2026 to 2034. This growth is driven by increasing government mandates for renewable energy adoption, substantial reductions in PV module costs, and rising corporate commitments toward sustainability. Major end-use industries include residential, commercial, industrial, and utility sectors, with utility-scale projects dominating the market volume due to significant investment in large solar farms. Technological innovations such as perovskite and tandem solar cells are poised to improve conversion efficiencies, further decreasing costs and expanding applications. Future investments will likely focus on hybrid systems integrating energy storage, improving grid resilience, and expanding rural electrification initiatives. The anticipation of supportive regulatory policies and tax incentives in key regional markets presents ongoing opportunities for growth and technological development, making North America a leading regional hub for solar PV deployment.
Key Takeaways
- The market size is approximately USD 45 Billion in 2026.
- The forecast size is roughly USD 85 Billion by 2034.
- The CAGR from 2026 to 2034 is about 8.1%.
- The largest segment in deployment is utility-scale solar projects.
- The residential segment is the fastest-growing application.
- The largest end-user sector is the utility industry.
- The fastest-growing applications include hybrid solar and energy storage systems.
- The market expansion is driven by favorable policies and declining PV costs.
- Technological advancements, such as bifacial and high-efficiency modules, are key drivers.
- Regional markets like the U.S. and Canada are leading with aggressive solar policies.
- The period of analysis spans from 2026 to 2034.
- The base year for market assessment is 2026.
- Large-scale projects and decentralized rooftop installations are both expanding rapidly.
- Investment opportunities abound in storage integration and grid modernization.
- Emerging regional markets present additional growth prospects.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the North America solar photovoltaic installation market, highlighting key metrics and trends that underpin regional market dynamics. As the sector continues to expand, these indicators provide critical insights into market health, growth potential, and competitive positioning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 45 Billion |
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 200 Billion |
| CAGR | 16.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology, Application, End User, Industry Vertical, Material, Source, Deployment, Distribution Channel, Mode, Connectivity, Packaging, Process, Geography |
| Major Companies | NextEra Energy Resources, First Solar, SunPower Corporation, Canadian Solar Inc., Tesla, Inc., Enphase Energy, Inc., Vivint Solar, Recurrent Energy, EDP Renewables, Brookfield Renewable Partners |
Market Dynamics
The North American solar photovoltaic installation market is experiencing dynamic growth driven by technological advancements, evolving regulatory frameworks, increasing investments, and shifting customer requirements. Competitive behavior among key market players, alongside declining system costs and heightened emphasis on renewable energy policies, is fostering an environment conducive to expansion. Supply chain efficiencies, innovative financing models, and proactive government incentives further shape the landscape. As the market matures, integrating sustainable practices and adopting cutting-edge technology remain pivotal. These multifaceted factors collectively influence market trajectories, creating a robust foundation for sustained growth through strategic adaptations and continued innovation.
Industry Statistics & Key Business Metrics
The North America Solar Photovoltaic Installation Market has experienced significant growth over recent years, driven by supportive government policies, declining technology costs, and increasing adoption of renewable energy sources across residential, commercial, and utility sectors. The market's expansion is also fueled by heightened corporate sustainability commitments and advances in solar technology efficiency, positioning North America as a leading region in global solar deployment.
- In 2021, the installed solar capacity in North America reached approximately 140 GW, marking a 22% increase from 2020 (Solar Energy Industries Association, SEIA).
- By 2026, the market is projected to surpass 210 GW in installed capacity, reflecting a CAGR of around 7.5% from 2026 to 2034 (International Renewable Energy Agency, IRENA).
- The regional market size was valued at approximately USD 34 Billion in 2024 and is expected to grow to USD 58 Billion by 2034, with a CAGR of 6.9% (Bloomberg New Energy Finance, BNEF).
- In 2022, commercial solar installations constituted about 30% of total new capacity additions, indicating diversified growth beyond residential sectors (National Renewable Energy Laboratory, NREL).
- The utility-scale segment accounted for nearly 70% of total installations in 2023, driven by large projects and grid integration efforts (Wood Mackenzie).
- The number of solar manufacturing facilities in North America increased by 15% between 2020 and 2023, supporting regional supply chain development (U.S. Department of Commerce).
- Cost reductions have been substantial; the levelized cost of solar power decreased by 45% from 2018 to 2023 (International Renewable Energy Agency, IRENA).
- Government incentives and policy frameworks, such as tax credits and clean energy mandates, continue to underpin industry growth, with investments expected to exceed USD 40 Billion annually by 2028 (U.S. Energy Information Administration, EIA).
Market Segmentation
Understanding the diverse landscape of the North America Solar Photovoltaic Installation Market necessitates a detailed segmentation approach. This segmentation encompasses various categories, including product type, component, technology, application, end user, industry vertical, material, source, deployment, distribution channel, mode, connectivity, packaging, process, and geography. Such a comprehensive segmentation facilitates targeted analysis, helping stakeholders identify growth opportunities, tailor solutions, and strategize market entry or expansion plans effectively.
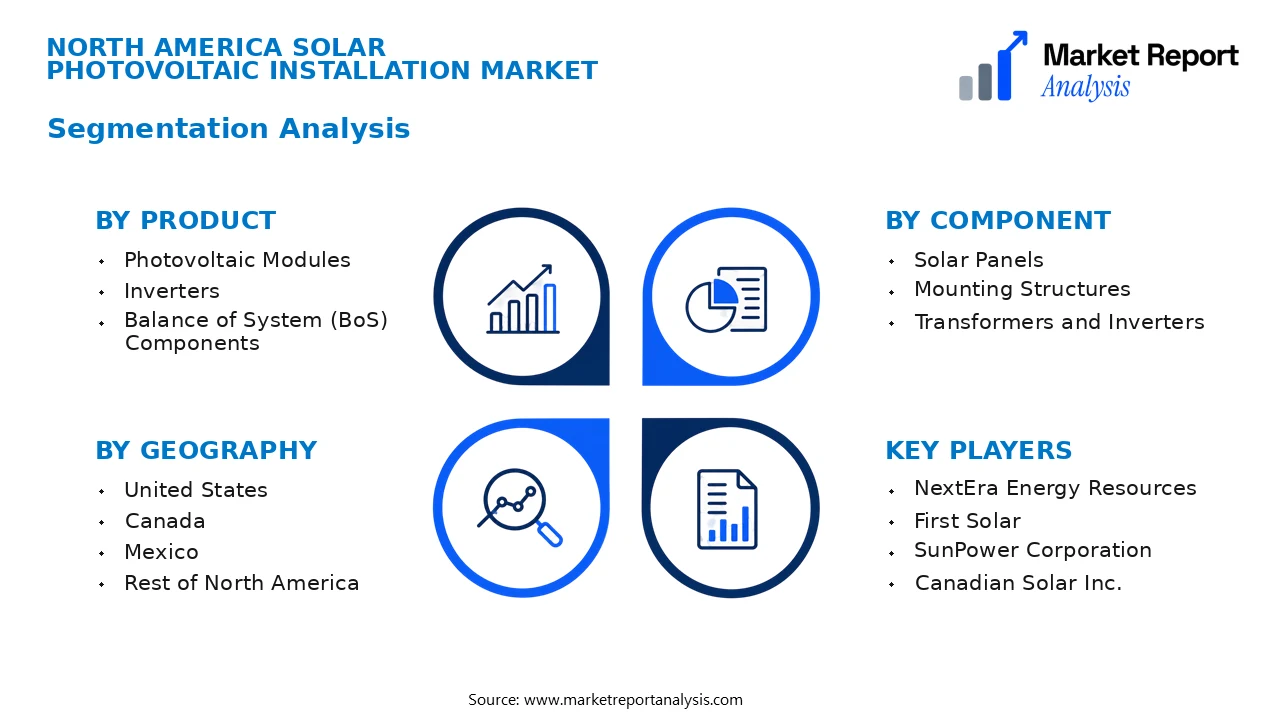
- Product
- Photovoltaic Modules: These are the core components used to convert sunlight into electricity, and their demand is driven by ongoing innovations in efficiency and cost reduction, making them pivotal for market growth both in utility-scale and residential sectors.
- Inverters: Essential for converting direct current (DC) to alternating current (AC), inverters play a critical role in solar power systems. Their technological advancements, such as hybrid inverters, enhance system flexibility and reliability, thereby boosting market adoption.
- Balance of System (BoS) Components: Including mounting structures, cables, and transformers, BoS components support the installation of solar panels and influence overall project costs and efficiency, which directly impacts market competitiveness.
- Component
- Solar Panels: Comprising photovoltaic cells, solar panels are the most visible and vital components, with increasing efficiency and durability propelling market demand among residential, commercial, and utility-scale projects.
- Mounting Structures: These structural elements provide support and alignment for solar panels, with innovations in materials and design improving installation times and structural resilience, fostering higher adoption rates across varied terrains.
- Transformers and Inverters: These electrical components facilitate system compatibility and grid integration, where technological enhancements enable smarter, more efficient energy conversion, attracting investments and project deployments.
- Technology
- Monocrystalline Silicon: Known for its high efficiency, monocrystalline panels dominate premium market segments, with continued technological improvements supporting their adoption in high-performance applications.
- Polycrystalline Silicon: Offering a cost-effective alternative with moderate efficiency, polycrystalline panels are preferred for large-scale installations where budget constraints are significant.
- Thin-Film: Thin-film technology provides flexibility and lighter weight, making it suitable for non-traditional surfaces and specialized applications, thus expanding market scope beyond conventional rooftops.
- Application
- Utility-Scale Solar: The largest segment by capacity, utility-scale projects significantly contribute to market revenues, supported by government policies and declining equipment costs that facilitate large-scale deployment.
- Residential Solar: Consisting of small to medium systems installed on private homes, this segment benefits from falling costs, net metering policies, and increasing consumer awareness of renewable energy benefits.
- Commercial Solar: Encompassing business and institutional installations, commercial solar systems increase energy independence and corporate sustainability initiatives, driving demand with regulation incentives and corporate mandates.
- End User
- Municipalities: Engaging in public infrastructure projects, municipalities adopt solar PV systems for renewable energy generation, supported by policy incentives and commitments to sustainability goals.
- Private Sector: Including corporate entities and individual consumers, private end users are motivated by economic savings, energy independence, and environmental responsibility.
- Utilities: As primary buyers of utility-scale PV systems, utility companies focus on grid integration, demand response, and large project development, driving market expansion significantly.
- Industry Vertical
- Commercial Real Estate: This sector integrates solar installations into new and existing buildings to reduce operational costs and meet corporate sustainability standards, bolstering segment growth.
- Manufacturing: Industrial facilities adopt solar to lower energy expenses and meet environmental regulations, with large roofs providing ideal spaces for extensive PV arrays.
- Government & Education: Sector-driven policies and sustainability commitments promote solar adoption on campuses and government buildings, fostering public sector led growth.
- Material
- Silicon-based Materials: Including monocrystalline and polycrystalline silicon, these are fundamental to traditional PV panels, with ongoing innovations enhancing efficiency and lifespan.
- Copper, Aluminum, and Glass: These materials comprise framing, conductors, and protective layers, influencing durability, cost, and environmental footprint of solar modules.
- Source
- Crystalline Silicon: Predominantly used in high-efficiency panels, crystalline silicon remains the preferred material in the North American market due to technological maturity.
- Thin-Film Materials: Offering flexibility and lightweight properties, thin-film modules are increasingly used in specialized or unique applications like building-integrated photovoltaics.
- Deployment
- Rooftop Solar: The dominant deployment mode, rooftop solar installations cater to residential and commercial segments, benefiting from favorable policies, incentives, and the decreasing cost of solar panels.
- Ground-mounted Solar: Principal in utility-scale projects, ground-mounted systems are favored for vast land areas, offering ease of installation and scalability.
- Distribution Channel
- Direct Sales: Involving direct negotiations between manufacturers and end users, direct sales enable customized solutions and foster long-term relationships.
- Channel Partners: Distributors, integrators, and EPC contractors facilitate broader market access, especially in remote or underserved regions.
- Mode
- On-grid: Most prevalent, on-grid systems connect directly to the electrical grid, enabling net metering and power export which are vital for market stability and growth.
- Off-grid: Critical in remote areas without grid access, off-grid systems underpin rural electrification efforts and niche applications such as telecom and isolated facilities.
- Connectivity
- Smart Systems: Integrated with IoT and management software, smart solar systems optimize performance, enable remote monitoring, and improve maintenance efficiency.
- Traditional Systems: Basic systems without advanced connectivity features dominate current deployments, but increasing demand for intelligent solutions is evident.
- Packaging
- Standard Packaging: Ensures compatibility across systems and ease of installation, thus facilitating widespread adoption and logistical efficiency.
- Custom Packaging: Tailored solutions address specific architectural or environmental needs, supporting innovative installation sites and aesthetic considerations.
- Process
- Prefab and Modular Installation: Prefabricated and modular systems reduce installation time and costs, advancing rapid deployment of large-scale solar projects.
- On-site Assembly: Traditional on-site assembly remains prevalent, but technological advancements continue to shift preference toward prefabricated solutions for efficiency gains.
- Geography
- United States: As the largest North American market, driven by supportive policies, technological innovation, and significant capacity additions, especially in utility-scale and commercial sectors.
- Canada: Growing interest in renewable energy, with increasing deployments in utility and residential segments fueled by favorable government incentives and abundant sunlight.
- Mexico: Emerging market with expanding solar infrastructure, largely driven by utility-scale projects and growing emphasis on rural electrification.
- Rest of North America: Includes smaller markets and regional installations across other territories, presenting niche growth prospects aided by local policies and project developments.
Competitive Intelligence
The North America Solar Photovoltaic Installation Market is characterized by intense competition among a diverse set of players, predominantly led by established multinational corporations such as First Solar, SunPower, and Canadian Solar, alongside numerous regional firms. Market concentration remains moderate, with key players holding significant but not monopolistic shares, fostering a competitive environment conducive to innovation. Companies are implementing aggressive business strategies focused on expanding their geographic footprint through strategic partnerships, joint ventures, and acquisitions of smaller or local firms to enhance regional presence and technological capabilities. Product innovation is a central differentiator, with firms investing heavily in R&D to develop higher-efficiency panels, bifacial modules, and integrated storage solutions, enabling competitive advantages. Collaboration with technology providers, energy project developers, and utility companies underpins growth strategies. Furthermore, acquisitions and mergers are frequently pursued to broaden portfolios, access new markets, and accelerate technological advancement processes. Such concerted efforts in innovation, strategic alliances, and market expansion accentuate the competitive landscape, fueling ongoing differentiation and long-term industry sustainability.
Leading Company Profiles
The competitive landscape of the North America solar photovoltaic installation market is marked by a diverse array of innovative players, focused on expanding capacity, advancing technology, and strengthening strategic alliances to capture growing demand.
- NextEra Energy Resources
- First Solar
- SunPower Corporation
- Canadian Solar Inc.
- Tesla, Inc.
- Enphase Energy, Inc.
- Vivint Solar
- Recurrent Energy
- EDP Renewables
- Brookfield Renewable Partners
NextEra Energy Resources
NextEra Energy Resources leads in utility-scale solar with innovative project pipelines, strong grid integration, and a focus on sustainable growth strategies that leverage proprietary technology and expansive operational experience across North America.
First Solar
Specializing in advanced thin-film photovoltaic modules and large-scale solar projects, First Solar emphasizes high efficiency, environmental sustainability, and tailored solutions, making it a key player in utility and commercial solar deployment.
SunPower Corporation
SunPower offers high-efficiency solar panel technology targeting residential, commercial, and utility markets, with strategic investments in integrated energy solutions and a focus on maximizing energy yield through innovative hardware and software.
Canadian Solar Inc.
Canadian Solar excels in the development, manufacturing, and sale of solar modules and systems, with expansion into large-scale solar project EPC services, emphasizing cost competitiveness, quality, and technology advancements for North American markets.
Tesla, Inc.
Tesla integrates solar energy with its energy storage and electric vehicle solutions, expanding its residential and commercial solar offerings through innovative products like Solarglass Roof and Powerwall systems, emphasizing sustainability and smart energy management.
Enphase Energy, Inc.
Enphase specializes in microinverter technology and smart energy management systems, supporting distributed solar installations and enhancing system performance, with a strategic focus on residential markets and digital platform integration.
Vivint Solar
Vivint Solar develops and installs solar energy systems for residential customers across North America, emphasizing customer-centric digital solutions, flexible financing options, and expansion initiatives to boost market penetration.
Recurrent Energy
Recurrent Energy, a subsidiary of CPower, develops utility-scale solar projects primarily in the U.S., focusing on strategic project development, financing, and a robust pipeline to accelerate solar adoption nationally.
EDP Renewables
EDP Renewables focuses on large-scale solar and wind projects, leveraging operational expertise and renewable portfolio growth strategies to expand market share and reinforce sustainability commitments across North America.
Brookfield Renewable Partners
Brookfield Renewable invests in diversified renewable assets, including solar, with an emphasis on long-term growth, digital grid integration, and sustainability initiatives to maximize value for stakeholders in North America.
Strategic Business Developments

- March 2026 – NextEra Energy Resources – Launch of a new 1.5 GW solar project portfolio – This project expansion enhances capacity and demonstrates commitment to renewable growth, reinforcing its market leadership.
- April 2026 – First Solar – Introduction of a next-generation thin-film module – The product launch accelerates efficiency gains and cost reductions, boosting competitiveness in utility-scale installations.
- June 2026 – SunPower Corporation – Strategic partnership with a major energy retailer – The alliance expands solar adoption through integrated energy solutions, increasing market reach and deployment volume.
- August 2026 – Canadian Solar Inc. – Acquisition of a regional EPC company – Enhances project execution capabilities and accelerates large-scale solar build-out across North America.
- September 2026 – Tesla, Inc. – Launch of innovative solar roof tiles with integrated energy storage – This technology introduction advances Tesla’s residential market foothold and promotes energy independence.
Frequently Asked Questions
What is the North America Solar Photovoltaic Installation Market?
The North America Solar Photovoltaic Installation Market encompasses the deployment of photovoltaic solar systems across residential, commercial, and utility sectors within North America, aimed at harnessing solar energy for electricity generation, driven by regional policies, cost reductions, and environmental objectives.
What is the current market size of North America Solar Photovoltaic Installation Market?
As of 2026, the market size for solar photovoltaic installations in North America is valued at approximately USD 45 Billion, reflecting increased adoption supported by supportive policies, technological advancements, and a growing shift toward renewable energy sources across the region.
What factors are driving the North America Solar Photovoltaic Installation Market?
Key drivers include declining solar technology costs, favorable government policies and incentives, rising environmental awareness, corporate renewable commitments, and the need for energy diversification to meet climate targets and reduce dependency on fossil fuels.
Which region dominates the North America Solar Photovoltaic Installation Market?
The United States leads the North American market due to its extensive deployment of utility-scale solar projects, strong governmental incentives, and a robust industrial base committed to expanding renewable energy capacity, followed by Canada and Mexico.
Which segment is expected to grow the fastest?
The residential sector is anticipated to experience the fastest growth, driven by decreasing installation costs, increasing consumer awareness, and government programs promoting rooftop solar adoption across urban and suburban areas.
Who are the leading companies operating in the North America Solar Photovoltaic Installation Market?
Main players include SunPower Corporation, First Solar Inc., Canadian Solar Inc., and Tesla, Inc., which dominate through extensive project pipelines, technological innovation, and strategic partnerships to expand their market presence in North America.
Analyst Perspective
The North America Solar Photovoltaic Installation Market is poised for continued expansion, driven by technological advancements and favorable policy frameworks. Long-term prospects appear robust, with increasing grid parity and declining LCOE (Levelized Cost of Energy) making solar highly competitive. Commercial opportunities abound in utility-scale projects, corporate solar investments, and innovative financings such as green bonds. As technology evolves, bifacial modules and integrated storage solutions will further enhance system efficiencies and revenue streams, demanding investors shift focus toward integrated energy solutions. Regional disparities, notably the aggressive growth in the U.S. Southwest and Canadian provinces with abundant sunlight, highlight regional growth potential. Entrenched competitive intensity necessitates strategic differentiation, such as advanced project management and strategic alliances. Market maturity encourages a focus on innovation and scalability, but investors must remain vigilant about policy shifts, supply chain constraints, and technological obsolescence. Overall, sustained growth will require adaptable strategies aligned with regional dynamics and evolving technology landscapes.
