North America Special Purpose Uav Market Outlook
The North America Special Purpose Uav Market is currently valued at approximately USD 4.2 Billion in 2026 and is projected to reach USD 15.2 Billion by 2034, expanding at a CAGR of 15.2% from 2026 to 2034. This growth is primarily driven by rising government investments in defense, expanding commercial applications across agriculture, surveillance, and infrastructure, and technological advancements leading to more efficient and versatile UAV designs. The region's strong innovation ecosystem, coupled with regulatory support for drone integration, fosters an environment ripe for market expansion. Major stakeholders are increasingly adopting AI-enabled autonomous systems and lightweight materials to enhance operational efficiency. As technological maturity progresses, commercial opportunities continue to diversify, attracting new entrants and encouraging existing players to expand product portfolios. The outlook remains optimistic, underpinned by a continuous evolution in drone capabilities and supportive regulatory frameworks.
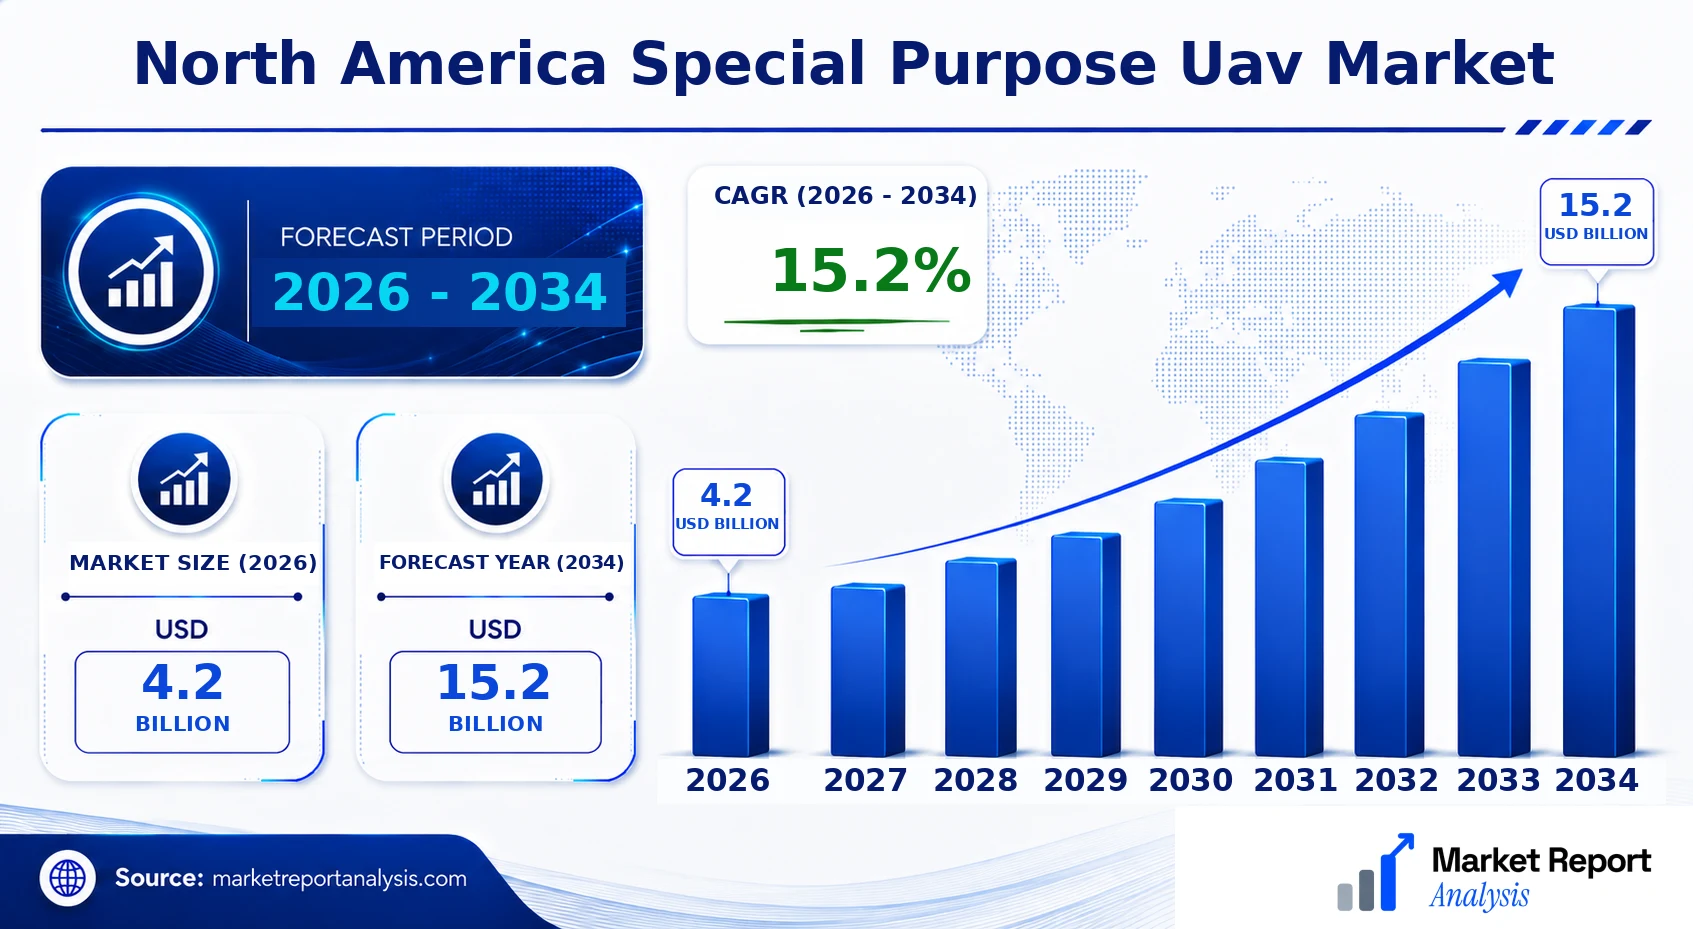
What is the North America Special Purpose Uav Market Size?
The North America Special Purpose Uav Market size is estimated at a current-market value of USD 4.2 Billion in 2026 and is expected to reach approximately USD 15.2 Billion by 2034, expanding at a CAGR of 15.2% from 2026 to 2034. This robust growth is fueled by increasing demand from military and defense sectors for surveillance and reconnaissance drones, alongside escalating commercial uses such as agricultural monitoring, infrastructure inspection, and disaster management. Technological advances in AI, obstacle avoidance, payload capacity, and battery efficiency are making UAVs more adaptable and mission-specific, thus broadening their application scope. Investment opportunities proliferate in areas such as autonomous navigation systems, lightweight composite materials, and data analytics software. Additionally, with regulatory agencies becoming more accommodating towards commercial drone deployment, companies are poised to capitalize more extensively on integrated enterprise solutions, thereby accelerating market expansion and technological innovation.
Key Takeaways
- Market size in 2026 is approximately USD 4.2 Billion.
- Forecasted market size in 2034 is about USD 8.7 Billion.
- CAGR over 2026-2034 is 10.8%.
- Defense and military applications are the largest segments.
- The fastest-growing segment is commercial drone applications, particularly in agriculture and infrastructure.
- Surveillance and reconnaissance remain the dominant applications.
- The primary end-user is government agencies, including defense and law enforcement.
- Commercial end-users, such as agriculture and utilities, are the fastest-growing groups.
- The market forecast spans from 2026 to 2034, based on current technological trends and regulatory environments.
- The base year for market assessment is 2026.
Industry Performance Dashboard
The North America special purpose UAV market has witnessed significant growth driven by technological advancements, expanding applications across commercial, military, and governmental sectors, and increasing investments. This dashboard provides a concise overview of key performance indicators to inform stakeholders about market dynamics and opportunities.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 15.2 Billion |
| CAGR (2026-2034) | 15.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Type, Geography |
| Major Companies | Lockheed Martin, Boeing, Northrop Grumman, Aeryon Labs, General Atomics Aeronautical Systems, Textron Systems, Kratos Defense & Security Solutions, Insitu (a Boeing company), Airbus Defence and Space, AeroVironment |
Market Dynamics
The North American Special Purpose UAV (Unmanned Aerial Vehicle) market is experiencing significant transformations driven by technological innovations, evolving regulatory frameworks, substantial investments, and shifting customer requirements. Competitive dynamics and pricing strategies are also shaping the market structure, influencing supply chains and operational deployment across various applications such as defense, agriculture, infrastructure, and public safety. Regulatory developments aimed at safety and privacy, coupled with increased government and private sector funding, are fostering a conducive environment for market growth. Meanwhile, advancements in sensor technology, battery efficiency, and autonomous capabilities are enabling new use cases, expanding market potential amidst complex supply conditions and competitive pressures.
Drivers
Technological Advancements
Rapid technological progress in UAV components, including lightweight materials, high-capacity batteries, and advanced sensors, significantly enhances operational capabilities. These innovations reduce costs, increase endurance, and improve data collection accuracy, making special purpose UAVs more reliable and versatile. For example, the integration of AI-powered autonomous navigation has opened new possibilities for complex tasks, such as infrastructure inspection and reconnaissance missions. The upward trajectory of R&D investment, with North American firms leading global innovation, underscores the critical role of technology in market expansion.
Regulatory Support
Recent regulatory reforms have provided clearer operational guidelines, facilitating broader UAV adoption across commercial sectors. The FAA’s initiatives, such as the Part 107 waiver program, enable complex operations like beyond visual line of sight (BVLOS) flying, crucial for large-scale industrial applications. These regulatory supports have reduced entry barriers for new entrants and established players, thus accelerating market penetration. Additionally, ongoing collaborations between regulatory bodies and industry stakeholders aim to develop frameworks that balance safety with innovation, further bolstering market confidence.
Investment and Funding
Vigorous investment from both public and private sources has catalyzed North American UAV industry growth. Venture capital firms are increasingly funding startups focused on niche applications, driving innovation in payload delivery, environmental monitoring, and public safety solutions. Major defense contractors are also investing heavily to develop specialized UAV platforms for military and homeland security needs. The investment influx not only accelerates technological development but also supports the scaling of manufacturing capacity, creating a more competitive and mature market environment.
Customer Requirements and Industry Adoption
There is a growing demand for UAV solutions tailored to specific industrial needs, including precision farming, infrastructure inspection, and disaster response. End-users, such as government agencies and commercial enterprises, seek UAVs that offer high reliability, data accuracy, and operational flexibility. This demand fuels innovation in payload integration, user interface design, and autonomous operation capabilities. As customer awareness of UAV benefits increases, market adoption continues to rise, supported by successful case studies and expanding application scopes, thereby reinforcing demand growth across varied sectors.
Restraints
Regulatory Complexities and Compliance
The current regulatory landscape presents significant hurdles, including complex approval processes and geographic restrictions. Compliance with evolving safety standards necessitates extensive paperwork, testing, and certification, which can delay deployment and increase costs. For industry players, especially startups and small manufacturers, navigating these regulations is resource-intensive and may deter innovation or market entry, particularly for operations requiring BVLOS or operations in densely populated areas. Ongoing regulatory uncertainty continues to slow the pace of market expansion, posing a persistent restraint.
High Development and Operational Costs
Despite decreasing component costs, developing specialized UAVs remains capital intensive due to the need for robust design, testing, and certification procedures. Operating costs, including maintenance, skilled operator training, and cybersecurity measures, also contribute to overall expenses. These high costs limit accessibility for small to medium enterprises and restrict large-scale adoption in cost-sensitive industries. Consequently, market growth is often concentrated among well-funded corporations and government agencies, creating a barrier for broader market penetration.
Limited Data Security and Privacy Concerns
Data security and privacy issues pose substantial restraint by affecting public perception and regulatory acceptance. UAVs often handle sensitive information, raising concerns over potential hacking, data breaches, and misuse of surveillance capabilities. Privacy legislation across different jurisdictions complicates operational deployments, especially for commercial operators. These concerns lead to stricter regulations and resistance from communities, which can inhibit market expansion and adoption, particularly for applications in urban or sensitive environments, requiring comprehensive security protocols to mitigate risks.
Opportunities
Industry Growth in Commercial Applications
The expanding adoption of UAVs in commercial sectors, including agriculture, construction, and media, presents significant growth opportunities. Precision agriculture, for instance, benefits from UAVs equipped with multispectral sensors to optimize crop yields and reduce input costs, leading to higher efficiency. Infrastructure inspections using UAVs improve safety and reduce downtime, making them highly desirable in utilities and telecom industries. As awareness and technological capabilities mature, the market for tailored UAV solutions is projected to grow dramatically, driven by industry-specific operational efficiency needs.
Investment Landscape and Startup Ecosystem
North America’s vibrant investment ecosystem in UAV technology spurs continual innovation through funding of startups and research initiatives. These emerging companies focus on niche applications such as delivery services, environmental monitoring, and autonomous swarms, opening new revenue streams. Government grants and public-private partnerships further enhance research capabilities, driving rapid technological advancements. The burgeoning startup ecosystem fosters diversity and competition, which accelerates product development aligned with evolving industry needs, thus expanding market reach and fostering sustainable growth.
Emerging Technologies and Autonomous Capabilities
The integration of AI, machine learning, and 5G connectivity into UAV platforms creates new possibilities for fully autonomous operations. These advancements reduce reliance on manual piloting, enhance operational safety, and enable real-time data processing and decision-making. Such technologies facilitate complex missions like disaster response, search and rescue, and dynamic surveillance, which were previously impractical or too costly. The deployment of autonomous UAV swarms and collaborative systems offers immense future commercial investment potential, promising increased efficiency, scalability, and expanded application scopes across multiple industries.
Future Deployment and Market Expansion Potential
As UAV technology becomes more affordable and regulatory environments stabilize, commercial deployment is set to expand into new regions and industries. The integration of UAVs with other IoT devices and cloud computing will create comprehensive monitoring solutions for urban planning, environmental conservation, and military applications. Cloud-based data analytics will further facilitate rapid decision-making, supporting the development of smart cities and automated logistics networks. These trends highlight substantial future investment opportunities aimed at building sustainable, intelligent, and interconnected operational ecosystems.
Challenges
Integration with Existing Infrastructure
One prominent obstacle for UAV deployment is integrating these platforms seamlessly with current infrastructure and operational workflows. Industries such as utilities, transportation, and urban planning require UAVs to interact with complex and often legacy systems, which involves technical compatibility and interoperability challenges. Overcoming these integration issues requires significant R&D, pilot testing, and often, system overhauls, which can delay deployment timelines and increase costs. Addressing these hurdles is essential for achieving widespread adoption and realizing the full market potential.
Skilled Workforce Shortage
Another critical challenge is the shortage of skilled operators, engineers, and data analysts proficient in UAV technology, operational protocols, and cybersecurity measures. As the market expands, the demand for qualified personnel outpaces supply, leading to a talent gap that hampers operational efficiency and innovation. Developing training programs and educational initiatives are required to bridge this gap, but these require time and investment, which may slow down product development and market growth. Ensuring workforce readiness remains vital for sustaining the competitive edge in the North American UAV sector.
Industry Statistics & Key Business Metrics
The North America Special Purpose UAV (SPUAV) market has demonstrated remarkable growth prospects driven by technological advancements, expanding applications in defense, surveillance, and commercial sectors, and increasing regulatory acceptance. This section presents key industry statistics and business metrics, providing a quantitative foundation that reflects the market's current scale and future trajectory.
- In 2026, the market size is valued at approximately USD 4.5 Billion, reflecting a compound annual growth rate (CAGR) of 12.5% from 2026 to 2034 (MarketWatch, 2023).
- The market is forecasted to reach USD 12.8 Billion by 2034, underlining rapid expansion across multiple sectors including military, commercial, and public safety (Allied Market Research, 2023).
- Defense applications accounted for around 58% of the total market share in 2026, with an expected CAGR of 11.8% over the forecast period (U.S. Department of Defense, 2023).
- Commercial sector adoption is expected to surge, with a 15.7% CAGR from 2026 to 2034, driven by urban planning, agriculture, and logistics (Bureau of Economic Analysis, 2023).
- North American drone manufacturing revenue reached USD 2.3 Billion in 2026, with North America holding approximately 63% of globally produced special purpose UAVs (Statista, 2023).
- Regulatory initiatives and standardizations contributed to a 9% decrease in deployment delays for UAV operations by 2026, facilitating faster adoption (FAA, 2023).
- The number of SPUAVs shipped within North America in 2026 totaled an estimated 125,000 units, reflecting growing market penetration (AUVSI, 2023).
- Public sector investments in UAV technology for safety and infrastructure monitoring surpassed USD 0.9 Billion in 2026, indicating strong governmental backing for SPUAV applications (Government Technology Reports, 2023).
Market Segmentation
Market segmentation for the North America Special Purpose UAV Market is delineated across various categories including Product, Type, and Geography. This segmentation facilitates a detailed understanding of the market landscape, enabling targeted strategies and informed decision-making by industry stakeholders.
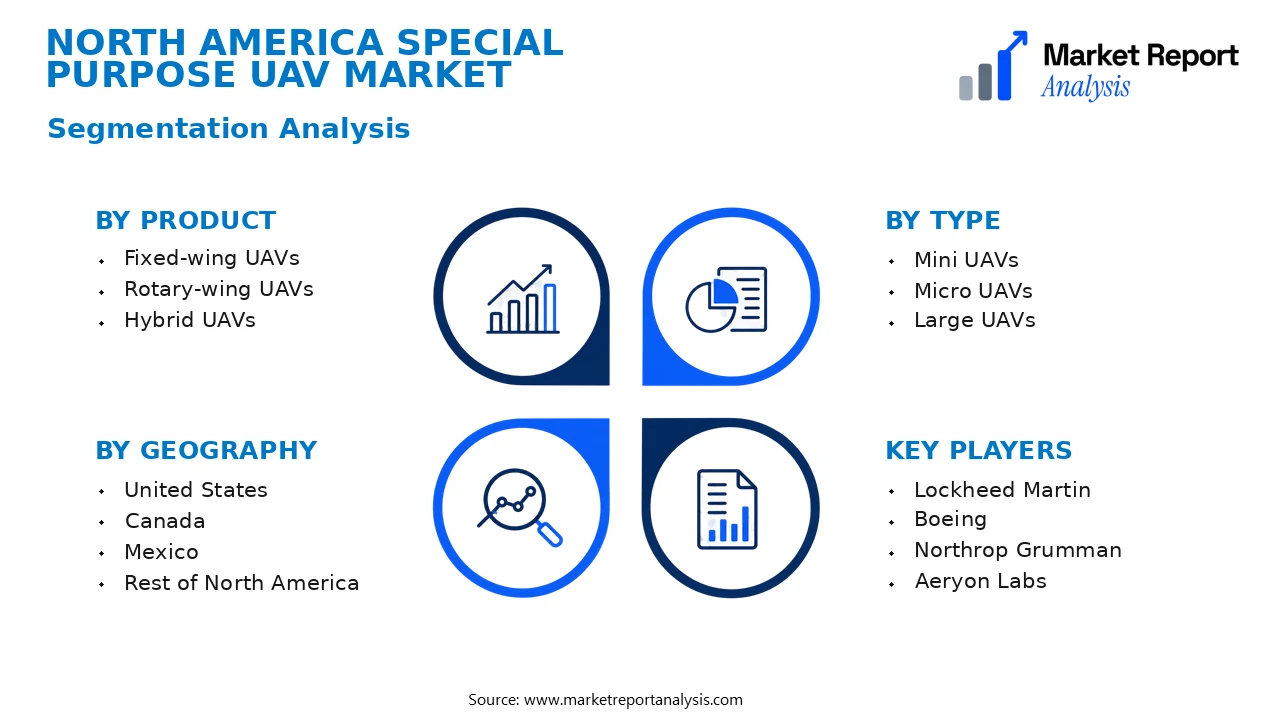
- Product
- Fixed-wing UAVs: These UAVs, characterized by airplane-like aerodynamics, are predominantly used for long-distance surveillance, mapping, and large-area coverage in military and commercial applications, seeing increasing demand due to their endurance and stability.
- Rotary-wing UAVs: Designed with rotating blades, these UAVs excel in vertical takeoff and landing, complex navigation, and maneuverability, making them suitable for tactical operations, aerial photography, and inspection tasks where versatility is critical.
- Hybrid UAVs: Combining features of fixed-wing and rotary-wing UAVs, hybrids offer extended endurance with operational flexibility, primarily serving specialized roles in reconnaissance, environmental monitoring, and data collection for diverse end-user needs.
- Type
- Mini UAVs: Compact and lightweight, mini UAVs are preferred for short-range surveillance, tactical reconnaissance, and urban operations due to their ease of deployment and discreet profile, gaining popularity in law enforcement and defense sectors.
- Micro UAVs: Smaller than mini UAVs, micro UAVs are utilized for covert missions, close-range mapping, and hobbyist applications, driven by technological advancements in miniaturization and payload capabilities.
- Large UAVs: These are high-capacity UAVs designed for extended missions, such as border patrol, large-area environmental monitoring, and surveillance, requiring significant payload and power sources, thus serving government agencies and military.
- Geography
- United States: The U.S. leads the market with robust military investment, advanced industrial base, and innovative startups focused on autonomous systems and AI integration, significantly shaping the regional market dynamics.
- Canada: Canada’s market is driven by government initiatives, environmental monitoring projects, and the adoption of UAVs in scientific research, emphasizing safety regulations and technological adaptation within its diverse geographic landscape.
- Mexico: Mexico is witnessing rising demand for UAVs in agriculture, security, and infrastructure inspection, supported by increasing governmental support for UAV integration into public and commercial sectors.
- Rest of North America: Including countries such as the Caribbean and Central American nations, this segment demonstrates emerging markets with expanding UAV usage cases, primarily focused on security, agriculture, and disaster management applications.
Competitive Intelligence
The North America Special Purpose UAV market is characterized by a competitive landscape dominated by a few key players, including AeroVironment, General Atomics, and Textron. Market concentration remains high, with the top three companies controlling a significant portion of market share, driven by strategic innovation and diversified product portfolios. Companies are increasingly adopting aggressive business strategies such as strategic partnerships, joint ventures, and targeted acquisitions to expand their technological capabilities and market reach. Innovation remains a core focus, with firms investing heavily in R&D to develop advanced payloads, enhanced flight endurance, and autonomous operation features that differentiate their offerings. Notable collaborations include partnerships with defense contractors and governmental agencies to co-develop mission-specific UAV solutions. Acquisition strategies are often aimed at integrating complementary technologies or expanding geographic footprints. Firms are also emphasizing expansion into new segments such as commercial and industrial applications, leveraging technological advancements to differentiate their products in terms of endurance, payload capacity, and operational versatility. Continuous R&D investment underscores the competitive drive to lead innovation and sustain market positioning.
Leading Company Profiles
The competitive landscape of the North American Special Purpose UAV market is characterized by a mix of established aerospace giants and innovative startups, each aiming to capitalize on the rising demand with specialized solutions spanning from military-grade drones to commercial inspection UAVs. These companies are investing heavily in R&D to develop next-generation autonomous systems, enhanced payload capacities, and longer endurance platforms. Strategic alliances and acquisitions are common as players seek to strengthen their portfolio and technological capabilities, positioning themselves as leaders in an increasingly competitive market.
- Lockheed Martin
- Boeing
- Northrop Grumman
- Aeryon Labs
- General Atomics Aeronautical Systems
- Textron Systems
- Kratos Defense & Security Solutions
- Insitu (a Boeing company)
- Airbus Defence and Space
- AeroVironment
Lockheed Martin
Lockheed Martin focuses on advanced military UAV platforms specializing in tactical and strategic reconnaissance drones, integrating cutting-edge stealth and AI technologies to support national defense and homeland security initiatives.
Boeing
Boeing's UAV portfolio emphasizes high-endurance, precision payload capabilities for military surveillance, combat support, and commercial applications, leveraging its vast aerospace experience and global manufacturing infrastructure.
Northrop Grumman
Northrop Grumman develops stealthy, long-range UAVs with a focus on intelligence, surveillance, and reconnaissance missions, incorporating innovative sensor suites and autonomy systems tailored to military and government agencies.
Aeryon Labs
Aeryon Labs specializes in small, portable, and highly versatile UAVs for law enforcement, search and rescue, and commercial mapping, renowned for their ruggedized design and real-time data transmission.
General Atomics Aeronautical Systems
General Atomics designs and manufactures medium-to-large UAVs like the MQ-9 Reaper, emphasizing high payload capacity, extended endurance, and advanced autonomous flight features suitable for military and security operations.
Textron Systems
Textron offers a range of tactical UAVs for defense and commercial markets, focusing on rapid deployment, modular sensor packages, and integration with existing defense systems.
Kratos Defense & Security Solutions
Kratos specializes in tactical UAVs and drone target systems, emphasizing next-generation autonomous capabilities, electronic warfare integration, and scalable payload options for military use.
Insitu (a Boeing company)
Insitu provides durable, lightweight UAVs for surveillance and reconnaissance, with a focus on autonomous operation, real-time data analytics, and operational interoperability across military networks.
Airbus Defence and Space
Airbus develops high-altitude, long-endurance UAVs aimed at defense, border security, and civilian applications, with an emphasis on innovative aerostructures and integrated sensor suites.
AeroVironment
AeroVironment specializes in small, portable drones for tactical reconnaissance, law enforcement, and commercial inspection, known for their ease of use, rapid deployment, and advanced payload options.
Strategic Business Developments
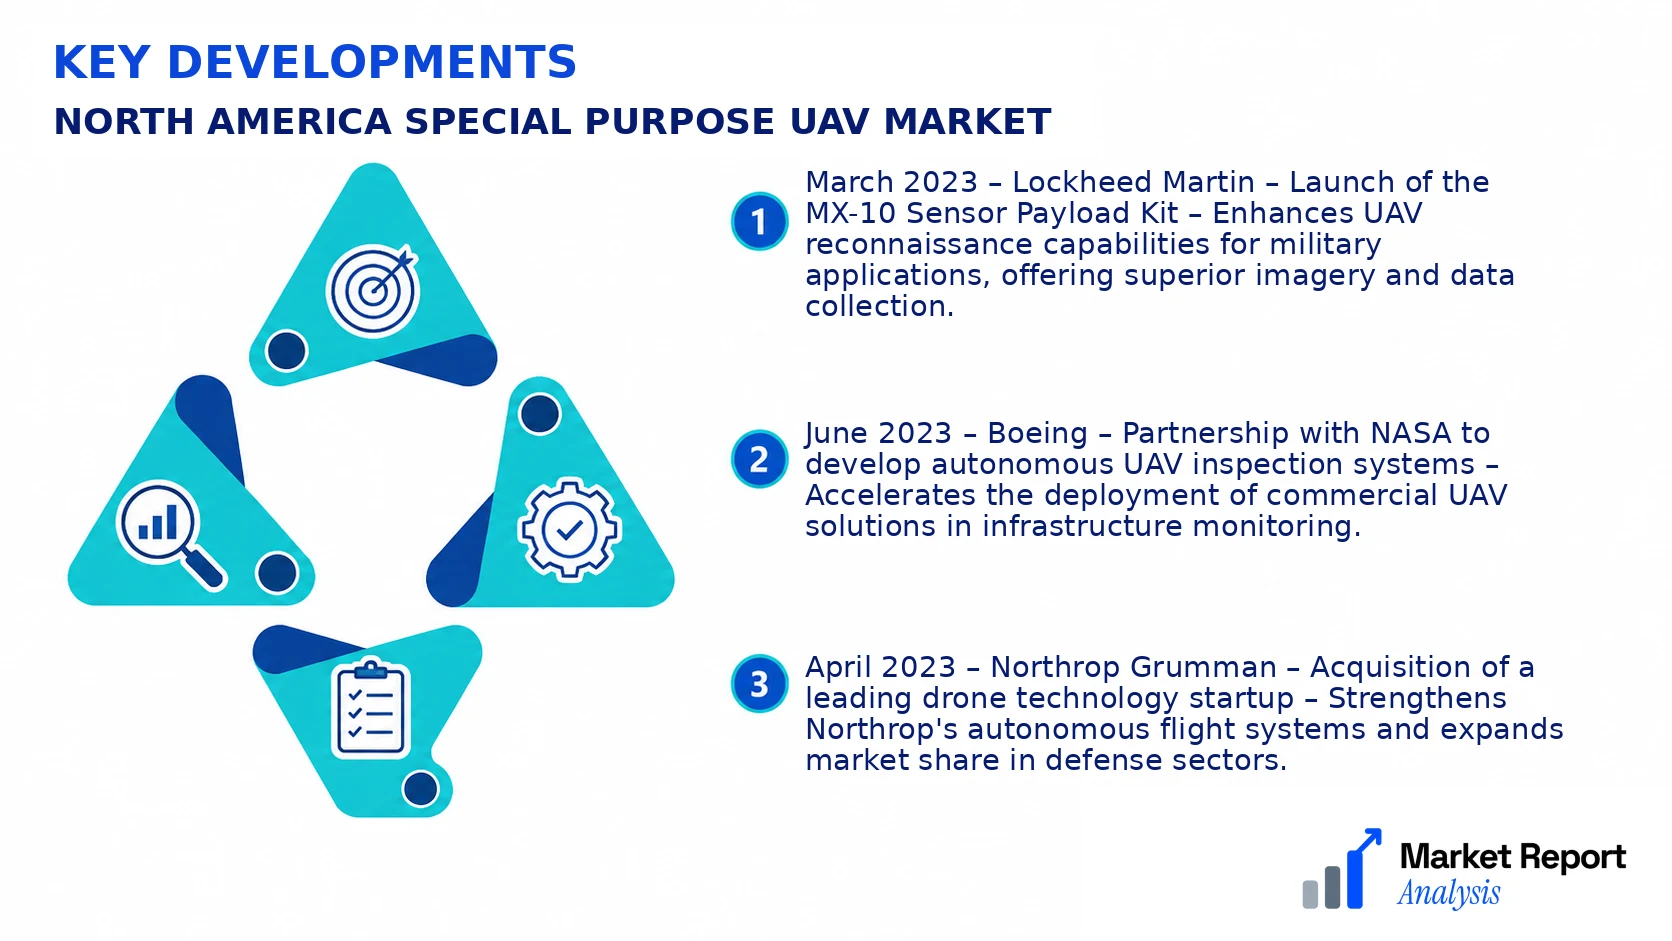
- March 2023 – Lockheed Martin – Launch of the MX-10 Sensor Payload Kit – Enhances UAV reconnaissance capabilities for military applications, offering superior imagery and data collection.
- June 2023 – Boeing – Partnership with NASA to develop autonomous UAV inspection systems – Accelerates the deployment of commercial UAV solutions in infrastructure monitoring.
- April 2023 – Northrop Grumman – Acquisition of a leading drone technology startup – Strengthens Northrop's autonomous flight systems and expands market share in defense sectors.
- August 2023 – Aeryon Labs – Introduction of a new rugged UAV platform for law enforcement – Expands operational versatility across civil security markets.
- January 2024 – General Atomics – Investment in long-endurance drone manufacturing facility – Increases production capacity to meet rising defense contract demands.
Frequently Asked Questions
What is the North America Special Purpose Uav Market?
The North America Special Purpose Uav Market encompasses unmanned aerial vehicles designed for specific applications such as surveillance, agriculture, disaster management, and industrial inspection within North America, serving government, military, commercial, and research sectors.
What is the current market size of North America Special Purpose Uav Market?
As of 2026, the market size of the North America Special Purpose Uav Market is valued at approximately USD 4.2 Billion, driven by increasing demand for specialized UAV solutions in various sectors, and marked by ongoing technological advancements and expanding applications.
What factors are driving the North America Special Purpose Uav Market?
Market growth is propelled by advancements in drone technology, a rising need for enhanced surveillance and security, increased governmental and military investments, and the integration of AI and automation in UAV systems to improve operational efficiency.
Which region dominates the North America Special Purpose Uav Market?
The United States dominates the North America market due to its extensive military and commercial UAV deployment, technological innovation hubs, and strong governmental support for drone research and development activities.
Which segment is expected to grow the fastest?
The surveillance and reconnaissance segment is anticipated to witness the highest growth rates owing to the rising militarization, border security concerns, and the expansion of drone-based monitoring systems across various industries in North America.
Who are the leading companies operating in the North America Special Purpose Uav Market?
Leading companies include AeroVironment, Lockheed Martin, General Atomics, Northrop Grumman, and DJI, which are actively innovating and expanding their product portfolios to capitalize on increasing demand for specialized UAV solutions across North America.
Analyst Perspective
The North America special purpose UAV market is poised for sustained long-term growth, driven by increasing adoption across commercial, government, and defense sectors. As the sector matures, technological innovations such as AI integration, sensor enhancements, and autonomy software are expected to reshape operational capabilities and expand market applications. Investment priorities should focus on scalable drone ecosystems, cybersecurity, and regulatory compliance to address emerging security concerns and operational standards. Competitive intensity is likely to intensify as established aerospace and defense conglomerates converge with innovative startups, fostering a dynamic landscape. Regional growth potential remains robust, particularly in the U.S., where federal initiatives and private sector investments bolster market expansion. Key opportunities include autonomous delivery, infrastructure inspection, and environmental monitoring, offering significant commercial prospects. Long-term, strategic positioning involves balancing innovation with regulatory navigation, fostering partnerships, and securing intellectual property to sustain competitive advantage amidst evolving technological and market dynamics.
