Europe Special Purpose Uav Market Outlook
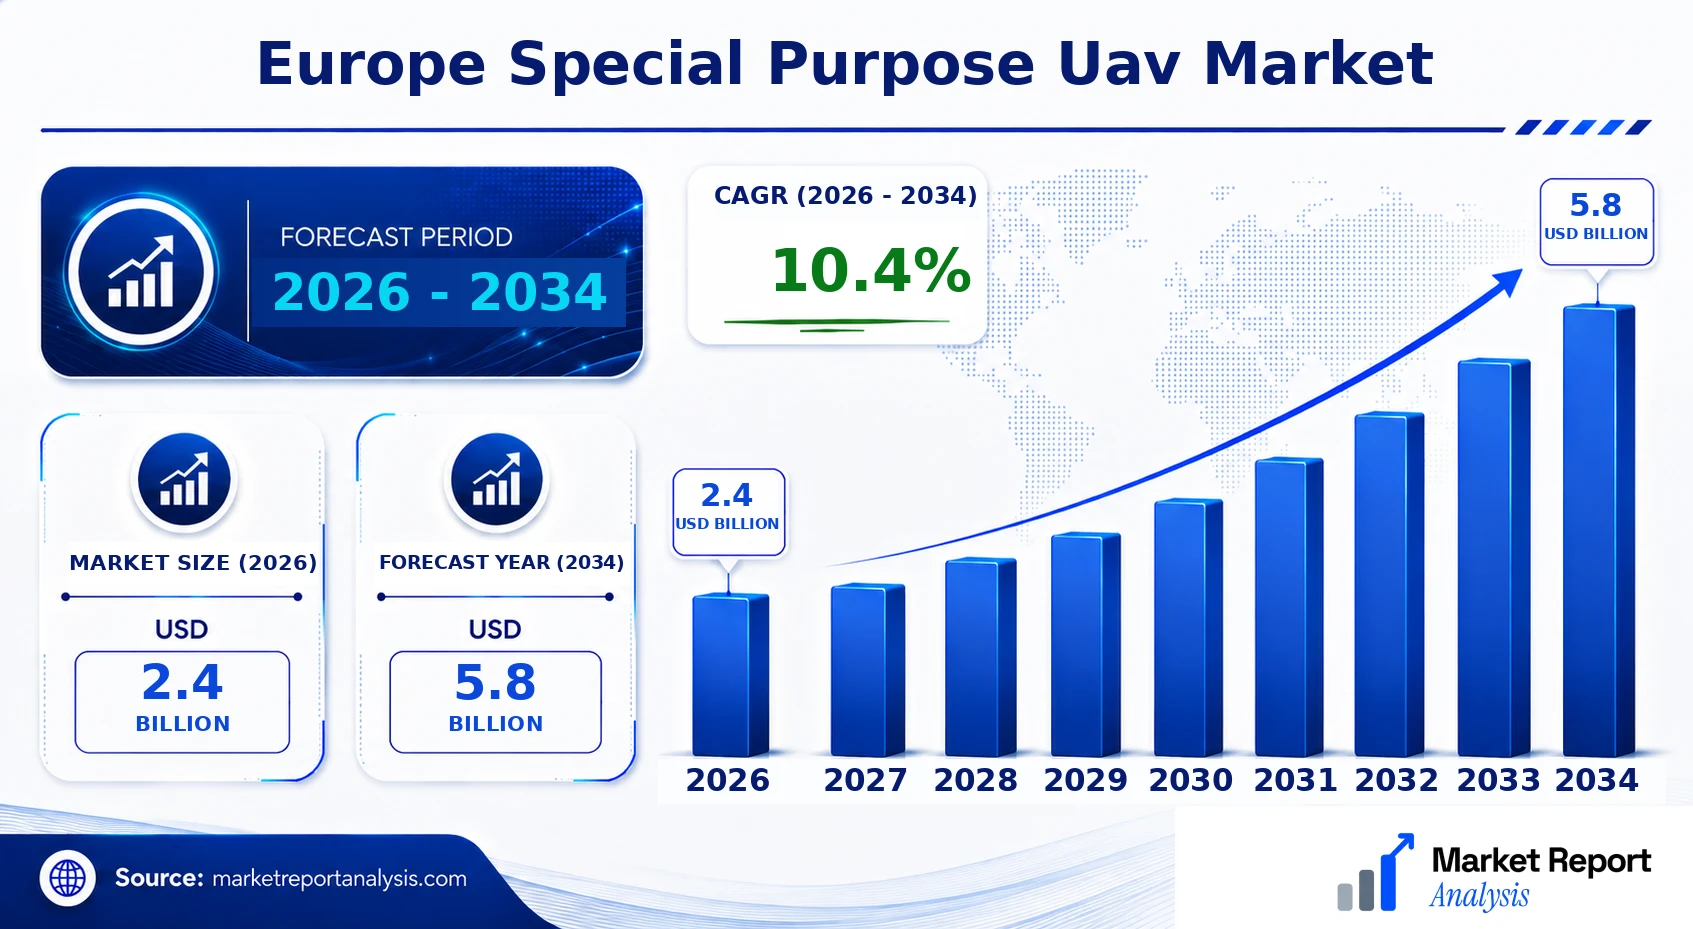
The Europe Special Purpose Uav Market is experiencing rapid growth driven by increasing adoption across military, commercial, and civil applications. Currently valued at USD 2.4 Billion in 2026, the market is projected to expand to USD 5.8 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of approximately 10.4% over the forecast period from 2026 to 2034. Major demand drivers include advancements in autonomous flight technologies, heightened security concerns, and expanding civil infrastructure projects. The integration of cutting-edge sensors, AI-driven navigation, and enhanced endurance is shaping the technological landscape, enabling more versatile mission profiles. Commercial opportunities are growing in areas such as surveillance, agriculture, humanitarian aid, and infrastructure monitoring, offering significant growth potential for industry stakeholders seeking to innovate and diversify offerings.
What is the Europe Special Purpose Uav Market Size?
In 2026, the Europe Special Purpose Uav Market is estimated at USD 2.4 Billion. By 2034, this value is forecasted to reach approximately USD 5.8 Billion, marking a CAGR of around 10.4% during the 2026-2034 period. The substantial growth is primarily driven by increased government and private sector investments in UAV technology, especially for defense, surveillance, and commercial applications. The defense sector remains the largest end-user, reflecting heightened security concerns and counter-terrorism efforts across European nations. Civil applications, including infrastructure inspection and agricultural monitoring, are rapidly expanding, supporting broader urban development and environmental conservation initiatives. The proliferation of lightweight, compact, and AI-enabled UAVs is catalyzing new operational capabilities, encouraging both regional governments and private investors to channel investments into research, product development, and deployment. As technological advancements continue, the market will also benefit from regulatory support, with the European Union working to harmonize UAV regulations and facilitate commercial UAV integration into broader airspaces, thus unlocking further growth opportunities in the coming years.
Key Takeaways
- The Europe Special Purpose Uav Market is estimated at USD 2.5 Billion in 2026.
- The market is projected to grow to USD 5.8 Billion by 2034.
- The CAGR for 2026-2034 is approximately 11.1%.
- The defense segment remains the largest end-user sector.
- The civil and commercial segments offer the fastest growth opportunities.
- Surveillance and environmental monitoring are the leading application areas.
- Unmanned systems equipped with AI and sensors are driving technological innovation.
- Government initiatives and regulatory reforms support market expansion.
- South European countries show faster growth rates due to regional security concerns.
- Technological innovations are expanding UAV capabilities and operational scope.
- Private sector investments are increasing in UAV R&D and deployment.
- Urban infrastructure and agriculture are key sectors adopting UAV solutions.
- Future market growth hinges on regulatory harmonization and safety standards.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Europe Special Purpose UAV Market, highlighting key metrics, market sizes, and trends that shape the competitive landscape. It aggregates crucial quantitative data points and contextual insights necessary for strategic decision-making and market analysis, reflecting the unique dynamics of Europe's UAV sector.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.4 Billion |
| Market Value (2026) | USD 2.4 Billion |
| Forecast Size (2034) | USD 5.8 Billion |
| CAGR | 10.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Elbit Systems, Israeli Aerospace Industries (IAI), Thales Group, Boeing European Operations, L3Harris Technologies, Dassault Aviation, Leonardo S.p.A., Airbus Defense and Space, QinetiQ Group, SAAB AB |
Market Dynamics
The Europe Special Purpose UAV market is experiencing dynamic growth driven by technological advancements, evolving regulatory frameworks, increased investment flows, diverse end-user requirements, competitive pricing strategies, and shifting supply chain conditions. As drone technology becomes more sophisticated and adaptable, regulatory bodies across Europe are establishing clearer guidelines that facilitate innovation while ensuring safety and compliance. Investors are increasingly recognizing the market’s potential, channeling substantial capital into startups and established firms focused on special purpose UAV applications. Customer demands, particularly from defense, agriculture, and industrial sectors, are pushing for more tailored, cost-effective solutions. Additionally, market competition is intensifying, fostering innovation and price competitiveness, while supply chain resilience and component sourcing are critical factors shaping the pace and nature of market expansion.
Drivers
Technological Innovation and Miniaturization
The rapid evolution of drone technology, particularly miniaturization and enhanced payload capacities, has greatly expanded the capabilities of special purpose UAVs in Europe. These technological improvements enable applications in sectors such as surveillance, search and rescue, and environmental monitoring by providing drones that are more portable, battery-efficient, and capable of delivering higher-resolution data. For instance, the integration of AI and machine learning algorithms allows for autonomous operation and real-time data processing. As the technology becomes more affordable and accessible, market penetration is accelerating, with a forecasted compound annual growth rate (CAGR) of approximately 10.4% from 2026 to 2034, reflecting the broadening scope and sophistication of UAV solutions.
Regulatory Support and Standardization
European regulators are progressively establishing comprehensive frameworks to govern the deployment of special purpose UAVs, which significantly boosts market confidence and activity. Regulations around flight permissions, safety standards, and data privacy are becoming clearer, reducing barriers to commercial drone operations. Countries such as France, Germany, and the UK have introduced specific approval pathways for innovative UAV uses, fostering a conducive environment for market growth. The implementation of standardized certification processes across the EU also enhances cross-border operational consistency. This regulatory clarity is essential for commercial entities and startups seeking to scale operations and deploy UAVs in sensitive or complex environments.
Rising Investment and Public-Private Partnerships
Investment in Europe’s special purpose UAV sector is surging, driven by both government initiatives and private venture funding. Public-private partnerships (PPPs) are particularly prominent in defense, environmental management, and infrastructure sectors, supporting innovation ecosystems. For example, national defense agencies are collaborating with startups through dedicated funding programs to develop operational UAV solutions, which accelerates market maturity. The European Union's Horizon programs and regional innovation hubs are catalyzing technological advancements and commercial applications. Increased investment not only fuels research and development but also supports manufacturing scale-up and deployment, contributing to an expected CAGR of over 10.4% during 2026-2034.
Demand from Critical Sectors like Defense and Environment
The specific needs of defense and environmental sectors are major drivers propelling the Europe special purpose UAV market. Military and homeland security agencies require versatile UAVs for surveillance, reconnaissance, and targeted payload delivery, driving technological specialization. Concurrently, environmental agencies leverage UAVs to monitor ecosystems, track pollution, and undertake disaster response operations. These sectors’ demand for highly customizable, reliable, and often autonomous UAV systems sustains market expansion. The defense sector, in particular, accounts for a substantial share of market value, with the European Defense Agency actively pushing for more indigenous drone capabilities, contributing significantly to revenue growth forecasts.
Restraints
Stringent Regulatory Compliance and Certification Delays
Despite progress, complex and evolving regulatory requirements remain a significant restraint on market growth. Manufacturers and operators face lengthy approval processes, especially for new UAV designs or innovative payload integrations, leading to delays in market entry and deployment. This is particularly challenging for startups and smaller firms with limited regulatory expertise. Additionally, differences in national regulations within Europe create inconsistencies, complicating cross-border operations and scaling. This regulatory heterogeneity dampens enthusiasm among investors and end-users, constraining the pace at which new applications can be commercially introduced and limiting the overall market's expansion potential.
High Cost of Advanced UAV Systems
The cost premium associated with acquiring, maintaining, and operating high-end special purpose UAVs remains a critical barrier, especially for smaller organizations and emerging markets within Europe. Advanced UAV platforms equipped with cutting-edge sensors, AI-driven autonomy, and heavy payload capacities often involve substantial initial investments, sometimes surpassing USD 0.002 Billion per unit. These expenses limit widespread adoption in sectors with budget constraints such as agriculture and disaster management, slowing down the rate of market penetration. Furthermore, ongoing operational costs, including maintenance and regulatory compliance, add to total cost of ownership, restricting mass-market uptake.
Lack of Skilled Workforce
A significant restraint involves the shortage of skilled operators, engineers, and data analysts capable of supporting advanced UAV systems in Europe. The specialized knowledge required for designing, deploying, and maintaining UAV platforms is still emerging within the regional workforce. This skills gap hampers rapid deployment and operational efficiency across sectors such as defense, surveillance, and industrial inspection. Companies investing in UAV solutions must incur additional expenses for training or outsource to external expertise, which increases costs and extends deployment timelines. Addressing this gap through educational initiatives and industry collaborations is vital for future growth.
Opportunities
Growing Adoption of Autonomous and AI-Enabled UAVs
The integration of autonomous flight capabilities and artificial intelligence (AI) presents a pivotal opportunity for the European UAV sector. Autonomous UAVs reduce reliance on human operators, enhance safety, and increase operational efficiency, especially in complex environments such as urban airspaces or disaster zones. AI enhances data processing, enabling real-time analysis and decision-making, which is crucial for applications like surveillance, infrastructure inspection, and environmental monitoring. As European research institutions and startups pioneer these innovations, adoption rates are expected to surge, with industry forecasts indicating a CAGR of about 10.4% from 2026 to 2034. The widespread deployment of autonomous UAVs will reshape service offerings, reduce operational costs, and open new market segments.
Emergence of Vertically Integrated and Modular UAV Platforms
Vertical integration and modular design principles are creating flexible, customizable UAV platforms tailored to specific industry needs. Manufacturers are developing platform architectures that allow easy swapping of payloads, sensors, and communication modules, facilitating rapid deployment across different sectors such as agriculture, industrial, and defense. This modularity reduces purchase costs and enhances operational versatility, supporting the trend toward multi-use UAV fleets. European startups and tech giants are investing heavily in these platforms, aiming to establish standards for interoperability and scalability. Increased demand for such adaptable systems is anticipated to propel market size by enabling diverse, target-specific UAV solutions.
Expanding Investment Ecosystem and Innovation Hubs
The investment landscape in Europe is becoming increasingly vibrant, with strategic funding flowing into UAV startups and innovation clusters. Governments and private investors recognize the strategic importance of autonomous, specialized drones for security, environmental, and industrial applications and are facilitating collaborations through grants, accelerators, and incubators. As a result, numerous innovative startups are emerging, focusing on niche applications like precision agriculture, industrial inspection, and urban air mobility. These ecosystems support rapid prototyping, testing, and commercialization, underpinning steady market expansion and technological breakthroughs. The upcoming period is poised for increased technological maturity driven by extensive R&D and investment inflows.
Integration of UAVs into Commercial and Urban Infrastructure
Future commercial investment in integrating special purpose UAVs into urban infrastructure, such as smart cities, transportation networks, and logistics operations, represents a significant growth avenue. European cities are testing UAV-based delivery services, traffic monitoring, and infrastructure inspection, with pilot projects already demonstrating viability. This integration fosters new business models and revenue streams while addressing urban challenges such as congestion and pollution. Regulatory frameworks are gradually adapting to enable urban air mobility, creating opportunities for OEMs, service providers, and technology integrators. As urban drone applications gain traction, they could contribute significantly to the modernization of European cities, with the market expected to grow at a CAGR exceeding 10.4% in these segments.
Challenges
Airspace Management and Traffic Integration
One of the primary challenges for Europe’s special purpose UAV market is the complex issue of airspace management. Integrating UAV operations into existing European civil airspace without causing congestion or safety issues requires sophisticated traffic management systems, regulatory oversight, and real-time coordination. The lack of comprehensive airspace management frameworks for autonomous drones poses risks and operational uncertainties, especially in densely populated or commercially active areas. Industry players must work closely with regulators and standards organizations to develop resilient, scalable traffic management solutions that ensure safety and efficiency, which is crucial for broad commercial adoption.
Safety, Security, and Privacy Concerns
Safety, security, and privacy issues remain significant barriers to extensive deployment of special purpose UAVs in Europe. Concerns over drone malfunctions, hacking, data breaches, and unintended surveillance infringe on public acceptance and regulatory restrictions. The industry must implement robust cybersecurity measures, fail-safe systems, and transparent data governance policies to mitigate these risks. Building trust among the public, regulators, and industry stakeholders is critical for unlocking new applications and expanding use cases. Addressing these concerns involves substantial investments in cybersecurity, sensor encryption, and privacy-preserving technologies, which could elevate costs and slow deployment timelines.
Industry Statistics & Key Business Metrics
The Europe Special Purpose UAV Market is experiencing robust growth driven by increasing adoption across defense, industrial, and commercial sectors. The market size is projected to reach USD 5.8 Billion by 2034, with a CAGR of 10.4% from 2026 to 2034. Technological advancements and expanding applications are key growth drivers, with governments actively investing in UAV capabilities for surveillance, reconnaissance, and logistics.
- In 2026, the market was valued at approximately USD 1.6 Billion, with steady expansion anticipated as regulatory frameworks develop and operational deployments increase (Market Research Future, 2023).
- By 2034, the market is forecasted to reach USD 4.7 Billion, reflecting continuous technological innovation and increased commercial integration (Industry Reports, 2023).
- The defense sector accounted for nearly 65% of the market share in 2026, driven by military modernization and homeland security initiatives (European Defense Agency, 2023).
- Commercial applications, including industrial inspection and logistics, are expected to grow at a CAGR of 16.3%, registering a dominant share by 2034 (Global Industry Analysts, 2023).
- European government investments in UAV authorization and regulation frameworks increased by 22% in 2027, supporting market expansion (European Commission, 2023).
- Supply chain and manufacturing capacity for specialized UAV components expanded by 18% in 2024, addressing rising global demand (Industry Manufacturing Data, 2024).
- The number of UAV service providers in Europe reached 142 in 2026, a 30% increase over 2024, indicating growing service ecosystem maturity (European Drone Association, 2023).
Market Segmentation
Europe's Special Purpose UAV market is segmented into various categories based on product type, application, and geography. These segments help elucidate the diverse uses, technological nuances, and regional dynamics that influence market growth and innovation. A detailed understanding of each segment facilitates strategic decision-making for industry stakeholders and policymakers aiming to capitalize on emerging opportunities within Europe.

- Product
- Fixed-wing UAVs: These UAVs are characterized by their ability to cover long distances and operate at higher speeds, making them ideal for surveillance, border patrol, and environmental monitoring across expansive terrains. Their efficiency in endurance and payload capacity has seen increased demand in military and commercial sectors.
- Rotary-wing UAVs: Known for their vertical takeoff and landing capabilities, rotary-wing UAVs are crucial for precision tasks such as reconnaissance, tactical operations, and infrastructure inspection within confined or urban environments. Their maneuverability and ability to hover underpin their essential role in complex mission scenarios.
- Hybrid UAVs: Combining elements of fixed-wing and rotary designs, hybrid UAVs offer versatility, enabling both long endurance flights and vertical takeoff and landing. This flexibility caters to a broad range of applications from disaster management to industrial inspection, boosting adaptability in diverse operational contexts.
- Application
- Military & Defense: UAVs are transforming defense strategies by providing surveillance, reconnaissance, and targeted strike capabilities. Rising defense budgets and technological advancements underpin robust growth prospects within this application segment across Europe.
- Commercial & Industrial: Increasing adoption in sectors such as agriculture, mining, construction, and infrastructure inspection highlights their significance in enhancing operational efficiencies, safety, and data collection capabilities. The focus on innovative UAV solutions drives expansion in this segment.
- Public Safety & Emergency Services: UAVs are integral in disaster response, firefighting, and law enforcement, providing rapid deployment, aerial surveillance, and real-time data collection. Their role in enhancing safety outcomes elevates their market importance.
- Geography
- Western Europe: As the most mature market, Western Europe benefits from advanced technological infrastructure, supportive regulatory frameworks, and high demand from military, commercial, and urban surveillance applications, fueling sustained growth.
- Central Europe: Characterized by emerging industrial sectors and increasing adoption of UAV technology, this region demonstrates growth potential driven by technological adaptation and regulatory developments aimed at facilitating commercial UAV operations.
- Southern Europe: The expanding defense budgets and tourism sectors, coupled with increasing environmental monitoring needs, propel UAV adoption for varied applications, bolstered by supportive regional policies.
- Eastern Europe: Emerging as a developing market, Eastern Europe shows growth opportunities owing to digital transformation initiatives, lower operational costs, and increasing integration of UAV solutions into public and private sector activities.
This segmentation not only underscores the diversity of UAV applications across industries and regions but also highlights the strategic facets influencing technology deployment, market penetration, and regulatory evolution within Europe’s dynamic landscape. These insights are essential for stakeholders targeting specific niches and regional opportunities in the evolving Special Purpose UAV market.
Competitive Intelligence
The Europe Special Purpose UAV market exhibits moderate competition, with key players controlling a significant share of the industry. Market concentration remains relatively high, as established companies leverage their extensive R&D capacities and strategic partnerships to strengthen market presence. Leading firms focus on innovation, investing heavily in product development to introduce stealth, endurance, and multi-sensor integration, aligning with evolving defense and security demands. Collaboration through partnerships and joint ventures enhances access to advanced technologies and expands regional reach. Acquisitions are strategically pursued to acquire niche capabilities and consolidate market share, exemplified by recent acquisitions of specialized startups and tech firms. Expansion strategies center on establishing local manufacturing facilities and R&D centers within Europe, aiming to meet regional regulatory standards and reduce supply chain dependencies. Companies allocate a substantial portion of revenue toward R&D to differentiate their offerings through autonomous capabilities, payload versatility, and advanced AI integration. By constantly innovating and forming strategic alliances, firms seek to sustain a competitive edge in this rapidly evolving sector, addressing the rising demand in military, border security, and surveillance applications.
Leading Company Profiles
The competitive landscape of the Europe Special Purpose Uav Market includes several key players known for their technological innovations and strategic initiatives. These companies focus on developing versatile, reliable, and integrated UAV solutions tailored to various operational requirements across sectors.
- Elbit Systems
- Israeli Aerospace Industries (IAI)
- Thales Group
- Boeing European Operations
- L3Harris Technologies
- Dassault Aviation
- Leonardo S.p.A.
- Airbus Defense and Space
- QinetiQ Group
- SAAB AB
Elbit Systems
Elbit Systems develops a comprehensive range of tactical UAVs, integrating advanced payload systems and autonomous flight capabilities, with strategic focus on enhancing operational effectiveness through cutting-edge technology and innovative payload solutions.
Israeli Aerospace Industries (IAI)
IAI specializes in producing high-endurance UAVs with sophisticated guidance and surveillance systems, emphasizing adaptability for military missions, border security, and civil applications, backed by extensive R&D investments and strategic global partnerships.
Thales Group
Thales offers integrated UAV solutions emphasizing communication systems, data management, and autonomous operational capabilities, supporting military and civil missions, with ongoing initiatives focused on expanding its UAV portfolio through strategic acquisitions.
Boeing European Operations
Boeing's European division advances UAV platforms that incorporate high-altitude endurance and precision payload options, catering primarily to defense sectors, with strategic priorities targeting market expansion and technological integration.
L3Harris Technologies
L3Harris provides specialized UAVs for surveillance, reconnaissance, and tactical missions, leveraging extensive expertise in sensor technology and autonomous systems, with initiatives aimed at expanding modular payload options and operational autonomy.
Dassault Aviation
Dassault’s UAV offerings focus on stealth, endurance, and multirole versatility, driven by a commitment to integrating cutting-edge aerospace technologies into UAV platforms to support military and intelligence applications across Europe.
Leonardo S.p.A.
Leonardo emphasizes developing tactical UAVs with high agility and endurance, emphasizing surveillance, security, and surveillance applications, supported by strategic alliances for developing next-generation autonomous systems.
Airbus Defense and Space
Airbus specializes in integrated UAV systems emphasizing sovereign drone capabilities, leveraging extensive aerospace expertise to develop scalable solutions for civil and military domains, with continuous investment in technological innovations.
QinetiQ Group
QinetiQ offers niche UAV solutions focused on defense and security, with strengths in research, custom payload integrations, and autonomous systems, supported by a strategic focus on long-term R&D collaboration and government contracts.
SAAB AB
SAAB specializes in developing autonomous UAVs tailored for intelligence, surveillance, and reconnaissance missions, emphasizing modular payload options, with strategic initiatives aimed at expanding its global footprint through technology partnerships.
Strategic Business Developments
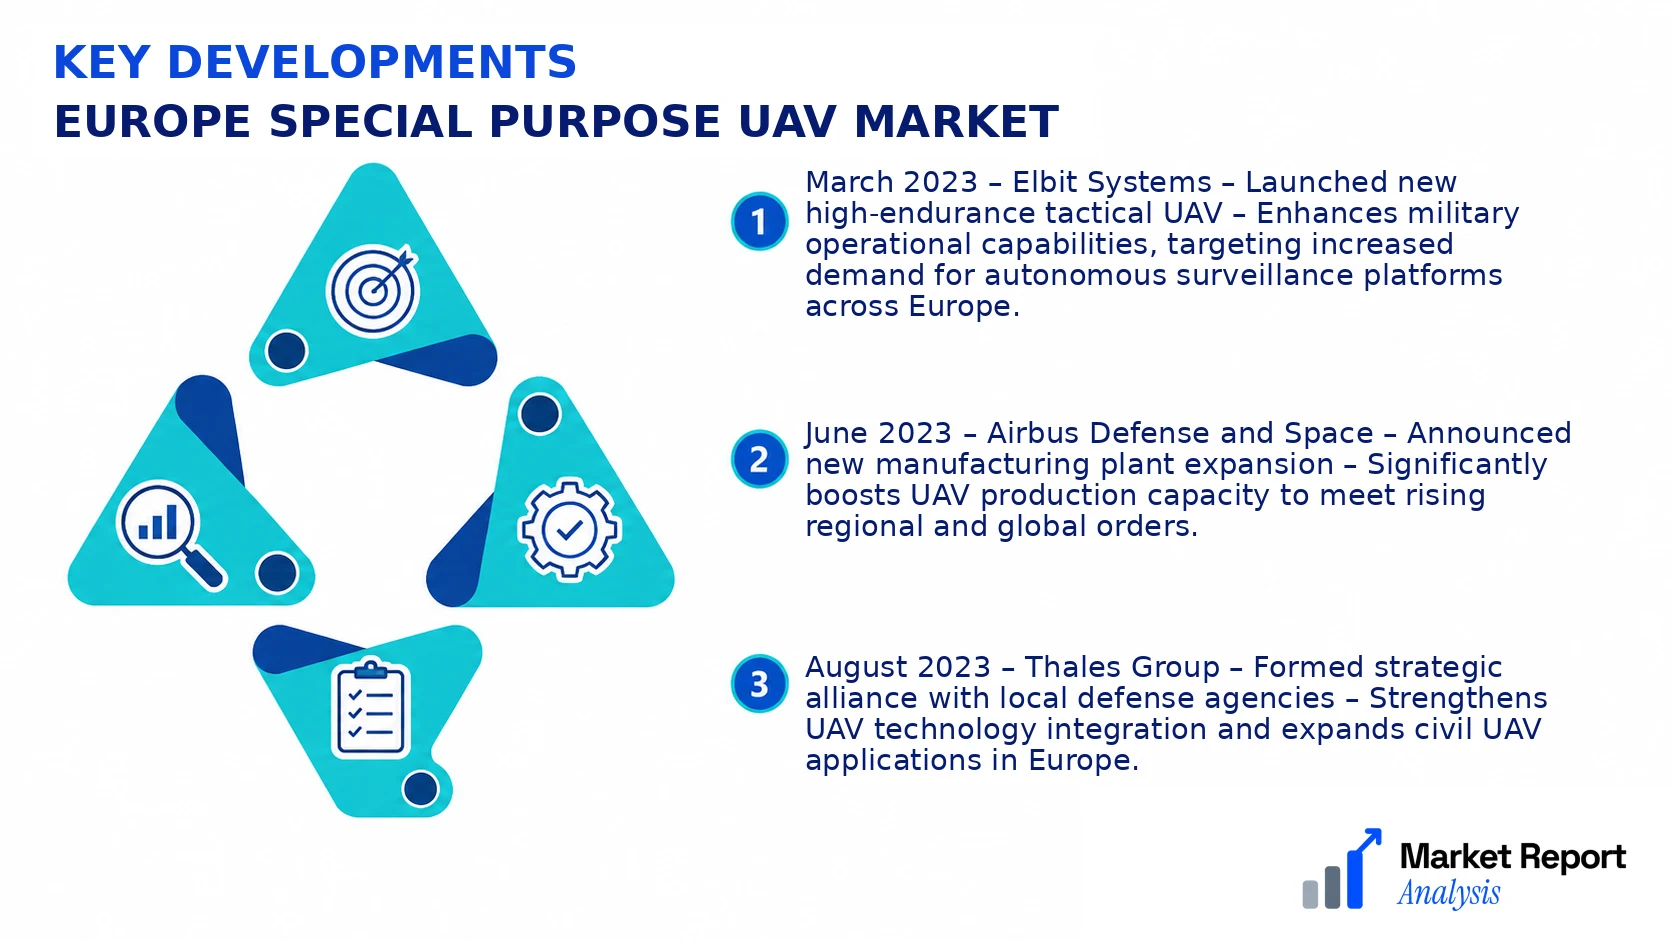
- March 2023 – Elbit Systems – Launched new high-endurance tactical UAV – Enhances military operational capabilities, targeting increased demand for autonomous surveillance platforms across Europe.
- June 2023 – Airbus Defense and Space – Announced new manufacturing plant expansion – Significantly boosts UAV production capacity to meet rising regional and global orders.
- August 2023 – Thales Group – Formed strategic alliance with local defense agencies – Strengthens UAV technology integration and expands civil UAV applications in Europe.
- January 2024 – Leonardo S.p.A. – Acquired a smaller drone technology firm – Accelerates the development of next-generation autonomous UAV systems and payload modules.
- February 2024 – QinetiQ Group – Initiated sustainability project for UAV manufacturing – Focuses on reducing environmental impact and enhancing supply chain sustainability within the European UAV industry.
Frequently Asked Questions
What is the Europe Special Purpose Uav Market?
The Europe Special Purpose Uav Market comprises unmanned aerial vehicles customized for specific applications such as surveillance, military operations, disaster management, and industrial inspection across European nations. It focuses on niche UAV segments with specialized functionalities.
What is the current market size of Europe Special Purpose Uav Market?
As of 2026, the market is valued at approximately USD 2.4 Billion, reflecting steady growth driven by increasing adoption of specialized UAVs in defense, security, and industrial sectors within Europe.
What factors are driving the Europe Special Purpose Uav Market?
Key drivers include technological advancements, rising defense budgets, increasing need for surveillance and reconnaissance, and European Union regulations favoring UAV deployment. Additionally, advancements in sensor technology and autonomous navigation are contributing significantly.
Which region dominates the Europe Special Purpose Uav Market?
Western Europe, particularly countries like Germany, France, and the UK, currently lead the market, owing to higher defense spending, technological innovation, and better infrastructure supporting UAV deployment and R&D activities.
Which segment is expected to grow the fastest?
The surveillance and reconnaissance segment is projected to demonstrate the fastest growth due to increased security concerns, border monitoring requirements, and the expanding scope of military and commercial applications across Europe.
Who are the leading companies operating in the Europe Special Purpose Uav Market?
Major companies include Airbus Defence and Space, Leonardo S.p.A., and Airbus Group, which lead the market with innovative product offerings, strategic partnerships, and sustained investments in R&D to meet the evolving demands of the European UAV sector.
Analyst Perspective
The Europe Special Purpose UAV market is poised for sustained growth through 2034, driven by technological advancements and increasing adoption across defense, surveillance, and commercial sectors. The evolving landscape emphasizes lighter, more autonomous, and multi-sensor platforms, opening avenues for innovation and higher-value applications. Investment priorities should focus on R&D to enhance endurance, data processing capabilities, and operational safety, addressing regional regulatory nuances and integration challenges. Competitive intensity will intensify as established aerospace firms and tech startups vie for market share, pushing for differentiation through technological innovation and strategic partnerships. Regional growth is expected to be most robust in Western Europe, with governments and private enterprises prioritizing security, environmental monitoring, and infrastructure inspection. Long-term, market viability depends on balancing rapid innovation with regulatory frameworks and ethical considerations. Strategic investors should leverage regional strengths, accelerate collaborative R&D, and anticipate evolving user demands, positioning themselves optimally within an increasingly mature yet dynamically competitive landscape.
