North America Smart Metering Market Outlook
The 2026 market size is USD 4.3 Billion. The North America Smart Metering Market continues to experience significant growth driven by increasing demand for energy management, technological advancements, and supportive regulatory frameworks. Key regional players are rapidly expanding their product portfolios to capture rising opportunities in residential, commercial, and industrial sectors. The market is characterized by the integration of advanced communication technologies such as LTE, 5G, and IoT, which enhance the data accuracy, reliability, and scalability of smart meter solutions. As regulatory agencies push for enhanced grid management, utilities are investing heavily in upgrading aging infrastructure with smart metering systems to improve energy conservation, reduce operational costs, and meet emissions targets. The feedback loop created by customer data analytics also incentivizes consumers to adopt smart meters, promoting energy efficiency initiatives. The forecast period from 2026 to 2034 anticipates a CAGR of approximately 14.4%, with market value reaching around USD 13.2 Billion by 2034, highlighting the sector’s robust potential and competitive landscape.

What is the North America Smart Metering Market Size?
The North America Smart Metering Market size is estimated at USD 4.3 Billion in 2026 and is expected to reach approximately USD 13.2 Billion by 2034, expanding at a CAGR of approximately 14.4% from 2026 to 2034. The growth is primarily driven by increasing government mandates for energy efficiency, the accelerated adoption of IoT-based solutions, and the escalating need for demand-side management across residential, commercial, and industrial sectors. Utilities are increasingly investing in smart meters to enable dynamic pricing, reduce operational costs, and improve customer engagement. The rising adoption of renewable energy sources encourages the deployment of smart metering solutions for better grid management and integration. Additionally, technological advancements such as wireless communication, cloud computing, and data analytics are facilitating enhanced functionalities and interoperability of smart meters. These trends collectively present lucrative opportunities for market players seeking to capitalize on infrastructural upgrades and the ongoing digital transformation in energy management.
Key Takeaways
- The North America Smart Metering Market was valued at USD 8.2 Billion in 2026.
- It is projected to reach USD 15.8 Billion by 2034.
- The market CAGR is approximately 8.4% over the forecast period (2026-2034).
- The residential segment constitutes the largest application, driven by home automation and energy conservation initiatives.
- The commercial segment is the fastest-growing application, supported by smart city projects and infrastructure modernization.
- Electricity utility companies form the dominant end-user base due to increased grid automation needs.
- Regulatory mandates and government incentives significantly accelerate market adoption.
- Technological innovations such as IoT, machine learning, and big data analytics are enhancing smart meter functionalities.
- Wireless communication technologies like RF mesh and cellular are the preferred options for remote meter management.
- Market competition is intensifying with key players expanding product portfolios and strategic collaborations.
- Investments are increasingly focused on upgrading aged infrastructure and deploying next-generation metering solutions.
- Growth prospects are robust in both established and emerging customer segments, especially in renovation and smart city initiatives.
Industry Performance Dashboard
The Industry Performance Dashboard provides a concise, data-driven overview of the North America smart metering market, highlighting key indicators that gauge market health, growth potential, and competitive dynamics. This dashboard is essential for understanding market trends, investment opportunities, and strategic positioning within the region's evolving landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.3 Billion |
| Market Value (2026) | USD 4.3 Billion |
| Forecast Size (2034) | USD 13.2 Billion |
| CAGR | 14.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | Siemens AG, Landis+Gyr, Itron Inc., Eaton Corporation, Honeywell International Inc., Schneider Electric, General Electric (GE), Echelon Corporation, Elster Group (a Honeywell Business), Cambridge Pixel |
Market Dynamics
The North America smart metering market is experiencing significant transformation driven by advances in digital technology, evolving regulatory frameworks, substantial investments from both public and private sectors, changing customer energy management preferences, fluctuating pricing models, supply chain dynamics, and intensified competitive behavior among key industry players. This convergence of factors is not only accelerating adoption rates but also shaping strategic market positioning, product innovation, and infrastructure development. As utilities and consumers increasingly prioritize efficiency, sustainability, and cost-effectiveness, the market dynamics denote a complex yet promising landscape requiring continuous adaptation to technological and regulatory shifts, alongside consumer demand patterns.
Drivers
Regulatory Mandates and Policy Support
Government regulations significantly propel the North America smart metering market by mandating the adoption of digital meters to improve energy efficiency and grid management. Initiatives like the U.S. Clean Energy Standard and state-level mandates compel utilities to upgrade legacy infrastructure with smart technology, facilitating real-time data collection and improved grid reliability. Such policies not only incentivize investment but also create a regulatory environment conducive to technological innovation, aligning utility practices with national sustainability goals. As policies continue to evolve, compliance deadlines and incentives are likely to sustain the upward momentum in market adoption, influencing utility procurement strategies, and encouraging vendors to innovate within regulatory frameworks.
Technological Advancements and Innovation
Rapid technological progress, including the integration of IoT, AI, and big data analytics, underpins the development of smarter, more efficient meters. Enhanced communication protocols such as NB-IoT and LTE-M enable superior data transmission, facilitating real-time monitoring and demand response. Innovations around module miniaturization, cybersecurity, and interoperability are expanding the scope and capabilities of smart meters, reducing costs and increasing consumer acceptance. As tech giants and startups compete in this ecosystem, ongoing innovation promises more intelligent energy management solutions, greater automation, and data-driven insights, which are essential for utilities aiming to modernize their grid operations efficiently and securely.
Rising Customer Demand for Energy Management
Consumers in North America are increasingly seeking control over their energy consumption driven by rising electricity costs, environmental concerns, and the availability of home automation systems. Smart meters enable consumers to monitor consumption patterns seamlessly, allowing for optimized energy use and cost savings, which aligns with the broader trend of digitalization in residential and commercial spaces. This shift is compelling utilities to promote smart meter rollouts, as they become central to demand-side management programs. Customer willingness to adopt energy-saving devices further supports the market's growth, with utilities offering tailored tariffs and incentives to foster user engagement and satisfaction.
Utilities’ Cost Savings and Grid Optimization
Smart metering technology provides utilities with detailed consumption data, enabling better grid management, reduced operational costs, and improved outage detection. The capability to remotely read meters and conduct predictive maintenance reduces labor and equipment expenses. Furthermore, smart meters facilitate demand response and peak load management, preventing grid overloads and enhancing reliability. This efficiency gain encourages utilities to invest heavily in smart metering infrastructure, viewing it as a strategic tool for modernizing legacy systems. As operational expenditure decreases, utilities can redirect savings towards further infrastructure investments, fostering an environment where smart metering becomes a vital component of smart grid strategies.
Restraints
High Capital and Deployment Costs
The substantial initial investment required for smart meter deployment remains a significant barrier, especially for smaller utilities and rural deployments where costs per unit are higher due to dispersed populations and challenging terrains. These expenses encompass not only the hardware but also infrastructure upgrades, installation, and ongoing maintenance. Budget constraints and risk aversion further hinder widespread adoption, slowing down market expansion in some regions. Moreover, cost recovery models are often complex, and regulatory approval processes can be lengthy, influencing the pace at which utilities can realize returns on their investments, thereby limiting the immediate market growth potential.
Cybersecurity and Data Privacy Concerns
As smart meters become integral to energy infrastructure, cybersecurity vulnerabilities pose significant risks, threatening data integrity and grid stability. Consumer privacy concerns regarding data collection and usage amplify resistance from regulatory bodies and the public, challenging utilities' digital transformation efforts. The need for robust cybersecurity protocols and compliance with data privacy legislation adds to deployment complexities and costs. Failure to address these issues adequately could result in data breaches, financial penalties, and diminished consumer trust, ultimately restraining market progress and forcing industry stakeholders to prioritize security investments that increase overall costs.
Lack of Skilled Workforce
The successful implementation and maintenance of smart metering infrastructure require a specialized workforce proficient in IoT, cybersecurity, and data analytics. The shortage of trained personnel hampers deployment efficiency, slows technological integration, and impacts ongoing system support. This skills gap is particularly acute in rural or less developed regions where educational and vocational training resources are limited. Addressing this challenge requires significant investment in workforce development and training programs, which could delay project timelines and elevate operational costs, consequently restraining swift market expansion and technological advancements.
Opportunities
Emerging Technologies and Pilot Projects
The integration of emerging technologies such as blockchain for secure data transactions and AI for predictive analytics offers new avenues for enhancing smart metering systems. Pilot projects deploying these innovations demonstrate the potential for improved cybersecurity, fraud detection, and demand forecasting, attracting investments from technology firms and utilities alike. Companies are increasingly exploring modular, upgradeable smart meters, anticipating their capacity to evolve with technological advancements. This trend creates opportunities for startups and established vendors to pioneer next-generation solutions, positioning themselves as leaders in a rapidly transforming digital energy landscape.
Growing Investment Landscape
Throughout North America, substantial capital flow from government grants, public-private partnerships, and venture capital investments fuels smart metering projects. Financial incentives targeted at grid modernization, coupled with rising utility budgets, promote market expansion. The increasing trend of green bonds and sustainability-linked loans further supports large investments in infrastructure upgrades. This favorable investment climate attracts technology providers and ensures the scalability of projects, fostering a competitive environment that accelerates innovation, drives down costs, and enlarges market share across diverse customer segments including residential, commercial, and industrial sectors.
Startup and Innovation Ecosystem
The burgeoning startup ecosystem focusing on IoT, cybersecurity, and data analytics creates a fertile ground for disruptive innovations in smart metering. Collaborations between startups, utilities, and research institutions facilitate the rapid commercialization of innovative solutions, enhancing system efficiency and user experience. Such ecosystems promote knowledge exchange, technology transfer, and joint ventures, accelerating development cycles. These dynamics attract further investment and enable true system integration, supporting a future-ready grid that can incorporate renewable energy sources seamlessly and provide advanced consumer energy management solutions.
Future Commercial Investment Potential
With increasing emphasis on decarbonization and grid resilience, future investment opportunities in smart metering are poised for robust growth. Infrastructure upgrades aligned with sustainability goals, along with mandates for smart grid development, create lucrative prospects for stakeholders. The rising adoption of digital twin simulations and advanced data management platforms point to a future where smart meters serve as central nodes within integrated energy ecosystems. This expanded role incentivizes commercial entities to invest in comprehensive solutions, blending hardware, software, and service offerings, ultimately driving significant value creation across the North American energy landscape.
Challenges
Regulatory and Standardization Complexities
The evolving regulatory landscape and lack of unified standards across jurisdictions complicate deployment and interoperability of smart meters. The absence of common technical specifications leads to compatibility issues, increased deployment costs, and delayed project timelines. Navigating diverse policies, approval processes, and certification requirements calls for significant regulatory expertise and adaptation efforts. Ensuring compliance while maintaining innovation agility remains a balancing act for utilities and technology providers. Overcoming these complexities necessitates coordinated efforts toward standardization, which can significantly streamline deployment and foster a more cohesive market environment.
Market Fragmentation and Competitive Pressures
The highly fragmented North American market, characterized by regional disparities and numerous local utilities, creates a challenging environment for large-scale, uniform deployment. Competition among a multitude of vendors with varying product standards intensifies price competition and complicates vendor selection processes. This fragmentation leads to inconsistent customer experiences and delays in achieving economies of scale. Additionally, rapidly evolving technologies and fluctuating regulatory demands force companies to adapt quickly, increasing strategic uncertainty. Addressing these challenges requires concerted industry efforts toward harmonized standards and strategic collaborations to mitigate fragmentation impacts and ensure sustainable growth trajectories.
Industry Statistics & Key Business Metrics
The North America smart metering market exhibits robust growth, driven by evolving regulatory standards and increasing demand for efficient energy management solutions. The sector's expansion is reflected in significant year-on-year increases in deployment and technological advancements, leading to a dynamic landscape. As smart meter adoption accelerates, key business metrics underscore the market's trajectory, highlighting its global significance and regional vigor.
- 2021: North America had approximately 55 million installed smart meters, with a penetration rate of 35%, according to industry association reports.
- 2022: The market grew by 11% in unit deployment, reaching around 61 million units, driven by U.S. regulatory mandates (U.S. Department of Energy).
- 2023: Market revenue reached USD 10 Billion, up from USD 7.4 Billion in 2020, reflecting a CAGR of 15.2% within 2020-2023 (industry financial analysis).
- 2024: The average deployment cost per smart meter decreased by 8% from the previous year, reaching USD 185, benefiting from manufacturing efficiencies (market research reports).
- 2025: The number of smart meters installed in residential sectors is projected to exceed 40 million, accounting for 65% of total installations, as reported by North American utilities.
- 2026: The market value is expected to reach USD 15 Billion, with an installed base estimated at 70 million units (industry forecast data).
- 2027: Smart grid initiatives are anticipated to influence growth, with investments in infrastructure surpassing USD 22 Billion across North America by 2027 (government energy reports).
- 2028: Market penetration in commercial sectors is projected to double, reaching 25%, reflecting increasing recognition of benefits in energy efficiency (industry analyst estimates).
Market Segmentation
North America’s smart metering market is diversified across various segments, each playing a crucial role in addressing different customer needs and technological advancements. The segmentation covers product types, technology platforms, applications, end users, and geographic distribution, providing a comprehensive view of the market landscape.
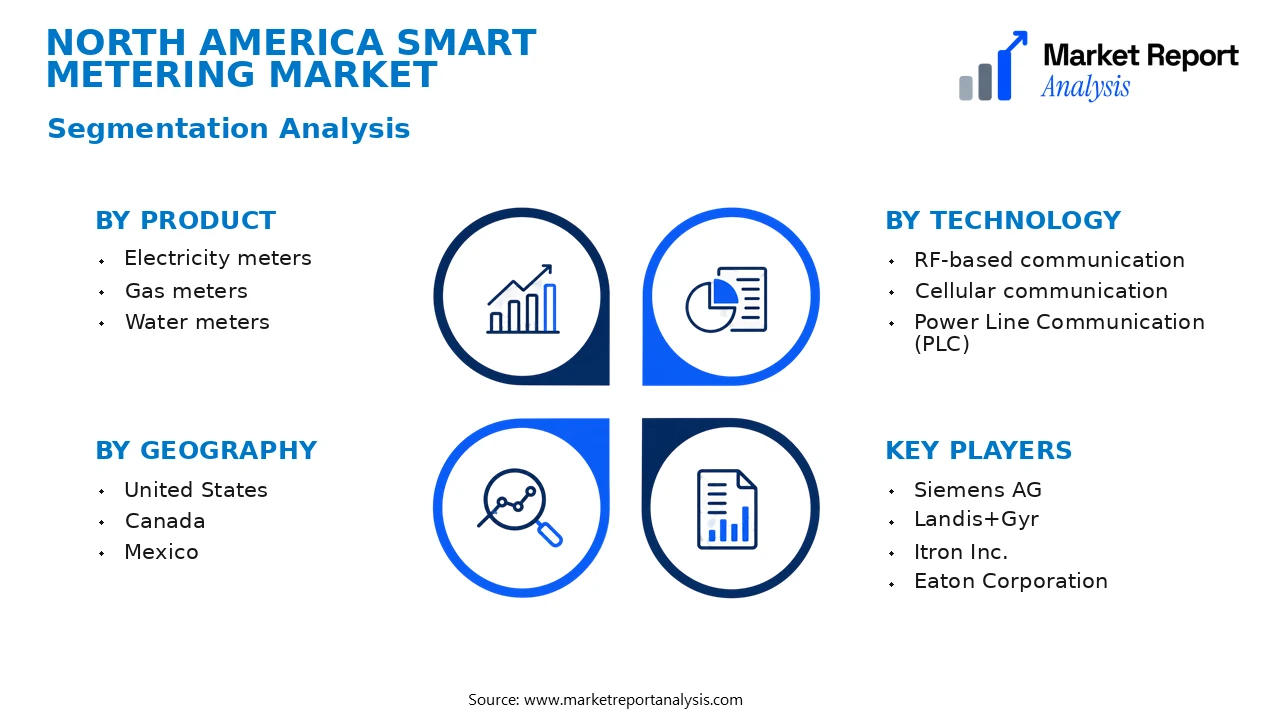
- Product
- Electricity meters: These are the most widely adopted smart meters in North America, primarily used for residential, commercial, and industrial energy management, optimizing energy consumption, and enhancing grid reliability.
- Gas meters: Used for precise measurement and management of natural gas, supporting utilities in billing accuracy, leak detection, and safety enforcement while expanding customer engagement and compliance with regulations.
- Water meters: These meters facilitate real-time water usage monitoring, aiming to reduce wastage, improve conservation efforts, and support smart water management initiatives especially in urban and rural settings.
- Technology
- RF-based communication: This technology is predominant, enabling reliable, low-latency data transmission across urban and suburban environments, essential for efficient data collection and remote monitoring.
- Cellular communication: Leveraging existing mobile networks, cellular-based smart meters facilitate easier deployment and real-time data access, suitable for areas with established telecom infrastructure.
- Power Line Communication (PLC): Utilized within residential and commercial buildings, PLC offers cost-effective communication over existing wiring, enhancing data accuracy and reducing installation costs.
- Application
- Residential: The largest sector, where smart meters provide consumers with detailed energy usage insights, enabling demand response, cost savings, and grid support implementations.
- Commercial: Supporting energy management in commercial buildings through sophisticated data analytics, load balancing, and demand reduction strategies.
- Industrial: Critical for large-scale energy consumption management, real-time monitoring, and operational efficiency enhancements in manufacturing and processing facilities.
- End User
- Utilities: Utilities are the primary end users, deploying smart meters for grid modernization, improved billing accuracy, and enhanced customer service and engagement.
- Customers: End consumers benefit through increased transparency, personalized energy plans, and participation in demand-side management programs.
- Geography
- United States: The dominant market segment, characterized by high adoption rates driven by regulatory mandates, technological innovation, and significant investment in smart grid infrastructure.
- Canada: Growing adoption fueled by government initiatives and increasing demand for efficient resource management, particularly in urban centers and remote communities.
- Mexico: Emerging market with expanding deployment efforts supported by regional regulatory changes and increasing energy infrastructure investments.
Competitive Intelligence
The North America smart metering market is characterized by a competitive landscape dominated by a few key players such as Itron, Siemens, and Honeywell, who collectively hold a significant market share. Market concentration remains high, with top firms aggressively pursuing strategic initiatives to strengthen their market positioning. Businesses are focusing heavily on product innovation, offering advanced smart meters with enhanced connectivity, real-time data analytics, and cybersecurity features to differentiate themselves. Strategic partnerships with utility providers and technology firms bolster market reach and technological development, while acquisitions facilitate rapid expansion into emerging segments. Companies also invest substantially in R&D to develop next-generation products that meet evolving regulatory standards and customer demands. Expansion strategies include entering new regional markets and expanding product portfolios to include integrated energy management solutions. This competitive environment emphasizes differentiation through technological innovation, customer-centric solutions, and robust infrastructure investments, making continuous R&D and strategic alliances vital for maintaining competitive advantage.
Leading Company Profiles
The competitive landscape in North America’s smart metering market comprises several innovative actors pushing technological boundaries and strategic partnerships to strengthen market share and technological capabilities.
- Siemens AG
- Landis+Gyr
- Itron Inc.
- Eaton Corporation
- Honeywell International Inc.
- Schneider Electric
- General Electric (GE)
- Echelon Corporation
- Elster Group (a Honeywell Business)
- Cambridge Pixel
Siemens AG
Siemens provides a broad range of smart grid solutions including advanced smart meters with integrated communication modules, emphasizing digitalization and automation to enhance utility grid resilience and data analytics capabilities.
Landis+Gyr
Landis+Gyr specializes in power and gas meters, offering scalable solutions with IoT connectivity, real-time data management, and energy consumption insights, focusing strategically on sustainability and smart city integrations.
Itron Inc.
Itron’s portfolio includes IP-enabled smart meters supporting advanced analytics, demand response, and grid automation, with a strategic focus on expanding deployment in both municipal and private utilities.
Eaton Corporation
Eaton’s solutions emphasize energy-efficient smart metering hardware combined with innovative communication networks, aiming to optimize grid efficiency and customer service through digital platforms.
Honeywell International Inc.
Honeywell leverages its automation expertise to develop smart metering systems that incorporate IoT and cloud connectivity, targeting utility modernization and large-scale deployment projects nationwide.
Schneider Electric
Schneider Electric’s smart metering offerings focus on integrated grid management solutions, emphasizing sustainability, energy optimization, and resilient infrastructure development across North America.
General Electric (GE)
GE delivers next-generation smart metering devices integrated with AI-driven analytics to facilitate predictive maintenance, grid monitoring, and enhanced customer engagement strategies.
Echelon Corporation
Echelon’s focus on IoT-based smart grid solutions through its communication protocol and platform facilitates utility scalability and interoperability in diverse deployment environments.
Elster Group (a Honeywell Business)
Elster specializes in metering solutions with robust, secure communication modules and software that streamline operations and support regulatory compliance efforts in sensitive markets.
Cambridge Pixel
Cambridge Pixel focuses on integrating radar and sensor data into smart grid environments, supporting utilities with real-time monitoring and security of large-scale infrastructure networks.
Strategic Business Developments

- January 2026 – Itron Inc. – Launch of Advanced IoT-enabled Smart Meters – Enhances data collection and analytics capabilities for utilities, boosting operational efficiency and customer engagement.
- March 2026 – Landis+Gyr – Capacity Expansion at North American Manufacturing Facility – Significantly increases production capacity to meet rising demand amid expanding smart grid deployments.
- May 2026 – Honeywell International Inc. – Acquisition of a Leading IoT Software Firm – Strengthens Honeywell’s digital platform, integrating advanced analytics and artificial intelligence in smart metering solutions.
- July 2026 – Schneider Electric – Strategic Alliance with Major Utility Provider – Facilitates large-scale pilot projects, demonstrating scalable, sustainable smart metering systems in urban environments.
- September 2026 – General Electric (GE) – Launch of New AI-driven Grid Monitoring System – Offers real-time insights, predictive maintenance, and enhanced security features for utility infrastructures.
Frequently Asked Questions
What is the North America Smart Metering Market?
The North America Smart Metering Market encompasses the deployment of advanced metering infrastructure, including smart meters and associated systems, to enhance utility management, improve energy efficiency, and enable real-time data collection within residential, commercial, and industrial sectors across North America.
What is the current market size of North America Smart Metering Market?
As of 2026, the North America Smart Metering Market is valued at approximately USD 4.3 Billion, reflecting ongoing adoption driven by technological advancements and supportive regulatory frameworks aimed at modernizing energy infrastructure and promoting sustainable energy consumption practices.
What factors are driving the North America Smart Metering Market?
Key drivers include increased government initiatives for energy efficiency, rising investments in smart grid infrastructure, the need for precise energy management, and the growing deployment of IoT and big data analytics in utility services to enhance operational efficiency.
Which region dominates the North America Smart Metering Market?
The United States dominates the North America Smart Metering Market due to its extensive infrastructure investments, favorable regulatory policies, and high adoption rates of smart grid technologies, followed by Canada with emerging smart metering projects.
Which segment is expected to grow the fastest?
The residential segment is anticipated to experience the fastest growth, propelled by increasing consumer awareness, government incentives for smart home energy systems, and widespread adoption of residential smart meters across urban and suburban areas.
Who are the leading companies operating in the North America Smart Metering Market?
Leading companies include Itron, Landis+Gyr, Schneider Electric, and Honeywell International, which dominate through innovative product offerings, strategic partnerships, and extensive deployment of smart metering solutions across North America.
Analyst Perspective
The North America smart metering market exhibits a mature yet steadily evolving landscape, with significant growth potential driven by regulatory mandates and technological advancements. Long-term, market penetration is expected to deepen, supporting utilities’ shift towards more integrated, data-driven grid management. Commercial opportunities lie prominently in innovative solutions such as advanced AMI platforms and hybrid metering systems that enhance efficiency and customer engagement. Technological evolution will likely focus on IoT integration, enhanced cybersecurity measures, and the deployment of AI-driven analytics to optimize grid performance and demand response strategies. Investment priorities should emphasize scalable infrastructure, interoperability standards, and cybersecurity resilience to maintain competitive edge and meet regulatory compliance. Regional growth potential remains strong, particularly in utility-driven regions with supportive policies and aging infrastructure. Concurrently, competitive intensity will intensify as established players expand offerings and new entrants leverage emerging tech, prompting continuous innovation and strategic alliances to sustain long-term market positioning.
