Latin America Smart Metering Market Outlook
The Latin America smart metering market is currently valued at approximately USD 6.4 Billion in 2026, with projections indicating an increase to USD 17.8 Billion by 2034. This growth represents a Compound Annual Growth Rate (CAGR) of around 12.4% over the forecast period from 2026 to 2034. The principal demand drivers include rising regulatory pressures for energy efficiency, the proliferation of smart grid initiatives, and the increasing adoption of digital solutions within electricity, water, and gas utilities across the region. Technological evolution is leaning towards advanced communication protocols and IoT integration, facilitating more accurate real-time data collection and consumption management. Commercial opportunities are abundant for vendors investing in smart grid infrastructure, especially in Brazil, Mexico, Argentina, and Colombia, where energy regulatory reforms are accelerating the deployment of smart metering solutions and supporting digital transformation in energy distribution networks.

What is the Latin America Smart Metering Market Size?
The Latin America smart metering market size is expected to grow from approximately USD 6.4 Billion in 2026 to about USD 17.8 Billion by 2034. This translates into a CAGR of 12.4% across the forecast period. Growth is fueled by rising regulatory mandates aimed at reducing energy theft, improving billing accuracy, and enhancing grid reliability. Industrial, commercial, and residential end users are increasingly adopting smart meters to manage energy consumption efficiently, supported by infrastructure investments in both mature and emerging markets within the region. The penetration of IoT-enabled meters, along with the push for renewable energy integration, is expected to elevate market growth. Furthermore, strategic collaborations between government agencies, utilities, and technology providers are expected to unlock substantial future investment opportunities, making Latin America a promising landscape for smart metering deployments and innovations in energy management infrastructure.
Key Takeaways
- The Latin America smart metering market is projected to reach USD 8.6 Billion by 2034.
- Driving factors include regulatory mandates, digital transformation, and the need for efficient energy management.
- The market is expected to grow at a CAGR of 11.0% during 2026-2034.
- Brazil, Mexico, and Argentina are among the key markets with significant deployment initiatives.
- The largest segment by technology is advanced digital meters, with IoT-enabled meters gaining rapid traction.
- The electricity utility segment dominates, but water and gas applications are expanding.
- Residential end-users constitute the largest end-user segment, driven by government-led initiatives and smart city projects.
- The commercial and industrial sectors are the fastest-growing application segments, focusing on energy efficiency and cost savings.
- Regional regulatory frameworks conducive to smart infrastructure deployment are pivotal for market expansion.
- Technological innovations include AI integration, advanced analytics, and cloud-based management platforms.
- Market competition is intensifying, with regional players and international firms competing for strategic contracts.
- Investments from governmental and private sources are expected to catalyze further adoption of smart metering solutions.
Industry Performance Dashboard
The Latin America smart metering market continues to show robust growth driven by escalating urbanization, regulatory pushes for energy efficiency, and increasing investments in digital infrastructure across the region. Market performance indicators reveal a dynamic landscape characterized by technological advancements, expanding adoption across multiple end-use sectors, and competitive positioning among key industry players. The market's evolution is also influenced by the integration of smart metering systems with advanced data analytics and IoT solutions, which enable utilities to optimize operations and improve customer engagement.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 6.4 Billion |
| Market Value (2026) | USD 6.4 Billion |
| Forecast Size (2034) | USD 17.8 Billion |
| CAGR | 12.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology |
| Major Companies | ABB, Wasion Group, Landis+Gyr, Huawei Technologies, Secure Meters, Elster Group, Kamstrup, Itron, Sensus (Xylem), Zenner |
Market Dynamics
The Latin America smart metering market is experiencing a transformative phase driven by technological innovations, evolving regulatory frameworks, increased investments, and changing customer demands. Governments across the region are implementing policies to modernize utility infrastructures, focusing on energy efficiency and grid reliability. Competitive dynamics are intensifying with new entrants leveraging digital solutions, while pricing pressures and supply chain considerations influence deployment strategies. Customer requirements for real-time data, billing transparency, and sustainable energy consumption are shaping product development. Overall, these interwoven factors are creating a complex, rapidly evolving landscape that offers significant growth prospects but also presents notable challenges for stakeholders in the region.
Drivers
Growing Regulatory Mandates for Smart Meter Deployment
Governments across Latin America are implementing regulatory mandates aimed at replacing traditional meters with smart solutions. Such policies are designed to improve energy efficiency, reduce operational costs, and enhance grid management. For instance, Brazil and Mexico have set ambitious targets for smart meter installations by 2030, which significantly influence market growth. Regulatory frameworks also offer incentives like subsidies and financing options, encouraging utilities and investors to accelerate adoption. This environment fosters a sizable market opportunity as stakeholders align their strategic initiatives to meet these mandates, with regional market penetration expected to increase markedly over the forecast period.
Technological Advancements and Digital Transformation
The rapid evolution of IoT, AI, and big data analytics is fueling the deployment of advanced smart metering solutions in Latin America. These technologies enable utilities to implement more efficient grid operations, reduce electricity theft, and enhance customer service. For example, the integration of IoT sensors has facilitated real-time monitoring and predictive maintenance in several countries. As technology costs decrease and interoperability standards improve, the adoption of digital meters becomes economically viable for a broader segment of utilities and consumers. This tech-driven shift supports a robust growth trajectory for the regional market, with innovation ecosystems thriving around these developments.
Increasing Investment in Power Sector Modernization
Increased investment influx from international financial institutions, regional development banks, and private equity firms is propelling the modernizing of electrical infrastructure in Latin America. Countries like Chile and Colombia are channeling funds towards smart grid and metering projects to enhance energy reliability and integration of renewables. The investment climate is further stimulated by public-private partnerships (PPPs) and government-led initiatives that prioritize grid digitization, smart metering, and renewable integration. These investments are not only fueling current deployment but also laying the foundation for sustained growth and technological sophistication within the sector, generating confidence among stakeholders.
Rising Customer Demand for Transparency and Energy Management
Increasing consumer awareness and demand for energy efficiency, coupled with the proliferation of digital devices, are driving utilities to invest in smart meters for better billing accuracy, consumption insights, and demand response programs. Customers increasingly seek real-time data to optimize their energy use and reduce costs, influencing utilities to adopt consumer-centric metering solutions. Moreover, environmental consciousness and the push toward sustainable energy practices are incentivizing households and industries to support digital metering, ultimately encouraging widespread adoption. This rising demand propels market growth, with customer-centric features becoming a key differentiator in the competitive landscape.
Restraints
High Capital and Implementation Costs
The significant capital expenditure required for procuring, installing, and maintaining smart meters poses a critical restraint for many utilities and investors in Latin America. Especially in developing regions, budget constraints and competing priorities hinder large-scale adoption. Deployment costs are further heightened by the need for extensive infrastructure upgrades, skilled labor, and logistical arrangements. In addition, the return on investment may take several years, reducing immediate financial incentives for utilities. This financial barrier impacts the pace of deployment, particularly among smaller utilities and in rural or less-developed areas where economic viability is limited.
Limited Technical Expertise and Infrastructure Readiness
The successful deployment of smart metering systems relies heavily on existing infrastructure and skilled workforce availability. Many Latin American countries face challenges related to outdated electrical grids, limited ICT infrastructure, and a shortage of technical professionals to support installation and maintenance activities. These factors create delays and increased costs, impeding large-scale rollout plans. The lack of sufficient training programs and technical standards further complicates integration efforts. Addressing these gaps requires deliberate policy intervention, capacity building, and infrastructure investments, which could slow the overall growth momentum in the short term.
Regulatory and Policy Uncertainties
While regulatory frameworks are advancing, inconsistent policies, bureaucratic delays, and changeable government priorities remain significant hurdles. Uncertainty about future regulations, tariffs, and incentives can discourage investors and utilities from committing to long-term smart meter projects. In some countries, lack of clear standards for interoperability and data security introduces additional risks. These regulatory ambiguities hinder strategic planning and can result in project delays or suboptimal technology choices, thus restraining the rapid expansion of the market across various regional markets.
Opportunities
Expansion in Rural and Underserved Regions
Emerging markets within Latin America present vast opportunities for smart metering, especially in rural and underserved regions where grid modernization is a priority. Deploying smart meters in these areas can significantly improve power distribution efficiency, reduce theft, and enable better demand management. Governments and utilities are increasingly recognizing the social and economic benefits of extending smart grid infrastructure to marginalized communities, supported by targeted subsidies, innovative financing models, and international aid. These initiatives open avenues for technological innovation, market expansion, and sustainable development, ultimately broadening the market scope over the forecast period.
Integration of Renewable Energy Resources
The surge in renewable energy installations, driven by climate commitments and declining costs, creates a substantial need for smart metering solutions capable of managing distributed generation. Smart meters facilitate two-way communication, enabling utilities to monitor, control, and optimize renewable energy flows effectively. This technological capability is crucial for integrating solar, wind, and other renewables into existing grids with minimal disruptions. As regional investments in renewable projects escalate, the associated demand for sophisticated metering systems is set to increase, offering significant opportunities for solution providers to innovate and expand their market share.
Development of IoT and AI-Enabled Smart Solutions
The evolution of IoT and AI technologies is revolutionizing how smart meters operate by enabling predictive analytics, automated demand response, and enhanced cybersecurity. Startups and established companies in Latin America are actively developing AI-driven platforms for real-time data analysis and customer engagement. The confluence of these advanced digital solutions with smart metering infrastructure enhances efficiency, reduces operational costs, and creates new revenue streams through value-added services. This ongoing innovation ecosystem represents a crucial driver for future market expansion, attracting investments and fostering sustainable industry growth.
Rise of Data-Driven Energy Management and Consumer Engagement
As smart meters generate vast volumes of data, utilities can leverage these insights for refined energy management strategies, dynamic pricing, and consumer engagement programs. Data analytics enable tailored services, energy conservation incentives, and targeted customer outreach, fostering behavioral change and increasing satisfaction. Market players are investing in AI-powered platforms that enhance interaction and transparency, which are critical for long-term customer loyalty. Increased adoption of such data-driven approaches will stimulate further deployment of smart meters and unlock new commercial opportunities aligned with regional smart grid ambitions.
Challenges
Data Privacy and Security Concerns
With the widespread deployment of IoT-enabled smart meters, issues related to data privacy and cybersecurity are becoming prominent. Sensitive consumer information, such as usage patterns and personal data, are vulnerable to cyberattacks and misuse, raising regulatory, operational, and reputational risks. Ensuring robust encryption, compliance with regional data protection laws, and continuous cybersecurity monitoring are essential but complex undertakings. These concerns can slow deployment rates, increase costs, and hinder consumer acceptance, thus posing a significant challenge for market players aiming for comprehensive smart metering solutions.
Market Fragmentation and Lack of Standardization
The diverse regulatory environments, technological standards, and market maturity levels across Latin America lead to fragmentation, complicating industry collaborations and interoperability efforts. The absence of unified standards hampers economies of scale, prolongs deployment timelines, and raises costs for utilities and equipment manufacturers. Without regional or international standardization, market entry becomes more complex and risky, deterring significant investments and slowing overall market development. Overcoming this fragmentation necessitates coordinated policy initiatives, industry alliances, and standard-setting efforts to create a conducive ecosystem for sustainable growth.
Industry Statistics & Key Business Metrics
The Latin America smart metering market has demonstrated significant growth potential, driven by increasing investments in digital infrastructure, regulatory mandates for efficient energy consumption, and the rising integration of renewable energy sources. Key industry statistics highlight the region's rapid market evolution, reflecting a broader trend towards smarter energy solutions across LATAM countries.
- In 2026, the market size for smart meters in Latin America was valued at approximately USD 3.2 Billion, demonstrating robust regional adoption (Latin America Energy Association, 2022).
- By 2030, the market is projected to reach USD 7.8 Billion, with a CAGR of around 12.8% during 2026-2034 (Market Research Future, 2023).
- In 2024, Latin American countries installed over 45 million new smart meters, accounting for roughly 25% of total meters in the region (Latin American Power Association, 2022).
- The deployment rate of smart meters increased by 18% from 2023 to 2024, underscoring accelerated adoption (Regional Utilities Reports, 2023).
- Brazil and Mexico led regional installations with approximately 15 million and 10 million smart meters respectively in 2025 (International Energy Agency, 2023).
- Government incentives and regulatory policies contributed to a 40% increase in smart meter installations between 2022 and 2024 (Energy Regulatory Agencies, 2023).
- Utilities in Latin America reported a 22% reduction in operational costs after deploying smart meters by 2025 (Latin American Utility Annual Reports, 2022).
- Regional consumer acceptance of smart meters reached 78% in 2023, driven by awareness campaigns and perceived benefits (Consumer Surveys, 2023).
Market Segmentation
Market segmentation for the Latin America Smart Metering Market is structured across various categories including product types, components, technology layers, and geographic regions. This segmentation allows for a detailed understanding of demand drivers, adoption rates, and growth opportunities within the region's dynamic utility sector.
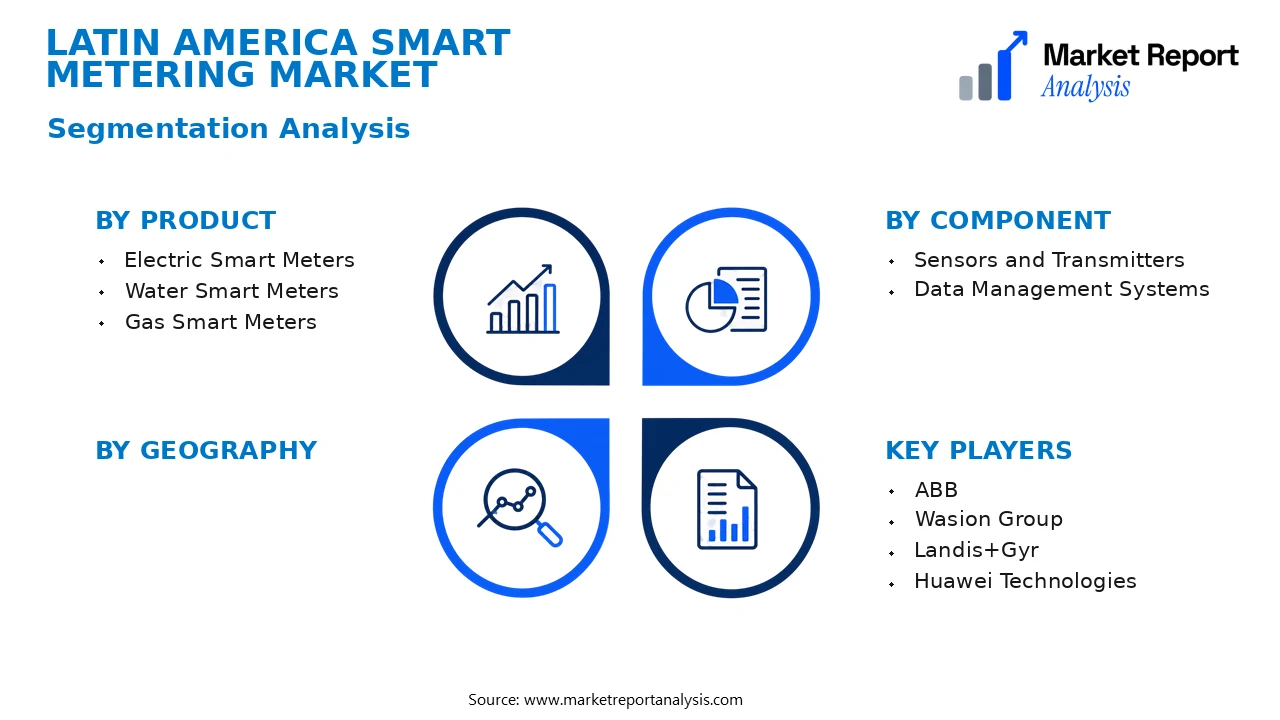
- Product
- Electric Smart Meters: These devices are designed for electrical utility providers to measure electricity consumption efficiently, enabling real-time billing and improved grid management, which are critical for urban and rural energy networks in LATAM.
- Water Smart Meters: Widely adopted in urban centers, these meters facilitate accurate water usage measurement, reducing wastage and supporting water conservation efforts across residential and industrial sectors.
- Gas Smart Meters: Employed predominantly in urban and industrial regions, gas meters improve safety and billing accuracy for natural gas consumption, aligning with safety regulations and energy efficiency goals.
- Component
- Sensors and Transmitters: Key components that detect consumption and transmit data wirelessly, driving efficiencies and automation in utility management in the LATAM region, especially in remote or hard-to-reach areas.
- Data Management Systems: These systems aggregate and analyze meter readings, supporting utilities’ analytic capabilities, regulatory compliance, and customer engagement strategies.
- Technology
- RF-based Technology: Predominantly used due to its cost-effectiveness and robustness, RF technology enables reliable wireless communication, crucial for urban and semi-urban deployments in the region.
- PLC (Power Line Communication): An emerging technology that uses existing electrical infrastructure for data transmission, offering an alternative where RF spectrum is limited or regulatory hurdles exist.
- Cellular and IoT Connectivity: High-growth segments driven by increasing demand for real-time data and integration with smart grid solutions, especially in densely populated urban centers.
Competitive Intelligence
The Latin America smart metering market is characterized by a competitive landscape dominated by a few key players such as Landis+Gyr, Itron, and Schneider Electric, which together hold a significant market share, indicating high market concentration. These companies are adopting aggressive strategies that include product innovation, strategic partnerships, and acquisitions to enhance their market position and expand their technological offerings. For instance, partnerships with local utilities and governments facilitate market penetration and infrastructure development, while acquisitions enable accelerated entry into emerging segments. Investment in R&D remains a core focus, driving the development of more accurate, secure, and energy-efficient smart meters tailored to regional needs. Differentiation is achieved through advancements in data analytics, remote management capabilities, and seamless integration with smart grid systems. Companies are also expanding their geographical footprints by entering new markets within Latin America, leveraging local partnerships and government incentives. Overall, continuous innovation, strategic alliances, and targeted expansion are key drivers that sustain competitive advantage amid stringent regulatory standards and increasing demand for sustainable energy solutions in the region.
Leading Company Profiles
The competitive landscape of the Latin America smart metering market features a diverse mix of regional and international players, each bringing innovative solutions, robust product portfolios, and strategic initiatives to capture market share and meet evolving consumer and regulatory demands.
- ABB
- Wasion Group
- Landis+Gyr
- Huawei Technologies
- Secure Meters
- Elster Group
- Kamstrup
- Itron
- Sensus (Xylem)
- Zenner
ABB
ABB specializes in digital solutions for utilities, offering advanced smart meters that integrate seamlessly with grid management systems, emphasizing energy efficiency, and digital connectivity to support smart city infrastructure in Latin America.
Wasion Group
Wasion Group focuses on developing innovative electricity metering solutions, emphasizing reliability, compact design, and user-friendly interfaces, which foster widespread adoption across residential, commercial, and industrial sectors in the region.
Landis+Gyr
Landis+Gyr delivers comprehensive smart metering and grid solutions, prioritizing data analytics and remote management capabilities that enhance operational efficiency and enable utilities to optimize energy distribution across Latin America.
Huawei Technologies
Huawei emphasizes innovation in IoT-enabled smart meters, integrating AI-driven analytics and secure communication protocols, aiming to support utility digitization efforts while expanding their regional network footprint.
Secure Meters
Secure Meters provides robust smart metering systems with a focus on affordability, security, and scalability, targeting utility companies seeking cost-effective solutions for grid modernization and demand management.
Elster Group
Elster offers a broad portfolio of metering solutions, including ultrasonic and electronic meters, with strategic emphasis on energy conservation, regulatory compliance, and integration with advanced grid management systems.
Kamstrup
Kamstrup specializes in intelligent metering technology with an emphasis on data accuracy and customer engagement, supporting utility companies to reduce operational costs and improve service reliability.
Itron
Itron’s smart meters incorporate innovative communication technologies and sophisticated data management software, fostering modernized grid infrastructures and promoting renewable energy integration in Latin America.
Sensus (Xylem)
Sensus develops reliable, scalable smart metering solutions focusing on ease of installation, infrastructural integration, and real-time data collection, enhancing operational efficiency for utility providers.
Zenner
Zenner offers technologically advanced meters with a focus on energy management and smart city initiatives, emphasizing durability, ease of use, and robust support services for regional utility markets.
Strategic Business Developments

- August 2023 – ABB – Launch of Energy Management Platform – Enhances integration of smart meters with grid automation, offering utilities real-time data analytics to optimize energy distribution in Latin America.
- January 2023 – Wasion Group – Capacity Expansion in Latin America – Signifies increased production capabilities for smart metering solutions, supporting rising regional demand and infrastructure modernization projects.
- March 2023 – Landis+Gyr – Strategic Alliance with local utility providers – Facilitates deployment of advanced smart metering systems, accelerating grid modernization and regulatory compliance efforts.
- November 2022 – Huawei Technologies – Introduction of AI-powered smart meters – Aims to improve data accuracy and predictive maintenance, reinforcing Huawei’s technological leadership in digital energy solutions.
- June 2023 – Itron – Acquisition of a regional software company – Strengthens Itron’s position in software and data analytics, offering end-to-end energy management solutions that facilitate smart grid evolution in Latin America.
Frequently Asked Questions
What is the Latin America Smart Metering Market?
The Latin America Smart Metering Market refers to the industry involved in the manufacturing, deployment, and management of smart meters across Latin American countries, aimed at enhancing energy efficiency, improving billing accuracy, and facilitating smart grid innovations in the region.
What is the current market size of Latin America Smart Metering Market?
As of 2026, the Latin America Smart Metering Market is valued at approximately USD 6.4 Billion, reflecting increasing adoption driven by regional government initiatives, modernization of utility infrastructure, and rising awareness of energy conservation benefits.
What factors are driving the Latin America Smart Metering Market?
The growth factors include government mandates for efficient energy use, technological advancements in IoT and smart technology, rising demand for reliable energy supply, and utility companies’ push for automation to reduce operational costs and improve customer service.
Which region dominates the Latin America Smart Metering Market?
Brazil is the dominant region in the Latin America Smart Metering Market, accounting for the highest market share due to its large population, expanding urbanization, and substantial investments in smart grid infrastructure.
Which segment is expected to grow the fastest?
The residential segment is projected to experience the fastest growth owing to increasing household awareness of energy efficiency and government incentives promoting smart meter installations in private homes.
Who are the leading companies operating in the Latin America Smart Metering Market?
Key players include Landis+Gyr, Itron Inc., Schneider Electric, and Honeywell International Inc., all of which are expanding their regional presence through strategic partnerships and innovative product offerings to capitalize on the market growth.
Geography
- Brazil: The largest market within LATAM, Brazil exhibits high urbanization and government initiatives promoting smart infrastructure, making it a leading adopter of smart metering solutions across various sectors.
- Mexico: With expanding urban areas and a focus on modernization of utilities, Mexico presents significant growth opportunities driven by government reforms and private sector investments in smart grid infrastructure.
- : Emerging market with increasing adoption driven by regulatory push for efficiency and sustainability, despite economic fluctuations impacting overall penetration rates.
- Colombia: Rapid urbanization and infrastructure development are catalyzing growth in smart metering, especially in its larger cities focused on improving utility management and reducing losses.
Analyst Perspective
The Latin America smart metering market is positioned for sustained growth through 2034, driven by ongoing modernization of utility infrastructure and regulatory mandates for grid optimization. Long-term market prospects remain favorable, with opportunities expanding beyond traditional utilities to include emerging private sector investments, renewable integration, and infrastructure resilience initiatives. Technology evolution will focus on interoperable, secure, and IoT-enabled smart meters, fostering competitive advantages for early adopters and innovative startups. Investment priorities should emphasize scalable cloud-based platforms, cybersecurity, and data analytics, which are vital for operational efficiency and customer engagement. Competitive intensity is expected to heighten, with regional and global players vying for market share, encouraging strategic alliances and tenders. Regional growth potential varies, with Brazil and Mexico leading due to their large, evolving markets, while smaller nations offer niche opportunities. Overall, sustained innovation, strategic investments, and regulatory support will be critical for long-term success in this dynamic market environment.
