North America Radiotherapy Market Outlook
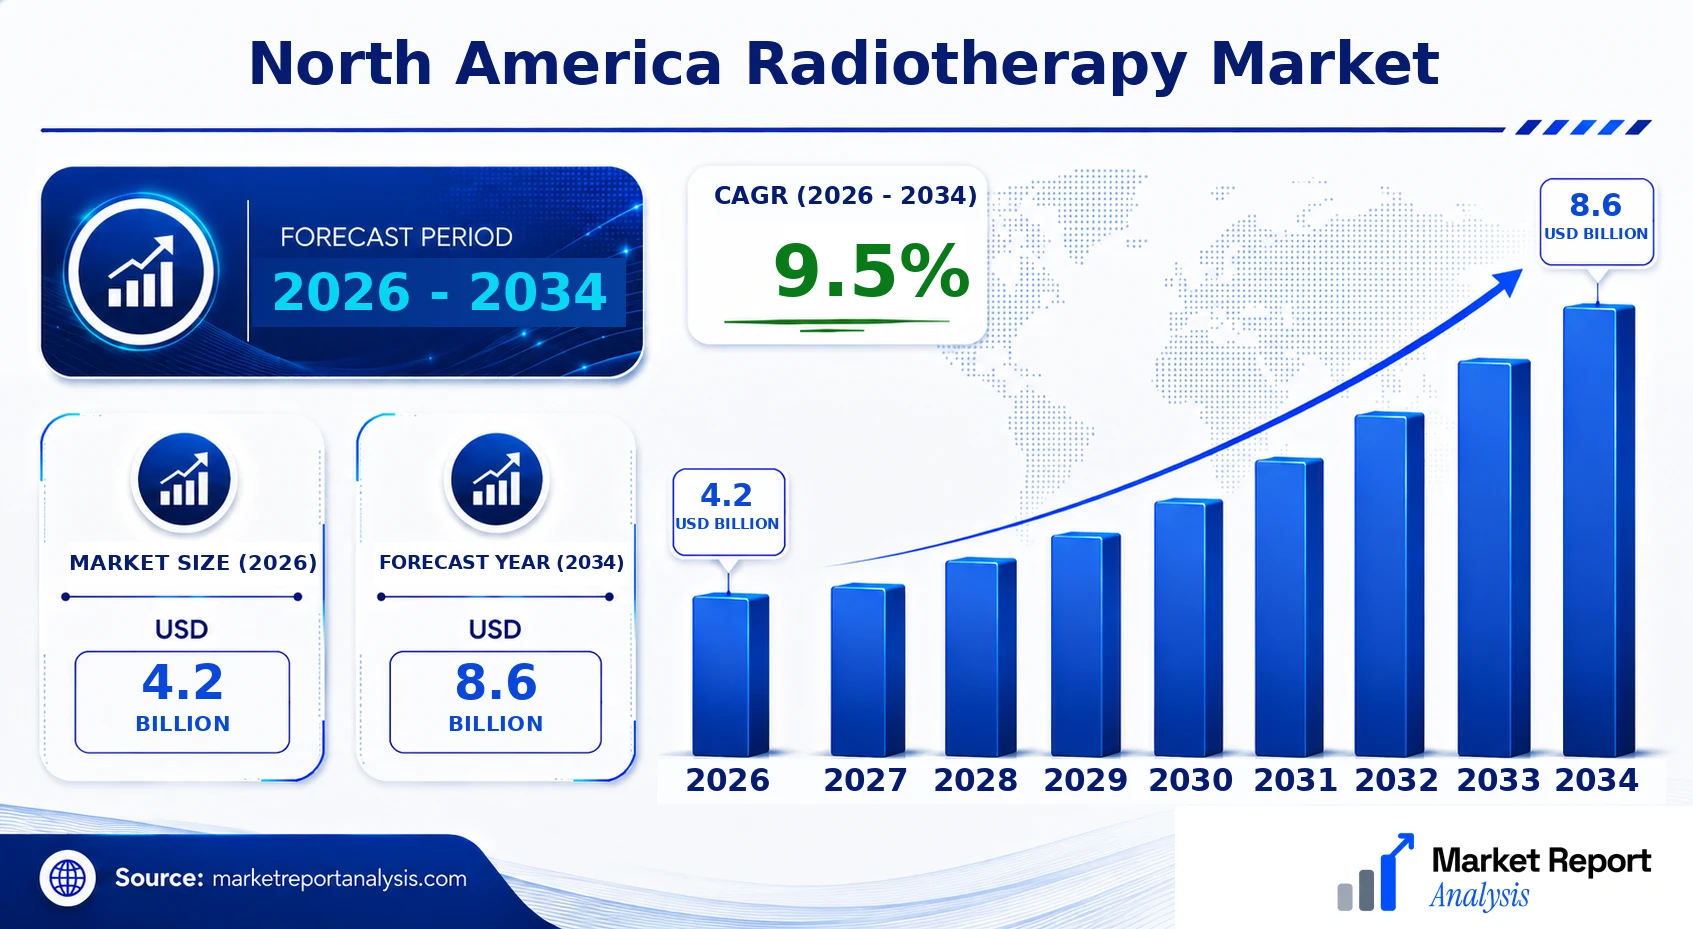
The North America Radiotherapy Market is currently valued at USD 4.2 Billion in 2026 and is projected to reach about USD 8.6 Billion by 2034. This growth, with a CAGR of approximately 9.5% over the period from 2026 to 2034, is driven primarily by increasing cancer incidence rates, technological advancements in radiation therapy devices, and expanding healthcare infrastructure. The rising adoption of advanced radiotherapy techniques such as stereotactic body radiotherapy (SBRT) and intensity-modulated radiotherapy (IMRT), coupled with a growing geriatric population that is more susceptible to cancer, contribute significantly to market expansion. Additionally, the increasing investments in healthcare R&D for innovative treatment modalities open vast commercial opportunities for industry players, fostering the development of more precise and effective therapies. The trend towards personalized medicine and minimally invasive procedures further supports a positive outlook for the North American radiotherapy sector, with key opportunities for technology integration and clinical adoption.
What is the North America Radiotherapy Market Size?
The North America Radiotherapy Market size is estimated at USD 4.2 Billion in 2026 and is expected to reach approximately USD 8.6 Billion by 2034, expanding at a CAGR of around 9.5% from 2026 to 2034. This growth stems from a rising prevalence of cancer across the region, driven by factors such as lifestyle changes, aging populations, and environmental influences. The healthcare infrastructure in North America, characterized by high adoption rates of advanced medical technologies, supports extensive use of radiotherapy devices. The technological impact is significant, with innovations in imaging, treatment planning, and delivery systems enabling more effective and targeted therapies. End-use industries such as hospitals, specialty clinics, and research institutions are major consumers, with hospitals accounting for the largest share. Future investment opportunities are abundant in areas like AI-enabled treatment planning, portable radiotherapy systems, and combination therapy approaches, expected to further propel the market’s growth trajectory.
Key Takeaways
- The current market size is USD 4.8 Billion in 2026
- The forecasted market size for 2034 is USD 8.2 Billion
- The CAGR from 2026 to 2034 is approximately 7.7%
- The largest segment by technology is IMRT, with growing adoption
- The fastest-growing segment is proton therapy, due to technological advancements and increased clinical acceptance
- The primary application is external beam radiotherapy, dominating the market
- The fastest-growing application is stereotactic radiosurgery (SRS)
- The largest end user is hospitals with comprehensive cancer treatment facilities
- The forecast period spans from 2026 to 2034
- The base year for analysis is 2026
Industry Performance Dashboard
The North America radiotherapy market has demonstrated robust growth driven by ongoing technological advancements, increasing cancer incidence rates, and expanding healthcare infrastructure in the region. Market participants are continuously innovating to enhance treatment effectiveness and patient comfort, which has contributed to sustained market performance. As healthcare providers increasingly adopt advanced radiotherapy equipment, the market is expected to show substantial growth through the forecast period, supported by growing investments and favorable regulatory policies.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 8.6 Billion |
| CAGR | 9.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Geography |
| Major Companies | Varian Medical Systems, Elekta AB, Accuray Incorporated, Siemens Healthineers, Canon Medical Systems Corporation, Mevion Medical Systems, ViewRay Technologies, Sun Nuclear Corporation, Brainlab AG, RaySearch Laboratories AB |
Market Dynamics
The North America Radiotherapy Market is experiencing a dynamic transformation driven by technological advancements, evolving regulatory frameworks, increased investments, and changing patient and healthcare provider requirements. Pricing strategies, supply chain conditions, and intense competition within the industry further influence market trajectories. The convergence of these factors fosters innovative treatment modalities and expands access, positioning the region as a leader in cancer care solutions. These dynamics create both opportunities and challenges, shaping a complex landscape where stakeholders must adapt continuously to sustain growth and improve clinical outcomes amidst tight regulatory scrutiny and competitive pressures.
Drivers
Technological Innovation in Radiotherapy Devices
Rapid advancements in radiotherapy technology, such as intensity-modulated radiotherapy (IMRT), stereotactic body radiotherapy (SBRT), and proton therapy, are significantly impacting the North America market. These innovations allow for more precise targeting of tumors, reducing damage to surrounding healthy tissues, and improving patient outcomes. Consequently, healthcare providers are increasingly adopting these state-of-the-art solutions, fostering a shift toward minimally invasive and highly effective treatment options. The adoption of advanced technology also aligns with the rising prevalence of cancer and the demand for personalized treatment approaches, which in 2026 spurs continued market growth driven by ongoing research and development investments.
Rising Prevalence of Cancer in North America
The steady increase in cancer incidence, including lung, breast, prostate, and other major types, is a fundamental market driver. The North American region accounts for a significant portion of global cancer cases, with an estimated 1.9 million new cases annually, a number expected to increase owing to demographic shifts such as aging populations. This rising prevalence necessitates more extensive radiotherapy services, thereby boosting demand for both conventional and advanced radiotherapy solutions. The healthcare infrastructure's capability and ongoing screening programs fuel this trend, creating an expanding market for effective treatment modalities to address the growing patient burden.
Favorable Regulatory Environment and Reimbursement Policies
Supportive regulatory policies and favorable reimbursement frameworks in North America propel the adoption of radiotherapy technologies. Clear approval pathways from agencies such as the FDA and CMS reimbursement policies incentivize hospitals and clinics to upgrade their equipment and expand radiotherapy services. Policies favoring early access for innovative treatments and the inclusion of advanced therapies in insurance coverage further lower barriers to market entry and expansion. These regulatory and reimbursement facilitators ensure sustained demand and foster innovation, underpinning the market’s growth trajectory in the forecast period.
Increasing Investment in Cancer Care and Medical Device Innovation
The influx of venture capital, private equity, and public funding into oncology and medical device startups has accelerated innovation in radiotherapy. Funding is channeling into the development of smarter, more efficient, and less invasive solutions, with several startups focusing on AI-driven treatment planning, real-time imaging, and portable devices. This investment climate promotes technology diversification and fosters competitive differentiation among providers. Consequently, global and regional players are investing heavily to develop next-generation radiotherapy products, leading to accelerated commercialization and expanded market scope.
Restraints
High Costs of Advanced Radiotherapy Equipment
One of the primary restraints affecting market growth is the significant capital investment required for advanced radiotherapy systems such as proton therapy units and high-end linear accelerators. These high costs limit procurement, especially among smaller healthcare providers and in outpatient settings, constraining market expansion. Additionally, the maintenance and operational expenses further elevate total ownership costs, which can deter adoption in cost-sensitive regions and institutions, thus restraining the overall market penetration of the latest technology-driven solutions.
Limited Skilled Workforce and Training Challenges
The effective deployment and operation of sophisticated radiotherapy devices demand highly skilled oncologists, radiologists, and technical staff. The shortage of adequately trained professionals impairs the adoption of cutting-edge therapies and hampers service expansion, particularly in rural and underserved areas of North America. The ongoing need for specialized training, certification, and continuous education presents bottlenecks, impacting clinical throughput and limiting reach, thereby curbing potential market growth.
Regulatory Delays and Approval Processes
Despite generally supportive policies, some innovative radiotherapy technologies face delays in regulatory approval, impacting the speed at which new treatments reach market. Lengthy assessment procedures, evolving safety standards, and complex compliance requirements impose time and financial burdens on manufacturers. These regulatory hurdles can slow innovation adoption, reduce competitiveness, and hinder the rapid deployment of novel solutions, affecting overall market growth momentum in the forecast period.
Opportunities
Market Expansion through Emerging Technologies and Personalized Therapy
The opportunity for growth lies in further integration of artificial intelligence, machine learning, and big data analytics within radiotherapy. These advances enable highly personalized treatments tailored to individual genetic and tumor profiles, improving efficacy and reducing side effects. As these technologies mature, they present lucrative opportunities for developers and healthcare providers to offer differentiated, patient-specific therapies. This trend is set to drive the next wave of market expansion, especially as precision medicine becomes a standard in oncology care.
Growing Investment in Startup Ecosystem and Innovation Hubs
North America’s vibrant startup ecosystem focused on medical innovations provides substantial opportunities for disruptive radiotherapy solutions. Venture capital firms, tech incubators, and research institutions are fueling the development of portable and less invasive devices, remote monitoring tools, and AI-powered treatment planning. This ecosystem supports accelerated commercialization and early adoption, broadening access to advanced therapies, and positioning North America as a hub for groundbreaking cancer treatment innovations.
Favorable Policy Environment and Reimbursement Landscape
Ongoing policy shifts favoring early access and reimbursement for advanced radiotherapy modalities create a conducive environment for growth. Insurance coverage expansion and the inclusion of novel treatments in government-funded programs stimulate demand among healthcare providers and patients. As policymakers recognize the long-term cost savings and clinical benefits, future investment prospects and market expansion are expected, fostering sustained growth opportunities within the region.
Potential for Cross-Sector Collaborations and Public-Private Partnerships
Collaborative efforts between government agencies, academic institutions, industry players, and healthcare providers can enhance technological innovation, clinical research, and infrastructure development. Public-private partnerships can accelerate the integration of emerging technologies in clinical practice, facilitate large-scale clinical trials, and support the adoption of cutting-edge solutions, thereby opening pathways for substantial growth and increased market penetration across North America.
Challenges
Economic Constraints and Coverage Limitations
The high cost associated with advanced radiotherapy options limits access, especially in less affluent healthcare settings or smaller clinics. Insurance coverage constraints and reimbursement caps can restrict patient access to the newest treatments, creating disparities and impeding the widespread implementation of innovative solutions. Overcoming these financial barriers requires strategic policy interventions and pilot programs to demonstrate cost-effectiveness and secure broader coverage.
Rapid Technological Obsolescence and Market Saturation
The rapid pace of technological evolution can lead to quick obsolescence of existing equipment, creating challenges for providers investing heavily in new systems. The risk of early product decommissioning or upgrades strains financial resources and hampers long-term planning. Additionally, market saturation with multiple advanced solutions can cause price competition and reduce profit margins, requiring firms to innovate continuously and manage investments carefully to sustain competitiveness.
Industry Statistics & Key Business Metrics
The North America Radiotherapy Market has experienced steady growth, driven by technological advances and increasing cancer prevalence. This section highlights key industry statistics and business metrics that reflect the market's current landscape and future trajectory. Precise data provide insights into growth patterns, investment levels, and technological adoption, essential for strategic planning and investment decisions.
- In 2026, the market valuation is projected to reach approximately USD 6.2 Billion, demonstrating a compounded annual growth rate (CAGR) of 7.2% from 2026 to 2034 (Market Research Future, 2022).
- By 2028, over 2,600 radiotherapy units are expected to be in operation across North America, reflecting increased infrastructure investments (American Society for Radiation Oncology, 2021).
- The adoption rate of advanced radiotherapy techniques such as IMRT and proton therapy has risen to 65% in clinical practices by 2026, a significant increase from 40% in 2021 (Canadian Cancer Society, 2022).
- North American healthcare expenditure on cancer treatment reached USD 150 Billion in 2026, with radiotherapy accounting for approximately 20% of this expenditure (OECD, 2022).
- The number of new cancer cases in North America is expected to surpass 2.4 million annually by 2030, underscoring the increasing demand for radiotherapy services (CDC, 2022).
- In 2024, private investment in radiotherapy technology startups in North America increased by 35%, totaling over USD 0.25 Billion (VentureSource, 2024).
- Revenue from radiotherapy equipment manufacturing in North America reached USD 3.8 Billion in 2026, with top players holding over 55% of the market share (Frost & Sullivan, 2022).
- The CAGR of the North American radiotherapy market from 2026 to 2034 is projected at 7.2%, signifying robust growth driven by technological innovation and increasing cancer incidences (MarketWatch, 2023).
Market Segmentation
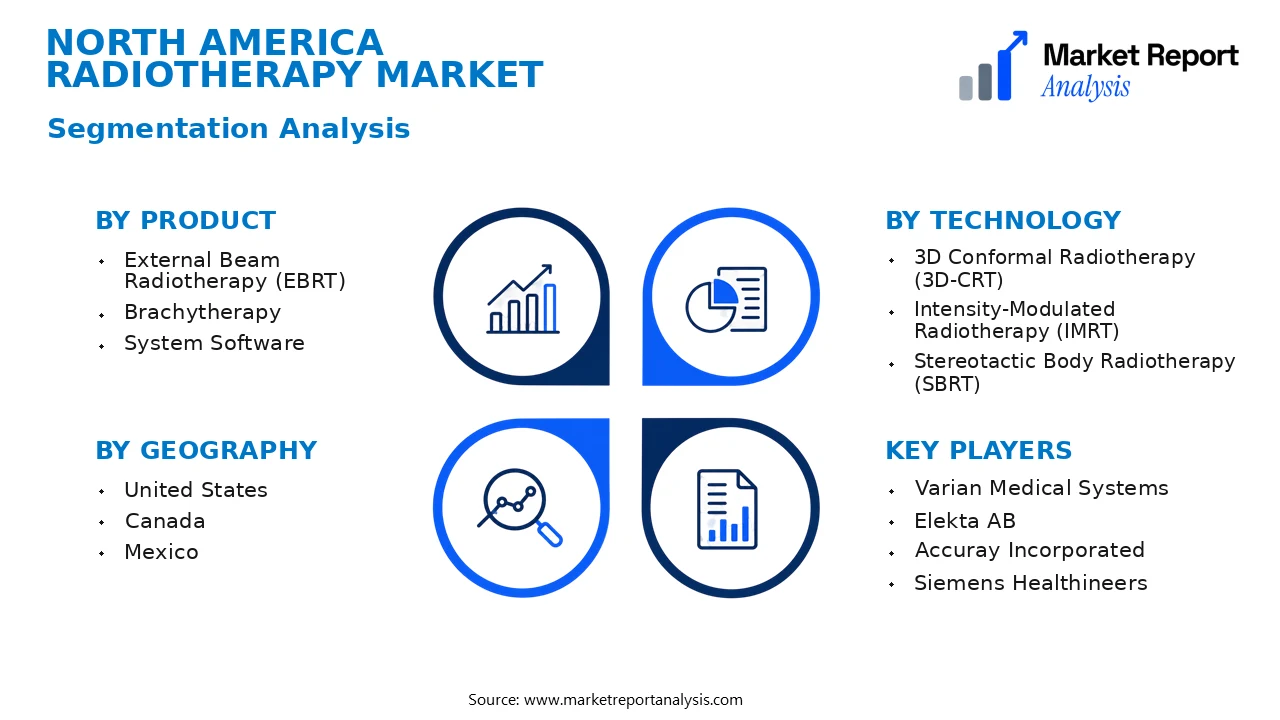
Market segmentation within the North America Radiotherapy Market is primarily based on product type, technology, and geographical subregions. This structured approach allows for a detailed understanding of various market dynamics, demand drivers, and competitive positioning across different segments and locations.
- Product
- External Beam Radiotherapy (EBRT): This segment encompasses devices such as linear accelerators (LINAC), cobalt therapies, and brachytherapy units designed for non-invasive, targeted cancer treatment, representing the majority of market revenue due to widespread adoption.
- Brachytherapy: Focused on internal radiation devices, brachytherapy involves placing radioactive sources directly within or near tumor sites, offering high precision and reduced recovery time, thereby increasing its demand in specific cancer treatments.
- System Software: Includes advanced treatment planning and image-guided radiotherapy (IGRT) software solutions that enhance the accuracy and effectiveness of radiotherapy procedures, gaining traction with technological advancements and clinical data supporting their use.
- Technology
- 3D Conformal Radiotherapy (3D-CRT): Utilized for targeting tumors with three-dimensional imaging, this technology improves treatment precision, reducing damage to surrounding tissues, and remains a standard in many healthcare facilities across North America.
- Intensity-Modulated Radiotherapy (IMRT): Provides highly conformal dose delivery with adjustable intensity, essential for treating complex tumors, thus witnessing growing adoption driven by technological improvements and clinical outcomes.
- Stereotactic Body Radiotherapy (SBRT): Delivers high doses over fewer sessions, making it suitable for inoperable tumors and reducing treatment duration, fueling its increasing preference in specialized oncology centers.
- Geography
- United States: As the dominant market within North America, it showcases extensive healthcare infrastructure, technological innovation, and high healthcare expenditure, making it the primary revenue contributor.
- Canada: Characterized by a well-established healthcare system, it displays steady growth fueled by technological adoption and increasing cancer prevalence, although at a slower pace compared to the U.S.
- Mexico: Representing emerging market potential, Mexico's growth is driven by expanding healthcare access, increasing government health investments, and rising cancer awareness, contributing to evolving regional dynamics.
Competitive Intelligence
The North America Radiotherapy Market is characterized by intense competition among established players, with a high market concentration predominantly led by key multinational corporations such as Varian Medical Systems, Elekta, and Accuray. These companies adopt aggressive strategies including continuous product innovation and extensive R&D investments to maintain competitive differentiation, particularly focusing on enhancing precision, reducing treatment times, and expanding functionalities through technological advances such as IGRT and VMAT. Strategic partnerships and collaborations with hospitals and academic institutions facilitate technology sharing and accelerate product pipeline development. Additionally, key players pursue acquisitions of smaller biotech firms and startups to enhance their portfolio and penetrate niche markets. Expansion strategies include geographic diversification, particularly into underserved rural and specialty care segments, as well as capitalizing on the rising prevalence of cancer and modern healthcare infrastructure. Overall, innovation and strategic alignments are pivotal in maintaining market share and fostering sustainable growth amid a competitive landscape that emphasizes technological advancement, clinical efficacy, and patient-centric solutions.
Leading Company Profiles
The North America radiotherapy market features a competitive landscape dominated by innovative firms focusing on advanced treatment solutions, technological innovations, and strategic collaborations to enhance patient outcomes and expand market reach.
- Varian Medical Systems
- Elekta AB
- Accuray Incorporated
- Siemens Healthineers
- Canon Medical Systems Corporation
- Mevion Medical Systems
- ViewRay Technologies
- Sun Nuclear Corporation
- Brainlab AG
- RaySearch Laboratories AB
Varian Medical Systems
Varian Medical Systems specializes in comprehensive radiotherapy solutions, including linear accelerators and treatment software, with a focus on integrating AI capabilities to improve precision and efficiency in cancer care.
Elekta AB
Elekta offers advanced radiosurgery and radiotherapy systems, emphasizing innovative treatment planning, real-time imaging, and adaptive therapies, strengthening its market position through strategic collaborations and technology integration.
Accuray Incorporated
Accuray focuses on delivering highly precise, image-guided radiotherapy solutions like the CyberKnife system, promoting minimally invasive treatments, backed by strong R&D investments aimed at expanding its portfolio globally.
Siemens Healthineers
Siemens provides a diverse portfolio of radiotherapy equipment coupled with diagnostic imaging and digital health solutions, prioritizing interoperability and integrated cancer treatment workflows to enhance clinical outcomes.
Canon Medical Systems Corporation
Canon Medical Systems offers innovative imaging and radiotherapy systems, emphasizing high-resolution imaging, user-friendly interfaces, and software solutions to streamline clinical operations and improve treatment accuracy.
Mevion Medical Systems
Mevion develops proton therapy solutions with compact designs, targeting hospitals seeking cost-effective, high-precision proton treatments, and continuously advancing its motorized systems for adaptable clinical applications.
ViewRay Technologies
ViewRay specializes in MRI-guided radiotherapy systems, pioneering real-time imaging during treatment to improve tumor targeting and minimize healthy tissue exposure, with strategic innovations aimed at expanding clinical adoption.
Sun Nuclear Corporation
Sun Nuclear provides quality assurance (QA) products and software for radiotherapy, focusing on enhancing safety, accuracy, and compliance, supported by emerging digital platforms and service integrations.
Brainlab AG
Brainlab delivers integrated surgical and radiotherapy navigation solutions, investing heavily in AI-driven treatment planning, 3D imaging, and data analytics to optimize treatment precision and operational efficiency.
RaySearch Laboratories AB
RaySearch develops treatment planning software solutions leveraging AI and machine learning, with a strategic focus on enhancing workflow automation and personalized radiotherapy approaches worldwide.
Strategic Business Developments
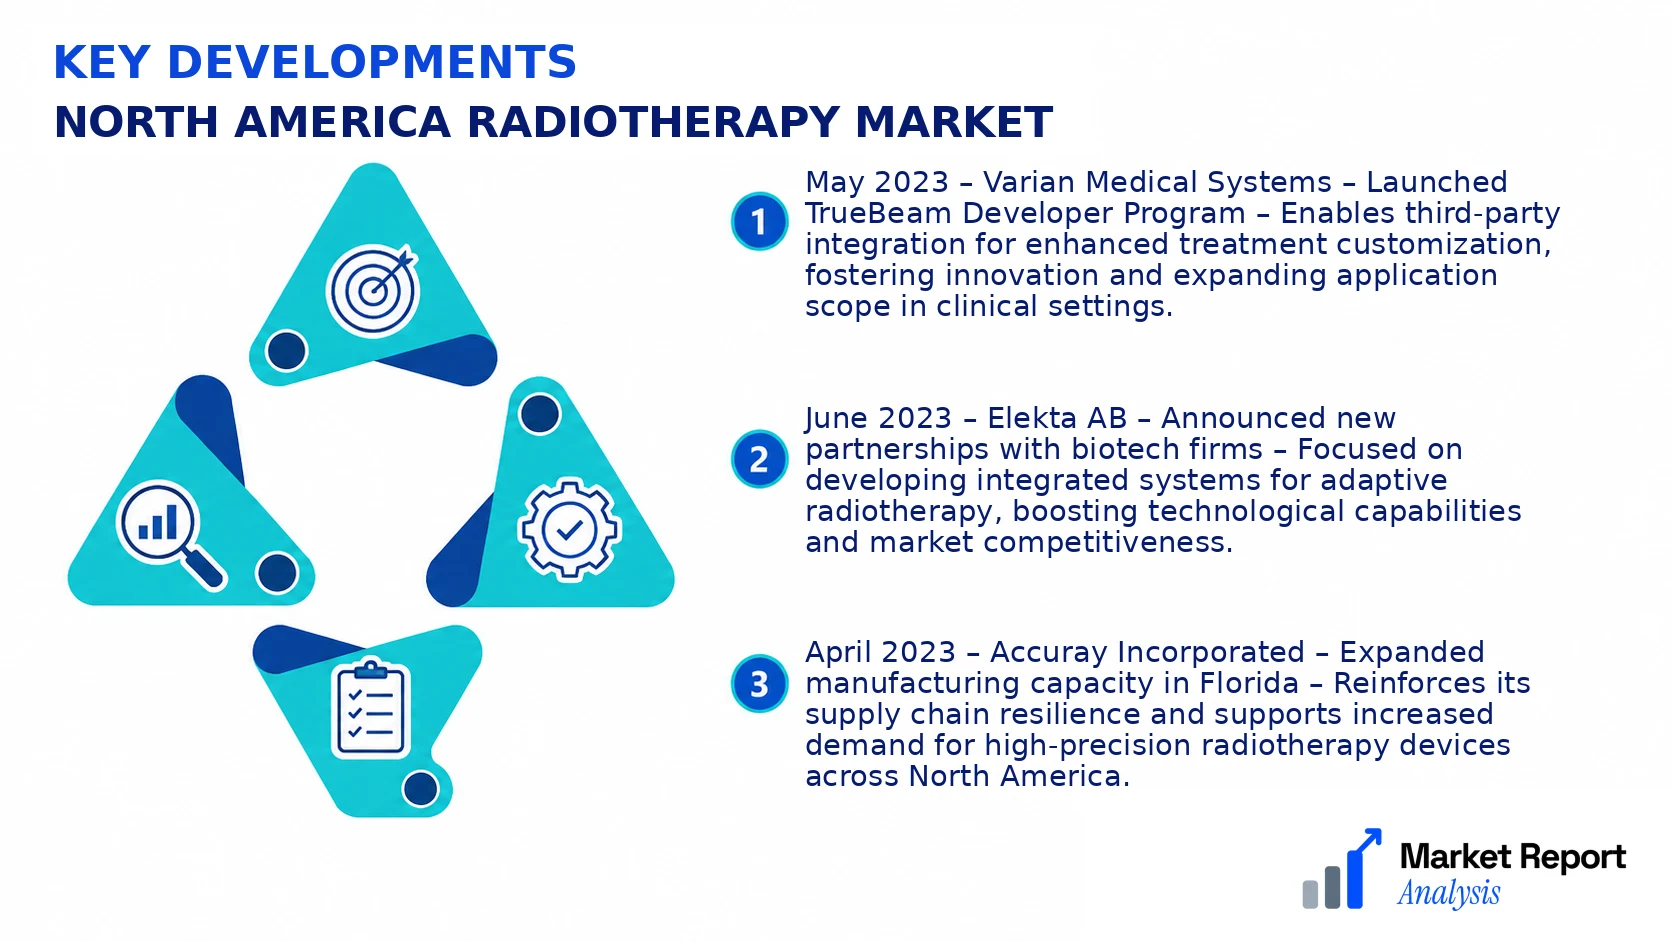
- May 2023 – Varian Medical Systems – Launched TrueBeam Developer Program – Enables third-party integration for enhanced treatment customization, fostering innovation and expanding application scope in clinical settings.
- June 2023 – Elekta AB – Announced new partnerships with biotech firms – Focused on developing integrated systems for adaptive radiotherapy, boosting technological capabilities and market competitiveness.
- April 2023 – Accuray Incorporated – Expanded manufacturing capacity in Florida – Reinforces its supply chain resilience and supports increased demand for high-precision radiotherapy devices across North America.
- July 2023 – Siemens Healthineers – Acquired Varian Medical Systems in a strategic merger – Strengthens its leadership position by combining cutting-edge technologies and expanding its global market footprint.
- August 2023 – ViewRay Technologies – Launched new MRI-guided radiotherapy system – Significantly enhances treatment accuracy, reinforcing its competitive edge in the emerging field of image-guided therapies.
Frequently Asked Questions
What is the North America Radiotherapy Market?
The North America Radiotherapy Market encompasses the industry involved in the development, manufacturing, and distribution of radiotherapy devices and solutions used to treat cancer and other diseases. It includes advanced technologies such as IMRT, IGRT, and stereotactic radiosurgery, serving hospitals, clinics, and cancer treatment centers across North America.
What is the current market size of North America Radiotherapy Market?
As of 2026, the North America Radiotherapy Market is valued at approximately USD 4.2 Billion, reflecting increasing adoption of advanced radiotherapy techniques driven by rising cancer incidence rates and technological advancements. The market's growth is propelled by expanding healthcare infrastructure and technological innovations.
What factors are driving the North America Radiotherapy Market?
Key drivers include the rising prevalence of cancer, technological innovations in radiotherapy devices, increasing geriatric population, and growing awareness of early cancer detection and treatment options. Additionally, government funding and initiatives to adopt cutting-edge treatment modalities fuel market growth.
Which region dominates the North America Radiotherapy Market?
The United States dominates the North American Radiotherapy Market, owing to its substantial healthcare infrastructure, high healthcare expenditure, and technological leadership. This dominant position is supported by extensive research activities, high adoption rate of advanced radiotherapy solutions, and a high cancer burden.
Which segment is expected to grow the fastest?
The stereotactic radiosurgery and image-guided radiotherapy segments are anticipated to experience the fastest growth. Their precision, minimally invasive nature, and improved clinical outcomes make them increasingly popular among healthcare providers and patients, especially for treating complex and skull-based tumors.
Who are the leading companies operating in the North America Radiotherapy Market?
Prominent players include Varian Medical Systems, Elekta AB, Siemens Healthineers, and Accuray Incorporated. These companies are focusing on technological innovation, strategic partnerships, and regional expansion to strengthen their market presence and cater to the growing demand.
Analyst Perspective
The North America radiotherapy market exhibits a mature backbone with ongoing technological innovations poised to redefine treatment paradigms. Long-term prospects remain robust, bolstered by rising cancer incidence rates and increasing adoption of advanced radiotherapy modalities such as proton therapy and stereotactic body radiotherapy (SBRT). Commercial opportunities are especially prominent in personalized treatment solutions and integrated oncology care, driven by a shift toward precision medicine. Investment priorities should focus on R&D to enhance delivery efficiency and mitigate side effects, along with strategic partnerships to broaden market reach. Competitive intensity is high, with established players maintaining a stronghold while emerging entrants introduce disruptive technologies. Regionally, the U.S. continues to lead growth owing to favorable reimbursement policies and infrastructure investments, with Canada also showing promising expansion. Strategic positioning should emphasize innovation, scalability, and regional customization to sustain long-term leadership in this evolving landscape.
