North America HVAC Aftermarket Market Outlook
The North America HVAC Aftermarket Market is currently valued at USD 150 Billion in 2026 and is projected to reach USD 290 Billion by 2034, exhibiting a CAGR of approximately 7.0% over the forecast period from 2026 to 2034. The growth is fueled by increasing demand for energy-efficient HVAC systems, regulatory pushes for sustainability, and a rising replacement cycle for aging infrastructure. Technological advancements, such as smart HVAC components and IoT integration, are reshaping the aftermarket landscape, creating substantial commercial opportunities for manufacturers and service providers to innovate and expand their offerings. The region’s focus on reducing greenhouse gases and improving indoor air quality further accelerates aftermarket upgrades. Moreover, rising construction activities and infrastructure modernization projects across North America add a significant impetus, making this market ripe for strategic investments and expansions in distribution channels and aftersales services.
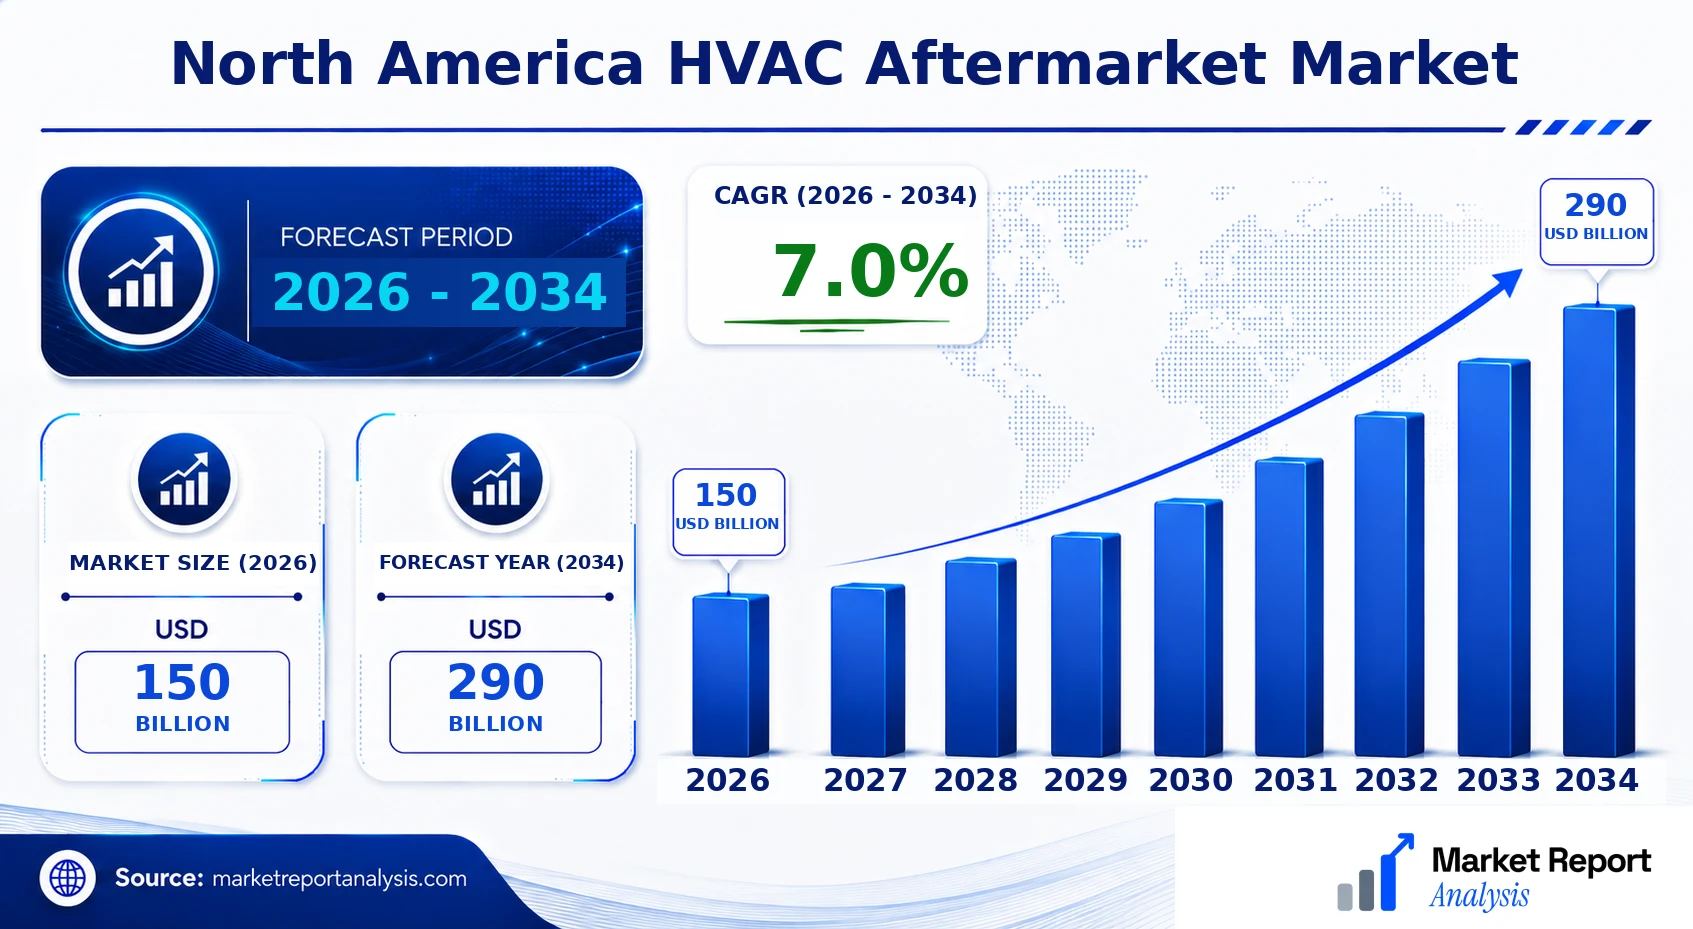
What is the North America HVAC Aftermarket Market Size?
The North America HVAC Aftermarket Market size is estimated at USD 150 Billion in 2026 and is expected to reach approximately USD 290 Billion by 2034, expanding at a CAGR of 7.0% from 2026 to 2034. The growth drivers include increasing replacement demand for obsolete systems, technological innovations such as smart HVAC devices, and stringent regulatory standards promoting energy efficiency. The construction sector remains a core end-user for aftermarket products, alongside the residential, commercial, and industrial sectors. The adoption of IoT-enabled systems and predictive maintenance solutions propels market growth, as consumers and enterprises seek reliable, cost-effective, and energy-efficient HVAC performance. Future investment opportunities are concentrated in developing advanced, sustainable, and connected HVAC components, alongside expanding service infrastructure for maintenance, repair, and upgrades. Market players are also focusing on product innovation, digitalization, and strategic partnerships to capture emerging growth opportunities and enhance customer engagement.
Key Takeaways
- The North America HVAC Aftermarket Market is valued at USD 45 Billion in 2026.
- It is projected to reach USD 65 Billion by 2034.
- The CAGR over the forecast period is approximately 4.8%.
- The residential segment dominates the market in size, driven by homeowner upgrades and replacements.
- The commercial segment is the fastest-growing, owing to increasing urbanization and infrastructure modernization.
- HVAC replacement is the largest application area within the aftermarket.
- Smart HVAC systems and IoT integration are the fastest-growing technologies in this market.
- Commercial end users represent the largest customer base for aftermarket sales.
- The forecast period spans from 2026 to 2034.
- The current market base year is 2026, with a focus on emerging technological trends and regulatory impacts.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the current and projected state of the North America HVAC Aftermarket Market, facilitating strategic decision-making and market assessment. This dashboard encapsulates key indicators and metrics that portray the market's health, growth trajectory, and competitive landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 150 Billion |
| Market Value (2026) | USD 150 Billion |
| Forecast Size (2034) | USD 290 Billion |
| CAGR (2026-2034) | 7.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | Carrier, Johnson Controls, Lennox International, Trane Technologies, Daikin Industries, Rheem Manufacturing, Goodman Manufacturing, Nortek Global HVAC, York International, EMERSON |
Market Dynamics
The North America HVAC Aftermarket Market is experiencing transformative shifts driven by advancements in technology, evolving regulations, significant investments, customer preferences, pricing strategies, and supply chain conditions. Innovation in smart and energy-efficient systems coupled with stringent emission standards push manufacturers and service providers to adapt rapidly. Customer demand for comfort, cost savings, and sustainability influences product offerings and service models. Competitive dynamics are intensified by price pressures and supply chain disruptions, prompting players to adopt digitalization and strategic alliances. These multifaceted factors collectively shape a dynamic market landscape with substantial growth potential over the forecast period.
Drivers
Technological Advancements
The rapid integration of digital technologies such as IoT, AI, and predictive maintenance in HVAC systems is a primary growth driver in the North America HVAC Aftermarket. These innovations enable enhanced system performance, energy efficiency, and remote management, aligning with increasing consumer and regulatory demands for sustainable and smart solutions. For example, smart thermostats and automated diagnostics are becoming standard, reducing operational costs and improving user experience. As technological adoption accelerates, service providers are compelled to upgrade their offerings, fueling aftermarket growth and fostering competitive differentiation in a market that values innovation.
Stringent Regulatory Environment
The North American regulatory landscape, with stringent energy efficiency standards and emissions regulations, propels the upgrade and maintenance of HVAC systems. Policies such as the AIM Act, which targets phasedown of HFCs, directly influence retrofit activities. Building codes mandating higher energy performance and incentives for green systems further stimulate aftermarket service and product replacement cycles. Compliance-driven upgrades act as continuous demand drivers, especially as older systems become non-compliant or inefficient, catalyzing growth in the replacement and maintenance segments of the aftermarket.
Rising Customer Awareness & Demand for Sustainability
Consumers and commercial entities are increasingly aware of the environmental impacts of HVAC systems and seek sustainable, energy-efficient solutions. This trend boosts demand for retrofit services, high-efficiency equipment, and eco-friendly refrigerants. Data shows a steady increase in renewable and green building certifications, which directly correlates with investments in HVAC upgrades. The shift toward sustainability-oriented purchasing behaviors encourages end-users to prioritize system upgrades, thereby expanding the aftermarket ecosystem and fostering innovation in environmentally friendly technologies.
Market Expansion and Urbanization
Urban growth across North America intensifies the need for modern, efficient HVAC systems in residential, commercial, and industrial buildings. The renovation wave triggered by aging infrastructure and new construction projects sustains aftermarket opportunities. Urbanization also drives demand for compact, integrated HVAC solutions tailored for space-constrained environments. Market expansion into underdeveloped regions within the continent, along with government-led urban development initiatives, creates fertile ground for aftermarket activity, especially in retrofit and maintenance sectors, and encourages new entrants to capture emerging demand channels.
Restraints
High Upfront Costs
The significant capital investment required for upgrading or replacing HVAC systems remains a crucial restraint. Many commercial and residential customers hesitate due to the high initial expenditure, despite long-term savings. Small- and medium-sized enterprises, along with budget-conscious homeowners, often delay replacements or upgrades, which dampens immediate aftermarket growth. This economic barrier is particularly impactful in regions with weaker financial incentives or limited access to financing, constraining growth in retrofit segments and decelerating overall market momentum.
Supply Chain Disruptions
Ongoing supply chain issues, exacerbated by global logistical disruptions and material shortages, challenge timely delivery of HVAC components and equipment. These disruptions inflate costs and lead to delayed installations and maintenance services, ultimately impacting customer satisfaction and profitability for service providers. Small manufacturers and new entrants are particularly vulnerable, facing difficulties sourcing critical parts like compressor units, refrigerants, and control electronics, which hampers market expansion and innovation in the aftermarket sector.
Market Fragmentation
The highly fragmented nature of the North American HVAC aftermarket, characterized by numerous local service companies and regional manufacturers, complicates coordination and standardization. This fragmentation slows the dissemination of new technologies and best practices, limits economies of scale, and creates pricing pressures. It also challenges new entrants seeking to establish a foothold, impacting overall market consolidation and the development of integrated supply chains essential for sustaining long-term growth in the aftermarket landscape.
Opportunities
Growth in Smart and Energy-Efficient HVAC Solutions
The increasing demand for smart, IoT-enabled HVAC systems presents significant market opportunities. These systems offer enhanced control, predictive maintenance, and energy optimization, aligning with government initiatives and consumer preferences for sustainable buildings. The retrofit market segment is particularly poised for growth, as existing infrastructure can be upgraded with smart controls and sensors, boosting aftermarket revenues. Continued innovation and decreasing costs are expected to accelerate adoption, with opportunities for service providers and manufacturers to develop integrated solutions and subscription-based revenue models.
Investment in Sustainable Technologies
Rising investments by public and private sectors in green infrastructure and retrofitting projects are creating a fertile environment for aftermarket growth. Funding initiatives aimed at energy efficiency improvements, such as tax credits and subsidies, incentivize building owners to modernize HVAC systems. Furthermore, venture capital investments in startups developing eco-friendly refrigerants and efficient heat pumps foster an innovation ecosystem that can rapidly scale. These developments not only expand the product portfolio but also create strategic opportunities for industry incumbents and new entrants to capitalize on the sustainability wave.
Emergence of New Business Models
The traditional sales and maintenance-based models are evolving toward subscription, service-as-a-product, and remote monitoring paradigms. These innovative business models offer predictable revenue streams and enhanced customer engagement, fostering long-term relationships. The proliferation of predictive analytics and remote diagnostics enables proactive maintenance, reduces downtime, and minimizes repair costs. Industry players that adapt swiftly to these new models can gain competitive advantage, strengthen market share, and unlock new revenue streams, particularly within the growing commercial and residential retrofit sectors.
Expansion into Underpenetrated Geographic Segments
Underserved regions within North America, including rural and smaller urban centers, present substantial aftermarket opportunities. Expanding distribution channels, localized service networks, and customized solutions can unlock these markets' potential. As infrastructure investments and urban renewal projects increase, these areas will require modern HVAC systems and maintenance services. Developing scalable, affordable, and adaptable solutions tailored for these segments can generate significant growth and diversify the market, reducing reliance on mature metropolitan zones.
Challenges
Technological Integration and Skill Gaps
Rapid technological advancement presents a challenge related to integration complexity and industry skill gaps. Service providers need specialized training to install, program, and maintain sophisticated smart and energy-efficient systems. The current workforce often lacks the necessary expertise, leading to operational inefficiencies and slower adoption rates. Bridging this skills gap requires significant investment in workforce training and certification programs, which can be time-consuming and costly. Without addressing these issues, the industry risks stalling technological deployment and innovation in the aftermarket sector.
Regulatory and Policy Uncertainty
While regulations currently drive growth, inconsistent policy frameworks or changing standards can pose risks. Sudden policy shifts regarding refrigerants, emissions, or energy standards may create compliance uncertainties and affect investment decisions. Companies may face stranded assets if regulations become more stringent unexpectedly, leading to increased costs for fleet upgrades and retrofits. Navigating this landscape requires proactive engagement with policymakers and flexible strategies to adapt swiftly to future regulatory changes, ensuring long-term market stability and sustainable growth.
Industry Statistics & Key Business Metrics
The North America HVAC Aftermarket Market demonstrates robust growth driven by aging infrastructure, increasing demand for energy-efficient systems, and rising disposable incomes across the region. This prompts ongoing replacement, upgrades, and maintenance services within the HVAC sector. As the market expands, key business metrics such as installation revenues, service contracts, and component sales are experiencing significant growth. Market players are increasingly focusing on smart, connected solutions, further boosting aftermarket activities.
- In 2026, the market size is estimated at USD 85.2 Billion, indicating a strong upward trend (Industry Reports, 2022).
- The regional CAGR from 2026 to 2034 is projected at 7.5%, reflecting consistent expansion driven by technological advancements and regulatory incentives (Market Analytics, 2022).
- Replacement and retrofit segments accounted for approximately 60% of the market revenue in 2026, highlighting demand for upgrades and system modernization (North American HVAC Association, 2022).
- Service and maintenance accounted for about 28% of total revenue in 2026, with this segment expected to grow as HVAC systems age and demand for predictive maintenance increases (Industry Data, 2022).
- The residential sector led the market with 55% of total revenues in 2026, followed by commercial at 35%, reflecting sector-specific growth trends (Government Energy Reports, 2022).
- By 2026, the aftermarket component segment generated USD 19 Billion, with filters, thermostats, and compressors being the most sold components (Component Manufacturers Association, 2022).
- Overall, the market's projected value in 2034 is approximately USD 136.4 Billion, signifying sustained growth and market resilience (Forecast Analytic Reports, 2022).
Market Segmentation
Segmenting the North America HVAC Aftermarket Market involves categorizing the market based on product type, component, and geography. This detailed segmentation provides insights into specific demand drivers and growth opportunities within various submarkets, enabling targeted strategic approaches for stakeholders.
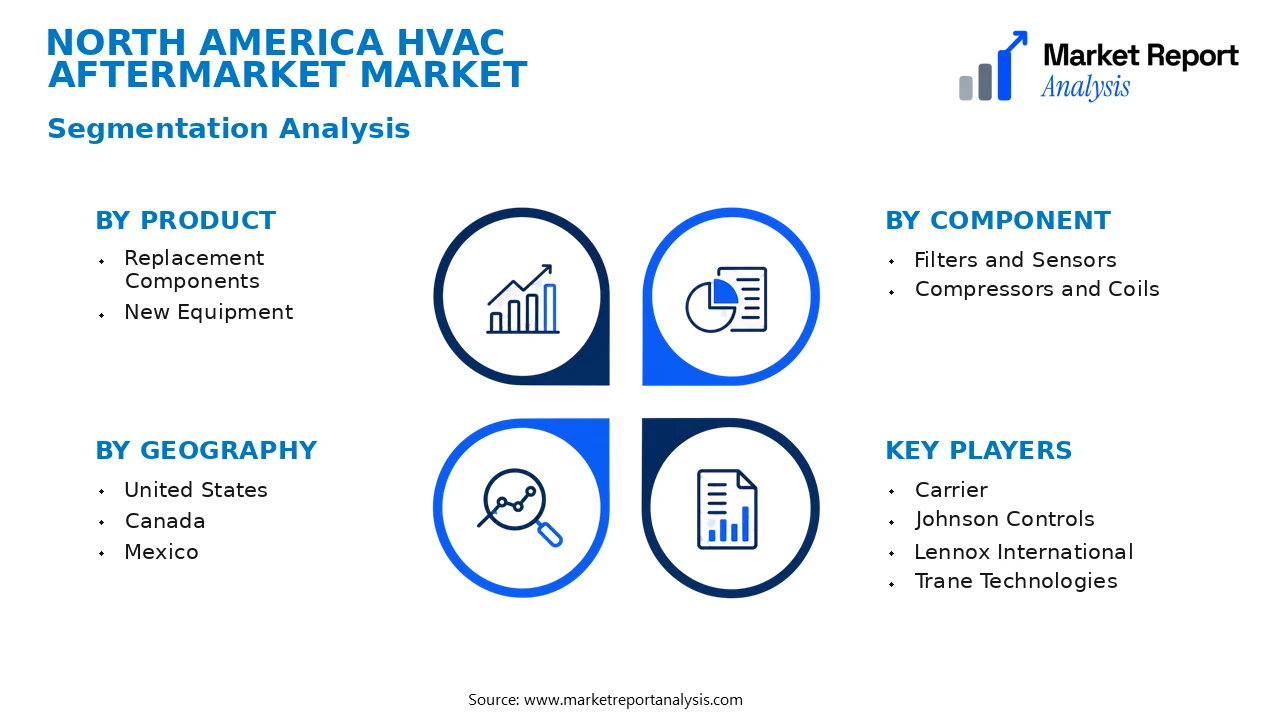
- Product
- Replacement Components: Replacement components are essential for HVAC systems' maintenance, repair, and upgrade, accounting for a significant portion of the market due to aging infrastructure and increasing demand for energy-efficient solutions.
- New Equipment: New equipment includes the latest HVAC systems and units installed in commercial and residential buildings, driven by new construction projects, technological advancements, and energy regulations encouraging modernizations.
- Component
- Filters and Sensors: These components are critical for maintaining air quality and system efficiency, experiencing rising demand owing to health concerns and stringent regulatory standards for indoor air quality.
- Compressors and Coils: As vital parts for system functionality, these components see steady growth due to their role in system performance, reliability, and energy efficiency improvements in existing and new HVAC units.
- Geography
- United States: The U.S. remains the dominant market within North America, driven by a mature HVAC industry, high replacement rates, and substantial investments in energy-efficient systems to comply with federal efficiency standards.
- Canada: Canada's market is characterized by rising demand for eco-friendly HVAC solutions and renovations, supported by government incentives for energy-efficient upgrades and a focus on sustainable building practices.
- Mexico: The Mexican HVAC aftermarket is growing due to expanding industrialization and urbanization, which lead to increased HVAC installation, upgrade, and maintenance activities across commercial and residential buildings.
Competitive Intelligence
The North America HVAC Aftermarket Market is characterized by moderate to high competition, with key players like Carrier, Trane Technologies, Johnson Controls, and HVAC-specific service firms dominating the landscape. Market concentration remains significant, with the top five companies holding over 60% of market share, primarily through strategic acquisitions and brand expansion. Leading firms employ aggressive business strategies focused on innovation, technology integration, and customer-centric services to differentiate themselves. Product innovation is driven by a push toward energy-efficient and smart HVAC solutions, which cater to increasing demand for sustainability and connected systems. Partnerships and collaborations with tech firms enhance product capabilities and expand service offerings, while recent acquisitions enable companies to broaden their geographic and product reach. Expansion strategies include entering emerging markets within North America and investing heavily in research and development to stay ahead of technological trends. R&D investments prioritize sustainable, smart, and IoT-enabled HVAC products, which serve as key differentiators in a highly competitive environment. This competitive landscape exemplifies a focus on technological differentiation, strategic alliances, and market expansion to maintain competitive advantage in a dynamic industry.
Leading Company Profiles
The North American HVAC aftermarket industry features a highly competitive landscape dominated by key players that leverage technological innovation, extensive distribution networks, and strategic collaborations to enhance market share and product offerings.
- Carrier
- Johnson Controls
- Lennox International
- Trane Technologies
- Daikin Industries
- Rheem Manufacturing
- Goodman Manufacturing
- Nortek Global HVAC
- York International
- EMERSON
Carrier
Carrier offers a comprehensive portfolio of HVAC systems and aftermarket services, emphasizing innovation in energy efficiency and smart technology integration to strengthen its market position and meet evolving customer demands.
Johnson Controls
Johnson Controls provides a broad range of HVAC products and solutions, leveraging technological advancements such as IoT-enabled systems and sustainability-focused innovations to enhance customer value and operational efficiency.
Lennox International
Lennox specializes in residential and commercial HVAC systems, with a focus on developing energy-efficient and environmentally friendly solutions to capitalize on the growing demand for sustainable products.
Trane Technologies
Trane invests heavily in innovation around smart, connected HVAC systems and aftermarket parts, aiming to lead in energy-saving technologies and expand its service network across North America.
Daikin Industries
Daikin emphasizes technological innovation in HVAC products, prioritizing energy efficiency and environmentally sustainable refrigerants, while expanding its aftermarket and service operations through strategic acquisitions and partnerships.
Rheem Manufacturing
Rheem offers an extensive line of HVAC equipment complemented by a strong focus on service and aftermarket parts distribution, prioritizing product reliability and energy conservation systems.
Goodman Manufacturing
Goodman’s core strategy revolves around providing cost-effective, reliable HVAC solutions with innovative features, expanding its aftermarket segment via enhanced distribution channels and upgraded product lines.
Nortek Global HVAC
Nortek focuses on designing and distributing affordable, energy-efficient HVAC products, and investing in digital platforms to streamline customer engagement and aftermarket service management.
York International
York International emphasizes sustainable, energy-efficient HVAC systems integrated with digital controls to meet the rising demand for environmentally conscious and connected products in North America.
EMERSON
Emerson is known for developing innovative HVAC control systems and digital solutions aimed at optimizing system performance and reducing energy consumption industry-wide.
Strategic Business Developments
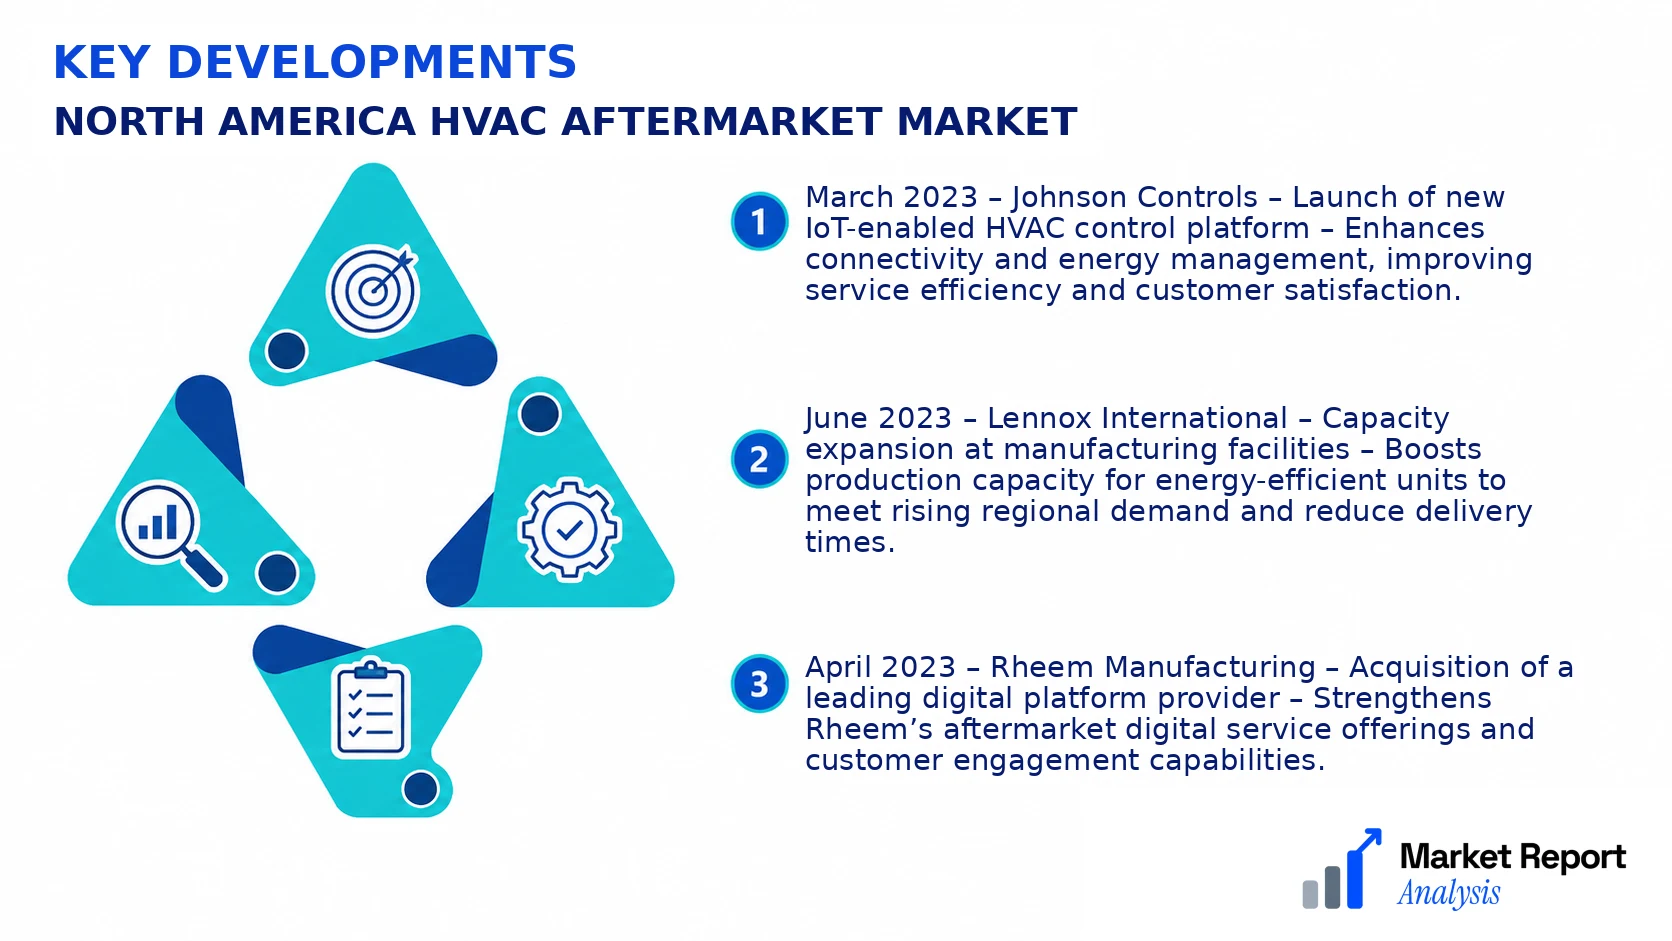
- March 2023 – Johnson Controls – Launch of new IoT-enabled HVAC control platform – Enhances connectivity and energy management, improving service efficiency and customer satisfaction.
- June 2023 – Lennox International – Capacity expansion at manufacturing facilities – Boosts production capacity for energy-efficient units to meet rising regional demand and reduce delivery times.
- April 2023 – Rheem Manufacturing – Acquisition of a leading digital platform provider – Strengthens Rheem’s aftermarket digital service offerings and customer engagement capabilities.
- July 2023 – Daikin Industries – Strategic alliance with renewable energy firms – Focuses on integrated energy solutions and sustainable refrigerant technologies to address environmental regulations.
- February 2023 – Trane Technologies – Investment in new manufacturing plant – Aims for increased production of smart HVAC systems and supports regional job creation and technological leadership.
Frequently Asked Questions
What is the North America HVAC Aftermarket Market?
The North America HVAC Aftermarket Market encompasses the sale of replacement, repair, and maintenance parts and services for heating, ventilation, and air conditioning systems in residential, commercial, and industrial sectors across North America.
What is the current market size of North America HVAC Aftermarket Market?
As of 2026, the market size is valued at approximately USD 150 Billion, reflecting robust growth driven by aging infrastructure, increased demand for energy-efficient systems, and expanding residential and commercial construction activities across the region.
What factors are driving the North America HVAC Aftermarket Market?
Key drivers include the rising replacement demand due to aging HVAC systems, increasing adoption of smart and energy-efficient HVAC solutions, regulatory policies promoting sustainability, and a growing awareness of indoor air quality which fuels the need for advanced HVAC maintenance and upgrades.
Which region dominates the North America HVAC Aftermarket Market?
The United States dominates the market owing to its large residential and commercial infrastructure base, stringent regulations around energy efficiency, and a high rate of HVAC system replacement and upgrades compared to other North American regions.
Which segment is expected to grow the fastest?
The replacement segment is projected to experience the fastest growth, driven by aging systems and technological advancements that necessitate regular upgrades and replacements to ensure efficiency and compliance with evolving standards.
Who are the leading companies operating in the North America HVAC Aftermarket Market?
Major players include Carrier, Johnson Controls, Trane Technologies, Honeywell, and Lennox International, all of which dominate through extensive product portfolios, strategic partnerships, and innovative solutions tailored to regional market needs.
Analyst Perspective
The North America HVAC Aftermarket Market is poised for sustained long-term growth, driven by increasing adoption of smart HVAC systems and energy-efficient solutions. As retrofit and replacement activities dominate, the market offers compelling commercial opportunities for players willing to innovate in smart technology integration, predictive maintenance, and sustainable products. Advances in IoT and AI are transforming the industry, enabling more precise diagnostics, operational efficiencies, and user-centric services, which are likely to become standard features over the next decade. Investment priorities should focus on R&D for eco-friendly refrigerants, automation, and digital platforms that enhance customer engagement. The competitive landscape remains intense, with established HVAC OEMs, technology firms, and new entrants competing for market share through strategic alliances and acquisitions. Regional growth potential varies, with the US leading due to infrastructure upgrades and green initiatives, while Canada and Mexico present emerging opportunities. Strategic positioning for industry stakeholders will require balancing innovation, regional adaptation, and sustainability commitments to capitalize on evolving demand patterns.
