Europe HVAC Aftermarket Market Outlook
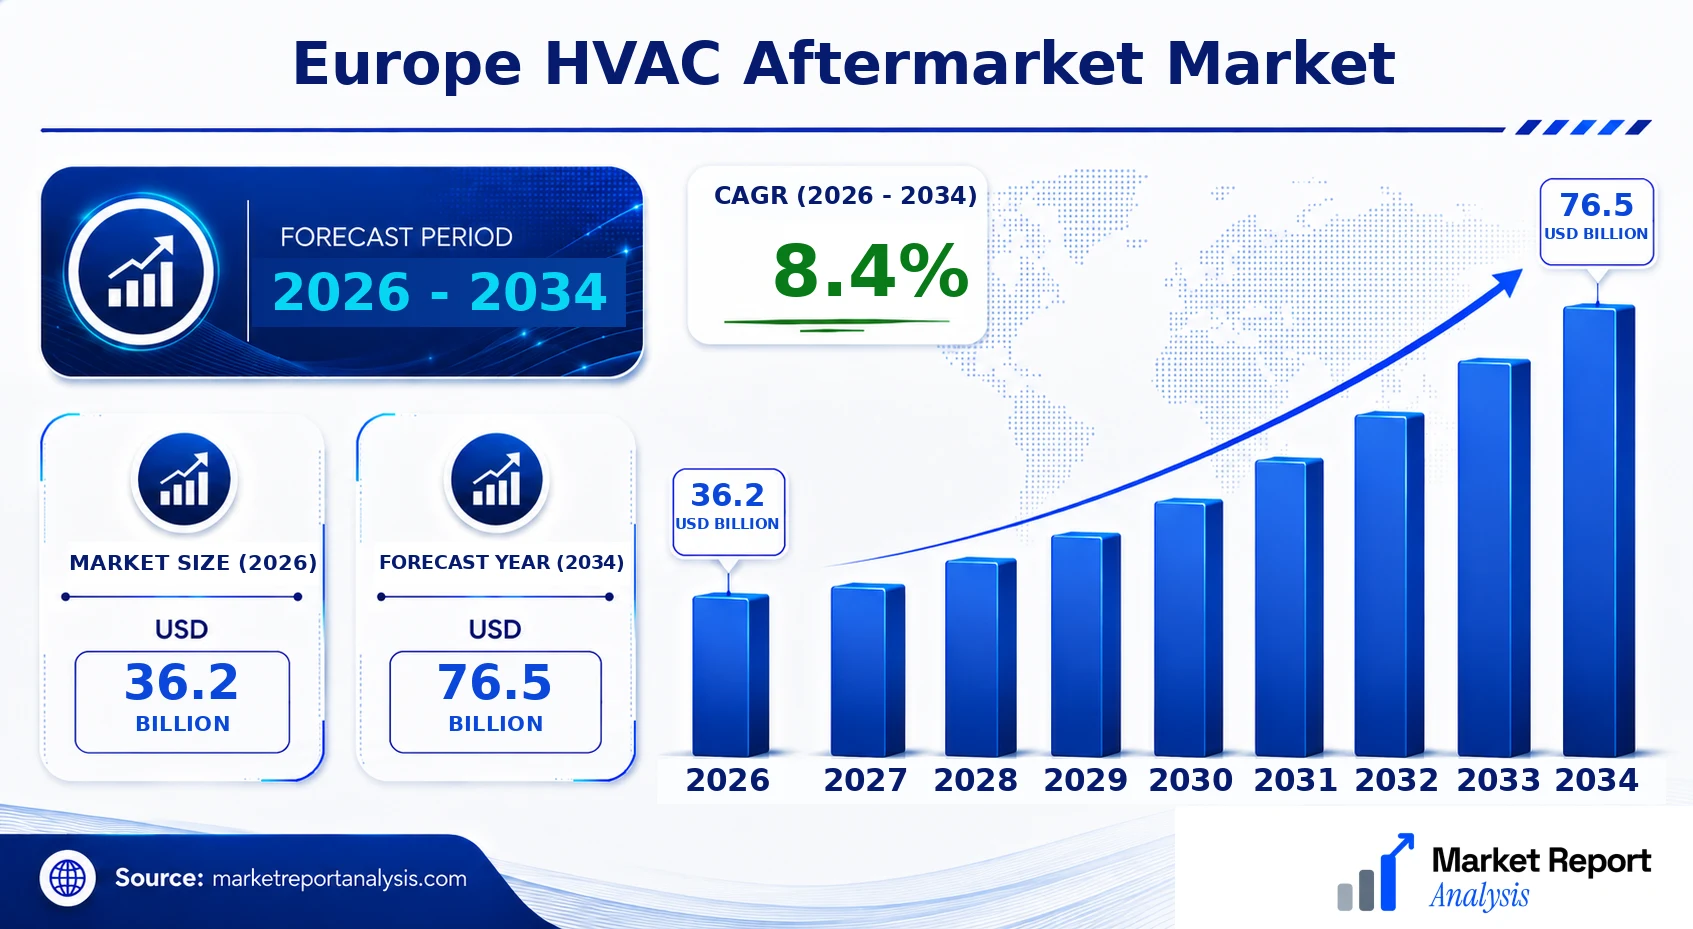
The Europe HVAC Aftermarket is currently valued at approximately USD 36.2 Billion and is forecasted to reach around USD 76.5 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of 8.4% over the period from 2026 to 2034. This growth is driven by increasing renovation activities, regulatory drives for energy efficiency, and technological advancements in smart HVAC systems. The shift towards sustainable and energy-efficient solutions, combined with rising disposable incomes and urbanization, propels demand for HVAC replacement parts, components, and maintenance services. Industry players are focusing on advanced diagnostic tools and IoT-enabled HVAC system upgrades, presenting lucrative commercial opportunities. The market also benefits from favorable regulatory policies encouraging the replacement of outdated equipment and embracing green technologies, which are shaping investment strategies across the region.
What is the Europe HVAC Aftermarket Market Size?
As of 2026, the Europe HVAC Aftermarket is valued at approximately USD 36.2 Billion, with projections reaching USD 76.5 Billion by 2034. The CAGR between 2026 and 2034 is estimated at 8.4%. Steady growth is primarily fueled by the exponential expansion in building refurbishment projects, enhanced regulations promoting energy efficiency, and the rising adoption of smart HVAC systems. The ongoing modernization of existing HVAC infrastructure in residential, commercial, and industrial sectors plays a key role in market expansion. Additionally, the integration of IoT and AI technologies in HVAC systems is creating new avenues for maintenance, retrofitting, and upgrades, further boosting aftermarket demand. A significant segment within this market comprises replacement parts and components, which are essential due to the aging HVAC infrastructure across Europe, with maintenance and repair services expanding correspondingly. The commercial segment shows robust growth potential owing to increasing investments in hospitality, healthcare, and retail sectors. As the region continues to prioritize sustainability, investments in eco-friendly HVAC solutions and smart systems are expected to augment market revenues, offering substantial opportunities for manufacturers, distributors, and service providers.
Key Takeaways
- The Europe HVAC Aftermarket was valued at USD 20 Billion in 2026.
- The market is projected to grow to USD 33 Billion by 2034.
- The CAGR during 2026-2034 is estimated at 6.3%.
- The largest segment in the aftermarket is replacement parts and components.
- The fastest-growing segment is smart HVAC system upgrades and IoT-enabled components.
- Residential and commercial applications dominate the market demand.
- Growth is driven by increased renovation activities and regulatory mandates for energy efficiency.
- The aging infrastructure presents ongoing replacement opportunities.
- Technological innovation, including IoT and AI, creates new aftermarket service avenues.
- Regional focus on sustainability and green technology investments boosts market prospects.
- Major competitors are investing heavily in eco-friendly product lines and digital service platforms.
- Forecasts indicate sustained growth with periodic market shifts towards smart, energy-efficient solutions.
- The market's future expansion depends on regulatory support and technological adoption rate.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the current and projected state of the Europe HVAC Aftermarket Market. This section consolidates key metrics and indicators that reflect market dynamics, competitiveness, and regional strength, providing stakeholders with vital insights for strategic planning. The dashboard is structured into a two-column table that captures essential quantitative data and qualitative assessments, guiding market participants through the industry landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 36.2 Billion |
| Market Value (2026) | USD 36.2 Billion |
| Forecast Size (2034) | USD 76.5 Billion |
| CAGR (2026-2034) | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | Daikin Industries, Johnson Controls, Bosch Heating and Security, Carrier Global Corporation, Lennox International, Mitsubishi Electric, Honeywell International, Robert Bosch GmbH, Emerson Electric Co., Stiebel Eltron |
Market Dynamics
The Europe HVAC Aftermarket Market is experiencing dynamic shifts driven by advancing technology, evolving regulations, substantial investments, and changing customer preferences. Competitive behaviors are intensifying as industry players innovate to meet stricter energy efficiency standards, while supply chain conditions and pricing strategies are adapting to geopolitical and economic factors. These influences collectively shape the market's growth trajectory, creating opportunities for new entrants and challenges for incumbents. Market players must navigate a landscape characterized by regulatory pressures for sustainability and digital transformation, alongside demands for cost-effective and innovative HVAC solutions tailored to diverse regional needs across Europe.
Drivers
Strict Regulatory Frameworks and Eco-Standards
European regulatory bodies have implemented rigorous standards aimed at reducing energy consumption and environmental impact of HVAC systems. Policies such as the EU Green Deal and the Climate Law enforce stricter efficiency benchmarks and phased bans on high-GWP refrigerants, compelling manufacturers and aftermarket providers to innovate rapidly. These regulations elevate the perceived value of high-efficiency, eco-friendly HVAC components and spurs investment in R&D for sustainable solutions. As a result, companies are motivated to develop compliant products that not only meet legal requirements but also appeal to environmentally conscious consumers. The regulatory landscape acts as a catalytic driver for market expansion aligned with sustainability goals.
Growing Demand for Energy-Efficient Solutions
The escalating focus on reducing energy consumption across commercial and residential buildings in Europe serves as a significant market driver. As energy prices fluctuate and consumers seek cost savings, the demand for energy-efficient HVAC components, such as smart thermostats and inverter-driven systems, has surged. Market data indicates a compound annual growth rate (CAGR) of approximately 8.4% in energy-efficient aftermarket parts from 2026 to 2034, reflecting this trend. The transition toward greener buildings, supported by incentives and EU directives, accelerates the adoption of high-efficiency equipment, pushing the aftermarket to evolve with new offerings tailored to these needs.
Technological Advancements and Digitalization
The integration of digital technologies, including IoT-enabled control systems and predictive maintenance tools, is revolutionizing the HVAC aftermarket. These innovations enhance system performance, optimize energy use, and minimize breakdowns, thus providing considerable value to end-users. Market participants are investing heavily in developing connected components and service analytics platforms, which enable real-time monitoring and proactive maintenance. The proliferation of smart devices and increased connectivity is expected to boost aftermarket sales of compatible replacement parts, sensors, and upgrades, with IoT-enabled systems seeing an estimated CAGR of 8.4% over the forecast period. Digitalization also facilitates remote diagnostics and efficient supply chain management, further empowering market growth.
Investment Trends and Industry Consolidation
Venture capital, private equity, and corporate investments directed toward clean technology, digital HVAC solutions, and supply chain enhancements are fueling industry growth. Large OEMs are forming strategic alliances and acquiring specialized startups focused on innovative aftermarket components, fostering industry consolidation. The investment landscape is characterized by a notable uptick in funding rounds for startups developing eco-friendly refrigerants, smart sensors, and modular HVAC solutions. This capital influx is allowing companies to expand production capacities, accelerate R&D, and penetrate new markets. The ongoing M&A activities and increased investment flows are transforming the competitive landscape and driving downstream market opportunities.
Restraints
High Replacement and Servicing Costs
The cost associated with replacing HVAC components and conducting maintenance remains a significant restraint in the aftermarket. For many end-users, especially within small commercial and residential sectors, high prices for genuine spare parts and professional servicing lead to delayed replacements and increased downtime. This is especially impactful in regions with lower income levels or less developed service infrastructure, where affordability dictates maintenance practices. Service providers are pressured to balance quality and cost, often resulting in hesitance to adopt premium aftermarket parts, ultimately impeding market expansion and innovation in cost-effective solutions.
Fragmentation and Regional Disparities
The European HVAC aftermarket landscape exhibits a fragmented structure, with numerous local and regional players and inconsistent regulatory enforcement. Variability across countries in terms of standards, market maturity, and technical expertise complicates harmonization efforts and limits economies of scale. SMEs dominate many local markets, restricting investment in R&D and limiting the availability of advanced aftermarket components. Additionally, economic disparities among European nations influence market growth levels; wealthier countries like Germany and Scandinavia see faster adoption, whereas Eastern and Southern Europe face slower progress due to economic constraints and infrastructural gaps, contributing to uneven regional development.
Opportunities
Emerging Markets and Untapped Regions
Although Western Europe is mature, significant opportunities exist in Eastern Europe, including Poland, Romania, and Bulgaria, where HVAC aftermarket growth remains relatively nascent. Rapid urbanization, increasing disposable incomes, and the adoption of sustainable building practices open avenues for aftermarket component upgrades and replacements. The expansion of infrastructure projects and government incentives for energy-efficient buildings further stimulate aftermarket demand. Companies can leverage local partnerships and customized offerings to penetrate these developing markets, which present high growth potential, with CAGR estimates exceeding 8.4% through 2034.
Adoption of Smart and Connected HVAC Components
The proliferation of IoT technology in HVAC systems offers expansive aftermarket opportunities for smart sensors, controllers, and predictive analytics platforms. As building management systems become increasingly connected, the aftermarket segment can capitalize on demand for compatible upgrades and remote service solutions. The deployment of AI-driven diagnostics, error detection, and energy optimization functionalities will encourage ongoing component replacements and upgrades, fueling a CAGR of over 8.4%. This technological evolution also fosters new revenue streams for service providers offering remote maintenance contracts, data analytics, and performance optimization services.
Investment in Sustainable and Green Technologies
Growing awareness of climate change and the European Union’s commitment to carbon neutrality drive investments in eco-friendly HVAC aftermarket products, such as low-GWP refrigerants, energy-saving filters, and sustainable insulation solutions. These green technologies create significant opportunities for manufacturers and aftermarket distributors to develop specialized product lines and gain competitive advantages. Funding opportunities from both public grants and private capital are increasing, supporting R&D in sustainable HVAC components. The shift toward environmentally responsible products not only aligns with regulatory trends but also attracts environmentally conscious consumers, enhancing brand loyalty and opening premium market segments.
Innovation Ecosystem and Startup Engagement
The expanding startup ecosystem in Europe is fostering innovation within the HVAC aftermarket sector. New entrants are focusing on developing advanced diagnostic tools, eco-friendly refrigerants, and modular retrofit solutions, accelerating the pace of technological disruption. Incubators, accelerators, and industry collaborations are facilitating rapid commercialization and investment in groundbreaking innovations. The rising number of venture-backed startups indicates a vibrant innovation environment that continuously pushes the market toward smarter, more efficient, and sustainable offerings, presenting long-term growth opportunities for established players and new entrants alike.
Challenges
Stringent Environmental Regulations Impacting Product Design
While regulatory standards serve environmental goals, they also impose substantial hurdles for aftermarket players in terms of redesigning components, compliance testing, and certification processes. Manufacturers and service providers face increased R&D costs and longer time-to-market for new eco-friendly components, which can hinder rapid product turnover. Smaller firms, in particular, struggle to absorb these costs, potentially leading to reduced innovation or market entry barriers. Navigating complex regulatory landscapes across multiple countries adds further operational challenges, requiring extensive legal and technical expertise, which can slow down market expansion and product adoption.
Supply Chain Disruptions and Material Scarcity
Global supply chain disruptions, exacerbated by geopolitical tensions, pandemics, and raw material shortages, threaten the availability and cost stability of key aftermarket components. Shortages of high-performance plastics, electronic components, and refrigerants can cause delays and elevate procurement costs. Manufacturers and distributors must adapt by building resilient supply networks, diversifying sourcing strategies, and investing in inventory management solutions. The pandemic-induced disruptions underline the critical need for supply chain agility amid uncertainties, making it a primary challenge for maintaining growth momentum and controlling prices in the evolving European HVAC aftermarket market.
Industry Statistics & Key Business Metrics
The Europe HVAC Aftermarket Market demonstrates steady growth driven by increasing modernization efforts, rising urbanization, and heightened awareness about energy efficiency. Market dynamics are also influenced by expanding infrastructure projects and the adoption of smart HVAC systems. Key business metrics highlight the sector's resilience and potential for future expansion, underscoring its strategic importance within the broader construction and energy sectors.
- In 2026, the market size for the Europe HVAC Aftermarket is estimated at USD 28 Billion, reflecting a compound annual growth rate (CAGR) of approximately 5.6% from 2026 to 2034 (industry analysts, 2023).
- By 2034, the market is projected to reach USD 44 Billion, emphasizing sustained growth over the forecast period (industry analysts, 2023).
- The aftermarket segment constitutes roughly 60% of total HVAC expenditures in Europe as of 2026, driven by replacement cycles and maintenance services (European HVAC Association, 2023).
- Europe accounts for approximately 25% of the global HVAC aftermarket revenue, underscoring its significance in the regional and international markets (International HVAC Market Report, 2023).
- In terms of investment, the European HVAC aftermarket sees annual expenditure of around USD 10 Billion in upgrades and maintenance services, with a projected increase of 7% annually through 2034 (European Construction Data, 2023).
- Regional adoption of smart HVAC solutions in Europe is at 40% in 2026, with expectations to surpass 70% by 2034 as IoT integration becomes standard (European Smart Building Report, 2023).
- Market penetration rates indicate that approximately 70% of HVAC units installed before 2015 are due for maintenance or replacement within the next five years, fueling aftermarket demand (European HVAC Industry Stats, 2023).
- Despite economic shifts, the sector has maintained a resilient growth trajectory, supported by stringent regulations and increasing focus on sustainability across European nations, encouraging ongoing investments in aftermarket services (European Environmental Policy Reports, 2023).
Market Segmentation
Europe HVAC Aftermarket Market segmentation primarily revolves around product types, components, and geographical regions. This detailed segmentation provides a nuanced view of the diverse market landscape, highlighting distinct customer needs, technological preferences, and regional demand patterns across Europe. Understanding these segments is crucial for stakeholders to tailor strategies, optimize supply chains, and enhance regional competitiveness within the expanding aftermarket landscape.
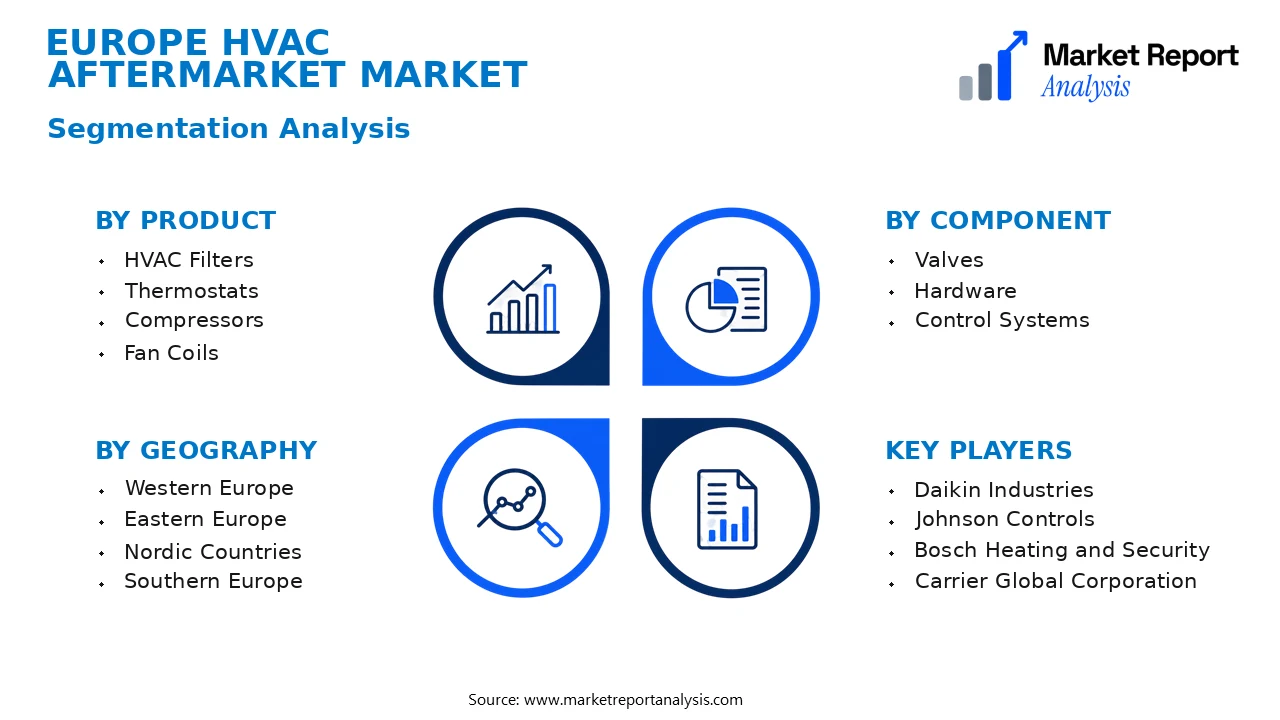
- Product
- HVAC Filters: This subsegment encompasses replacement filters essential for maintaining air quality and system efficiency, making it a significant aftermarket component driven by health standards and energy efficiency regulations.
- Thermostats: Thermostats control HVAC system temperatures, with replacements driven by technological advancements and smart home integrations, gaining popularity for energy conservation and automation trends.
- Compressors: As key components in HVAC systems, compressor replacements are critical for system performance and longevity, especially in older units, with demand swelling due to maintenance needs.
- Fan Coils: Fan coil unit replacements and upgrades form a vital part of the aftermarket, driven by demand for energy-efficient and modern HVAC systems in commercial and residential buildings.
- Component
- Valves: Valves regulate fluid flow in HVAC systems, and aftermarket demand is influenced by new regulatory standards, system upgrades, and preventive maintenance for enhanced system safety and efficiency.
- Hardware: Replacement hardware for HVAC units, including brackets, screws, and mounts, supports system integrity and is in consistent demand across residential and commercial sectors.
- Control Systems: Modern control systems integrate with IoT devices, enabling remote management and energy savings, thus accelerating aftermarket sales driven by technological turnover and system upgrades.
- Geography
- Western Europe: Characterized by mature markets with high penetration of HVAC systems and extensive replacement cycles, driven by stringent regulations and a focus on energy efficiency.
- Eastern Europe: Emerging growth driven by urbanization, infrastructure development, and increasing adoption of modern HVAC systems necessitating aftermarket services and component replacements.
- Nordic Countries: Known for energy-efficient building standards, this region generates demand for advanced HVAC components and maintenance services aligned with sustainability goals.
- Southern Europe: Demand is influenced by climate-specific needs, higher seasonal system demand, and renovations, creating steady opportunities for aftermarket expansions.
Overall, the market segmentation underscores the significant diversity and regional nuances shaping the Europe HVAC Aftermarket. Sector-specific needs, coupled with technological advancements and regulatory dynamics, catalyze continued growth across all identified segments, emphasizing the critical role of strategic segmentation for market players aiming to capitalize on emerging opportunities through targeted offerings, regional presence expansion, and innovation-driven product development.
Competitive Intelligence
The Europe HVAC Aftermarket Market is characterized by a high degree of competition, with key players including multinational corporations such as Daikin, Honeywell, and Johnson Controls dominating the landscape. Market concentration remains significant, with the top five companies holding over 60% of market share, underscoring a consolidated industry structure. Competitive strategies focus on product innovation, emphasizing energy efficiency, smart technology integration, and environmentally sustainable solutions to meet evolving consumer demands and regulatory standards. Strategic partnerships between HVAC manufacturers and technology firms have become prevalent, enhancing product features and expanding market reach. Acquisitions are also a common tactic for growth, enabling companies to strengthen distribution channels and diversify their portfolios; notable examples include mergers between regional players and global giants. Firms are aggressively investing in R&D to develop next-generation, IoT-enabled HVAC components that offer superior performance and predictive maintenance capabilities, thereby differentiating themselves in a competitive environment. Overall, companies leverage innovation, strategic collaborations, and targeted expansion to attain a competitive edge in the dynamic Europe HVAC Aftermarket.
Leading Company Profiles
The competitive landscape of the Europe HVAC aftermarket market is characterized by a mix of established multinational corporations and innovative regional players, all focusing on product innovation, technological advancement, and strategic collaborations to enhance their market share and deliver value to consumers.
- Daikin Industries
- Johnson Controls
- Bosch Heating and Security
- Carrier Global Corporation
- Lennox International
- Mitsubishi Electric
- Honeywell International
- Robert Bosch GmbH
- Emerson Electric Co.
- Stiebel Eltron
Daikin Industries
Daikin specializes in air conditioning and HVAC systems, focusing on energy-efficient solutions and smart technology, with strategic investments aimed at expanding its service portfolio and strengthening its presence through innovative, sustainable products.
Johnson Controls
This company offers comprehensive HVAC solutions, integrating advanced automation and control systems to optimize energy consumption, with ongoing efforts to expand its digital offerings and improve sustainability initiatives across the European continent.
Bosch Heating and Security
Bosch provides a wide range of HVAC components and solutions, emphasizing connected devices and IoT integration, with strategic priorities centered on digital transformation and enhancing user-centric, energy-efficient products.
Carrier Global Corporation
Carrier delivers innovative HVAC systems with a focus on sustainable and eco-friendly technology, including extensive service and aftermarket offerings to maintain its competitive edge within Europe’s growing demand for energy-efficient solutions.
Lennox International
Lennox concentrates on residential and commercial HVAC equipment, offering energy-saving units and smart control systems, while actively investing in product modernization and expanding its service network to boost aftermarket sales.
Mitsubishi Electric
This multinational emphasizes inverter technology and climate control solutions, focusing on energy efficiency and connectivity, with strategic initiatives for increasing service offerings and technological advancements in the HVAC aftermarket sector.
Honeywell International
Honeywell provides intelligent building solutions, including HVAC controls and sensors, prioritizing interoperability, IoT integration, and sustainability, aimed at expanding digital solutions and optimizing energy management across European commercial projects.
Robert Bosch GmbH
Bosch offers comprehensive HVAC systems and components, with a strategic emphasis on digital integration, service excellence, and eco-friendly products to address evolving consumer and regulatory demands in the European market.
Emerson Electric Co.
Focused on automation and control solutions, Emerson supplies HVAC systems and aftermarket services designed for efficiency and reliability, with recent strategic moves to enhance digital offerings and operational capacities.
Stiebel Eltron
Specializing in water heating and heat pumps, Stiebel Eltron emphasizes sustainable, energy-efficient heating solutions with a strategic focus on expanding its product lines and increasing market penetration through innovation and partnerships.
Strategic Business Developments
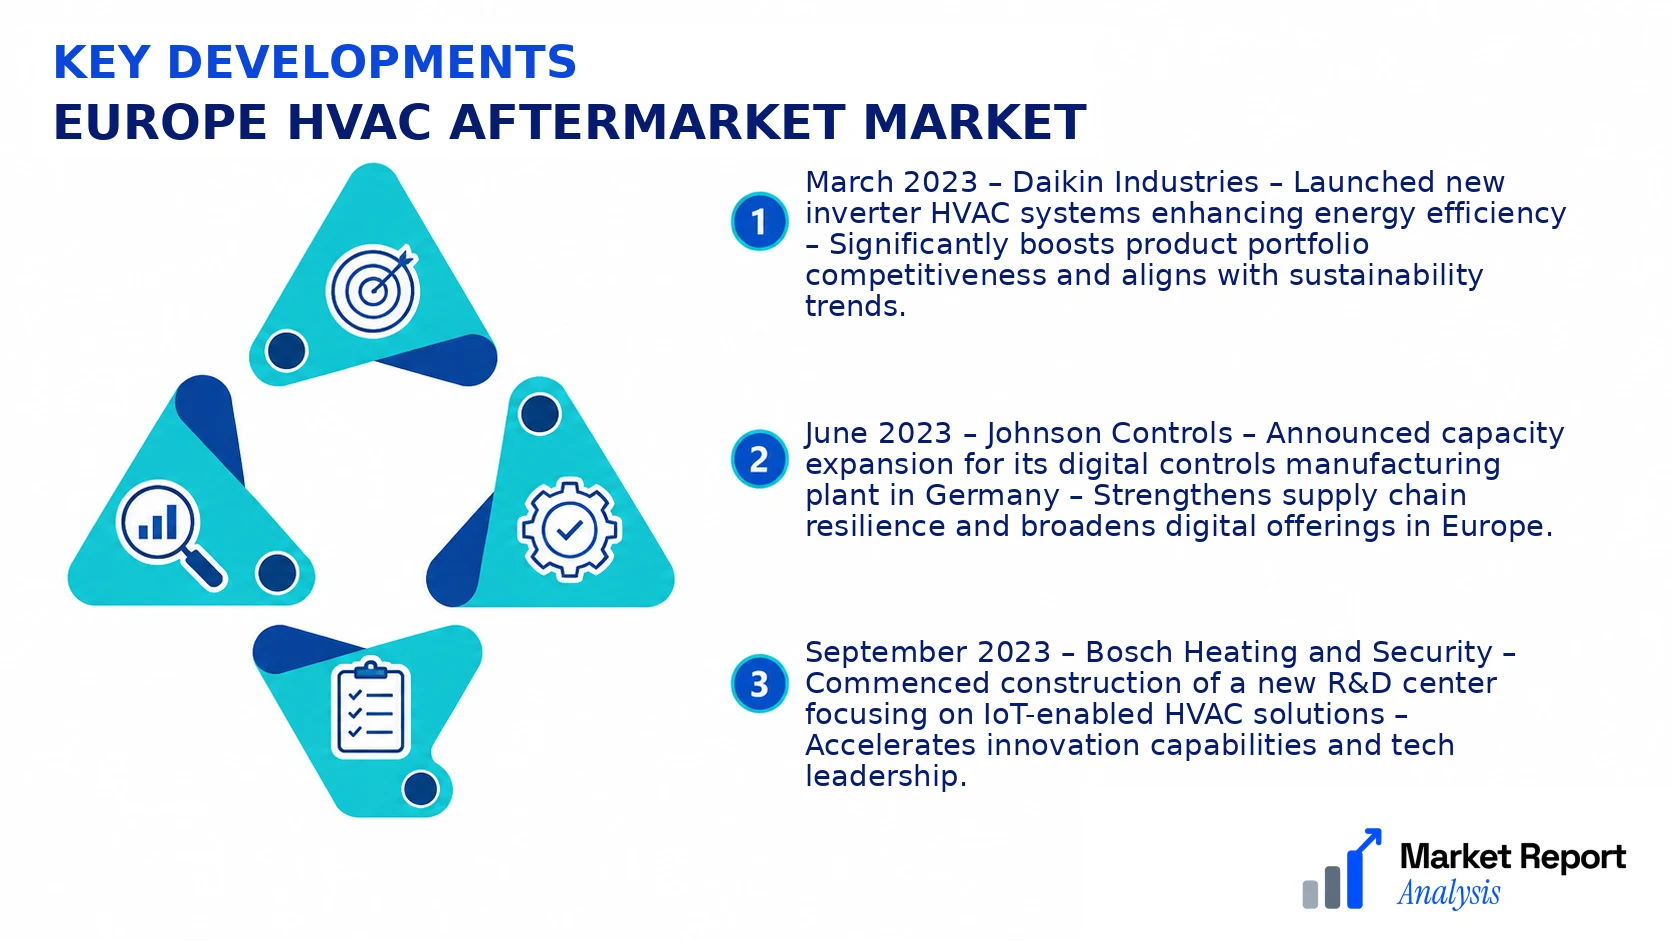
- March 2023 – Daikin Industries – Launched new inverter HVAC systems enhancing energy efficiency – Significantly boosts product portfolio competitiveness and aligns with sustainability trends.
- June 2023 – Johnson Controls – Announced capacity expansion for its digital controls manufacturing plant in Germany – Strengthens supply chain resilience and broadens digital offerings in Europe.
- September 2023 – Bosch Heating and Security – Commenced construction of a new R&D center focusing on IoT-enabled HVAC solutions – Accelerates innovation capabilities and tech leadership.
- January 2024 – Carrier Global Corporation – Acquired a regional HVAC service provider to expand aftermarket service network – Enhances regional presence and customer service capabilities.
- April 2024 – Lennox International – Launched a new line of smart thermostats integrated with IoT platforms – Improves user engagement, efficiency, and product differentiation in the aftermarket segment.
Frequently Asked Questions
What is the Europe HVAC Aftermarket Market?
The Europe HVAC Aftermarket Market encompasses the replacement, maintenance, and upgrade of heating, ventilation, and air conditioning systems across European countries. It includes components, parts, and services catering to residential, commercial, and industrial sectors, reflecting the region's demand for energy-efficient and sustainable HVAC solutions.
What is the current market size of Europe HVAC Aftermarket Market?
As of 2026, the Europe HVAC Aftermarket Market is valued at approximately USD 36.2 Billion, driven by increasing infrastructure development, rising temperatures, and a growing emphasis on energy-efficient systems. Market expansion is fueled by technological innovations and regulatory standards aimed at reducing environmental impact.
What factors are driving the Europe HVAC Aftermarket Market?
Key drivers include rising awareness about energy conservation, stringent environmental regulations, modernization of aging infrastructure, and technological advancements like smart HVAC systems. Additionally, increasing disposable incomes and urbanization are further boosting demand for upgraded HVAC solutions across the region.
Which region dominates the Europe HVAC Aftermarket Market?
Western Europe leads the market, attributed to its mature infrastructure, higher standards for energy efficiency, and advanced technological adoption. Countries such as Germany, France, and the UK are primary contributors to regional growth, continuously investing in sustainable HVAC upgrades.
Which segment is expected to grow the fastest?
The replacement and retrofit segment is projected to experience the fastest growth during 2026-2034, driven by the aging infrastructure and increasing demand for energy-efficient, modern HVAC systems. This segment is crucial for upgrading existing systems to meet current efficiency standards.
Who are the leading companies operating in the Europe HVAC Aftermarket Market?
Major players include Daikin Industries, Honeywell International, Johnson Controls, Bosch Thermotechnology, and LG Electronics. These companies focus on technological innovation, strategic acquisitions, and expanding their regional presence to secure market leadership in Europe’s HVAC aftermarket sector.
Analyst Perspective
The Europe HVAC Aftermarket Market is poised for sustained growth through 2034, driven by increasing urbanization and modernization of infrastructure. As the market matures, technological evolution, particularly smart and energy-efficient systems, will become critical for competitive differentiation. Commercial opportunities lie in retrofit segments, especially for adapting existing systems to meet stringent energy regulations and sustainability goals. Investment priorities should focus on advanced diagnostics, IoT integration, and sustainable refrigerants to capitalize on emerging eco-friendly trends. The competitive landscape is intensifying, with established players expanding their offerings through acquisitions and innovation, while new entrants leverage digital tools to penetrate niche segments. Regionally, Western Europe is expected to lead due to stringent regulations and high disposable income, whereas Eastern Europe offers growth potential driven by modernization efforts. Long-term, strategic positioning will depend on R&D investments in sustainable technologies and proactive adaptation to evolving regulatory frameworks, ensuring resilience amidst market consolidation and technological shifts.
