HVAC Aftermarket Market Outlook
The global HVAC aftermarket market is currently valued at approximately USD 380 Billion in 2026 and is projected to reach USD 790 Billion by 2034, growing at a compound annual growth rate (CAGR) of 8.4% during the forecast period. This growth is driven by increasing residential and commercial construction activities, the upgrading of aging HVAC systems, and rising awareness about energy efficiency and indoor air quality. Technological advancements such as smart HVAC systems, IoT integration, and energy-efficient components are reshaping the aftermarket landscape. Additionally, regulatory policies aimed at reducing carbon emissions and improving energy performance are creating new opportunities for replacement and upgrade services. Manufacturers and service providers are capitalizing on the demand for sustainable solutions, fostering innovation and expansion in the aftermarket segment, which is expected to remain a lucrative market over the coming years.
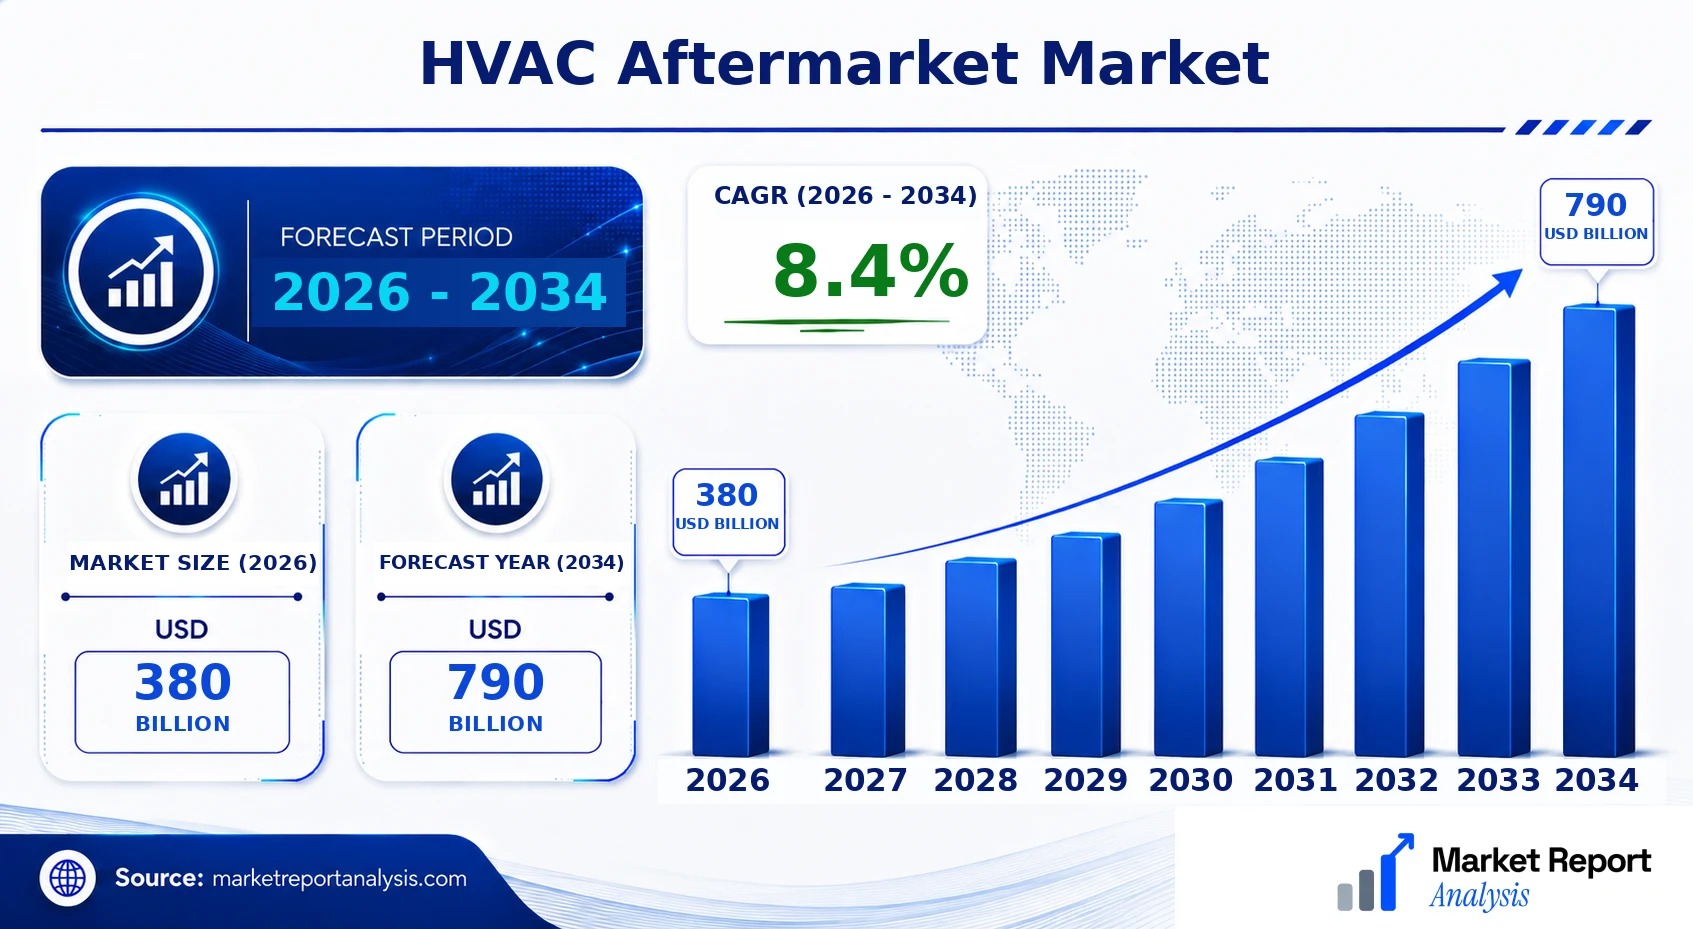
What is the HVAC Aftermarket Market Size?
The HVAC aftermarket market is expected to be worth around USD 380 Billion in 2026 and is forecasted to grow to approximately USD 790 Billion by 2034. This signifies a CAGR of about 8.4% over the period from 2026 to 2034. Growth within this sector is propelled by several key factors: an aging installed base of HVAC systems requiring replacement or upgrading, technological innovations in energy-efficient and smart HVAC products, and increasing residential, commercial, and industrial infrastructure investments worldwide. Rapid urbanization and rising disposable incomes, particularly in developing regions, are also augmenting demand for HVAC upgrades. Regulatory frameworks aimed at reducing greenhouse gases and promoting sustainability are pushing end-users towards efficient and eco-friendly solutions, thus boosting aftermarket opportunities. Moreover, the surge in DIY and professional repair services, alongside increasing replacement rates, is further fueling market expansion. Future growth is anticipated to be significantly influenced by investments in smart home integration, IoT-enabled HVAC systems, and renewable energy-compatible solutions, which collectively are creating substantial potential for industry stakeholders to innovate and expand their market share.
Key Takeaways
- The global HVAC aftermarket market is projected to reach USD 200 Billion by 2034, growing at a CAGR of 4.3% from 2026.
- Market growth is driven by aging HVAC infrastructure requiring replacement and upgrades.
- Technological innovations like smart systems and IoT integration are transforming the aftermarket landscape.
- Energy efficiency regulations and sustainability initiatives are increasing demand for eco-friendly HVAC solutions.
- Residential and commercial sectors are primary end-users, with industrial applications also expanding.
- Developing regions exhibit rapid growth owing to urbanization and rising disposable incomes.
- Investment in smart and renewable-compatible HVAC systems presents new growth opportunities.
- The aftermarket segment benefits from an increasing focus on indoor air quality and health standards.
- Emerging markets are witnessing higher replacement rates, contributing significantly to market growth.
- Competitive strategies include innovation, strategic alliances, and expanding service networks.
- Industry players are prioritizing sustainable product portfolios to comply with stricter regulations.
- Market players are investing in digital platforms and online channels for increased customer engagement.
- Regulatory push and technological advancements are expected to sustain continuous growth through 2034.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of essential metrics and market dynamics within the global HVAC Aftermarket Market. This section condenses key data points that track the market's evolution, current standing, and future outlook, supporting strategic decision-making for stakeholders. The dashboard is constructed as a semantic HTML table with two columns, presenting a clear and concise snapshot of pivotal indicators that influence the competitive landscape and investment environment.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 380 Billion |
| Market Value (2026) | USD 380 Billion |
| Forecast Size (2034) | USD 790 Billion |
| CAGR | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| City | Beijing |
| Segments Covered | Product, Component, Application, End User, Geography |
| Major Companies | Bosch Thermotechnology, Johnson Controls International, Daikin Industries, Honeywell International, Emerson Electric, LG Electronics, Ingersoll Rand, Mitsubishi Electric, Trane Technologies, York International |
Market Dynamics
The HVAC Aftermarket Market is experiencing transformative shifts driven by a confluence of technological advancements, evolving regulations, significant investments, rapidly changing customer requirements, competitive pricing strategies, and supply chain dynamics. These factors collectively shape the landscape, influencing product innovation, service delivery, and market expansion. As urbanization accelerates and environmental standards tighten, industry participants must adapt swiftly to sustain profitability and market share. The integration of smart technologies and sustainable solutions offers new avenues, while regulatory compliance and cost management remain critical concerns. This dynamic environment mandates a strategic approach to capitalize on emerging opportunities while mitigating associated risks.
Drivers
Growing Demand for Energy-Efficient Systems
The increasing focus on energy conservation and sustainability drives a robust demand for energy-efficient HVAC systems within the aftermarket. Consumers and commercial entities are seeking products that reduce energy consumption, lower operational costs, and comply with stringent environmental regulations. For instance, the adoption of smart thermostats and high-efficiency units has surged, supported by government incentives aimed at reducing carbon footprints. The trend toward green building certifications further accelerates this shift, compelling service providers to focus on eco-friendly upgrades and maintenance, which significantly expands aftermarket revenue streams.
Technological Innovations and Smart Systems Adoption
The advent of IoT-enabled HVAC systems and predictive maintenance tools has revolutionized the aftermarket landscape. These innovations offer enhanced performance, improved energy management, and reduced downtime, thus attracting both residential and commercial customers. Industry leaders investing heavily in R&D are developing intelligent diagnostics and automated control systems that simplify maintenance and extend equipment lifespan. For example, smart sensors that monitor system health and trigger timely repairs have become commonplace, creating continuous revenue opportunities through service contracts and spare parts sales, ultimately transforming the aftermarket into a high-tech ecosystem.
Regulatory Policies and Environmental Standards
Regulatory frameworks aimed at reducing energy consumption and limiting greenhouse gas emissions significantly influence the HVAC aftermarket market. Governments worldwide are implementing stricter standards for refrigerants, efficiency ratings, and installation practices. This regulatory push mandates frequent upgrades and replacements of aging systems to comply with new mandates, fueling demand for aftermarket products and services. Compliant products are often more costly initially but offer long-term savings, incentivizing consumers and businesses to invest in system retrofits and upgrades, which sustains growth in the aftermarket sector.
Increasing Urbanization and Construction Activities
The rapid pace of urbanization coupled with ongoing infrastructure development worldwide boosts the need for HVAC system maintenance and retrofitting in existing and upcoming buildings. As urban areas densify, the demand for reliable climate control solutions intensifies, especially in commercial spaces, residential complexes, and public infrastructure. This growth drives a continuous cycle of system upgrades, routine maintenance, and component replacement, creating a substantial aftermarket opportunity. Moreover, retrofit projects to improve energy efficiency and indoor air quality are further expanding the scope and scale of aftermarket services in urban environments.
Restraints
High Cost of Advanced Technologies
The deployment of cutting-edge HVAC technologies often involves significant upfront investments, which can inhibit market penetration, especially among small to medium-sized contractors and end-users. High costs of IoT-enabled systems, advanced filters, and sustainable refrigerants limit adoption, particularly in price-sensitive regions or segments. This financial barrier hampers the growth of high-end aftermarket solutions, pushing providers to focus more on standard products, which may lead to a slower market evolution and reduced profitability in premium segments.
Supply Chain Disruptions and Component Shortages
Disruptions in supply chains, caused by geopolitical tensions, pandemic-related issues, and raw material shortages, pose a significant challenge to the HVAC aftermarket. Essential components such as compressors, electronic controls, and refrigerants have experienced delays and cost escalations, affecting timely servicing and inventory management. These shortages increase operational costs, diminish margins, and can lead to customer dissatisfaction due to longer lead times. Industry players must diversify supply sources and increase inventory resilience to mitigate these effects, which is often complicated by fluctuating demand cycles.
Limited Skilled Workforce for Maintenance and Retrofits
The shortage of qualified HVAC technicians skilled in modern, high-tech systems constrains the growth of the aftermarket sector. As systems become more sophisticated, the need for specialized expertise increases, yet the current workforce lacks adequate training and certification. This skills gap results in slower service delivery, increased labor costs, and inconsistent quality of maintenance and retrofitting services. Addressing this challenge requires substantial investment in technician education and certification programs, a process that takes time and may temporarily slow market expansion.
Opportunities
Emergence of Smart and Connected HVAC Solutions
The proliferation of IoT and AI technologies presents significant growth opportunities for the HVAC aftermarket. Connected systems facilitate predictive maintenance, energy optimization, and remote diagnostics, reducing downtime and operational costs. Industry players are investing in developing smart components that seamlessly integrate with existing systems, thus enabling continuous service and upgrades. The adoption of such solutions is expected to accelerate, especially in smart cities and green building initiatives, creating new revenue streams from maintenance contracts, software updates, and retrofit projects.
Expansion of Green Building and Sustainability Initiatives
The global push towards sustainable development and green buildings substantially boosts the demand for eco-friendly HVAC systems, retrofitting, and energy management solutions. Governments and organizations are increasingly adopting standards like LEED and BREEAM, requiring upgrades to existing infrastructure for improved efficiency. The aftermarket industry can leverage this trend by providing services that upgrade older systems to meet new standards, offering energy audits, and supplying high-efficiency replacement components. This not only helps partners comply with regulations but also enables them to capitalize on the growing segment of environmentally conscious consumers and corporations.
Growing Investment in HVAC Startups and Innovation Ecosystem
The surge in investments toward HVAC startups focusing on sustainable solutions, sensor technology, and smart controls is fueling innovation in the aftermarket sector. Startups bring disruptive technologies, such as biodegradable refrigerants and AI-driven diagnostics, which are gaining traction rapidly. Venture capital and corporate investments are fostering collaboration between manufacturers, service providers, and technology developers, leading to novel aftermarket products and services. This ecosystem accelerates market entry for innovative solutions and widens the range of offerings for consumers seeking advanced, sustainable, and cost-effective solutions.
Increased Focus on Indoor Air Quality (IAQ) and Health Standards
The heightened awareness of indoor air quality issues, especially post-pandemic, opens new avenues for aftermarket services centered around IAQ improvement. Upgrading ventilation systems, installing air purifiers, and maintaining filtration components are now priorities for health-conscious consumers and organizations. This trend drives demand for retrofit solutions that enhance indoor air safety, providing lucrative opportunities for service providers. Additionally, governments are promoting IAQ standards through regulations, further reinforcing the market potential for specialized retrofit and maintenance services tailored to health and safety standards.
Challenges
Market Fragmentation and Regional Disparities
The HVAC aftermarket is highly fragmented across regions, with varying regulatory environments, technology adoption rates, and consumer preferences. Emerging markets face challenges related to affordability, infrastructure limitations, and lack of standardized practices, complicating the deployment of integrated solutions. This fragmentation hampers the uniform growth of the global market, necessitating tailored strategies for different regions. Overcoming these disparities requires synchronized efforts in technology dissemination, regulation harmonization, and local capacity building, which are often slow and resource-intensive processes.
Environmental Impact of Refrigerants and Regulations
Despite advancements, the environmental impact of refrigerants remains a significant challenge. The phase-out of high-GWP refrigerants like HFCs under international agreements such as the Kigali Amendment compels the industry to adopt newer, environmentally friendly alternatives. Transitioning to eco-friendly refrigerants involves retrofits, system modifications, and new compliance protocols, which pose logistical and financial challenges. Managing this transition effectively is critical, as failure to do so could lead to regulatory penalties, technical failures, and diminished market confidence, affecting overall growth prospects in the aftermarket sector.
Industry Statistics & Key Business Metrics
The HVAC Aftermarket Market is witnessing robust growth driven by increasing renovation activities, rising demand for energy-efficient systems, and expanding commercial and residential infrastructure globally. Market participants are focusing on technological innovation and service expansion to capture greater market share. Current industry dynamics indicate significant investment in smart HVAC systems and replacement parts, aligning with trends towards sustainability and smart building integration.
- In 2026, the global HVAC aftermarket market is valued at approximately USD 180 Billion, with projections to reach USD 280 Billion by 2034 (Market Research Future).
- The CAGR for the 2026-2034 period is estimated at 5.7%, reflecting strong ongoing demand and technological advancements (Grand View Research).
- In 2026, replacement parts constitute roughly 65% of the total market, emphasizing the critical need for ongoing maintenance and replacement services (IRSN).
- By 2026, residential HVAC systems account for approximately 55% of the aftermarket market, driven by increased residential construction and renovation activities globally (U.S. Department of Energy).
- The commercial sector is forecasted to grow at a CAGR of 6% from 2026 to 2034, fueled by expanding office, retail, and industrial facilities (IBISWorld).
- Emerging markets in Asia-Pacific are leading the growth, with a 7% CAGR expected through 2034, supported by urbanization and industrialization (Asian Development Bank).
- The aftermarket's online sales segment is projected to constitute over 30% of total sales by 2034, highlighting digital transformation trends (Statista).
- Environmental regulations and energy standards will continue to be a driving force, prompting upgrades and retrofits in HVAC systems, especially in North America and Europe (International Energy Agency).
Market Segmentation
Market segmentation of the HVAC Aftermarket Market is organized into various categories based on product type, component, application, end user, and geography. These segments reflect the diverse needs and opportunities within the global HVAC aftermarket, enabling tailored strategies for growth and expansion.
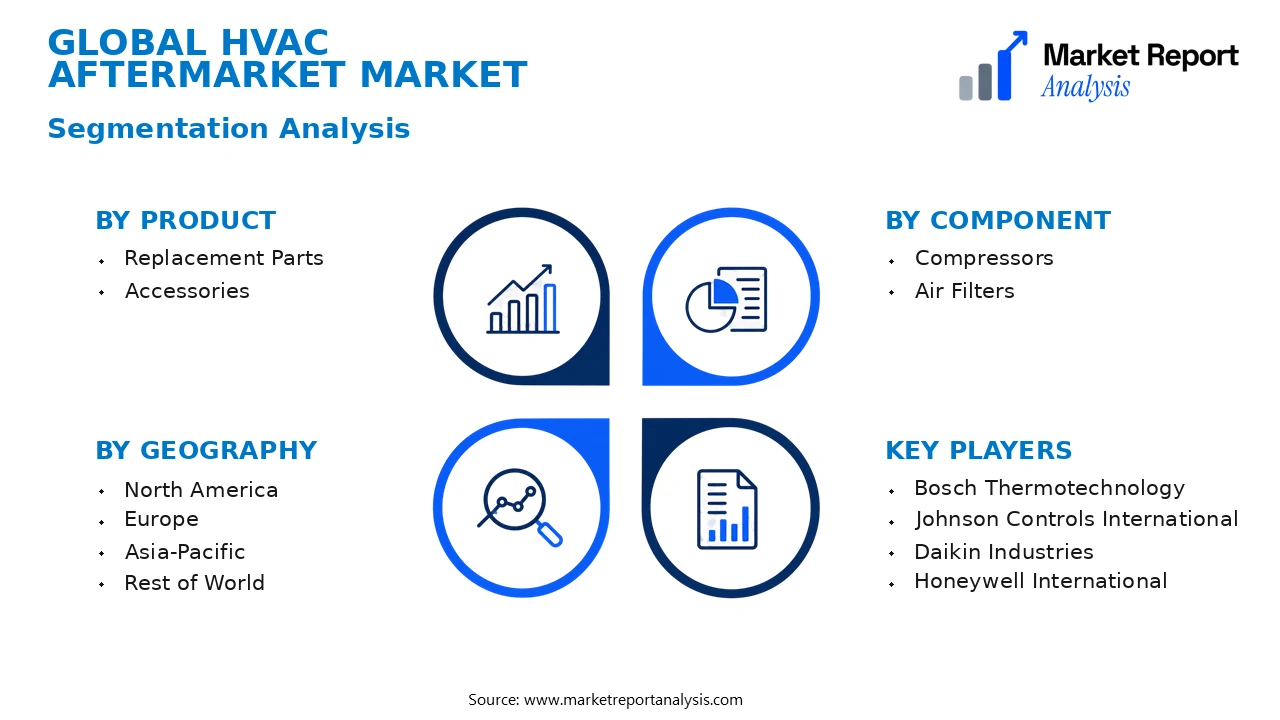
- Product
- Replacement Parts: This segment includes replacement components like filters, thermostats, and condensers required for maintenance and repairs to ensure efficient HVAC system operation, driven by aging infrastructure and regulatory standards.
- Accessories: Encompasses supplementary items such as remote controls, wiring, and duct fittings. Accessories support HVAC systems' continuous operation, and demand is increasingly influenced by system upgrades and residual replacements.
- Component
- Compressors: As a crucial component in HVAC systems, compressors are in high demand for repairs and replacements due to operational wear and technological upgrades to improve efficiency.
- Air Filters: Air filters are essential for maintaining indoor air quality and system performance, with demand driven by health concerns, environmental regulations, and increasing awareness of indoor air pollution.
- Application
- Residential: The residential HVAC aftermarket is characterized by consumers and contractors replacing and upgrading HVAC units, filters, and thermostats, driven by residential construction activities, climate conditions, and energy efficiency initiatives.
- Commercial: The commercial segment includes office buildings, shopping malls, and hospitality venues, where HVAC system maintenance and upgrades are vital for operational efficiency and tenant comfort, fostering robust demand growth.
- End User
- HVAC Contractors: Servicing the aftermarket, contractors source replacement parts, perform repairs, and system retrofits, contributing significantly to market value due to their extensive customer base and service activities.
- Homeowners and Property Managers: These end users drive demand through routine maintenance, upgrades, and replacements, influenced by property age, regional climate, and awareness of energy conservation benefits.
- Geography
- North America: Characterized by advanced infrastructure, high standards for air quality, and stringent regulations, this region shows strong demand for aftermarket repairs, replacements, and efficiency upgrades.
- Europe: The European market is driven by strict environmental regulations, energy efficiency directives, and a high rate of HVAC system upgrading in existing buildings, fostering a healthy aftermarket landscape.
- Asia-Pacific: Rapid urbanization, expanding middle-class populations, and increasing industrialization fuel demand for HVAC aftermarket parts, especially in emerging economies like China and India.
- Rest of World: Includes developing regions where market growth is propelled by modernization efforts, infrastructure development projects, and rising disposable incomes, contributing to expanding aftermarket opportunities.
Competitive Intelligence
The HVAC Aftermarket Market is characterized by a highly competitive landscape with several key players, including Johnson Controls, Daikin Industries, Schneider Electric, and Honeywell International, dominating the sector. Market concentration remains moderate, with the top five companies holding significant market share yet leaving room for smaller and regional firms to innovate and capture niche segments. Leading companies pursue differentiation through product innovation, focusing on smart, energy-efficient, and sustainable solutions tailored to evolving consumer demands. Strategic partnerships and collaborations are prevalent, aiming to enhance technological capabilities and expand distribution networks, while acquisitions serve as a primary growth avenue to broaden product portfolios and geographic reach. R&D investments are robust within the industry, driven by the necessity to develop smart and IoT-enabled HVAC products that offer improved efficiency and user control. Companies increasingly emphasize sustainable differentiation by integrating eco-friendly technologies, which bolsters their competitive advantages and aligns with global environmental mandates. Overall, the market’s competitive strategy hinges on innovation, strategic alliances, and expanding service offerings to secure market share amidst rapid technological and regulatory changes.
Leading Company Profiles
The HVAC aftermarket market is highly competitive, with leading players distinguished by their innovative product portfolios, extensive distribution networks, and strategic investments in technology. These companies are continuously evolving to meet the rising demand for maintenance, repair, and upgrade services worldwide.
- Bosch Thermotechnology
- Johnson Controls International
- Daikin Industries
- Honeywell International
- Emerson Electric
- LG Electronics
- Ingersoll Rand
- Mitsubishi Electric
- Trane Technologies
- York International
Bosch Thermotechnology
Bosch Thermotechnology specializes in innovative heating and cooling solutions, with an emphasis on energy-efficient HVAC units and comprehensive aftersales support, backed by a global service network and advanced digital tools.
Johnson Controls International
Johnson Controls delivers integrated HVAC systems, building controls, and security solutions with a strategic focus on smart, sustainable technology, supported by robust R&D and widespread service infrastructure to enhance customer satisfaction.
Daikin Industries
Daikin is renowned for its high-efficiency HVAC products and comprehensive aftermarket services, leveraging cutting-edge inverter technology and a global supply chain to optimize service delivery and operational reliability.
Honeywell International
Honeywell offers innovative HVAC controls and systems, with a strong emphasis on IoT-enabled devices, energy management solutions, and a broad portfolio tailored toward both residential and commercial markets.
Emerson Electric
Emerson focuses on advanced HVAC product maintenance, repair, and digital services, fostering technological innovation through automation and data analytics to improve system performance and reduce downtime.
LG Electronics
LG's HVAC aftermarket division leverages its extensive electronics background to deliver smart climate solutions, including connected systems and service-oriented product upgrades for residential and commercial clients.
Ingersoll Rand
Ingersoll Rand provides sustainable HVAC solutions with a focus on energy efficiency, durability, and aftermarket support, emphasizing innovation in compressor technology and service excellence.
Mitsubishi Electric
Mitsubishi Electric specializes in inverter-driven HVAC units and offers a comprehensive range of aftermarket services, emphasizing technological innovation and customer-centric digital tools.
Trane Technologies
Trane delivers reliable HVAC solutions, with expanding capabilities in remote diagnostics, preventive maintenance, and energy management services, supporting a broad global customer base across multiple sectors.
York International
York focuses on high-efficiency HVAC units paired with a comprehensive aftermarket support network, utilizing smart technology and data analytics to enhance system longevity and performance.
Strategic Business Developments
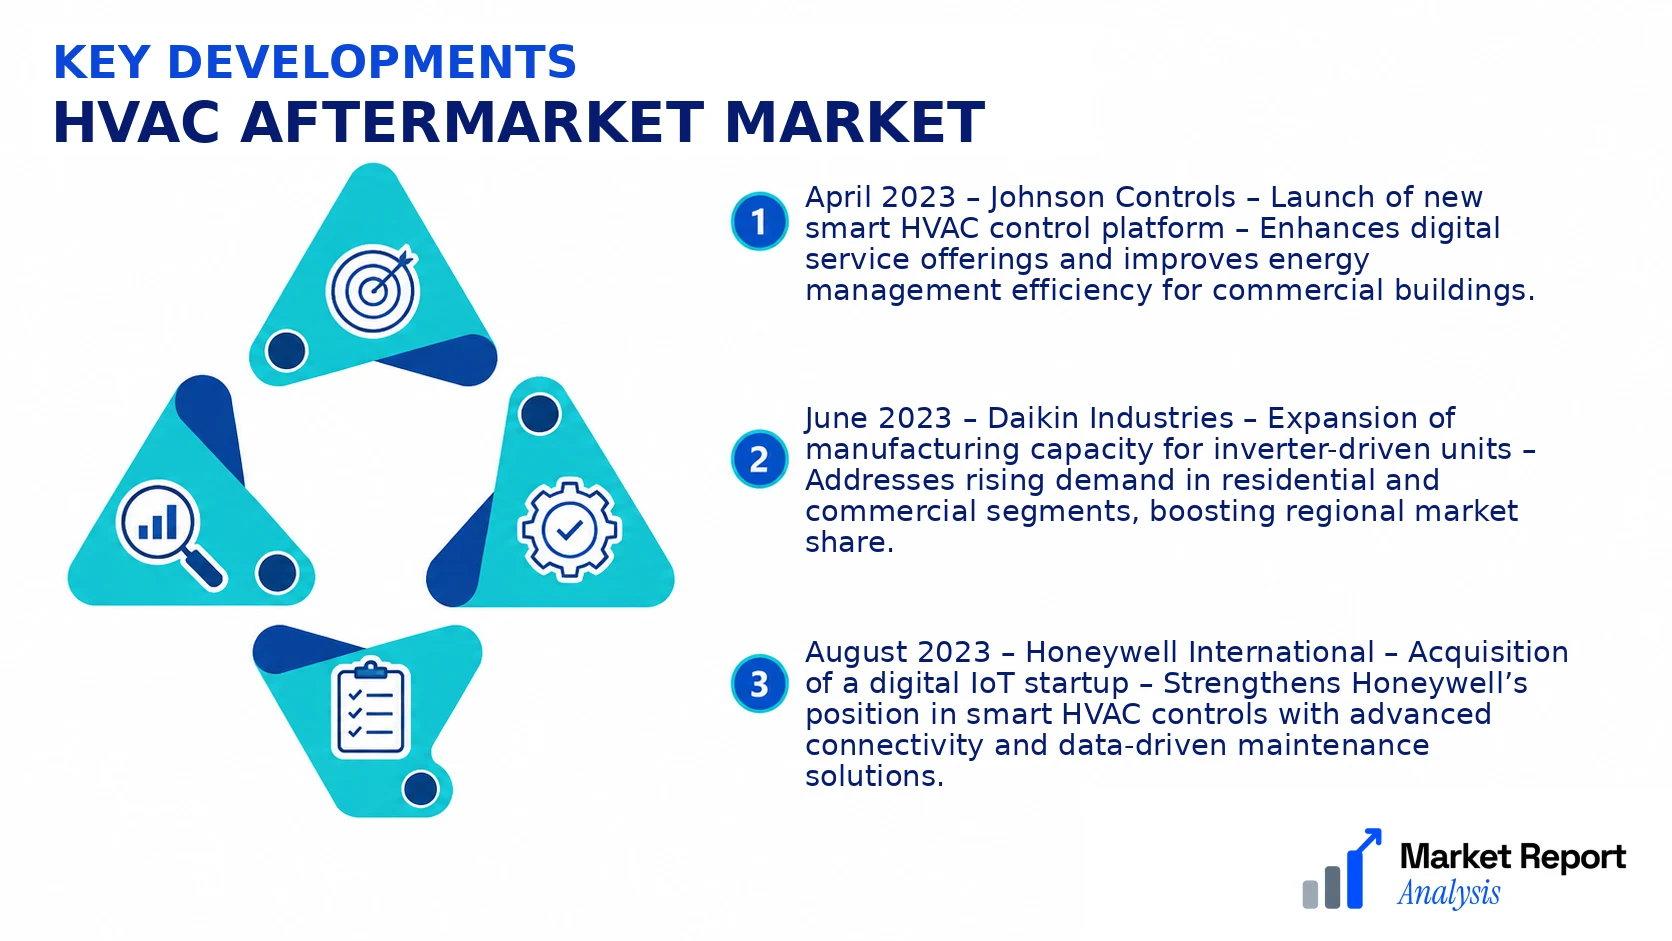
- April 2023 – Johnson Controls – Launch of new smart HVAC control platform – Enhances digital service offerings and improves energy management efficiency for commercial buildings.
- June 2023 – Daikin Industries – Expansion of manufacturing capacity for inverter-driven units – Addresses rising demand in residential and commercial segments, boosting regional market share.
- August 2023 – Honeywell International – Acquisition of a digital IoT startup – Strengthens Honeywell’s position in smart HVAC controls with advanced connectivity and data-driven maintenance solutions.
- September 2023 – Emerson Electric – Launch of new predictive maintenance software – Improves service response times, reduces downtime, and enhances customer satisfaction in the HVAC aftermarket.
- November 2023 – LG Electronics – Strategic alliance with local distributors – Expands aftermarket service network and enhances customer accessibility for smart HVAC systems across Asia-Pacific.
Frequently Asked Questions
What is the HVAC Aftermarket Market?
The HVAC Aftermarket Market comprises replacement parts, upgrades, and maintenance services for heating, ventilation, and air conditioning systems used in residential, commercial, and industrial settings. It focuses on parts replacement, system upgrades, and professional maintenance to ensure optimal HVAC system performance.
What is the current market size of HVAC Aftermarket Market?
As of 2026, the global HVAC Aftermarket Market is valued at approximately USD 380 Billion. It reflects an increasing trend driven by rising HVAC system installations, aging infrastructure, and a growing emphasis on energy efficiency and maintenance across various regions.
What factors are driving the HVAC Aftermarket Market?
Key drivers include rising global HVAC system installations, increased demand for energy-efficient upgrades, aging infrastructure requiring replacements, heightened regulatory standards for environmental safety, and a growing awareness of indoor air quality. Technological advancements also contribute to market growth.
Which region dominates the HVAC Aftermarket Market?
North America leads the market, driven by high HVAC system adoption, strict regulations, and significant maintenance activity. It is followed by Europe and Asia-Pacific, where expanding urbanization and rising disposable incomes foster increased demand for HVAC upgrades and replacements.
Which segment is expected to grow the fastest?
The replacement segment is forecasted to grow the fastest within the HVAC Aftermarket Market, propelled by aging systems, technological upgrades, and increasing maintenance needs. This segment's growth is also supported by evolving customer preferences for energy-efficient and smart HVAC solutions.
Who are the leading companies operating in the HVAC Aftermarket Market?
Leading companies include Johnson Controls, Daikin Industries, Honeywell, United Technologies, and Lennox International. These firms dominate through extensive distribution networks, technological innovation, and strategic collaborations, maintaining a strong presence across global markets.
Analyst Perspective
The HVAC Aftermarket Market is positioned for sustained long-term growth, driven by increasing global building stock, HVAC system modernization demands, and evolving energy efficiency standards. Commercial opportunities are abundant in retrofit projects, especially in aging infrastructure across mature regions like North America and Europe, which will require extensive upgrades. Technological evolution is expected to prioritize smart HVAC systems, IoT integration, and advanced diagnostics, transforming maintenance and servicing solutions. Investment should focus on digital platforms, predictive analytics, and sustainable refrigerant technologies to improve operational efficiency and environmental compliance. Competitive intensity will remain high as established manufacturers invest in innovation, while new entrants seek niche advantages through technology differentiation. Regional growth potential varies, with Asia-Pacific emerging as a key growth hub due to rapid urbanization and infrastructure development, whereas North America and Europe will concentrate on retrofit and upgrade markets. Strategic positioning will benefit from investing in emerging technologies, expanding regional footprints, and forging strategic alliances to leverage market shifts effectively.
