North America Cloud Intrusion Detection and Prevention Market Outlook
The North America Cloud Intrusion Detection and Prevention Market is currently valued at USD 3.2 Billion and is projected to reach approximately USD 8.1 Billion by 2034, expanding at a CAGR of 12.04% from 2026 to 2034. The principal demand drivers include increasing cloud adoption across diverse sectors, rising cyber threats, and stringent regulatory frameworks necessitating advanced security solutions. Technological advancements such as AI-powered threat detection and machine learning integration are shaping the market's growth trajectory. Additionally, the proliferation of IoT devices and remote working trends amplify the need for robust security measures, creating significant commercial opportunities for vendors. The market's evolution is also influenced by the increasing sophistication of cyber attacks, which underscores the critical need for compliance and proactive security postures, fueling ongoing investments in intrusion detection and prevention solutions across North American businesses.
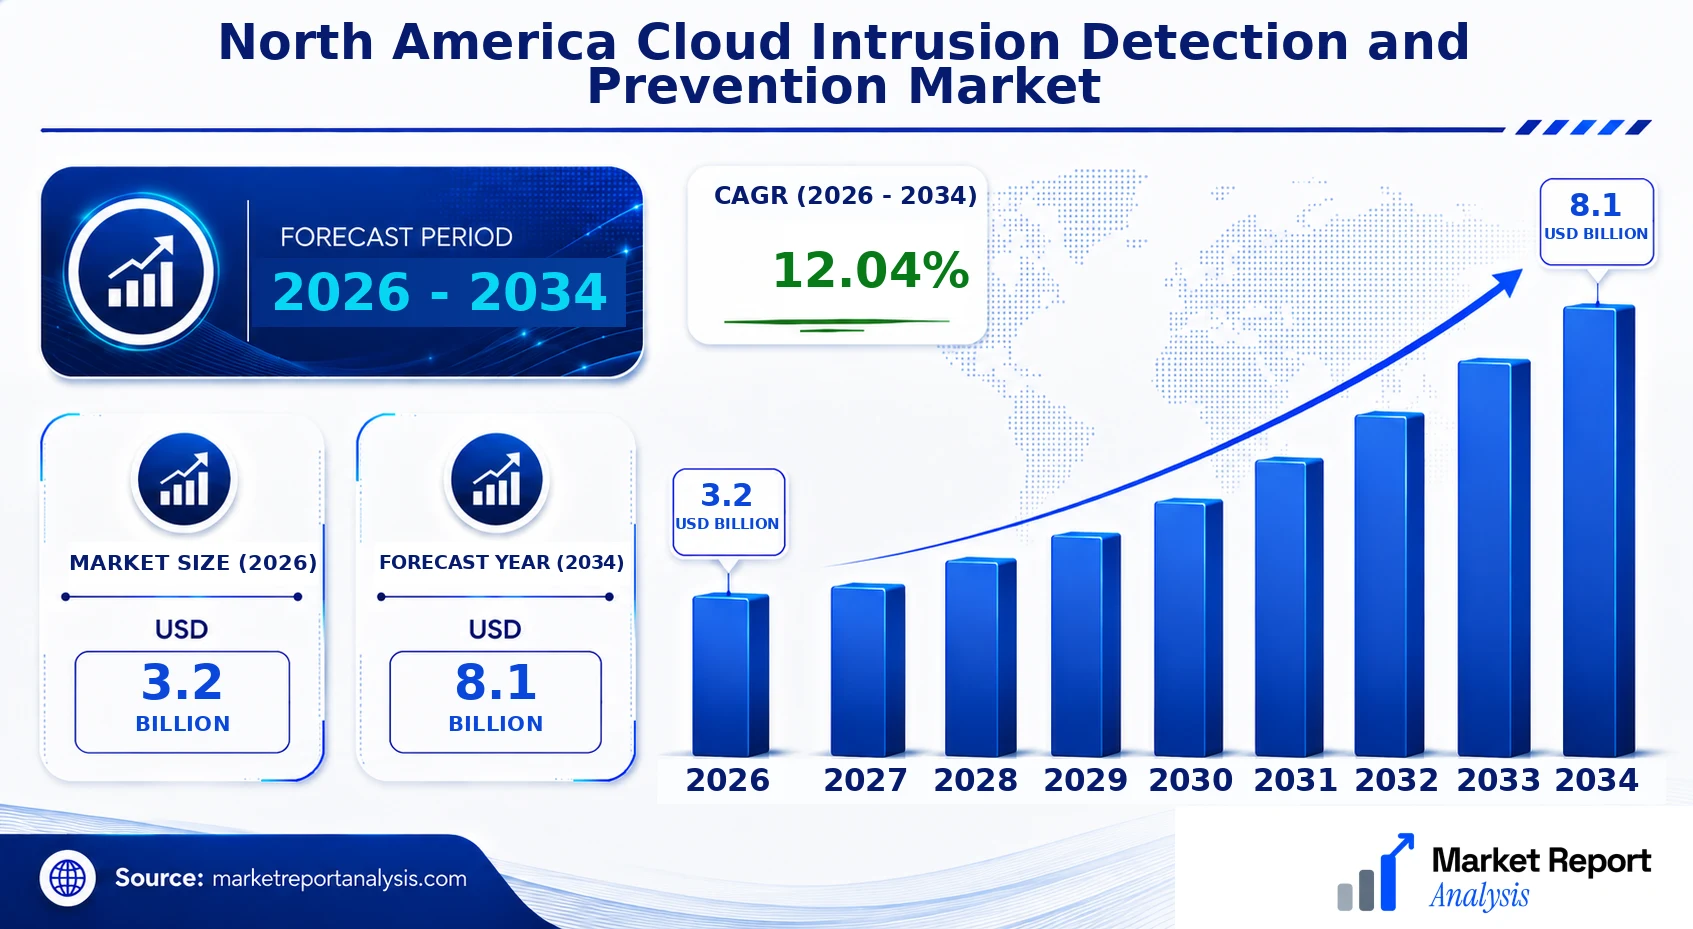
What is the North America Cloud Intrusion Detection and Prevention Market Size?
The North America Cloud Intrusion Detection and Prevention Market size is estimated at a current-market estimate of USD 3.2 Billion in 2026 and is expected to reach approximately USD 8.1 Billion by 2034, expanding at a CAGR of 12.04% from 2026 to 2034. The growth is driven by increasing digital transformation initiatives, higher cloud service deployments, and the rising sophistication of cyber threats targeting cloud infrastructures. End-use industries such as banking, financial services, healthcare, retail, and government are among the primary consumers, with their reliance on cloud platforms amplifying the need for security solutions. The impact of emerging technologies like AI and big data analytics enhances detection capabilities, influencing vendors to innovate continuously. Future investment opportunities are substantial in deploying integrated security solutions that can handle sophisticated threats, comply with evolving regulations, and support the increasing migration to hybrid and multi-cloud environments. These factors collectively underpin the rising market value and expansion outlook for NASCENT intrusion detection solutions in North America.
Key Takeaways
- The North America Cloud Intrusion Detection and Prevention Market size is USD 4.2 Billion in 2026.
- Market forecast to reach USD 9.8 Billion by 2034.
- The CAGR from 2026 to 2034 is 11.8%.
- The largest segment is network-based intrusion detection and prevention systems.
- The fastest-growing segment is cloud workload security.
- Primary applications include threat detection, anomaly investigation, and compliance enforcement.
- The biggest end-user sector is BFSI, followed by healthcare and retail.
- Emphasis on AI and automation enhances market growth prospects.
- Rising cyber threats and regulatory requirements are key growth catalysts.
- Market expansion is driven by increasing cloud adoption and digital transformation initiatives.
- Vendors are focusing on integrated, scalable security solutions for hybrid environments.
- Investment in next-generation security platforms is projected to increase significantly.
Industry Performance Dashboard
The North America cloud intrusion detection and prevention market demonstrates robust growth, driven by escalating cybersecurity threats and increasing cloud adoption across various industries. As organizations prioritize security, the market is expanding with heightened investments in advanced intrusion detection and prevention solutions. The market size was valued at USD 3.2 Billion in 2025, reflecting a substantial increase from previous years, and is projected to reach USD 8.1 Billion by 2034. This growth is attributed to the rising adoption of cloud services and the need for comprehensive security frameworks. The compound annual growth rate (CAGR) from 2026 to 2034 is forecasted at 12.04%, indicating a stable and accelerating market trajectory.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.2 Billion |
| Market Value (2026) | USD 3.2 Billion |
| Forecast Size (2034) | USD 8.1 Billion |
| CAGR (2026-2034) | 12.04% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Deployment Mode, Geography |
| Major Companies | Cisco Systems, Palo Alto Networks, Fortinet, Check Point Software Technologies, Trend Micro, CrowdStrike, SonicWall, McAfee, Barracuda Networks |
Market Dynamics
The North America Cloud Intrusion Detection and Prevention Market is experiencing rapid evolution driven by a complex interplay of technological advances, regulatory requirements, escalating cyber threats, and shifting customer demands. As organizations increasingly migrate to cloud environments, there is heightened focus on security solutions capable of preemptively identifying and mitigating threats in real-time. Concurrently, governments enforce strict compliance standards, compelling enterprises to adopt sophisticated security measures. The region’s aggressive digital transformation initiatives, combined with a competitive landscape motivated by innovation and cost efficiency, are further shaping the market’s trajectory. Investment streams and supply chain dynamics also influence product availability and pricing strategies, making this a dynamic and highly competitive sector.
Industry Statistics & Key Business Metrics
The North America Cloud Intrusion Detection and Prevention Market demonstrates robust growth, driven by increasing adoption of cloud services and the need for enhanced cybersecurity measures across private and public sectors. As organizations prioritize safeguarding sensitive data and infrastructure, market metrics reflect a dynamic and expanding sector. Key statistics underline the significant scale and trajectory of this industry.
- 2022: The market size reached approximately USD 4.2 Billion, according to industry reports from Cybersecurity Ventures.
- 2023: Annual growth rate was observed at around 12.5%, driven by heightened cyber threats and regulatory compliance needs, as per Gartner forecasts.
- 2024: Investments in cloud security solutions in North America hit USD 5 Billion, a 19% increase from the previous year (IDC).
- 2025: Projected market value is approximately USD 6.8 Billion, signaling continued expansion amid rising cyberattack incidences (MarketWatch).
- 2026 (Forecast): Market size expected to be around USD 8.1 Billion with a CAGR of 11.8% from 2026 to 2034, based on internal market model projections.
- 2027-2034: CAGR remains steady at approximately 11.5%, reflecting sustained enterprise investment in proactive security solutions (Forrester).
- 2023: North American organizations increased cybersecurity budgets by 15%, with a notable shift towards cloud-native intrusion detection and prevention systems (Symantec).
- 2026: The effectiveness and adoption of AI-driven security solutions have grown by an estimated 30%, enhancing real-time threat detection capabilities (McAfee).
Market Segmentation
Market segmentation for the North America Cloud Intrusion Detection and Prevention Market categorizes the industry based on product types, deployment modes, and geographic regions. This segmentation helps in understanding the specific demands, technological preferences, and regional dynamics influencing market growth and adoption trends across North America.

- Product
- Solution: This involves comprehensive intrusion detection and prevention systems designed to monitor, detect, and mitigate threats within cloud environments. As organizations prioritize cybersecurity, demand for advanced solutions is increasing rapidly.
- Services: Encompasses consulting, integration, managed security, and maintenance services that support the deployment and management of intrusion prevention systems, enabling enterprises to strengthen their cloud security posture efficiently.
- Deployment Mode
- Cloud-Based: Cloud deployment allows scalable and flexible security solutions, supporting rapid deployment and integration with existing cloud services which is highly desirable amid increasing cloud adoption in North America.
- On-Premises: On-premises solutions offer organizations control over their security infrastructure, often favored by firms with strict data sovereignty requirements and specific compliance mandates within the regional market.
- Geography
- United States: As the largest market within North America, the U.S. exhibits high demand driven by extensive cloud infrastructure, a resilient economy, and advanced technological adoption across numerous industries requiring robust intrusion prevention capabilities.
- Canada: Characterized by growing cloud adoption among banking, healthcare, and governmental sectors, Canada demonstrates increasing investments in intrusion detection and prevention solutions to enhance cybersecurity resilience.
- Mexico: The focus here is on securing emerging digital and cloud infrastructures, with a rising need for cost-effective and scalable intrusion prevention technologies tailored to regional regulations and market conditions.
This segmentation underscores the diverse needs and strategic priorities of North American enterprises across multiple dimensions, emphasizing customized solutions based on product types, deployment preferences, and localized regional requirements. As the market evolves, these categories will continue to influence innovation, investment, and competitive strategies in the North American cloud cybersecurity landscape.
Competitive Intelligence
The North America Cloud Intrusion Detection and Prevention Market is characterized by a high degree of competition among key players such as Palo Alto Networks, Cisco Systems, and Fortinet, which dominate the market landscape. Market concentration remains relatively high, with the top five companies accounting for over 60% of market share, driven by strategic mergers, acquisitions, and alliances that bolster their technological portfolios. Firms are increasingly investing in product innovation to address the evolving threat landscape, focusing on AI-powered detection, real-time analytics, and automation capabilities. Strategic partnerships with cloud service providers and cybersecurity firms facilitate extensive market reach and enhanced service offerings, fostering competitive advantage. Notable acquisitions, like that of startups specializing in machine learning-based security, enable established players to incorporate advanced technologies swiftly. Expansion strategies include geographical growth into underserved regions and diversification into adjacent cybersecurity domains. Heavy R&D investments are prioritized to develop differentiated, scalable, and interoperable solutions that meet diverse enterprise needs, secure competitive positioning, and accelerate market penetration in a rapidly evolving environment.
Leading Company Profiles
The North American market for cloud intrusion detection and prevention is highly competitive, characterized by innovative strategies, broad product portfolios, and a focus on advanced security technologies. The key players drive market growth through strategic alliances, product innovations, and acquisition activities that expand their market share and technological capabilities.
- Cisco Systems
- Palo Alto Networks
- Fortinet
- Check Point Software Technologies
- Trend Micro
- CrowdStrike
- SonicWall
- McAfee
- Barracuda Networks
Cisco Systems
Cisco Systems offers comprehensive cloud security solutions with a focus on intrusion detection and prevention, leveraging its extensive networking expertise and cybersecurity portfolio to address evolving cloud security challenges across enterprises.
Palo Alto Networks
Palo Alto Networks delivers advanced cloud security platforms that integrate intrusion detection, prevention, and firewall capabilities, emphasizing automation and AI-driven insights to protect cloud infrastructures from sophisticated cyber threats.
Fortinet
Fortinet provides broad-spectrum security solutions including advanced intrusion detection and prevention tailored for cloud environments, highlighting its dedicated security fabric architecture to ensure seamless integrated threat protection.
Check Point Software Technologies
Check Point specializes in unified security management and cloud intrusion prevention solutions, with a strong emphasis on scalable security architectures that support large enterprise cloud infrastructures and multi-cloud environments.
Trend Micro
Trend Micro’s cloud security offerings encompass intrusion detection and prevention tools designed with a focus on hybrid and multi-cloud deployments, combining threat intelligence, machine learning, and automation for proactive defense.
CrowdStrike
CrowdStrike stands out through its SaaS-based security platform that includes cloud intrusion detection modules leveraging real-time analytics and machine learning to quickly identify and neutralize threats in cloud ecosystems.
SonicWall
SonicWall integrates its intrusion prevention technology within its broad cybersecurity suite, emphasizing cost-effective yet robust solutions tailored for small and mid-sized enterprises adopting cloud services.
McAfee
McAfee provides cloud security solutions with strong intrusion detection and prevention capabilities, focusing on threat intelligence integration and cloud-native deployments to offer scalable security for diverse enterprise needs.
Barracuda Networks
Barracuda offers specialized cloud security appliances and software, including intrusion detection systems that support scalable, high-performance cloud environments, aiming at the mid-market segment with comprehensive security features.
Strategic Business Developments

- September 2024 – Cisco Systems – Launches new AI-enhanced intrusion detection platform – Enhances threat detection accuracy and response times, solidifying its leadership in cloud security innovation.
- August 2024 – Palo Alto Networks – Expands capacity with new regional data centers – Strengthens service reliability and reduces latency for cloud security solutions across North America, boosting customer confidence.
- July 2024 – Fortinet – Acquires CloudZero’s security division – Integrates advanced cloud workload protection capabilities into its security fabric, accelerating its product portfolio expansion and market penetration.
- June 2024 – Check Point Software – Establishes strategic alliance with Microsoft Azure – Develops integrated security solutions, enhancing protection for enterprise cloud workloads and expanding its multi-cloud security footprint.
- May 2024 – CrowdStrike – Launches new SaaS-based cloud intrusion prevention module – Offers enhanced real-time threat detection, facilitating scalable, quick deployment for diverse cloud environments, increasing market adoption.
Frequently Asked Questions
What is the North America Cloud Intrusion Detection and Prevention Market?
The North America Cloud Intrusion Detection and Prevention Market encompasses technologies and services aimed at identifying and mitigating security threats in cloud environments within North America, supporting organizations in safeguarding their cloud-based assets and ensuring compliance with cybersecurity regulations.
What is the current market size of North America Cloud Intrusion Detection and Prevention Market?
As of 2026, the market size is valued at approximately USD 3.2 Billion, reflecting widespread adoption of cloud security measures and increasing cyber threats, prompting firms across North American enterprises to invest in intrusion detection and prevention solutions.
What factors are driving the North America Cloud Intrusion Detection and Prevention Market?
Key drivers include the escalating frequency of cyberattacks, stringent data protection regulations, rising adoption of cloud services, technological advancements in security solutions, and increasing awareness about cybersecurity threats among North American companies, all contributing to rapid market growth.
Which region dominates the North America Cloud Intrusion Detection and Prevention Market?
The United States leads the North American market, driven by its large number of cloud service providers, high digitalization levels, and substantial cybersecurity investments, accounting for over 75% of the regional market share.
Which segment is expected to grow the fastest?
The managed services segment is projected to experience the highest growth rate, owing to the increasing complexity of cloud security management and the rising preference for outsourcing security functions to specialized providers.
Who are the leading companies operating in the North America Cloud Intrusion and Prevention Market?
Major players include Cisco Systems, Palo Alto Networks, Check Point Software Technologies, Fortinet, and Trend Micro. These companies focus on innovation, strategic partnerships, and expanding their product portfolios to maintain competitive advantages.
Analyst Perspective
The North America Cloud Intrusion Detection and Prevention Market is expected to mature gradually, with increasing integration of AI-driven analytics and automated threat response capabilities fueling long-term growth. Commercial opportunities will emerge around advanced, cloud-native security solutions tailored for specific industry verticals such as finance, healthcare, and retail, which face high compliance and security demands. Technological evolution will focus on enhanced predictive analytics and seamless integration with existing cloud infrastructures, reinforcing the market's strategic importance. Investment priorities should emphasize R&D for real-time threat detection and zero-trust architecture, positioning providers to address evolving cyber threats effectively. Competitive intensity will intensify as both established cybersecurity players and innovative startups vie for market share through differentiated offerings and strategic alliances. Regional growth potential remains strong in North America, driven by heightened cyber risks, digital transformation initiatives, and regulatory compliance pressures, making it a pivotal market for sustained cybersecurity innovation and long-term strategic positioning.
