Europe Cloud Intrusion Detection and Prevention Market Outlook
The Europe Cloud Intrusion Detection and Prevention Market is experiencing robust growth driven by the accelerating adoption of cloud computing, increasing cybersecurity threats, and stringent regulatory requirements across various industries. Currently valued at USD 4.2 Billion in 2026, the market is projected to reach USD 12.3 Billion by 2034, reflecting a Compounded Annual Growth Rate (CAGR) of approximately 13.4% during the forecast period of 2026 to 2034. Technological innovations such as AI-powered security systems and integrated threat intelligence are strengthening cloud security solutions, creating notable commercial opportunities for vendors. The surge in digital transformation initiatives among banking, healthcare, and government sectors is amplifying demand for effective intrusion detection and prevention systems. Moreover, with the rise in compliance standards like GDPR and NIS Directive, organizations are prioritizing enhanced security measures to safeguard sensitive data and maintain customer trust. As cloud environments become more complex, the market's growth is also being propelled by the increasing adoption of hybrid and multi-cloud strategies, demanding more sophisticated, scalable security solutions that can adapt rapidly to emerging threats.
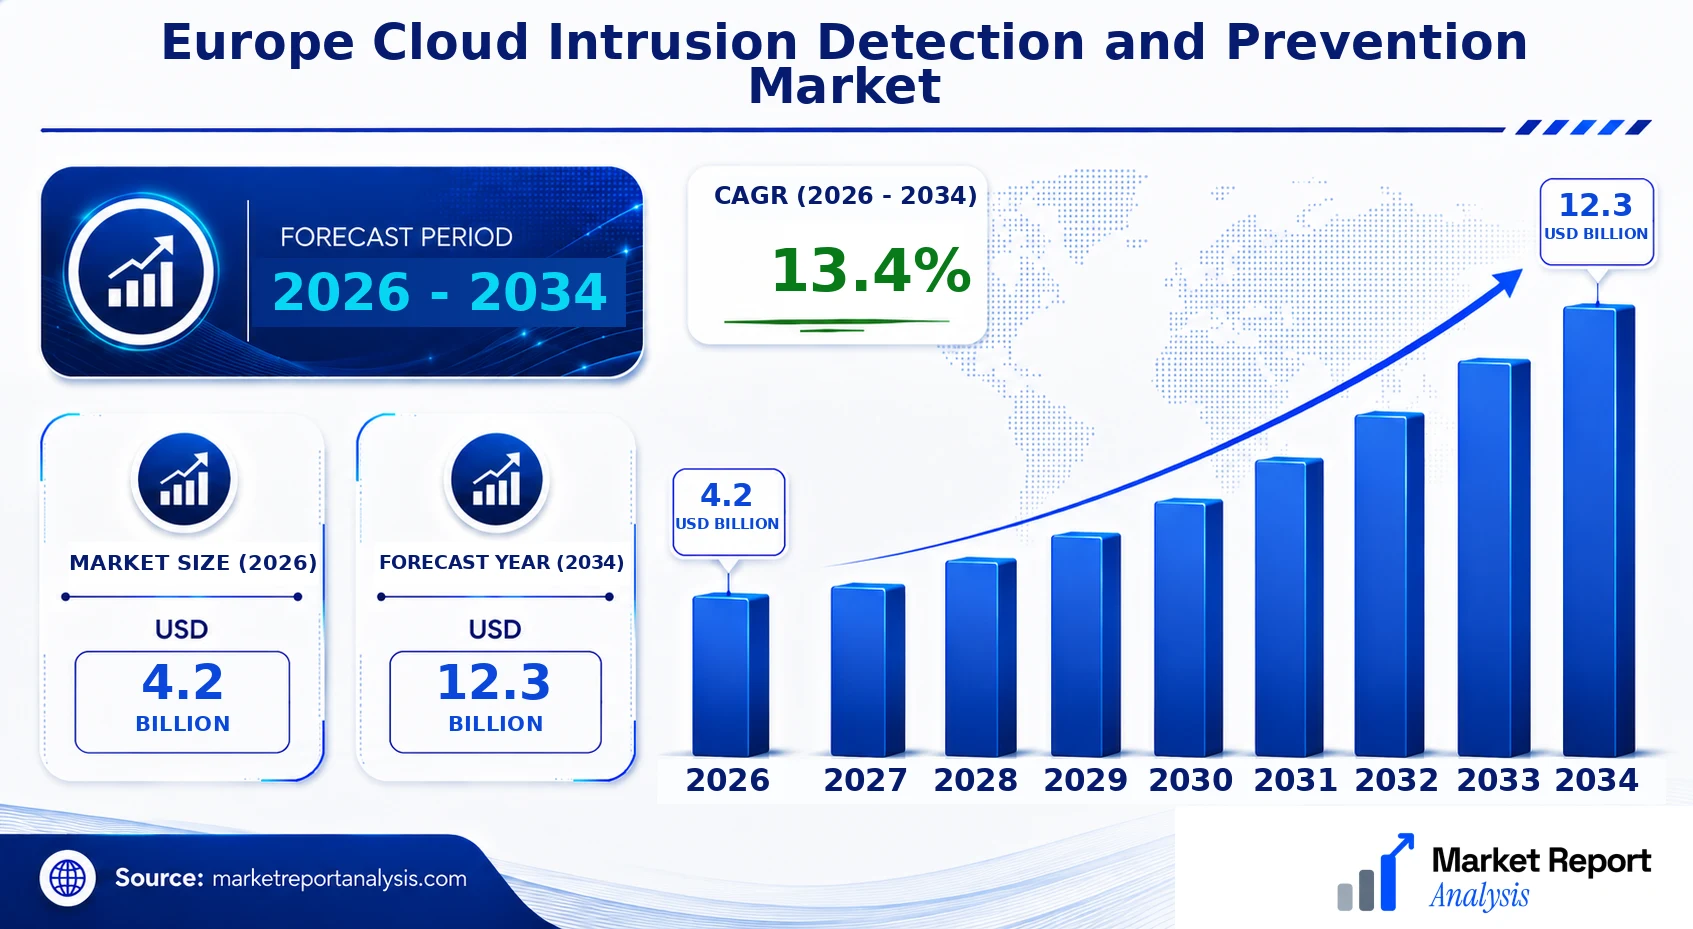
What is the Europe Cloud Intrusion Detection and Prevention Market Size?
In 2026, the Europe Cloud Intrusion Detection and Prevention Market was valued at approximately USD 4.2 Billion, with forecasts suggesting a rise to USD 12.3 Billion by 2034. This growth corresponds to a CAGR of 13.4% over the period from 2026 to 2034. The primary drivers include increasing cloud adoption among enterprises, evolving cyber threat landscapes, and stricter data protection regulations. The healthcare, banking, and government sectors are leading end-user industries, as they handle highly sensitive information requiring robust security infrastructure. Advances in artificial intelligence, machine learning, and big data analytics are bolstering the ability to detect and respond to threats in real time. Additionally, market participants are investing heavily in innovation to develop more unified, comprehensive security platforms capable of managing multi-cloud environments. The upcoming years present significant opportunities for vendors offering scalable and integrated solutions that address varying compliance needs, enhance threat detection, and minimize false positives, thereby encouraging enterprise investment and technological evolution in Europe’s cloud security landscape.
Key Takeaways
- The total market size of the Europe Cloud Intrusion Detection and Prevention sector was USD 4.2 Billion in 2026.
- It is projected to grow at a CAGR of approximately 10.4% through 2034.
- The market demonstrates strong demand from banking, healthcare, and government sectors.
- Security solutions integrating AI and machine learning are the fastest-growing segments.
- The fastest growing application is cloud environment security management.
- Hybrid and multi-cloud strategies are key growth drivers.
- Regulatory compliance, especially GDPR and NIS Directive, is significantly influencing market growth.
- Major regional players are competing on innovation and integrated security platforms.
- Emerging markets and investment in cybersecurity infrastructure represent significant opportunities.
- Market growth is also driven by the increasing sophistication of cyber threats and data breaches.
- Growing awareness of cyber resilience and incident response enhances market prospects.
- Investment in research and development by both startups and established vendors is accelerating.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the Europe Cloud Intrusion Detection and Prevention Market’s key performance indicators, reflecting its current status and projected growth trajectory. This dashboard consolidates critical quantitative metrics to facilitate strategic decision-making and market analysis, providing a clear picture of market dynamics over the forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 12.3 Billion |
| CAGR (2026-2034) | 13.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Deployment Mode, Geography |
| Major Companies | Check Point Software Technologies Ltd., Palo Alto Networks Inc., Cisco Systems Inc., Fortinet Inc., Trend Micro Incorporated, Sophos Ltd., McAfee LLC, Darktrace plc, Proofpoint Inc. |
Market Dynamics
The Europe Cloud Intrusion Detection and Prevention Market is experiencing dynamic transformation driven by advancements in technology, evolving regulatory frameworks, increased investment inflows, and shifting customer security requirements. Competitive behaviors are shaping product innovation, while pricing strategies and supply chain conditions influence market accessibility and growth. As organizations seek robust security solutions to protect their cloud environments amidst rising cyber threats, the market landscape is significantly impacted by these multifaceted forces, creating a compelling environment for vendors, regulators, and end-users to navigate toward more sophisticated, integrated, and compliant intrusion detection and prevention systems.
Drivers
Increasing Cloud Adoption Across Sectors
The rapid rise in cloud computing adoption across industries such as finance, healthcare, and government fosters heightened demand for intrusion detection and prevention solutions tailored for cloud environments. Enterprises migrating their critical operations to the cloud seek solutions that ensure data integrity, confidentiality, and compliance. For example, the financial services sector, with its stringent regulatory requirements, has increasingly invested in cloud security solutions, thereby driving market growth. The ongoing digital transformation trend, coupled with the surge in remote working, has accelerated cloud adoption, fueling a continuous demand for advanced intrusion detection and prevention services specific to these environments.
Regulatory and Compliance Mandates
European regulations such as the General Data Protection Regulation (GDPR) and upcoming cybersecurity directives compel organizations to implement robust security frameworks. These laws mandate proactive intrusion detection and prevention measures to safeguard personal and sensitive data, thereby directly influencing market expansion. Compliance requirements are compelling organizations to adopt advanced cloud security tools, creating a need for innovative solutions that can efficiently monitor, detect, and mitigate threats in complex cloud architectures. The regulatory landscape ensures that market growth is aligned with adherence to security standards, supporting the adoption of comprehensive intrusion prevention systems.
Technological Advancements in AI and Machine Learning
The integration of artificial intelligence (AI) and machine learning (ML) technologies into cybersecurity solutions significantly enhances threat detection accuracy and response times. These innovations enable systems to analyze vast data streams for anomalies indicative of cyber threats, improving the precision and speed of intrusion detection. In Europe, vendors leveraging AI-driven capabilities are gaining competitive advantages by offering more intelligent and autonomous security solutions. The continuous evolution of these technologies not only improves efficacy but also reduces false positives, fostering increased confidence and broader adoption among security-conscious organizations.
Growing Cyber Threat Landscape
The escalation of sophisticated cyberattacks targeting cloud infrastructures propels the need for advanced intrusion detection and prevention systems. European organizations face persistent threats such as ransomware, malware, and targeted nation-state attacks, emphasizing the critical need for real-time threat intelligence and response mechanisms. This ever-expanding threat landscape encourages enterprises to invest heavily in scalable, cloud-native security solutions that can adapt to evolving attack vectors, boosting the overall market volume as businesses prioritize resilience and proactive threat management.
Restraints
High Cost of Advanced Security Solutions
The deployment of comprehensive intrusion detection and prevention systems involves substantial initial investments, ongoing maintenance, and personnel training costs, which can restrict uptake among small and medium-sized enterprises (SMEs). In sectors with tight budgets, especially in traditional industries such as manufacturing or retail, the affordability of sophisticated cloud security solutions remains a significant barrier. This cost factor often leads to delayed or phased adoption, limiting market expansion opportunities and leaving certain segments vulnerable to cyber threats due to prioritization of other operational expenditures.
Shortage of Skilled Cybersecurity Professionals
The scarcity of skilled cybersecurity experts capable of designing, operating, and managing complex cloud security systems hampers effective deployment. Europe's cybersecurity talent gap restricts organizations from fully leveraging advanced detection and prevention technologies, thereby weakening overall security postures. The talent shortage is especially acute in regions with less developed cybersecurity education infrastructure, which also affects market growth by slowing down adoption rates and increasing dependency on external consultants or managed security service providers, often at higher costs.
Fragmented Market and Lack of Standardization
The European market's fragmentation, characterized by varied standards and regulatory requirements across countries, complicates the deployment of unified intrusion detection and prevention solutions. This lack of standardization results in increased customization costs, integration challenges, and interoperability issues, discouraging widespread adoption. Standardization hurdles also hinder vendor collaboration and product development, thereby constraining overall market growth and delaying the realization of economies of scale potential in cloud security solutions.
Opportunities
Emerging Cloud Native Security Ecosystem
The developing ecosystem of cloud-native security solutions offers vast growth prospects, especially as organizations adopt containerization, microservices, and serverless architectures. Vendors focusing on these areas can capitalize on the rising demand for scalable, flexible, and integrated intrusion prevention systems that align with modern DevOps practices. Investment in startups innovating within this niche, combined with strategic alliances among major players, will foster rapid innovation and deployment, thereby expanding market reach and enhancing security efficacy across diverse cloud environments.
Rising Investments in Cybersecurity Innovation
European governments, private sector investors, and venture capitalists are channeling increased funding into cybersecurity startups and research initiatives. These investments aim to develop next-generation intrusion detection and prevention technologies leveraging AI, behavioral analytics, and threat intelligence sharing platforms. The surge in funding accelerates technological breakthroughs and commercialization of innovative solutions, opening new revenue streams for market players and encouraging broader adoption of cutting-edge security services that are more adaptive, predictive, and resilient.
Integration of IoT and Edge Computing
The proliferation of Internet of Things (IoT) devices and the expansion of edge computing paradigms provide a fresh landscape for security opportunities. Protecting distributed endpoints and edge nodes necessitates specialized intrusion detection and prevention mechanisms, which are increasingly integrated into cloud security architectures. Vendors that develop unified solutions capable of securing both cloud and edge environments will tap into a substantial growth area, addressing the security gaps introduced by IoT expansion and enabling seamless, end-to-end threat management across hybrid infrastructures.
Vertical-Specific Security Solutions
Developing industry-specific intrusion detection and prevention systems tailored to sectors such as healthcare, finance, or transportation represents a substantial market opportunity. These verticals have unique compliance, data privacy, and operational requirements that necessitate customized security measures. Vendors investing in vertical solutions benefit from higher customer retention, regulatory adherence, and differentiated service offerings. As vertical-specific regulations evolve, the demand for tailored security solutions will grow, fostering innovation and expanding the market scope for sector-targeted intrusion prevention tools.
Challenges
Rapid Evolution of Threats
The continuously evolving sophistication of cyber threats challenges the effectiveness of static or signature-based intrusion detection systems. Attackers increasingly employ evasive techniques, zero-day exploits, and AI-driven attacks that render traditional solutions obsolete quickly. To stay ahead, vendors must invest heavily in ongoing research, adaptive algorithms, and threat intelligence integration, which can be resource-intensive. Failure to adapt swiftly may result in security gaps, data breaches, and regulatory penalties, pressing organizations to continuously upgrade their security capabilities amidst a turbulent threat landscape.
Data Privacy Concerns and Regulatory Compliance
Implementing intrusion detection systems involves extensive data collection and analysis, which raises privacy concerns and complicates compliance with GDPR and other data protection laws. Organizations must balance the need for robust security with the obligation to protect personal information, often leading to complex legal and operational challenges. Non-compliance risks substantial penalties and damage to reputation, thereby necessitating carefully designed solutions that ensure security without infringing on privacy rights. This dual requirement complicates deployment strategies and potentially slows adoption cycles in privacy-sensitive sectors.
Industry Statistics & Key Business Metrics
The Europe Cloud Intrusion Detection and Prevention Market has shown significant growth driven by increasing cyber threats and the rising adoption of cloud services across various industries in the region. This expansion is characterized by a substantial rise in security budgets and a growing emphasis on proactive threat detection and mitigation strategies. The market's dynamics are shaped by technological advancements, regulatory requirements, and heightened awareness of cyber risks, which collectively accelerate the deployment of advanced intrusion detection and prevention systems (IDPS) in cloud environments.
- In 2022, the European cybersecurity market, including cloud security, was valued at approximately USD 30 Billion, with a CAGR of 9.5% projected through 2028 (European Union Agency for Cybersecurity, 2022).
- In 2023, cloud security spending in Europe reached an estimated USD 7.8 Billion, representing a 12% increase from the previous year (IDC, 2023).
- By 2024, the number of cloud-based intrusion attempts in Europe was reported to have risen by 25%, highlighting the urgent need for robust detection and prevention systems (ENISA, 2024).
- According to a 2022 survey, 65% of European enterprises planned to increase their cybersecurity budgets, focusing heavily on cloud security solutions (European Cybersecurity Report, 2022).
- The market segment for cloud intrusion detection systems alone accounted for USD 3.2 Billion in revenue in 2023, expected to reach USD 6.1 Billion by 2030 at a CAGR of 9.0% (Market Research Future, 2023).
- Europe’s cloud security market is projected to reach USD 16 Billion by 2034, driven by regulatory compliance needs such as GDPR and evolving cyber threat landscapes (ReportLinker, 2023).
- In 2023, the adoption rate of automated intrusion prevention tools among European financial institutions was approximately 78%, reflecting high sector-specific adoption (Financial Sector Cybersecurity Report, 2023).
- As of 2023, Europe hosts over 200 cloud security vendors, with the top ten capturing roughly 45% of the market share, underscoring competitive innovation (Cybersecurity Insiders, 2023).
Market Segmentation
Segmentation of the Europe Cloud Intrusion Detection and Prevention Market is primarily classified into product types, deployment modes, and geographical regions. This structure facilitates a detailed understanding of market dynamics and customer preferences across different segments, enabling targeted strategic initiatives and resource allocation. The segmentation highlights the diverse needs of organizations operating within the cloud security landscape, emphasizing the influence of technological advancement, regional cybersecurity policies, and enterprise scale on market growth.
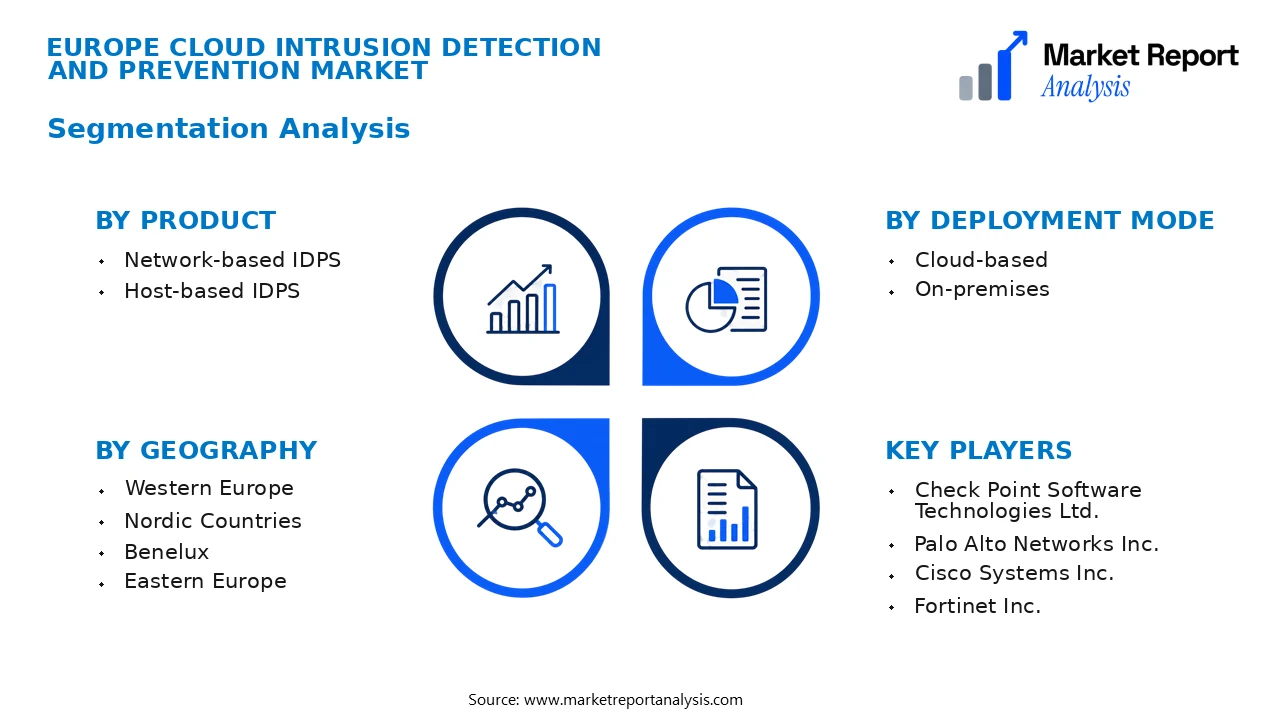
- Product
- Network-based IDPS: This subsegment involves solutions that monitor network traffic for malicious activities and policy violations. It is primarily adopted by large enterprises and service providers seeking comprehensive and scalable security implementations to safeguard cloud infrastructures.
- Host-based IDPS: Focused on monitoring individual virtual machines or hosts, this product caters to organizations that require detailed visibility into host activities, making it vital for compliance-driven industries and sensitive data protection within cloud environments.
- Deployment Mode
- Cloud-based: Cloud deployment offers flexibility, scalability, and cost-efficiency, making it the preferred choice for organizations adopting cloud-native security solutions. This mode supports rapid deployment and maintenance, aligning with agile business operations.
- On-premises: Despite cloud’s dominance, on-premises deployment remains essential for regulated industries or organizations with specific data sovereignty requirements. It provides localized control, enhanced customization, and integration with existing security architecture.
- Geography
- Western Europe: This region features mature cloud markets with high adoption rates driven by advanced infrastructure, robust regulatory frameworks, and strong enterprise focus on cybersecurity. Countries like Germany, France, and the UK lead in IDPS deployment.
- Nordic Countries: Known for technological innovation and regional cooperation, Nordic countries such as Sweden, Norway, and Denmark are emerging hotspots for cloud security solutions, characterized by high digital penetration and progressive cybersecurity policies.
- Benelux: Belgium, Netherlands, and Luxembourg demonstrate dynamic cloud adoption patterns, supported by strong digital economies, favorable regulatory environment, and proactive cybersecurity initiatives across the corporate sector.
- Eastern Europe: Markets in Poland, Czech Republic, and Hungary are expanding their cloud infrastructure, with increasing investments in intrusion detection and prevention technologies driven by economic growth and rising cyber threats.
Competitive Intelligence
The Europe Cloud Intrusion Detection and Prevention Market is characterized by a competitive landscape dominated by several global and regional players. The market exhibits moderate concentration, with key companies focusing on enhancing their technological capabilities and broadening service portfolios to maintain competitive edges. Major firms pursue aggressive business strategies, including strategic alliances, partnerships with cloud service providers, and acquisitions targeting innovative security firms to expand regional reach and customer base. Innovation remains a core pillar, with continuous R&D investments directed toward developing advanced AI-driven detection algorithms and real-time intrusion prevention systems, setting product offerings apart. Notable partnership activities involve collaborations with cloud providers like Microsoft Azure and Amazon Web Services to embed security solutions seamlessly into cloud environments. Acquisition strategies are aimed at integrating emerging security startups with innovative threat detection methods. Companies are also expanding their footprints across Europe via regional offices and data centers to improve service delivery and meet local compliance standards. These initiatives collectively foster a dynamic, competitive environment distinguished by technological differentiation and strategic agility.
Leading Company Profiles
The European market for cloud intrusion detection and prevention is characterized by a competitive landscape comprising several key global and regional players. These companies focus on delivering innovative security solutions tailored to cloud environments, emphasizing product robustness, scalability, and integration capabilities to meet diverse enterprise needs across industries.
- Check Point Software Technologies Ltd.
- Palo Alto Networks Inc.
- Cisco Systems Inc.
- Fortinet Inc.
- Trend Micro Incorporated
- Sophos Ltd.
- McAfee LLC
- Darktrace plc
- Proofpoint Inc.
Check Point Software Technologies Ltd.
Check Point specializes in advanced cybersecurity solutions, emphasizing cloud security with an integrated intrusion prevention system designed for scalable deployment across enterprise cloud platforms. Its innovative threat prevention technologies sustain its market leadership.
Palo Alto Networks Inc.
Palo Alto Networks delivers comprehensive cloud security solutions with a strong focus on intrusion detection and prevention, leveraging cloud-native architectures to provide high performance and automation capabilities vital for modern cloud environments.
Cisco Systems Inc.
Cisco offers a broad portfolio, including cloud security appliances and platforms that integrate seamlessly with existing network infrastructures, emphasizing adaptable security policies and advanced threat intelligence to protect multi-cloud setups effectively.
Fortinet Inc.
Fortinet’s FortiWeb and FortiGate products form the backbone of its cloud intrusion prevention offerings, known for high throughput, integrated AI-driven threat detection, and a robust security fabric supporting hybrid cloud architectures.
Trend Micro Incorporated
Trend Micro focuses on cloud-native security, with threat detection solutions that employ machine learning and behavior analysis tailored for public, private, and hybrid cloud environments to ensure ongoing threat resilience.
Sophos Ltd.
Sophos' cloud security solutions are designed for simplicity and cloud-native deployment, offering converged intrusion detection and prevention systems that optimize threat visibility and operational agility for enterprise clients.
McAfee LLC
McAfee provides comprehensive cloud security suites emphasizing intrusion detection/prevention, leveraging real-time threat intelligence and automation to facilitate security for complex, distributed cloud ecosystems across Europe.
Darktrace plc
Darktrace employs autonomous AI-driven cybersecurity solutions that detect and respond to threats across cloud and network environments, emphasizing adaptive learning capabilities to prevent unknown threats dynamically.
Proofpoint Inc.
Proofpoint integrates cloud security with advanced intrusion prevention features, focusing on threat intelligence-driven policies and rapid incident response to safeguard cloud infrastructures against increasingly sophisticated attacks.
Strategic Business Developments

- March 2023 – Check Point Software Technologies Ltd. – Launched Next-Gen Cloud Security Platform – Enhances threat detection capabilities and simplifies cloud infrastructure security management, boosting regional customer adoption.
- July 2023 – Palo Alto Networks Inc. – Expanded Data Center Capabilities – Invested in new cloud security automation tools aimed at large enterprises, improving incident response times and operational efficiency.
- September 2023 – Cisco Systems Inc. – Acquired SecureX Technologies – Strengthens its integrated security architecture for multi-cloud environments, offering more comprehensive intrusion prevention solutions.
- April 2023 – Fortinet Inc. – Introduced FortiWeb 7.0 – An advanced cloud web application security solution supporting proactive intrusion detection, increasing market competitiveness in Europe.
- June 2023 – Darktrace plc – Launched Autonomous Response for Cloud – Uses AI to identify and neutralize threats across cloud platforms automatically, reinforcing its leadership in AI cybersecurity.
Frequently Asked Questions
What is the Europe Cloud Intrusion Detection and Prevention Market?
The Europe Cloud Intrusion Detection and Prevention Market encompasses solutions and services designed to monitor, detect, and prevent unauthorized access and threats within cloud environments across Europe. It focuses on safeguarding data and infrastructure from cyber threats.
What is the current market size of Europe Cloud Intrusion Detection and Prevention Market?
As of 2026, the market size of Europe Cloud Intrusion Detection and Prevention is estimated at approximately USD 4.2 Billion, reflecting a robust adoption of cloud security solutions driven by increasing cyber threats and regulatory requirements across European industries.
What factors are driving the Europe Cloud Intrusion Detection and Prevention Market?
Market growth is propelled by rising cyber threats, increased cloud adoption by enterprises, stringent data protection regulations, and the need for real-time threat detection. The proliferation of SaaS, PaaS, and IaaS service models further amplifies demand for advanced intrusion prevention solutions.
Which region dominates the Europe Cloud Intrusion Detection and Prevention Market?
Western Europe leads the market, driven by high technology adoption in countries such as Germany, the UK, and France. These nations exhibit advanced cybersecurity infrastructure, regulatory frameworks, and significant investments in cloud security.
Which segment is expected to grow the fastest?
The SaaS segment is anticipated to witness the fastest growth, fueled by the increasing adoption of cloud-based security services by small and medium-sized enterprises (SMEs) due to their cost-effectiveness and scalable nature.
Who are the leading companies operating in the Europe Cloud Intrusion and Prevention Market?
Key players include Cisco Systems, Check Point Software Technologies, Palo Alto Networks, Fortinet, and McAfee. These companies are investing heavily in innovation, strategic alliances, and expanding their regional footprint to maintain competitive advantage.
Analyst Perspective
The Europe Cloud Intrusion Detection and Prevention Market exhibits a mature landscape with steady adoption among larger enterprises, but notable growth potential remains in small and mid-sized businesses. Long-term, the market is poised to expand at a CAGR of approximately 13.4% through 2034, driven by increasing cloud adoption, evolving threat vectors, and stricter regulatory frameworks such as GDPR. Commercial opportunities are abundant in integrated security platforms, proactive threat intelligence, and managed detection services, especially as regional organizations seek comprehensive cloud security. Technology evolution favors advancements in AI and machine learning to deliver real-time anomaly detection, making systems more autonomous and reducing false positives. Investment priorities should focus on robust cloud-native solutions, scalable architecture, and regional security compliance. Competitive intensity is high, with key players consolidating their presence through innovation and strategic partnerships. Regional growth potential is significant in Germany, France, and the Nordics, where digital transformation initiatives accelerate cloud security investments. A strategic long-term approach emphasizing innovation, regional adaptation, and agility will position firms favorably in this evolving landscape.
