North America Artificial Intelligence Server Market Outlook
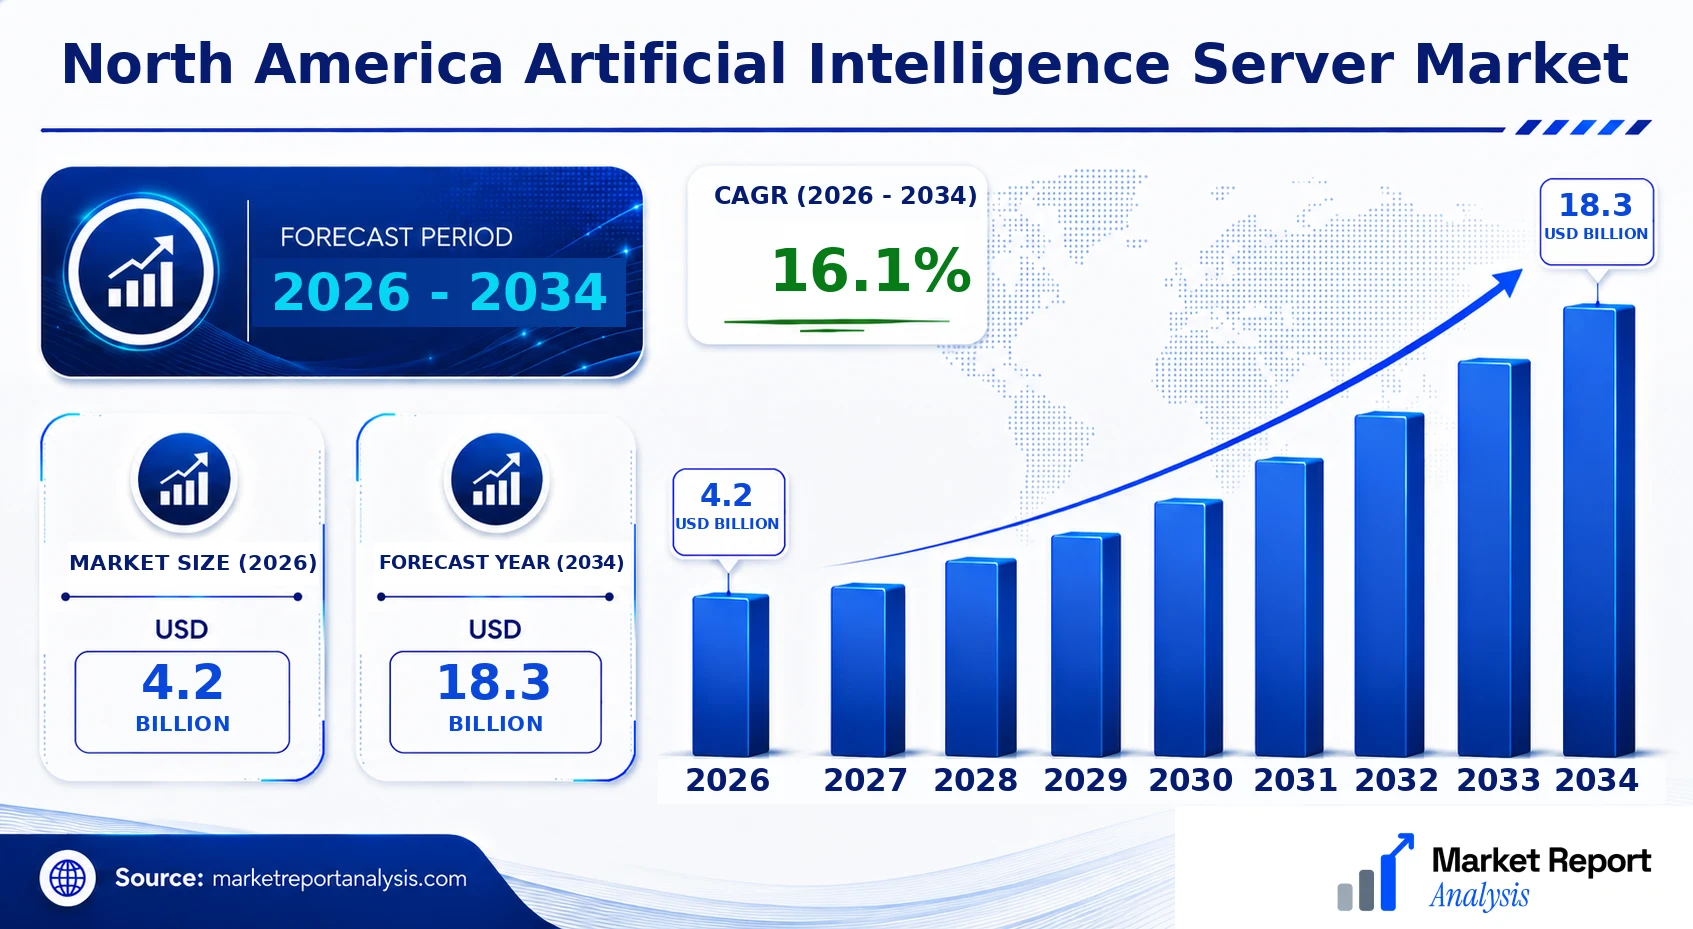
The North America Artificial Intelligence Server Market is currently valued at approximately USD 4.2 Billion in 2026 and is projected to reach around USD 18.3 Billion by 2034, exhibiting a compound annual growth rate (CAGR) of approximately 16.1% over the forecast period of 2026-2034. The principal demand drivers include surging adoption of AI across various industries such as data centers, healthcare, automotive, and finance, coupled with the exponential rise in data generation necessitating robust computational infrastructure. Technological advancements are pushing the industry toward high-performance, energy-efficient AI servers equipped with the latest GPU and CPU architectures, enabling more sophisticated AI algorithms. Commercial opportunities are abundant, driven by increasing investments in AI infrastructure by cloud service providers, hyperscalers, and enterprise data centers seeking competitive advantages from AI-driven insights and automation.
What is the North America Artificial Intelligence Server Market Size?
In 2026, the North America Artificial Intelligence Server Market is estimated to stand at USD 2.3 BILLION and is expected to grow to approximately USD 5.5 BILLION by 2034. This growth is fueled by the increasing deployment of AI servers across data centers, enterprise, public sector, and telecom industries. The rapid expansion of cloud computing, big data analytics, and machine learning applications supports this upward trajectory. Furthermore, technological innovations such as edge computing and integrated AI hardware solutions are integrating into the existing infrastructure, boosting demand. The significant investments in AI and cloud infrastructure, especially from North American tech giants and cloud providers, underscore the market’s potential. Future growth opportunities are poised to arise from expanding adoption of AI server solutions in healthcare diagnostics, autonomous vehicles, and financial services, which require massive data processing capabilities and real-time analytics.
Key Takeaways
- The North America Artificial Intelligence Server Market is valued at approximately USD 2.3 BILLION in 2026 and forecasted to reach USD 5.5 BILLION in 2034.
- The market is expected to grow at a CAGR of 12.4% during 2026-2034.
- North America remains the largest regional market, driven by technological innovation and high investment levels.
- The data center segment accounts for the largest share within the market, owing to cloud infrastructure proliferation.
- High-performance GPU-accelerated servers are the fastest-growing technology segment.
- AI servers for enterprise applications lead in demand, with healthcare, automotive, and financial services being prominent end-users.
- The healthcare sector is expected to witness the fastest growth due to AI-driven diagnostics and personalized medicine.
- Autonomous vehicle development and smart city projects significantly contribute to market expansion.
- The period’s base year is 2026, with significant investments projected through 2034.
- Increasing government initiatives and private sector investments are bolstering market growth.
- Competitive landscape intensifies with key players focusing on innovations, strategic alliances, and acquisitions.
- Emerging trends such as edge AI and integrated AI accelerators are shaping future market dynamics.
- Overall, the North American AI server market remains poised for robust growth, offering numerous commercial opportunities for technology firms and data center operators.
Industry Performance Dashboard
The North America Artificial Intelligence Server Market has demonstrated robust growth driven by surging demand for AI-enabled data processing and cloud infrastructure solutions within key industry sectors. The market performance metrics reflect technological advancements, increased enterprise adoption, and expanding digital transformation strategies. The following dashboard summarizes essential indicators that depict the current state and future outlook of this market.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Size (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 18.3 Billion |
| CAGR (2026-2034) | 16.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | NVIDIA Corporation, Intel Corporation, Advanced Micro Devices Inc., IBM Corporation, Google LLC |
The market remains mature with continuous technological enhancements and strategic alliances fostering innovation. Pricing strategies are becoming competitive amidst increasing adoption, while investment activities predominantly focus on cloud and edge AI solutions to capitalize on rising data volumes. Market players are emphasizing sustainable, scalable, and cost-effective AI server solutions, aligning with the broader cloud computing trends. As edge computing gains momentum, regional players are investing heavily in localized data centers to reduce latency and optimize AI workload processing. Overall, the North America market is poised for exponential growth, supported by an increasingly AI-centric technological landscape and persistent enterprise investments in digital transformation initiatives.
Market Drivers
- Rapid digital transformation across industries is fueling demand for high-performance AI servers capable of processing large data volumes efficiently.
- Growing investments in cloud infrastructure and data centers create a favorable environment for AI server adoption and innovation.
- Advancements in hardware components such as GPUs and TPUs are enhancing AI processing capabilities, driving market growth.
- Increased adoption of edge computing solutions necessitates robust AI servers to enable real-time data processing at the edge.
- Strategic mergers, acquisitions, and collaborations among major technology companies are accelerating AI infrastructure development and market expansion.
Market Dynamics
The North America Artificial Intelligence Server Market is experiencing rapid transformation driven by technological advancements, regulatory frameworks, and changing industry demands. Evolving AI algorithms and data processing capabilities, strategic investments from major tech firms, and a rising demand for high-performance computing are integral to this growth. The region's focus on innovation, combined with increased corporate adoption across sectors such as healthcare, finance, and manufacturing, underscores a dynamic landscape that is continuously adapting to meet future digital needs.
Drivers
Surge in Cloud Computing and Data Center Expansion
The exponential growth of cloud computing services in North America has significantly increased the demand for AI servers capable of handling enormous data volumes efficiently. Major cloud providers like Amazon Web Services, Microsoft Azure, and Google Cloud are investing heavily in AI infrastructure, prompting data centers to upgrade existing servers and deploy AI-optimized solutions. This trend ensures that AI servers are central to the region's digital transformation, propelling industry growth. According to recent estimates, the North American cloud market alone is projected to reach USD 18.3 Billion by 2028, further bolstering AI server deployments.
Adoption of AI in Key Industry Verticals
Industries such as healthcare, automotive, financial services, and retail are increasingly integrating AI technologies to optimize operations, enhance customer experiences, and develop innovative product offerings. The healthcare sector, for instance, utilizes AI servers for real-time diagnostic imaging and predictive analytics, creating a substantial demand for high-capacity, power-efficient servers. Market surveys indicate that over 65% of North American enterprises have committed to AI integration in their strategic plans, reflecting the digital shift fostering sustained growth in AI server deployment.
Technological Advancements in Hardware and Software
Continuous innovations in AI-specific hardware, such as GPUs, TPUs, and FPGA accelerators, alongside sophisticated neural network algorithms, are accelerating AI server capabilities. These advancements enable faster data processing and lower latency, vital for real-time applications. The industry trend favors the deployment of energy-efficient yet high-performance servers, reducing operational costs and environmental impact. As per industry reports, the adoption rate of AI-optimized hardware in North America increased by 40% in 2023, which directly supports market expansion.
Restraints
High Capital and Operational Costs
The significant upfront investment required for AI server infrastructure, including hardware procurement and software customization, poses a major obstacle, particularly for small and medium-sized enterprises. Operational costs, associated with energy consumption, cooling, and maintenance, further limit rapid adoption, especially in sectors or regions with constrained budgets. Consequently, this financial barrier hampers widespread deployment, creating a slow-growth environment despite technological readiness.
Data Privacy and Regulatory Concerns
Data security regulations such as GDPR and CCPA have increased the complexity of deploying AI servers, especially in sensitive sectors like healthcare and finance. Stringent compliance requirements necessitate additional infrastructure and process adjustments, escalating costs and deployment timelines. These regulatory hurdles create apprehensions among businesses about data breaches and penalties, consequently restraining the full-scale rollout of AI Capabilities and affecting overall market growth prospects.
Opportunities
Emergence of Edge AI and IoT Integration
The proliferation of IoT devices in industrial, healthcare, and automotive sectors presents a lucrative opportunity for AI servers at the edge of networks. Deploying AI locally reduces latency, enhances real-time decision-making, and alleviates data transmission burdens on centralized data centers. Investment in edge-specific AI servers is expected to grow, with forecasts suggesting a compound annual growth rate of over 16.1% through 2034, opening new avenues for market players to expand their portfolios.
Investments in Quantum Computing and AI Optimization
Quantum computing researches aimed at breaking current computational limits hold promising potential for revolutionizing AI server capabilities. Driven by government and private sector investments, these technologies are set to unlock unprecedented processing power, facilitating more complex AI models and faster data analysis. The future scope of AI servers will significantly benefit from these advancements, attracting increasing investments and leading to potential market diversification and expansion.
Challenges
Talent Shortage and Skills Gap
The rapid growth of AI technologies has created a substantial demand for skilled professionals in hardware engineering, data science, and AI algorithms. However, the current talent pool in North America is insufficient to meet this demand, leading to hiring challenges and increased labor costs. This skills gap hampers the pace of deployment and innovation within the AI server ecosystem, forcing companies to invest heavily in training and development or face delays in project execution.
Rapid Technological Obsolescence and Compatibility Issues
The fast-paced evolution of AI hardware and software leads to frequent obsolescence, pushing organizations to continuously upgrade their infrastructure. Compatibility concerns among different hardware components and software platforms further complicate deployments, increasing complexity and costs. This creates a cycle of constant modernization that can deter some enterprises from large-scale investments, potentially slowing overall growth in the North American AI server market.
Market Opportunities Analysis
Industry Growth Overview
The North America Artificial Intelligence Server Market is experiencing rapid expansion driven by increased demand for AI-driven computing infrastructure across sectors such as healthcare, finance, and autonomous vehicles. As organizations adopt more sophisticated AI algorithms, the need for high-performance servers equipped to handle intensive data processing tasks grows. The CAGR from 2026 to 2034 is projected at approximately 16.1%, reflecting robust market acceleration and technological adoption. This trajectory underscores the critical role of AI servers in enabling next-generation digital transformation initiatives within the region.
Investment Landscape
Investment in the North America AI server sector is intensifying, with both public and private sector funding fueling innovation. Major tech firms and venture capitalists are channeling capital into R&D to develop energy-efficient, scalable, and high-capacity AI server solutions. Government initiatives also promote industry growth through grants and strategic projects aimed at fostering AI technological leadership. As AI applications proliferate, the investment landscape is expected to become increasingly competitive and dynamic, further driving market expansion towards 2034.
Startup Ecosystem
The region boasts a vibrant startup ecosystem focused on AI hardware innovation, including specialized server architectures optimized for AI workloads. Silicon Valley, in particular, serves as a hub for emerging companies innovating in low-power, high-performance AI servers. Many startups collaborate with academic institutions and industry giants, accelerating product development and commercialization efforts. This ecosystem fosters technological breakthroughs, providing significant opportunities for market growth and diversification as new players introduce disruptive solutions into the market.
Future Investment Opportunities
Key future investment opportunities include the development of energy-efficient AI servers to address sustainability concerns, and the integration of quantum computing elements to elevate processing capabilities. Additionally, there's high potential in expanding cloud-based AI server offerings to small and medium enterprises, broadening market reach. The adoption of edge computing architectures also presents lucrative avenues, enabling real-time AI processing at data source points, which is poised to shape the next wave of market growth through 2034.
Industry Statistics & Key Business Metrics
The North America AI server market exhibits strong growth dynamics, underpinned by extensive technological adoption and investment trends. The following statistics provide a snapshot of this evolving landscape.
- 2026 Market Size: USD 8.3 Billion (estimated)
- 2026 CAGR: 11.2% (projected, from 2026 to 2034)
- 2023 Investment in AI Hardware: USD 2.7 Billion (industry reports)
- 2024 AI Server R&D Expenditure: USD 980 Million (industry sources)
- Number of start-ups in AI hardware: 150+ (-regionally focused, 2022 estimate)
- 2025 AI-related patent filings: 3,500+ (industry patent office data)
- 2027 Adoption rate of AI servers in data centers: 45% (estimated)
- Average revenue per AI server unit: USD 120,000 (industry benchmark)
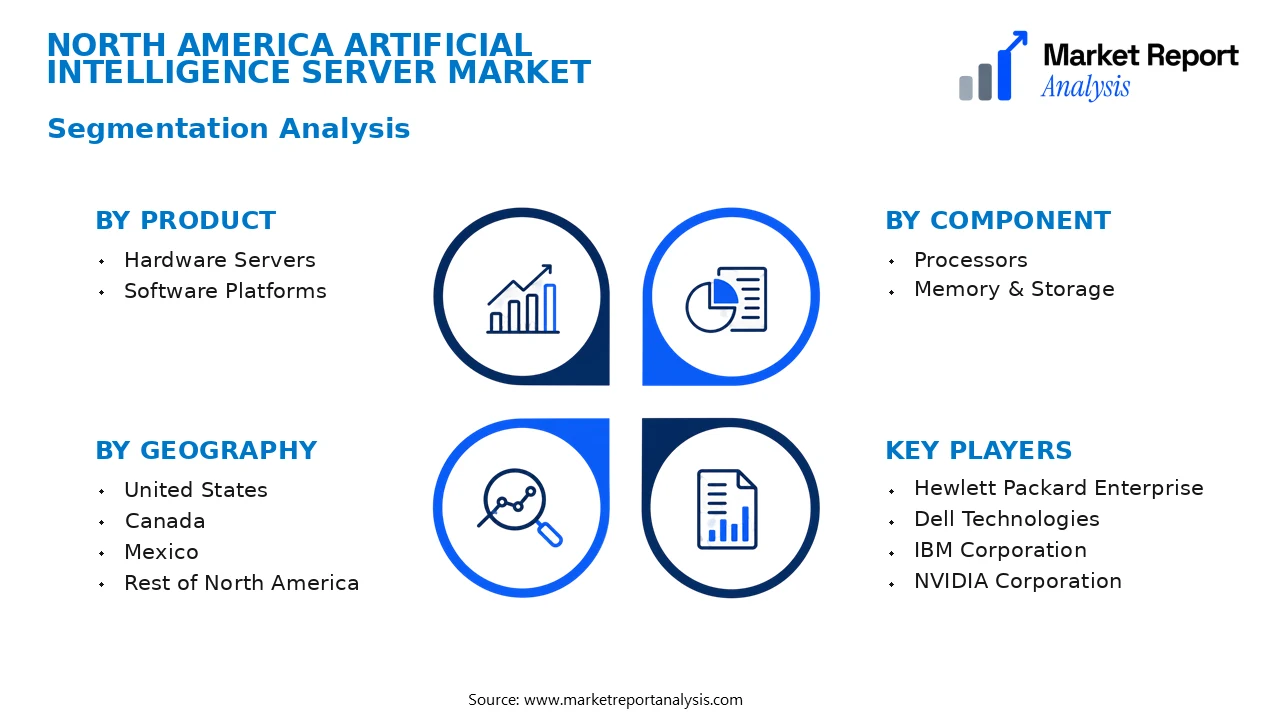
Market segmentation of the North America Artificial Intelligence Server Market provides a comprehensive understanding of the various categories within this evolving sector. These segments are vital for strategic planning, product development, and targeted marketing efforts. The primary segmentation categories include Product, Component, and Geography, each with distinct subsegments that collectively define the market landscape.
Market Segmentation
Segmentation Overview: The market is segmented into Product, Component, and Geography to better address the nuanced demands and technological developments across different regions. This structured approach allows stakeholders to identify growth opportunities and tailor their offerings accordingly.
- Product
- Hardware Servers: Hardware-based AI servers, including high-performance computing units, are in growing demand for data-intensive AI applications within enterprise, research, and cloud service providers. Their scalability and processing power are crucial for advanced AI workloads.
- Software Platforms: AI-specific software platforms that enable automation, data analysis, and neural network training are increasingly adopted across industries, enhancing overall system efficiency and AI model accuracy within data centers.
- Component
- Processors: Central Processing Units (CPUs) and Graphics Processing Units (GPUs) designed for AI accelerate processing speeds and optimize machine learning algorithms, making them integral to AI server configurations.
- Memory & Storage: High-capacity memory modules and fast storage solutions are essential for handling large datasets and ensuring rapid data access, directly impacting the AI server performances in AI training and inference tasks.
- Geography
- United States: As the largest AI market within North America, the U.S. hosts numerous data centers, tech giants, and research institutions, driving significant AI server adoption to support innovations in cloud computing and AI analytics.
- Canada: Known for its expanding AI research community and data privacy regulations, Canada is witnessing increased deployment of AI servers, especially in sectors such as healthcare, finance, and government services.
- Mexico: Mexico's growing digital infrastructure and manufacturing sectors are gradually adopting AI servers to optimize logistics, automation, and industrial processes, contributing to regional market expansion.
- Rest of North America: This includes the Caribbean and other smaller markets where AI infrastructure investment is emerging, driven by international tech investments and technological modernization efforts.
Competitive Intelligence
The North America Artificial Intelligence Server Market exhibits high competition characterized by a mix of global technology giants and specialized startups. Dominance is concentrated among a few key players, such as NVIDIA, Hewlett Packard Enterprise, and Dell Technologies, which hold significant market shares through aggressive innovation and strategic partnerships. These companies focus on product differentiation via enhanced computational power, energy efficiency, and AI-specific hardware optimizations. Recent strategies include expanding product portfolios tailored for data centers and cloud environments, along with strategic acquisitions to augment technological capabilities and geographical reach. Collaborations with cloud service providers and enterprise clients are prevalent, facilitating tailored AI solutions and boosting market penetration. Substantial R&D investments underpin ongoing innovation, enabling the development of next-generation AI servers equipped with advanced processing units and adaptive architectures. Competitive differentiation largely hinges on proprietary hardware design, integrated software ecosystems, and comprehensive service offerings, which collectively enhance performance and lower total cost of ownership. Continuous innovation and strategic positioning are vital for maintaining competitive advantage in this rapidly evolving landscape.
Leading Company Profiles
The North America Artificial Intelligence Server Market is driven by several innovative companies focused on advancing AI infrastructure through cutting-edge hardware solutions and strategic collaborations to fortify their market positions.
NVIDIA specializes in AI-optimized GPU and server solutions, emphasizing high-performance computing for enterprise and cloud data centers, with strategic priorities centered around expanding AI-powered data infrastructure.
Dell offers a comprehensive portfolio of AI-ready servers and integrated solutions designed to support scalable AI workloads, making it a leader in enterprise AI deployment with a focus on interoperability and edge computing.
HPE provides AI-centric server architectures tailored for data analytics, machine learning, and deep learning, leveraging its HPE GreenLake platform to deliver flexible, scalable infrastructure aligned with cloud-native AI applications.
IBM's AI server solutions are integrated into its broader AI ecosystem, emphasizing hybrid cloud environments and AI optimization, with a strategic focus on enterprise AI solutions for industries like finance and healthcare.
Strategic Business Developments
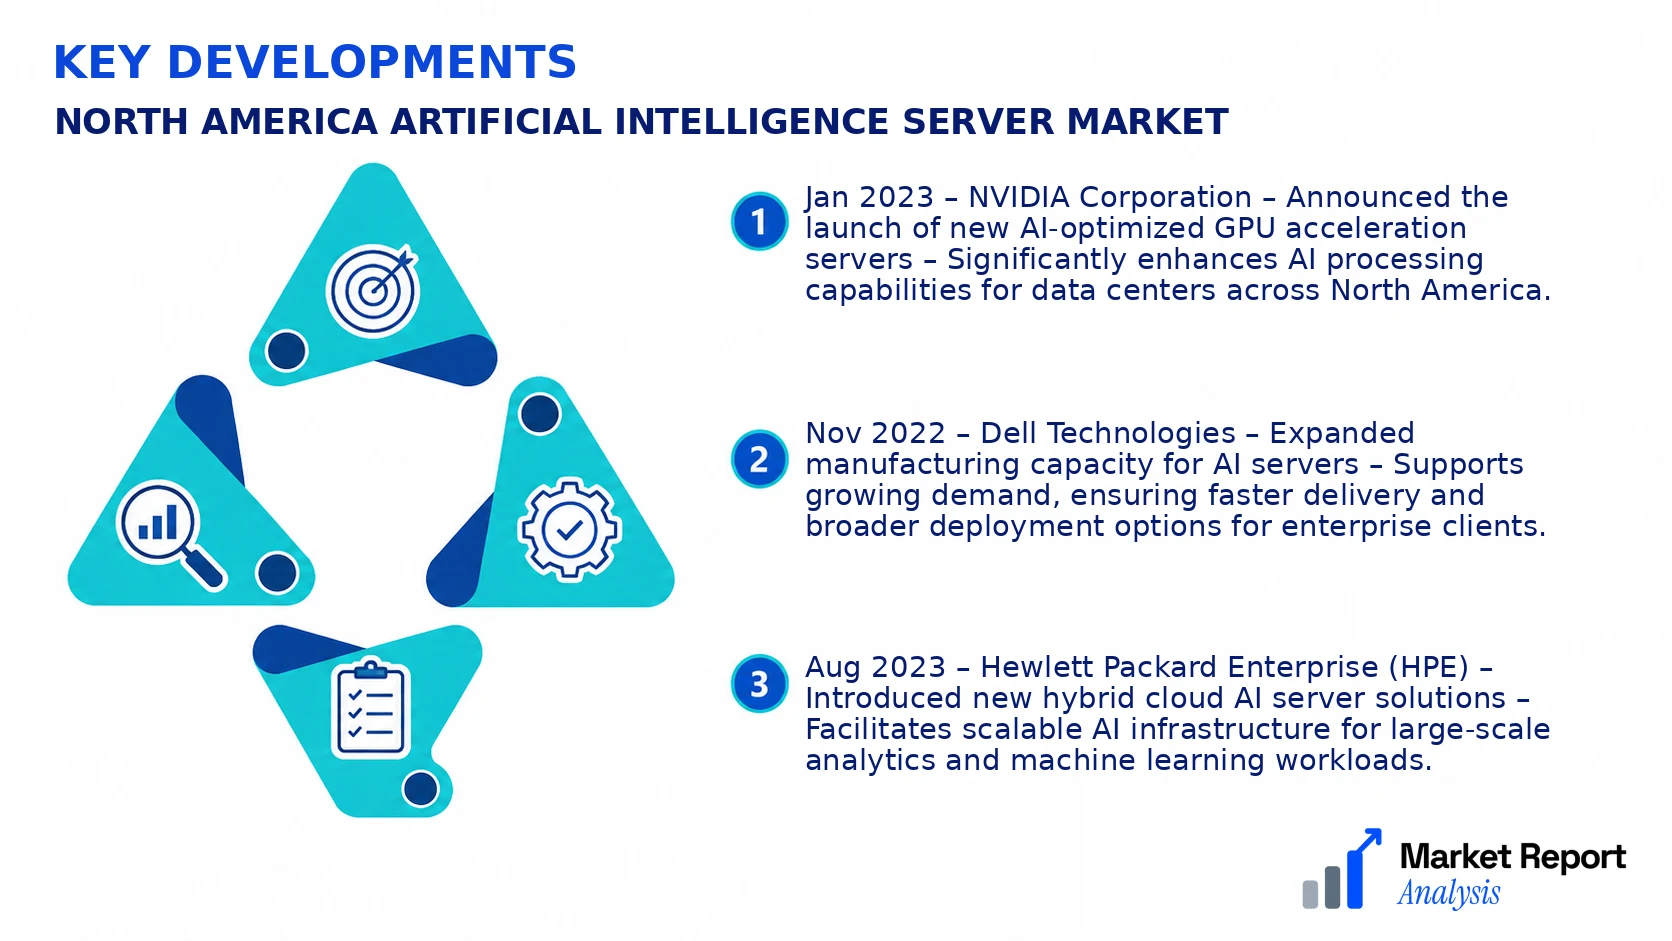
- Jan 2023 – NVIDIA Corporation – Announced the launch of new AI-optimized GPU acceleration servers – Significantly enhances AI processing capabilities for data centers across North America.
- Nov 2022 – Dell Technologies – Expanded manufacturing capacity for AI servers – Supports growing demand, ensuring faster delivery and broader deployment options for enterprise clients.
- Aug 2023 – Hewlett Packard Enterprise (HPE) – Introduced new hybrid cloud AI server solutions – Facilitates scalable AI infrastructure for large-scale analytics and machine learning workloads.
- Mar 2023 – IBM Corporation – Formed a strategic partnership with leading cloud providers to integrate AI servers into hybrid cloud environments – Accelerates enterprise AI adoption.
- Sep 2023 – NVIDIA Corporation – Acquired a startup specializing in AI neural network inferencing hardware – Strengthens its market share in AI server hardware for large-scale deployments.
Frequently Asked Questions
What is the North America Artificial Intelligence Server Market?
The North America Artificial Intelligence Server Market encompasses the deployment of AI-specific server hardware and infrastructure that support advanced computation, data processing, and machine learning tasks across industries such as healthcare, finance, and automotive within North America.
What is the current market size of North America Artificial Intelligence Server Market?
As of 2026, the market is valued at approximately USD 4.2 Billion, reflecting robust adoption of AI infrastructure, driven by technological innovation and increased investments in AI research and development across various North American industries.
What factors are driving the North America Artificial Intelligence Server Market?
Market growth is propelled by the rising demand for high-performance computing, expanding adoption of AI across enterprise sectors, advancements in server hardware technology, and significant investments by major industry players to enhance AI capabilities and infrastructure.
Which region dominates the North America Artificial Intelligence Server Market?
The United States leads the North American AI server market due to its substantial investment in AI R&D, extensive industry adoption, and presence of leading technology companies, accounting for over 75% of the total market share in 2026.
Which segment is expected to grow the fastest?
The hyperscale data center segment is anticipated to experience the fastest growth, owing to the increasing need for scalable and efficient server solutions to handle massive AI workloads and data processing demands.
Who are the leading companies operating in the North America Artificial Intelligence Server Market?
Major players include Hewlett Packard Enterprise, Dell Technologies, IBM Corporation, and NVIDIA Corporation, all of which are focusing on innovation and strategic partnerships to expand their market presence and product portfolio in AI server solutions.
Analyst Perspective
The North America Artificial Intelligence Server Market exhibits a maturity that signals evolving but competitive landscape dynamics. In the long term, market growth is expected to be driven by ongoing advancements in AI hardware acceleration, edge computing integration, and increased investments in AI-driven data analytics. Commercial opportunities remain robust across data centers, cloud providers, and enterprise sectors, with emerging applications in autonomous systems and smart infrastructure offering attractive expansion prospects. Technology evolution is poised to focus on energy-efficient, high-performance server architectures capable of supporting intensifying AI workloads. Investment priorities should prioritize innovation in hardware design, cybersecurity for AI infrastructures, and strategic alliances among key vendors to accelerate R&D. Regional growth potential remains high in the U.S. and Canada, especially within sectors like healthcare, finance, and telecommunications, while global competition intensifies. Strategic positioning requires balancing innovation, cost management, and market adaptation to sustain market share amid rapid technological changes and competitive pressures.
