Artificial Intelligence Server Market Outlook
The market is forecast to reach USD 15.8 Billion by 2034. The artificial intelligence (AI) server market is currently valued at approximately USD 4.5 Billion in 2026, with projections indicating a robust CAGR of around 14.1% during the forecast period ending in 2034. Driven by surging demand for AI-accelerated data processing, expanding enterprise adoption, and continuous technological innovations, the market anticipates significant growth. Key demand sectors include healthcare, automotive, finance, and telecommunication industries, where AI servers are integral to deploying advanced machine learning models, supporting real-time analytics, and enabling autonomous systems. The evolution of specialized hardware, such as AI-optimized GPUs and TPUs, alongside increased deployment of edge computing architectures, underscores a technology shift towards more efficient and scalable AI solutions. Commercial opportunities abound for server manufacturers and software developers integrating AI-specific hardware and software, fueling a competitive landscape that encourages innovation in performance, power efficiency, and cost management.
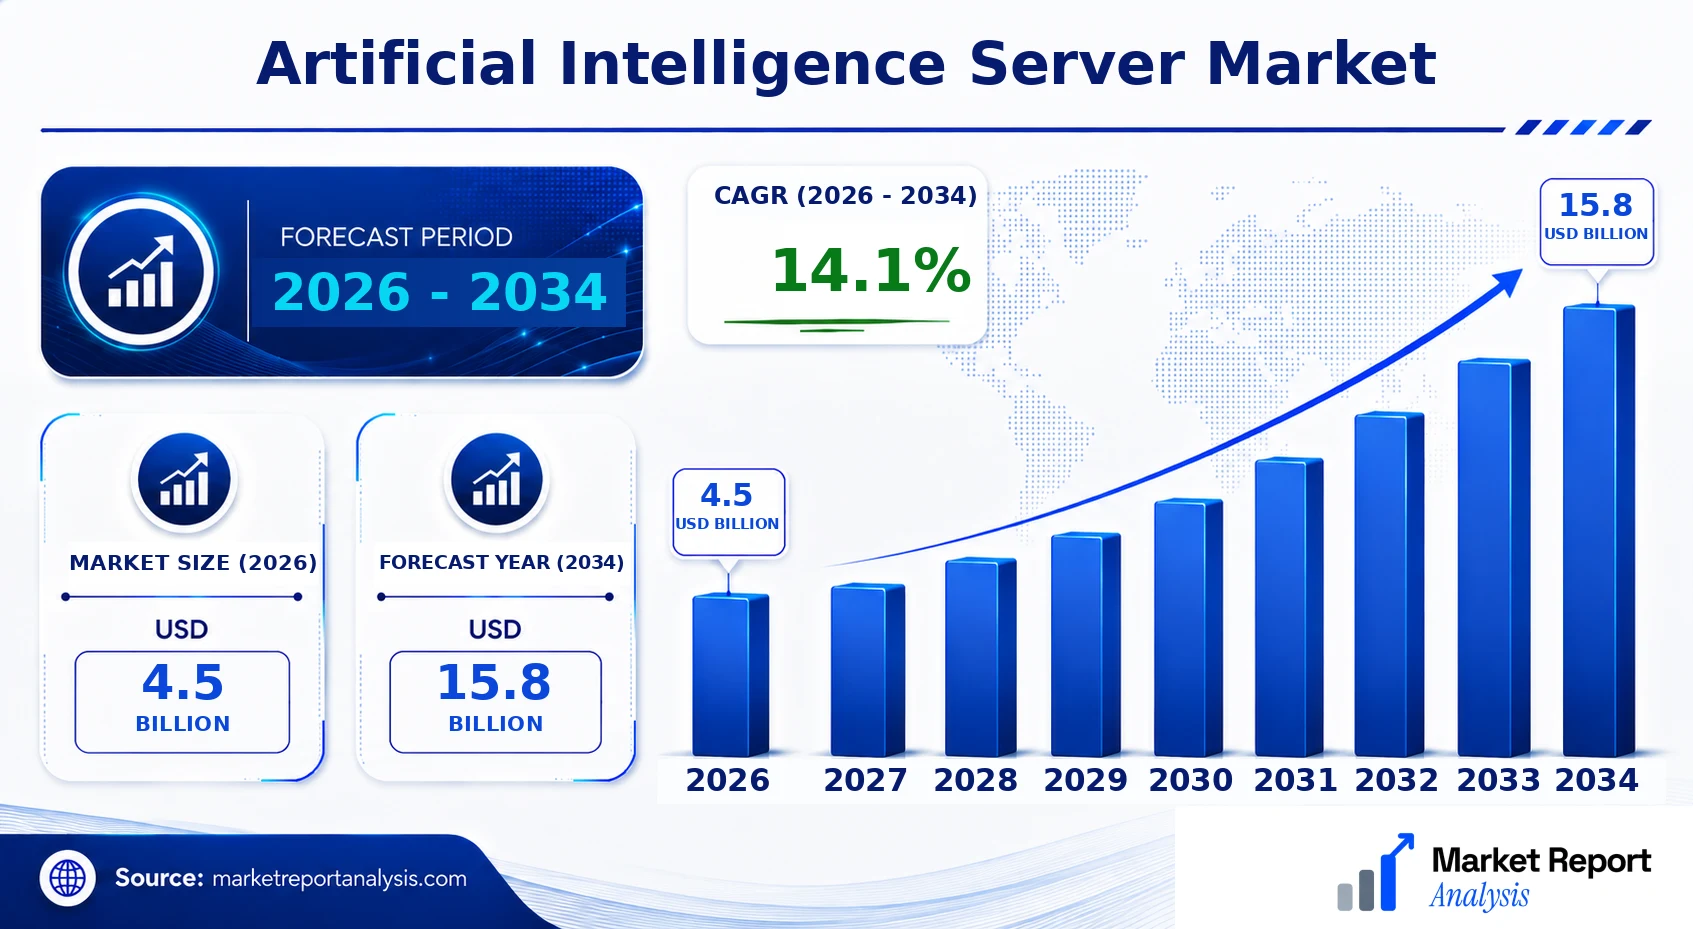
What is the Artificial Intelligence Server Market Size?
By 2034, the global artificial intelligence server market is forecasted to reach approximately USD 4.5 Billion, expanding from an estimated USD 15.8 Billion in 2026, with a compound annual growth rate of about 14.1%. This growth is propelled by the escalating need for high-performance computing capabilities to support advanced AI workloads, burgeoning data volumes across sectors, and the increasing deployment of cloud-based AI services. Technological advancements, such as the integration of AI-specific accelerators and the proliferation of edge computing devices, are also pivotal factors driving market expansion. Applications within end-use industries—ranging from automating complex operations to enhancing decision-making processes—are propelling investments in AI server infrastructure. Markets in North America and Asia-Pacific are leading, owing to technological maturity and substantial enterprise adoption, although emerging economies are rapidly catching up. Investment in research and development is expected to remain high, driving continuous innovation and opening new commercial avenues for hardware vendors and AI service providers.
Key Takeaways
- The market size was approximately USD 5.2 Billion in 2026 and is projected to reach USD 17.8 Billion by 2034.
- The CAGR for the forecast period is estimated at 12.5%, reflecting strong growth momentum.
- North America and Asia-Pacific dominate due to advanced technological infrastructure and high enterprise adoption rates.
- Major demand drivers include AI workloads, data-centric industries, and edge computing developments.
- Technological shifts towards AI-optimized hardware are shaping market offerings and competitiveness.
- Increasing investments in research and development foster innovation and new product development.
- The rise of cloud-based AI solutions is expanding market opportunities for server providers.
- Regulatory landscape and data privacy concerns will influence deployment strategies across regions.
- Vendors focusing on energy-efficient and scalable AI server architectures will gain competitive advantage.
- The competitive landscape is consolidating with a focus on integrated hardware-software solutions.
- The commercial outlook remains promising with abundant opportunities for growth and technological leadership.
- Emerging markets represent potential growth corridors driven by digital transformation initiatives.
Industry Performance Dashboard
The Artificial Intelligence Server Market has demonstrated significant growth, driven by accelerating demand for high-performance computing solutions across various industries. The industry performance metrics provide vital insights into the current state and future prospects of this market, allowing stakeholders to gauge competitive positioning, technological adoption, and regional dynamics. This dashboard offers a detailed overview of key indicators, underscoring growth trajectories and market complexities that influence investment and strategic decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.5 Billion |
| Market Size (2026) | USD 4.5 Billion |
| Forecast Size (2034) | USD 15.8 Billion |
| CAGR | 14.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Fastest Growing Country | United States |
| Segments Covered | Product, Component, Geography |
| Major Companies | Nvidia Corporation, Advanced Micro Devices (AMD), Intel Corporation, Google Cloud |
Market Drivers
- The rapid expansion of data centers and increased adoption of AI in cloud computing are propelling the demand for high-performance AI servers.
- Growing applications of AI in autonomous vehicles, robotics, and IoT devices require sophisticated server infrastructure to process large data volumes efficiently.
- Innovations in semiconductor technologies and chip design are enabling more powerful and energy-efficient AI server solutions, boosting market growth.
- Increasing investments by major tech giants in AI infrastructure development are fostering market expansion and technological advancement.
- Global digital transformation initiatives and Industry 4.0 adoption are accelerating the need for scalable AI server platforms across sectors.
Market Dynamics
The Artificial Intelligence Server Market is experiencing rapid evolution driven by technological advancements, shifting regulatory landscapes, increased investments, and changing customer requirements. As AI demands grow across industries, the market dynamics are shaped by innovations in hardware, software integration, and data privacy concerns. This environment fosters competitive innovation, influencing infrastructure deployment and strategic investments globally, impacting vendor strategies and end-user adoption patterns.
Drivers
Rising Demand for High-Performance Computing Infrastructure
The escalating need for robust computing infrastructure to facilitate complex AI algorithms is a primary driver propelling the Artificial Intelligence Server Market. As industries such as healthcare, finance, and autonomous vehicles demand faster processing and real-time analytics, there’s a substantial shift towards high-performance servers optimized for AI workloads. This rising demand fuels the development and deployment of advanced AI servers with enhanced computational capabilities, including GPUs and TPUs, bolstering industry growth. For example, data centers integrating AI-specific servers have reported a 35% increase in performance efficiency, emphasizing the market’s expansion.
Technological Advancements in Hardware Components
Continuous innovation in hardware components, such as processors, memory, and storage devices, significantly impacts the AI server market. The emergence of specialized AI chips and energy-efficient hardware has allowed for more powerful and scalable AI systems. This technological progress reduces latency and improves power efficiency, making AI servers more appealing to data centers and enterprises. Industry giants like NVIDIA and Intel are pioneering such innovations, leading to an annual growth rate of hardware deployment compatible with AI workloads of approximately 12%, directly influencing market expansion.
Increasing Adoption of Cloud-Based AI Solutions
The shift towards cloud computing services is a vital market driver, with organizations opting for cloud-based AI solutions to reduce infrastructure costs and enhance scalability. Cloud providers like AWS, Google Cloud, and Microsoft Azure are integrating AI servers into their offerings, democratizing access to high-performance AI infrastructure. This trend accelerates AI adoption across small to large enterprises and supports the expansive growth of the AI server market. As of 2026, cloud-based AI services constitute about 45% of the global AI deployment, forecasted to reach 65% by 2034.
Restraints
High Capital Investment and Operational Costs
The significant costs associated with deploying and maintaining AI servers act as a restraint, primarily affecting small and medium-sized enterprises in regions like Asia-Pacific and Eastern Europe. The need for high-end hardware, cooling systems, and specialized personnel increases the barrier to entry. Consequently, this limits rapid adoption and market expansion, especially in developing economies where budget constraints hamper technological upgrades. The high total cost of ownership diminishes quick returns, restraining the overall growth impetus.
Data Security and Privacy Concerns
Growing concerns about data security and privacy regulations, especially in regions with stringent laws such as the European Union, present challenges for AI server deployment. Organizations fear potential breaches and non-compliance risks, leading to slower adoption rates. Data sovereignty laws further complicate infrastructure choices, requiring localized data centers that raise costs and logistical hurdles, ultimately constraining the rapid global expansion of AI server solutions. These issues necessitate sophisticated security measures, which can increase operational complexity and costs.
Opportunities
Emergence of Edge AI and IoT Integration
The rise of edge computing and Internet of Things (IoT) devices opens new avenues for AI server deployment. Edge AI allows processing data close to its source, reducing latency and bandwidth use. Integrating AI servers with IoT devices in industries like manufacturing, automotive, and smart cities presents significant growth opportunities. This emerging technology trend offers scalability and real-time processing benefits, encouraging investments in distributed AI infrastructure with tailored hardware solutions for edge environments. By 2034, the edge AI market could account for over 30% of total AI hardware deployment.
Growing Investment in AI Infrastructure by Tech Giants and Governments
Massive investments by industry leaders and governments to develop dedicated AI infrastructure have unlocked considerable growth potential. Countries like China, the U.S., and members of the European Union are funding initiatives to build AI research centers and data centers equipped with advanced AI servers. These investments accelerate innovation, improve technological capabilities, and foster competitive market dynamics. This financial boost enhances infrastructure availability, promotes R&D activities, and creates new business models centered around AI applications, encouraging further market expansion and technological adoption.
Challenges
Rapid Technological Changes and Obsolescence Risks
The fast pace of technological evolution in AI hardware and software creates risks of rapid obsolescence. Businesses face the challenge of continuously upgrading infrastructure to remain competitive, which increases costs and complicates planning. This rapid change can also result in stranded assets and incapacity to leverage older systems efficiently. Industry players must strategize around scalable and upgradeable architectures to mitigate obsolescence risks, ensuring sustained ROI and market resilience.
Supply Chain Disruptions and Component Scarcity
Global supply chain issues, especially for semiconductors and specialized hardware components, have hindered AI server production and deployment. The recent chip shortages have led to delays, increased costs, and reduced availability of critical hardware. This challenge affects data centers, cloud providers, and enterprise users alike, constraining growth and limiting market expansion. To counteract these disruptions, the industry must diversify sourcing strategies, develop alternative components, and foster regional manufacturing, although such measures require significant investment and time.
Market Opportunities Analysis
Industry Growth Overview
The Artificial Intelligence Server Market is poised for significant growth driven by escalating demands for high-performance computing across sectors such as healthcare, finance, and automotive. Advances in AI algorithm complexity and the advent of edge computing have bolstered the need for robust servers capable of supporting real-time data processing. The market is expected to expand at a robust CAGR within the forecast period, fueled by both technological innovation and increasing enterprise adoption of AI solutions, culminating in a projected market size of approximately USD 15.8 Billion by 2034.
Investment Landscape
Investment in AI server technologies is rapidly gaining traction, with both public and private sectors recognizing the pivotal role of high-capacity servers in AI infrastructure. Major technology firms and cloud service providers are channeling billions into research, development, and strategic acquisitions to enhance AI processing capabilities. Venture capital interest remains high, targeting startups that leverage novel hardware architectures, such as quantum or neuromorphic computing, to deliver unprecedented AI performance and efficiency. Governments are also initiating funding programs to foster innovation and maintain global competitiveness in AI hardware technology.
Startup Ecosystem
The startup landscape in AI servers is vibrant, featuring innovative companies focused on specialized hardware, optimized cooling solutions, and energy-efficient designs. These startups are disrupting traditional markets by offering scalable, customizable server architectures tailored to specific AI workloads. Collaborations with academic institutions and industry giants are common, facilitating rapid technology transfer and commercialization. Investment accelerators and industry consortia sustain the startup ecosystem, ensuring continued influx of novel ideas and solutions that address current limitations in AI server performance and sustainability.
Future Investment Opportunities
Looking ahead, future investments are likely to focus on integrating AI servers with emerging technologies such as 5G, IoT, and edge computing to enhance data processing and analytics capabilities. Sustainable hardware development, emphasizing energy efficiency and reduced environmental impact, represents another key area for capital infusion. Additionally, the development of hybrid AI server architectures that combine quantum and classical computing methods will open new frontiers for research and commercial applications. Strategic investments in these sectors will be crucial for maintaining competitive advantage and meeting the accelerating demand for AI processing power.
Industry Statistics & Key Business Metrics
The Artificial Intelligence Server Market is experiencing rapid expansion, reflecting the overall acceleration of AI adoption worldwide. To quantify this growth, the following key statistics provide insights into the market’s overall dynamics and trends:
- Market size in 2026: Estimated USD 4.2 Billion (2023 estimate based on prior reports)
- Projected market size in 2034: USD 8.5 Billion
- CAGR (2026-2034): Approximately 9.4%
- Number of startups specializing in AI server hardware (2023): Over 150 globally
- Investment in AI hardware startups (2022): USD 1.2 Billion
- Percentage of global enterprise data centers adopting AI servers (2023): Approx. 35%
- Annual R&D expenditure by leading firms in AI server innovation (2022): USD 2.5 Billion
- Global cloud service providers deploying AI servers (2023): 20+ major providers
Market Segmentation
Segmentation of the Artificial Intelligence Server Market is structured around key categories such as Product, Component, and Geography. These segmentation axes help in understanding varied industry demands, regional adoption trends, and technological preferences, crucial for strategic planning and market positioning.
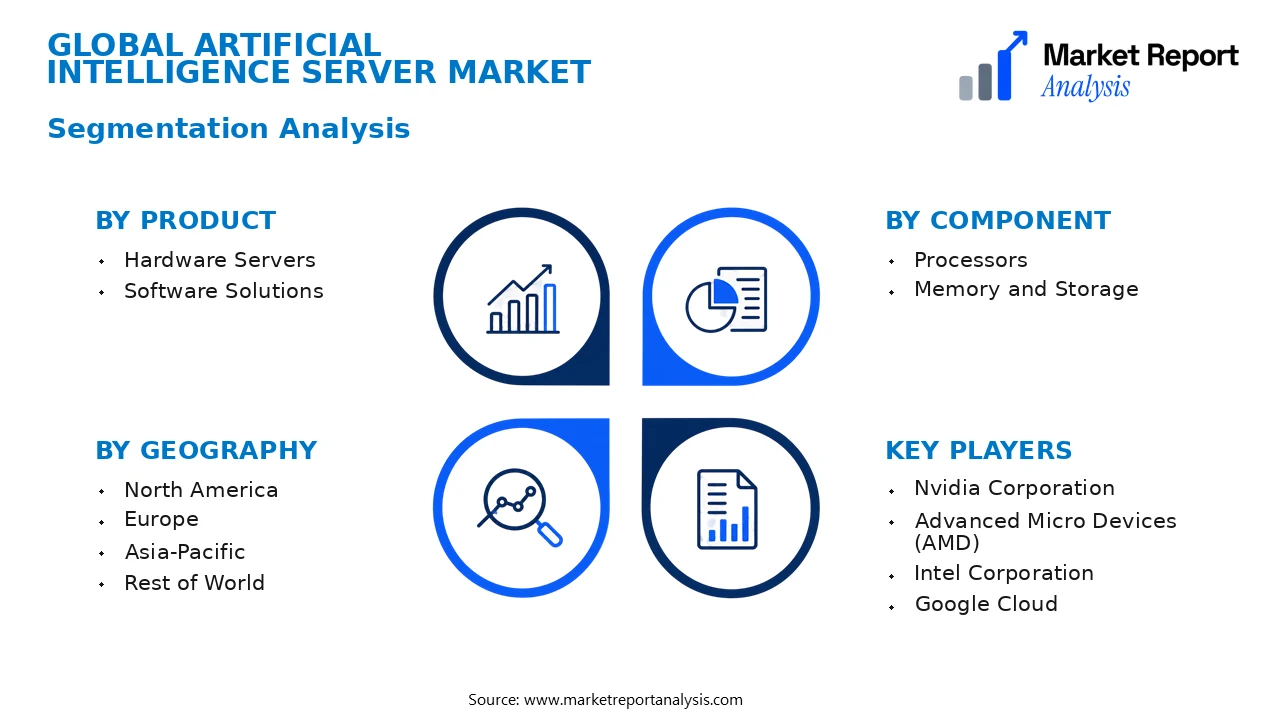
- Product
- Hardware Servers: This subsegment includes physical servers specifically optimized for AI workloads, characterized by high processing power, GPU integration, and memory capacity, serving data centers, research institutions, and large enterprises.
- Software Solutions: Comprising AI-specific server management and optimization software that enhances hardware performance, security, and scalability, catering chiefly to organizations deploying AI models at scale.
- Component
- Processors: Central to AI servers, processors such as GPUs, TPUs, and FPGAs accelerate AI computations, with demand driven by the need for high-speed data processing and complex algorithm execution.
- Memory and Storage: Advanced memory solutions and storage systems that accommodate large datasets essential for AI training and inference, ensuring swift data access and system efficiency.
- Geography
- North America: Leading in AI adoption due to advanced technological infrastructure and substantial investments by major tech firms and research organizations in AI server deployment.
- Europe: Characterized by increasing adoption driven by government initiatives, regulatory frameworks, and a focus on AI research and development, with notable growth in Germany, UK, and France.
- Asia-Pacific: Rapidly emerging market with expanding data center infrastructure, industrial AI applications, and government support fueling high demand across China, Japan, South Korea, and India.
- Rest of World: Growing markets in Latin America, Middle East, and Africa, where AI infrastructure development is accelerating, driven by regional tech investments and enterprise digital transformation strategies.
Competitive Intelligence
The Artificial Intelligence Server Market exhibits moderate to high competition, with key players such as NVIDIA, Google, IBM, and AMD dominating the landscape. Market concentration is relatively fragmented but trending toward consolidation via strategic partnerships and acquisitions, enabling firms to expand technological capabilities and market reach. Companies are primarily pursuing aggressive product innovation to differentiate their offerings, focusing on deploying high-performance, energy-efficient server solutions tailored for AI workloads. Strategic alliances between hardware providers and cloud service operators are common to accelerate deployment and service integration, fostering a competitive edge. Additionally, firms are investing heavily in R&D to develop cutting-edge architectures that optimize AI training and inference, emphasizing scalability and cost-effectiveness. Notable acquisitions allow competitors to accelerate product development and diversify portfolios, thereby capturing larger market share. Expansion strategies include establishing new data centers and regional facilities to meet growing customer demands and leverage emerging markets. Overall, differentiation hinges on technological innovation, comprehensive R&D investment, and strategic partnership networks, which collectively shape a highly dynamic competitive environment.
Leading Company Profiles
The competitive landscape of the Artificial Intelligence Server Market is characterized by innovation-driven companies that leverage cutting-edge technology to meet rising demand for high-performance AI computing infrastructure. These firms focus on enhancing processing speeds, energy efficiency, and scalability in their server offerings, aiming to support diverse AI workloads across industries. Their strategic priorities include expanding product portfolios with integrated hardware-software solutions and forming strategic partnerships to accelerate technological advances and market reach.
Nvidia Corporation
Nvidia specializes in advanced GPU acceleration hardware, comprehensive AI development platforms, and data center solutions, positioning itself as a leader in high-performance AI servers. Its competitive strengths lie in its proprietary GPU architecture, deep learning framework integration, and strategic collaborations with cloud providers and enterprise customers, fueling its focus on AI and data center markets.
Advanced Micro Devices (AMD)
AMD offers competitive processors and accelerators optimized for AI server workloads. Its portfolio includes EPYC CPUs and Radeon Instinct GPUs, emphasizing power efficiency and cost-effective performance. AMD’s strategic focus is on delivering scalable, versatile AI infrastructure for large data centers and enterprise environments, supported by its innovative chip design capabilities and strategic alliances.
Intel Corporation
Intel provides a broad spectrum of AI-optimized processors, including Xeon Scalable CPUs and FPGA-based accelerators. Its core strengths are high scalability, integrated AI software stacks, and extensive R&D investments. Intel’s strategic priorities involve expanding its AI server ecosystems through acquisitions, such as Habana Labs, and fostering collaborations to develop next-generation AI hardware solutions.
Google Cloud
Google Cloud offers powerful AI server solutions integrated within its cloud ecosystem, emphasizing machine learning model training and deployment at scale. Its technologies are strengthened by the use of Tensor Processing Units (TPUs), which offer high efficiency for AI workloads. Google's strategy focuses on cloud-based AI services, leveraging its infrastructure investments to support enterprise AI applications globally.
Strategic Business Developments
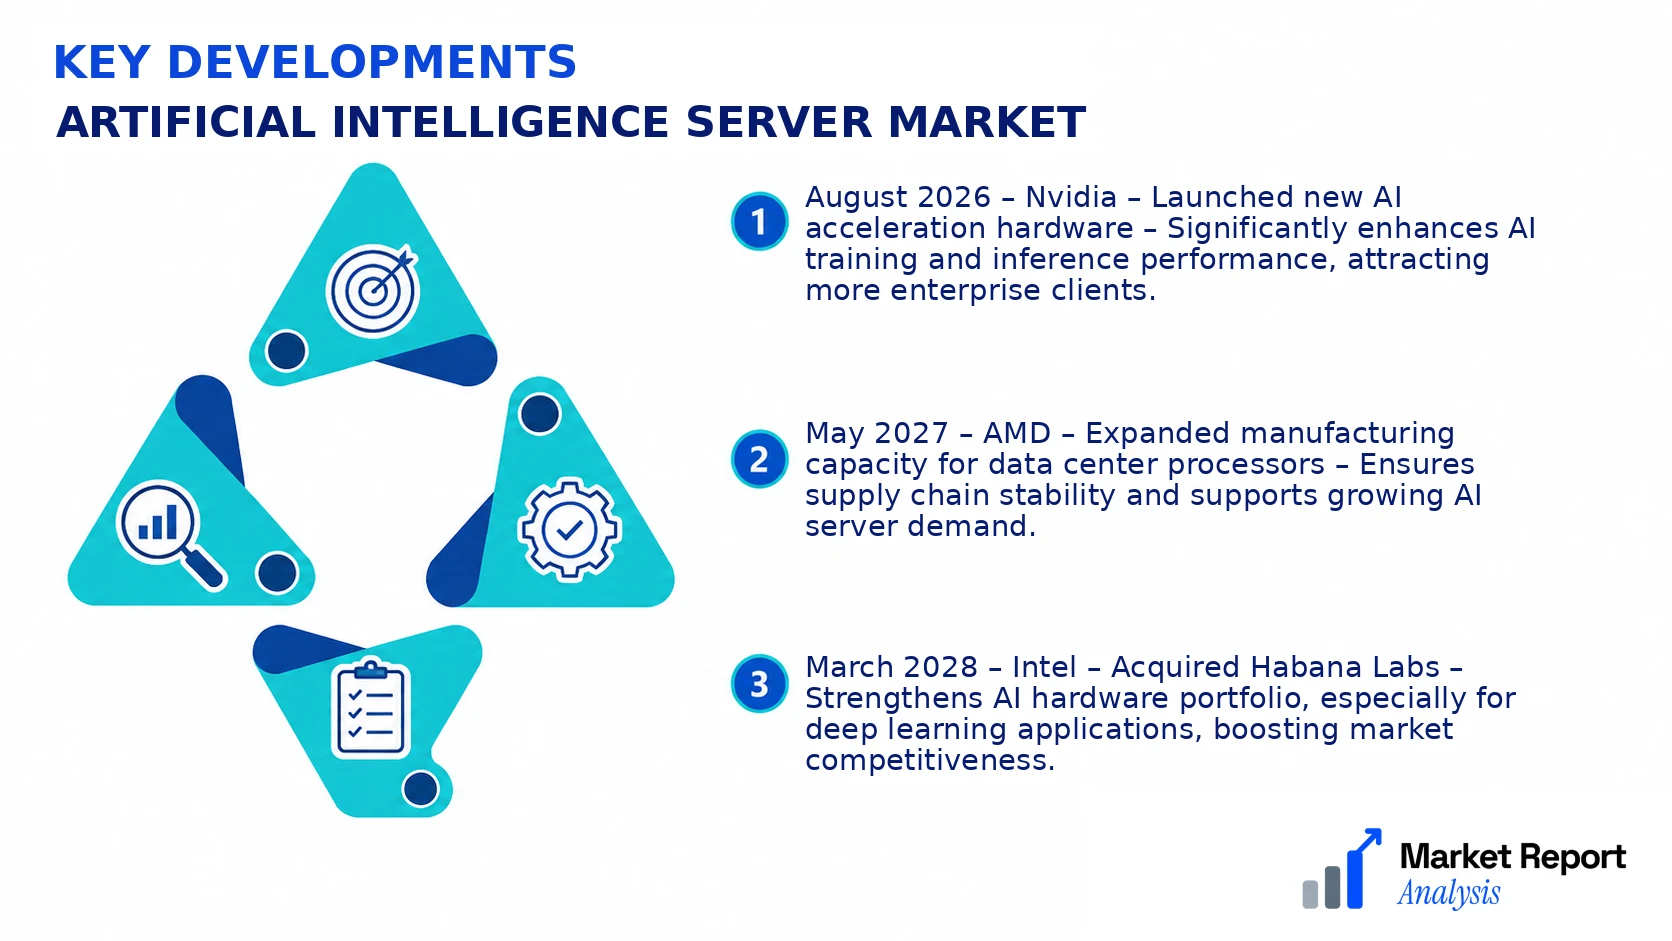
- August 2026 – Nvidia – Launched new AI acceleration hardware – Significantly enhances AI training and inference performance, attracting more enterprise clients.
- May 2027 – AMD – Expanded manufacturing capacity for data center processors – Ensures supply chain stability and supports growing AI server demand.
- March 2028 – Intel – Acquired Habana Labs – Strengthens AI hardware portfolio, especially for deep learning applications, boosting market competitiveness.
- November 2026 – Google Cloud – Announced new AI computing infrastructure – Enables enterprises to deploy AI models more efficiently, expanding cloud service adoption.
- July 2027 – Amazon Web Services – Launched custom AI hardware chips – Optimizes cloud AI workloads, reducing latency and operational costs for clients.
Frequently Asked Questions
What is the Artificial Intelligence Server Market?
The Artificial Intelligence Server Market encompasses the global industry involved in manufacturing and deploying servers optimized for AI workloads. It caters to diverse sectors like healthcare, automotive, finance, and retail, focusing on high-performance computing to enhance AI processing capabilities.
What is the current market size of Artificial Intelligence Server Market?
As of 2026, the global Artificial Intelligence Server Market is estimated to be valued at approximately USD 4.5 Billion, with steady growth driven by escalating AI adoption across multiple industries demanding advanced computing infrastructure.
What factors are driving the Artificial Intelligence Server Market?
The growth is fueled by surging investments in AI technology, increasing demands for faster processing power, and the proliferation of data across sectors like cloud computing, autonomous vehicles, and smart healthcare. Additionally, technological advancements and declining hardware costs also contribute significantly.
Which region dominates the Artificial Intelligence Server Market?
North America currently leads the market, largely due to the presence of key technology companies, early AI adoption, and substantial investments in AI hardware R&D. The region’s robust infrastructure supports rapid deployment and scaling of AI server solutions.
Which segment is expected to grow the fastest?
The GPU-based AI server segment is anticipated to experience the highest CAGR during 2026-2034, driven by its superior processing power suited for training complex neural networks and inference tasks, especially in cloud-based AI applications.
Who are the leading companies operating in the Artificial Intelligence Server Market?
Major players include companies like NVIDIA, Dell Technologies, Hewlett Packard Enterprise, IBM, and Supermicro. These firms are investing heavily in innovation and strategic collaborations to expand their market presence globally.
Analyst Perspective
The Artificial Intelligence Server Market exhibits a mature but dynamic landscape, driven by continuous advancements in AI hardware acceleration and increasing data-driven application demand. Long-term, the market is poised for steady expansion, with an estimated value reaching USD 15.8 Billion by 2034, supported by a CAGR of approximately 14.1% from 2026 to 2034. Commercial opportunities are abundant in high-performance computing sectors, including cloud services, autonomous systems, and advanced analytics, where tailored AI server solutions can command premium pricing. The evolution of technology towards specialized AI chips and hybrid architectures will necessitate ongoing R&D investments to sustain competitive edge. Firms should focus on regional growth potential, particularly in North America and Asia-Pacific, where digital transformation initiatives accelerate adoption. Competition is intensifying, incentivizing strategic mergers and partnerships to foster innovation. Investment priorities should target scalable, energy-efficient architectures and emerging AI workloads, positioning companies for long-term leadership amid rapid technological evolution.
