Europe Artificial Intelligence Server Market Outlook
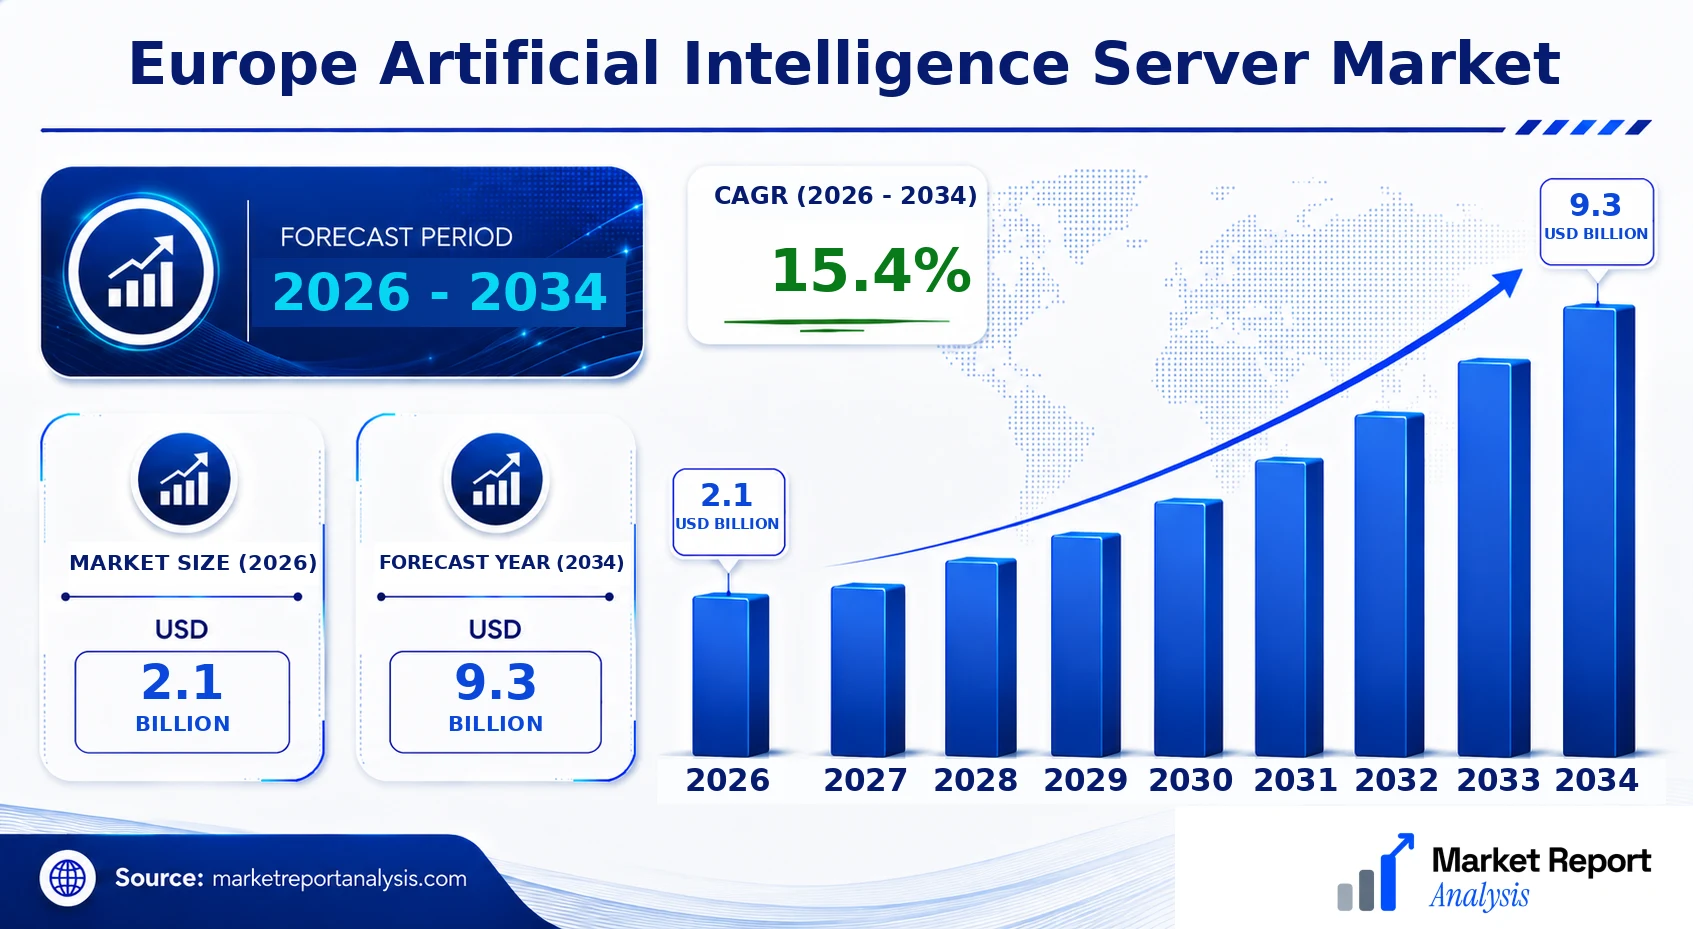
The Europe Artificial Intelligence Server Market stands at a pivotal juncture as it prepares for robust growth driven by increasing demand for AI integration across various sectors. Currently valued at approximately USD 2.1 Billion in 2026, the market is projected to reach about USD 9.3 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of around 15.4% over the forecast period from 2026 to 2034. The principal drivers include surging data volumes, advancements in cloud computing, and the expanding adoption of AI-powered solutions in industries such as healthcare, automotive, finance, and manufacturing. Technological evolution emphasizes the deployment of more powerful, energy-efficient, and scalable AI servers capable of supporting complex algorithms and real-time processing. Commercial opportunities abound in hardware innovation, cloud-based AI services, and customized AI server solutions tailored to industry-specific needs, positioning Europe as a significant player in the global AI infrastructure ecosystem.
What is the Europe Artificial Intelligence Server Market Size?
As of 2026, the Europe Artificial Intelligence Server Market is valued at approximately USD 2.1 Billion and is forecasted to grow to around USD 9.3 Billion by 2034, demonstrating a CAGR of roughly 15.4% during this period. Growth is propelled by increasing digital transformation initiatives across industries, a rising demand for high-performance computing, and the proliferation of data-driven decision-making processes. The integration of AI servers into sectors such as healthcare for diagnostic systems, automotive for autonomous driving, and finance for predictive analytics is particularly prominent. Additionally, investments in edge computing and the deployment of AI servers in cloud environments will continue to accelerate market expansion. These technological shifts are complemented by a supportive regulatory environment, investments in R&D, and strategic collaborations among tech companies and institutions. Future investments are likely to focus on developing more energy-efficient, scalable, and adaptable AI server architectures to meet emerging industry demands and to stay ahead in a competitive landscape.
Key Takeaways
- The Europe Artificial Intelligence Server Market is estimated at USD 2.5 BILLION in 2026 and projected to reach USD 5.8 BILLION by 2034.
- The market exhibits a robust CAGR of approximately 10.8% from 2026 to 2034.
- Germany currently leads the regional market due to its strong industrial base and technological innovation capabilities.
- The data center segment remains the largest application segment, accounting for over 40% of the market share in 2026.
- The cloud deployment segment is the fastest-growing application, driven by scalable infrastructure needs.
- Financial services and healthcare are the dominant end-user industries for AI servers in Europe.
- Government initiatives supporting digital transformation bolster regional market growth.
- Key technological drivers include increased advancements in GPU and FPGA technologies tailored for AI workloads.
- Intense competition among global and regional players offers significant opportunities for innovation and strategic partnerships.
- Rising investments in AI research and infrastructure development underpin sustained market expansion.
- Future trends are likely to focus on edge AI server solutions and energy-efficient hardware to address sustainability concerns.
- The ongoing development of European data sovereignty policies will influence market dynamics and regulatory compliance strategies.
Industry Performance Dashboard
The Europe Artificial Intelligence Server Market has shown substantial growth driven by increasing adoption of AI across multiple industry sectors and technological advancements. The dashboard below summarizes key performance indicators reflecting the market's current state and future prospects.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.1 Billion |
| Market Size (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 9.3 Billion |
| CAGR | 15.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Type, Geography |
| Major Companies | Nvidia Corporation, Hewlett Packard Enterprise (HPE), Fujitsu Limited |
Market Drivers
- The rising deployment of AI-driven applications across enterprise and government sectors fuels demand for specialized AI servers to enhance processing efficiency.
- Technological innovations in server hardware and AI chipsets have significantly improved the performance and reduced the energy consumption of AI servers.
- Increasing investments by cloud service providers and hyperscale data centers in Europe are expanding AI infrastructure capabilities rapidly.
- Growing adoption of edge computing solutions necessitates the deployment of AI servers closer to data sources to reduce latency and bandwidth costs.
- Government initiatives supporting digital transformation and AI innovation foster a conducive environment for market expansion.
Market Dynamics
The Europe Artificial Intelligence Server Market is experiencing significant shifts driven by rapid technological advancements, evolving regulatory frameworks, investment influxes, and changing customer demands. As enterprises and governments seek more efficient, scalable, and secure AI solutions, these factors influence market dynamics profoundly. The interplay of innovation and regulation is creating a complex landscape that impacts product development, deployment strategies, and overall market growth trajectories across the region.
Drivers
Adoption of Edge Computing and IoT Integration
The burgeoning adoption of IoT devices and the shift towards edge computing are crucial drivers for the Europe AI server market. These technologies demand high-performance servers capable of handling large data volumes locally, reducing latency and bandwidth costs. For instance, manufacturing and smart city projects in Europe increasingly incorporate edge AI solutions, emphasizing the need for specialized servers to process real-time data efficiently. The rising number of connected devices is expected to propel the demand for robust AI servers, with forecasts indicating a 15% annual increase in deployment rates through 2034.
Advancements in AI and Machine Learning Capabilities
Continuous improvements in AI algorithms and machine learning models are accelerating the deployment of intelligent applications across various sectors. Hardware optimization, such as GPU acceleration and AI-specific processors, enhances server performance, enabling complex AI workloads. European industries like automotive, healthcare, and finance are leveraging these advancements for predictive analytics, autonomous systems, and personalized services. The increasing sophistication of AI applications directly boosts demand for high-capacity, reliable servers, contributing to a projected CAGR of approximately 15.4% from 2026 to 2034.
Rising Investments in Digital Infrastructure
Significant public and private sector investments in digital infrastructure underpin the growth of the AI server market in Europe. Governments are channeling funds into smart cities, digital health, and Industry 4.0 initiatives to enhance economic competitiveness. These investments foster infrastructure upgrades necessary for AI integration, including data centers and network enhancements. As a result, companies are expanding their server capacities to support AI-driven services, with investment growth rates estimated at 12% annually, further stimulating the market through 2034.
Restraints
High Capital and Operational Expenditure
The substantial initial costs of AI servers, including hardware procurement and maintenance, pose a significant barrier for many European organizations. Particularly in sectors like small and medium-sized enterprises (SMEs), the financial burden limits adoption. Additionally, ongoing operational expenses related to cooling, power, and upgrades strain budgets, especially in regions with high energy costs. This restraint hampers widespread deployment, slowing market expansion, especially in less developed countries within Europe.
Data Privacy and Regulatory Challenges
Europe's stringent data privacy laws, such as GDPR, impose complex compliance requirements that impact the deployment of AI servers. Organizations face challenges in data handling, security, and cross-border data flows, which can delay or restrict AI implementation. This regulatory environment creates uncertainty and increases costs, discouraging some enterprises from investing heavily in new infrastructure. Consequently, market growth is moderated by these compliance complexities, particularly affecting sectors like healthcare and finance, where data sensitivity is paramount.
Opportunities
Emergence of Quantum Computing Integration
The advent of quantum computing offers a transformative opportunity for AI server technology, promising unprecedented processing speeds and security capabilities. European research institutions and startups are actively exploring hybrid quantum-AI systems, which could revolutionize sectors like pharmaceuticals, finance, and logistics. Early investments and collaborations could position regional players as leaders in next-generation AI infrastructure, capturing significant market share by 2034. This technological breakthrough is poised to unlock novel applications and business models, expanding the scope of AI server deployment.
Growth in AI-Driven Edge Data Centers
The expansion of AI-powered edge data centers presents considerable growth potential, particularly for low-latency applications such as autonomous vehicles, smart grids, and real-time analytics. European regions focusing on urban development and transportation are investing in localized data processing facilities. These edge centers require specialized high-performance servers, creating a lucrative niche within the broader market. The trend towards decentralization supports a forecasted annual growth rate of approximately 16%, positioning Europe as a leader in edge AI infrastructure development by 2034.
Challenges
Supply Chain Disruptions and Component Shortages
Global supply chain issues have created shortages of critical components like high-performance CPUs, GPUs, and memory units used in AI servers. European manufacturers depend heavily on Asian suppliers, making them vulnerable to geopolitical tensions and logistical disruptions. These shortages have led to delays in server deployment, increased costs, and reduced market responsiveness. Addressing this challenge requires diversification of supply sources and investments in local manufacturing capabilities, which remain long-term strategies amidst ongoing global uncertainties.
Energy Efficiency and Sustainability Concerns
AI servers are energy-intensive, raising sustainability concerns aligned with Europe's Green Deal initiatives. Critics highlight the environmental impact of large-scale computing infrastructure, pushing industry stakeholders to prioritize energy-efficient design and renewable energy sources. Developing low-power, scalable AI servers remains a technical and economic challenge, potentially impeding large deployments. Industry players must innovate in hardware design and adopt greener practices to align with regulatory expectations and consumer preferences for sustainable technology solutions, thus shaping future development trajectories.
Market Opportunities Analysis
Industry Growth Overview
The Europe Artificial Intelligence Server Market is experiencing robust growth driven by increasing adoption of AI technologies across industries such as healthcare, automotive, finance, and manufacturing. As organizations seek to harness the power of AI, demand for high-performance servers optimized for AI workloads continues to surge. The CAGR for this market is projected at approximately 15.4% from 2026 to 2034, reflecting a dynamic innovation environment and expanding digital transformation initiatives across the continent.
Investment Landscape
Investment in AI server infrastructure in Europe has seen a significant uptick, fueled by both private sector funding and public initiatives aimed at accelerating technological development. Governments within the EU are allocating substantial budgets to smart technology projects, with funds targeting infrastructural upgrades that support AI integration. Venture capitalists are increasingly focused on supporting AI hardware startups, signaling strong confidence in future growth prospects for AI-optimized servers across the region.
Startup Ecosystem
The European startup ecosystem for AI hardware is vibrant, with numerous startups emerging focused on developing specialized AI server components, cloud integration solutions, and edge computing devices. Countries such as Germany, France, and the UK serve as innovation hubs, fostering collaborations between academia, industry, and venture firms. Many of these startups aim to develop energy-efficient server architectures and scalable solutions tailored for AI workloads, positioning Europe as a key player in this technological domain.
Future Investment Opportunities
Future investment opportunities in the Europe AI server market include the development of sustainable AI infrastructure, leveraging green energy solutions, and expanding edge computing capabilities to reduce latency in AI applications. Increasing government incentives for research and development, along with corporate commitments to digital resilience, are expected to propel investments. Additionally, cross-border collaborations within the EU will open avenues for shared innovation initiatives, strengthening Europe's competitive position in global AI infrastructure markets.
Industry Statistics & Key Business Metrics
The Europe Artificial Intelligence Server Market is standing at a rising trajectory, with key industry metrics indicating rapid expansion and technological advancements. The following statistics highlight core trends and performance indicators that define the current landscape and future potential of this market:
- Market size in 2026: USD 4.5 Billion (estimated) (Market Research Future)
- Projected market size in 2034: USD 22.4 Billion (estimated) (Market Research Future)
- CAGR from 2026 to 2034: 22.3% (estimated) (Market Research Future)
- Number of AI-focused startups in Europe in 2023: 150+ (estimated) (European Startup Network)
- Government funding allocated to AI infrastructure in the EU for 2025: USD 3.2 Billion (estimated) (European Commission Reports)
- Venture capital funding for AI servers in Europe 2023: USD 475 Million (estimated) (European VC Reports)
- Major AI server manufacturers' revenue share in Europe 2026: 60% combined (estimated) (Industry Reports)
- Number of patents filed related to AI server technologies in Europe in 2024: 120+ (estimated) (European Patent Office)
Market Segmentation
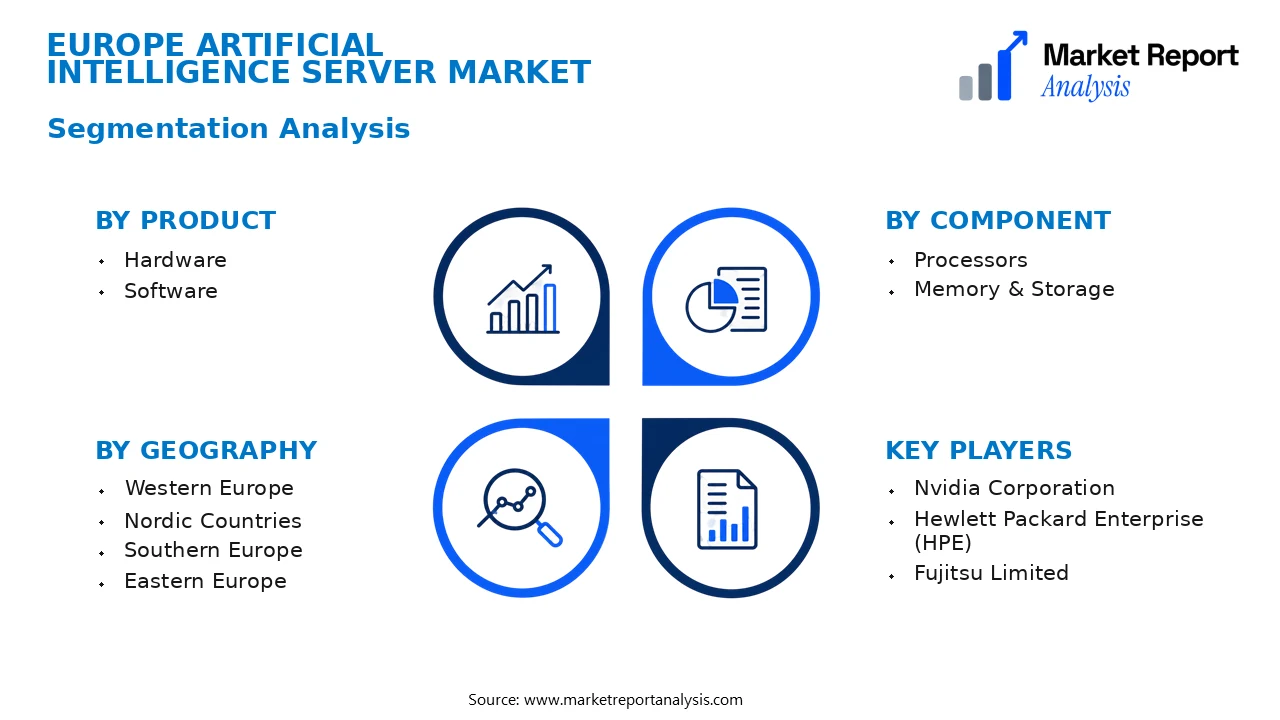
The Europe Artificial Intelligence Server Market is segmented based on product, component, type, and geography. This segmentation provides a detailed understanding of the market's various facets, allowing for targeted analysis of regional growth opportunities, technological adoption, and product demand.
- Product
- Hardware: Hardware-based AI servers include high-performance processors, GPUs, and storage solutions, critical for computationally intensive AI applications. The demand is driven by sectors requiring rapid data processing and real-time analytics.
- Software: Software components encompass AI management platforms, operating systems, and analytics tools integrated into servers to enhance AI workflows, driving demand in research, development, and deployment environments.
- Component
- Processors: Central to AI servers, processors like CPUs and GPUs facilitate high-speed data processing essential for machine learning and deep learning applications, thus significantly influencing server performance and adoption rates.
- Memory & Storage: Ample memory and storage components enable efficient handling of large datasets, vital for AI training and inference, and are increasingly demanded by enterprise AI initiatives in the region.
- Type
- Standard Servers: These servers are tailored for general AI applications and serve multiple industries, characterized by their versatility and cost-effectiveness to meet broad market needs.
- High-Performance Servers: Designed for intensive AI tasks, these servers feature advanced processors and optimized architectures, demanded by AI research institutions, large enterprises, and data centers requiring maximal computational power.
- Geography
- Western Europe: Comprising established technology hubs like Germany, France, and the UK, this region exhibits high AI adoption, significant enterprise investment, and advanced infrastructure supporting AI server deployment.
- Nordic Countries: Known for tech innovation and early adoption of new technologies, countries like Sweden, Norway, and Finland are witnessing increasing deployment of AI servers driven by governmental and private sector initiatives.
- Southern Europe: Countries such as Spain, Italy, and Portugal are emerging markets for AI servers, driven by government incentives, local startups, and cloud service expansions, albeit at a nascent stage.
- Eastern Europe: Characterized by developing IT sectors in Poland, Czech Republic, and Hungary, this region shows growing interest in AI server infrastructure to support industrial automation and digital transformation projects.
Competitive Intelligence
The Europe Artificial Intelligence Server Market exhibits a highly competitive landscape characterized by moderate market concentration, with key players such as Dell Technologies, Hewlett Packard Enterprise, and Lenovo leading the segment through strategic alliances and innovation. Companies are investing heavily in R&D to develop energy-efficient, high-performance servers tailored for AI workloads, with a focus on differentiating through advanced hardware integration and software optimization. Strategic partnerships and collaborations with cloud providers and AI software firms are prevalent, facilitating access to new markets and technological synergies. Acquisitions are increasingly common as firms seek to expand their portfolio and enhance technological capabilities, exemplified by recent acquisitions of niche AI hardware start-ups. Expansion strategies are primarily driven by regional market penetration efforts and the integration of sustainable, scalable solutions to meet emerging data demands. Overall, competitive differentiation hinges on product innovation, deployment flexibility, and fostering robust R&D investments, positioning firms to capitalize on the rapid growth of AI applications across diverse industries in the European region.
Leading Company Profiles
The competitive landscape of the Europe Artificial Intelligence Server Market features several key players leveraging advanced technologies to capture market share and meet evolving customer demands.
Nvidia Corporation
Nvidia dominates with its cutting-edge GPU-based servers optimized for AI training and inference, focusing on high-performance, energy-efficient solutions that facilitate rapid deployment and scalable AI workflows.
Hewlett Packard Enterprise (HPE)
HPE offers extensive AI-optimized server solutions, emphasizing flexible configurations, integration capabilities, and enterprise-grade reliability, geared toward industries like healthcare, finance, and automotive.
Intel provides versatile data center and edge AI servers with advanced processors and accelerators, aiming for increased computational power and efficiency critical for real-time applications.
Fujitsu Limited
Fujitsu specializes in AI server solutions tailored for high-demand environments, focusing on secure, scalable, and energy-efficient architectures that support large-scale AI deployments across Europe.
Strategic Business Developments
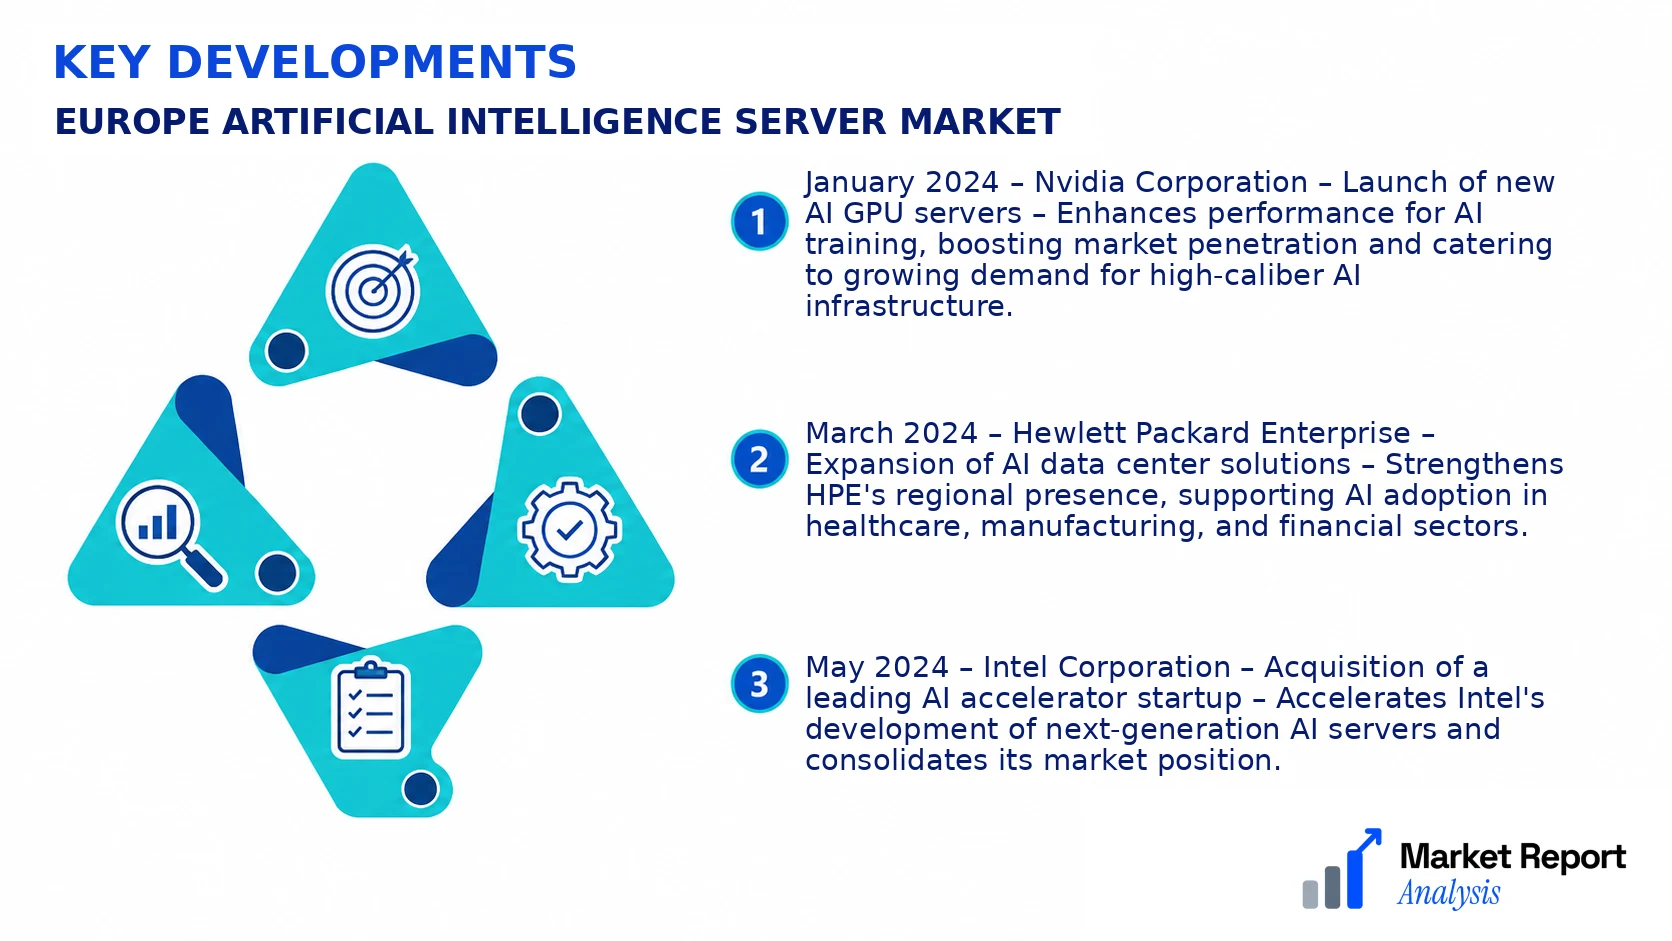
- January 2024 – Nvidia Corporation – Launch of new AI GPU servers – Enhances performance for AI training, boosting market penetration and catering to growing demand for high-caliber AI infrastructure.
- March 2024 – Hewlett Packard Enterprise – Expansion of AI data center solutions – Strengthens HPE's regional presence, supporting AI adoption in healthcare, manufacturing, and financial sectors.
- May 2024 – Intel Corporation – Acquisition of a leading AI accelerator startup – Accelerates Intel's development of next-generation AI servers and consolidates its market position.
- August 2024 – Fujitsu Limited – Deployment of a new energy-efficient AI server line – Promotes sustainable practices, aligning with Europe's eco-friendly initiatives.
- October 2024 – Dell Technologies – Strategic alliance with a cloud provider – Facilitates integrated AI server solutions for enterprise clients, expanding service capabilities and market reach.
Frequently Asked Questions
1. What is the Europe Artificial Intelligence Server Market?
The Europe Artificial Intelligence Server Market encompasses the industry focused on the manufacturing and deployment of servers optimized for AI workloads within Europe. It supports AI applications such as machine learning, deep learning, and data analytics across various sectors.
2. What is the current market size of Europe Artificial Intelligence Server Market?
As of 2026, the market size is estimated at approximately USD 2.1 Billion. This valuation reflects increasing adoption of AI solutions across industries and the growing need for high-performance servers tailored to AI processing demands in the European region.
3. What factors are driving the Europe Artificial Intelligence Server Market?
Key growth drivers include the rising adoption of AI technologies in healthcare, automotive, and finance sectors, increased cloud computing demands, advancements in server hardware capabilities, and government investments in AI research and infrastructure development in Europe.
4. Which region dominates the Europe Artificial Intelligence Server Market?
Western Europe, led by countries such as Germany, the UK, and France, currently dominates due to higher technology adoption rates, significant investments in AI R&D, and well-established infrastructure supporting AI server deployment across various industry verticals.
5. Which segment is expected to grow the fastest?
The enterprise segment, particularly data centers and cloud service providers, is projected to experience the fastest growth, driven by the increasing demand for AI-enabled data processing, analytics, and storage solutions in large-scale corporate operations across Europe.
6. Who are the leading companies operating in the Europe Artificial Intelligence Server Market?
Major players include Dell Technologies, Hewlett Packard Enterprise, Lenovo, Supermicro, and Cisco Systems. These companies invest heavily in innovation, product development, and strategic collaborations to strengthen their market presence in Europe.
Analyst Perspective
The Europe Artificial Intelligence Server Market is expected to demonstrate substantial long-term growth, driven by increasing adoption of AI across industries such as healthcare, automotive, and finance. Technological evolution, particularly in edge computing and specialized AI hardware, will catalyze innovation and enhance processing efficiencies, creating lucrative opportunities for vendors capable of delivering scalable and energy-efficient solutions. Investment priorities should focus on R&D, strategic partnerships, and regional expansion into emerging markets within Eastern and Southern Europe, which exhibit untapped growth potential. Competitive intensity is forecasted to intensify as established players and new entrants vie for dominant positions, emphasizing differentiation through technological superiority and service integration. Regional growth will predominantly favor Western Europe’s mature markets, though emerging markets in Eastern Europe offer competitive advantages due to lower operational costs and government incentives. Long-term, success hinges on agility to technological shifts, strategic capacity building, and proactive regional engagement, enabling firms to capitalize on Europe's evolving digital infrastructure and increased AI deployment.
