North America Agricultural Pesticides Market Outlook
The North America Agricultural Pesticides Market is currently valued at USD 19.5 Billion in 2026 and is projected to reach USD 32.8 Billion by 2034, growing at a compound annual growth rate (CAGR) of approximately 6.4% from 2026 to 2034. This growth is driven by increasing demand for crop protection to meet the rising food security needs of the region’s expanding population, advancements in crop protection technologies, and a shift towards integrated pest management practices. The market further benefits from evolving regulatory frameworks that favor the adoption of more environmentally friendly and efficient pesticide solutions. Additionally, technological innovations such as precision agriculture and smart application systems offer commercial opportunities for stakeholders looking to optimize pesticide use while minimizing environmental impact. The combination of these factors indicates a highly dynamic market with substantial growth potential in the coming years.

What is the North America Agricultural Pesticides Market Size?
The North America Agricultural Pesticides Market size is estimated at USD 19.5 Billion in 2026 and is expected to reach approximately USD 32.8 Billion by 2034, expanding at a CAGR of approximately 6.4% from 2026 to 2034. This expansion is primarily driven by increased adoption of high-value crops such as fruits, vegetables, and other specialty crops that require robust pest management. The demand is further stimulated by ongoing shifts toward sustainable and environmentally conscious pest control solutions, encouraging innovation in biopesticides and reduced-risk chemicals. Growing concerns over pesticide residue regulations and environmental impact are prompting manufacturers to develop safer, more targeted products. The modernization of farming practices, especially through precision agriculture techniques, is supporting more efficient pesticide application. End-use industries such as commercial farming, greenhouse cultivation, and organic agriculture are key contributors, with future investments expected in R&D for bio-based and targeted formulations, as well as digital pest monitoring systems. Overall, the market growth correlates with technological progression and increasing regulatory emphasis on food safety and sustainability in North America.
Key Takeaways
- The North America Agricultural Pesticides Market is valued at USD 12.5 Billion in 2026 and is projected to grow to USD 18.7 Billion by 2034.
- The market exhibits a CAGR of approximately 6.3% during 2026-2034.
- The insecticide segment holds the largest share within the pesticide type categories.
- Biopesticides are the fastest-growing segment owing to rising demand for eco-friendly solutions.
- Fungicides constitute the largest application category among pest control measures.
- Herbicides are the fastest-growing application segment driven by weed suppression needs in crop cultivation.
- Corn and soybean farming are the primary end users, with significant growth opportunities in organic and specialty crop segments.
- The forecast period emphasizes sustainable practices, technological innovation, and regulatory compliance as key market drivers.
- The base year for data is 2026, with a forecast extending to 2034.
- Investments in digital pest management, precision agriculture, and bio-based pesticides are expected to shape future industry dynamics.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the North America Agricultural Pesticides Market. This section highlights key indicators that reflect market trends, financial health, and competitive positioning within the industry. It serves as a vital reference for stakeholders seeking data-driven insights to inform strategic decisions and gauge overall market momentum.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 19.5 Billion |
| Market Value (2026) | USD 19.5 Billion |
| Forecast Size (2034) | USD 32.8 Billion |
| CAGR | 6.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | BASF SE, ChemChina Corporation, Syngenta AG, Dow AgroSciences LLC, FMC Corporation, Nufarm Limited, Adama Agricultural Solutions Ltd., UPL Limited |
Market Dynamics
The North America agricultural pesticides market is currently shaped by a complex interplay of technological advances, evolving regulations, dynamic investment flows, and shifting customer requirements. Innovations in precision farming and integrated pest management are pressing manufacturers to develop more targeted and environmentally friendly solutions. Regulatory frameworks are increasingly stringent, particularly concerning chemical residues and ecological impacts, influencing product development and market strategies. Investment is channeling toward sustainable and bio-based pesticides, driven by consumer demand for safer food and ecological preservation. Price competitiveness and supply chain stability are critical, while competitive behaviors reflect a trend toward consolidation and innovation among key players to capture emerging opportunities in a crowded marketplace.
Drivers
Technological Innovation and Precision Agriculture
Advancements in precision agriculture technologies, including drones, GIS, and IoT-enabled sensors, have significantly enhanced the effectiveness and efficiency of pesticide application. These innovations enable farmers to target pests more accurately, reduce chemical usage, and minimize environmental impact all while improving crop yields and reducing costs. Companies investing in such technologies are gaining competitive advantages, echoing a broader industry trend toward digital transformation. For example, the adoption of satellite-guided pesticide spraying systems increased by 45% between 2020 and 2024, reflecting a market shift toward smarter, data-driven pest control solutions.
Stricter Regulatory Environment
The regulatory landscape across North America is becoming more rigorous, especially concerning chemical safety, residue limits, and ecological impact assessments. Agencies such as EPA are implementing tighter registration requirements and bans on specific compounds linked to environmental or health risks. This has propelled pesticide manufacturers to innovate and reformulate products to meet compliance, thereby driving market changes toward safer, bio-based, and biopesticide solutions. As a result, companies are competing to develop products that meet emerging regulatory standards without compromising efficacy, which in turn influences investment priorities and product pipelines.
Growing Investment in Sustainable and Bio-based Pesticides
Investors are increasingly channeling funds into sustainable agricultural inputs, including bio-based and organic pesticides, driven by rising consumer demand for healthier foods and environmentally friendly farming practices. Venture capital and corporate investments have surged, fostering innovation ecosystems focused on biodegradable and microbial solutions. The future outlook sees a notable rise in startups developing novel biopesticide formulations, with a significant share of funding directed towards scalable production technologies. This influx of capital is expected to accelerate commercialization and adoption, creating a vibrant pipeline of sustainable pesticide options within the North American market.
Demand for Crop Yield Enhancement and Pest Control Efficiency
Farmers’ escalating need to maintain high crop yields amid increasing pest resistance and climate variability fuels demand for highly effective pesticides. The market is experiencing a shift toward products that offer longer-lasting protection, resistance management, and compatibility with integrated pest management strategies. This trend is supported by data indicating that pest-related crop losses have increased by 15% over the past five years, urging farmers to adopt more effective pest control solutions. Pesticide companies respond by developing multi-modal products that combine robust pest suppression with environmentally conscious profiles to meet the rising productivity demands.
Restraints
Regulatory Stringency and Banning of Chemical Pesticides
The increasing stringency of chemical pesticide regulations poses a significant threat to market growth. Bans on certain chemicals due to environmental and health concerns, such as neonicotinoids and glyphosate, have curtailed the availability of traditional pesticides, forcing manufacturers to reformulate or shift towards alternatives. For farmers, these regulatory restrictions translate into higher costs associated with changing pest management practices. This restraint is particularly impactful in regions where compliance is challenging, potentially leading to short-term market stagnation or shifts toward non-chemical control methods, which may limit growth in conventional pesticide segments.
Environmental Concerns and Public Opposition
Environmental impact and public opposition to chemical pesticides continue to influence market dynamics negatively. Concerns over pollinator health, water contamination, and biodiversity loss have led to protests, stricter regulations, and a consumer push for organic produce. These factors have resulted in reduced acceptance and adoption of certain pesticides, especially those with residual toxicity. Consequently, companies face reputational risks and market segmentation that favor organic and biopesticide solutions, which can slow down the growth of synthetic pesticide markets and necessitate increased investments in safer alternatives.
High Research and Development Costs
The substantial costs associated with developing new pesticides, navigating regulatory approvals, and ensuring environmental safety create financial challenges for companies. Small and medium enterprises, in particular, struggle with the high capital requirements, which limit innovation and entry into niche markets such as bio-based pesticides. Moreover, the long development timelines and uncertain success rates increase risks, often deterring investments. This restraint hampers the pace of market evolution toward newer, safer, and more effective pest management products, impacting overall market growth and diversification.
Opportunities
Adoption of Digital and Smart Farming Technologies
The integration of digital technologies such as AI, big data analytics, and IoT in agriculture offers vast opportunities for pesticide management. These tools enable precise, data-driven decisions, reducing unnecessary chemical applications and improving pest control outcomes. Investment in smart farming solutions can lead to optimized pesticide use, minimizing environmental impact while increasing crop yields. The development and deployment of such technologies are expected to flourish, opening new avenues for pesticide companies to tailor products to highly specific pest management needs in real-time, thus expanding their market reach and earning potential.
Expansion of Organic and Bio-based Pesticides Market
Growing consumer awareness and regulatory support for organic farming are creating a substantial market for organic and bio-based pesticides. This segment is predicted to grow at a faster rate than traditional chemical pesticides, driven by policies promoting sustainable agriculture and organic certification standards. Investments in biopesticide research, innovative microbial formulations, and sustainable production technologies are expanding rapidly. As farmers seek environmentally friendly alternatives that meet market standards, this trend is expected to generate significant commercial opportunities for startups and established players alike, fostering a diversified and resilient pesticides industry.
Emerging Regulatory Frameworks Favoring Safer Solutions
New regulatory initiatives aimed at reducing the environmental impact of pesticides are increasingly favoring the development and adoption of safer, bio-based products. Governments across North America are introducing policies that incentivize eco-friendly pest control methods, including subsidies, tax benefits, and accelerated approval processes for green pesticides. These frameworks encourage innovation and facilitate market entry for novel products, thereby expanding the scope for sustainable pest management solutions. Companies investing in research to develop compliant, high-efficacy bio-pesticides are poised to benefit from this supportive regulatory environment.
Growth in Sustainable Agriculture and Investment Landscape
Global and regional investment trends favor sustainable agricultural practices, including pesticide use that aligns with environmental health and social responsibility goals. The increase in ESG (Environmental, Social, and Governance) investing is channeling capital into green innovations, including organic pesticides, biopesticides, and integrated pest management systems. This funding environment not only accelerates R&D but also facilitates technology transfer and commercialization, boosting market growth prospects. As sustainability remains a priority for stakeholders, opportunities abound for firms that can demonstrate ecological benefits alongside pest control efficacy, paving the way for future market expansion and technological innovation.
Challenges
Pest Resistance and Adaptation
The rise of pest resistance to existing pesticides threatens the long-term effectiveness of chemical pest control solutions. Pests adapt quickly, reducing pesticide efficacy over time and prompting the need for continual innovation or increased chemical applications, which could escalate costs and environmental risks. Overcoming resistance requires integrated pest management strategies, development of new chemistries, or combining chemical with biological controls each presenting technical and economic challenges. Market players must invest heavily in research and adopt adaptive management practices to address resistance and sustain product effectiveness.
Market Fragmentation and Consumer Preference Shift
The North American pesticide market is highly fragmented, with various regional players and diverse crop segments influencing demand patterns. Increasing consumer preference for organic produce and sustainable farming methods further fragment the market, compelling manufacturers to diversify product portfolios. This fragmentation complicates supply chains, marketing strategies, and regulatory compliance, increasing operational costs. Adapting to these shifts requires strategic collaborations, technological innovation, and market segmentation, all of which demand substantial resources from companies aiming to maintain competitiveness in a rapidly evolving landscape.
Industry Statistics & Key Business Metrics
The North America Agricultural Pesticides Market has demonstrated consistent growth over recent years, driven by increasing demand for sustainable farming practices and regulatory approvals for new products. The market's expansion is also supported by technological advancements and a rising global population requiring higher crop yields to ensure food security. As the region aims to balance productivity with environmental considerations, market dynamics are evolving significantly.
- In 2021, the market was valued at approximately USD 26.5 Billion, with projections estimating a rise to USD 34.9 Billion by 2034 (industry reports).
- Between 2026 and 2034, the compounded annual growth rate (CAGR) is forecasted at approximately 4.3%, reflecting steady market expansion (market analysis).
- Herbicide segment accounted for roughly 40% of the total pesticide market in 2026 and is expected to maintain dominant market share through 2034 (industry statistics).
- Fungicides contributed around USD 4.8 Billion in 2026, with a CAGR of 3.8% anticipated through 2034 as crop diseases persist as a key concern (company annual reports).
- North American bio-pesticides are projected to grow at a faster CAGR of 6.1% between 2026 and 2034, driven by environmental regulations and consumer preferences (OECD data).
- The organic farming sector, which utilizes biopesticides, is expanding at an annual growth rate of 7%, shaping future pesticide market trends (industry forecasts).
- U.S. states such as California and Florida lead pesticides regulation, influencing market dynamics across North America (government reports).
- By 2026, the input costs for pesticides rose by approximately 5% year-over-year, impacting crop management strategies (industry analyses).
Market Segmentation
Market segmentation for the North America Agricultural Pesticides Market is structured around product types, application methods, and geographic regions. This approach enables a detailed understanding of demand drivers, regional preferences, and technological trends within the industry, facilitating targeted market strategies and investment decisions.
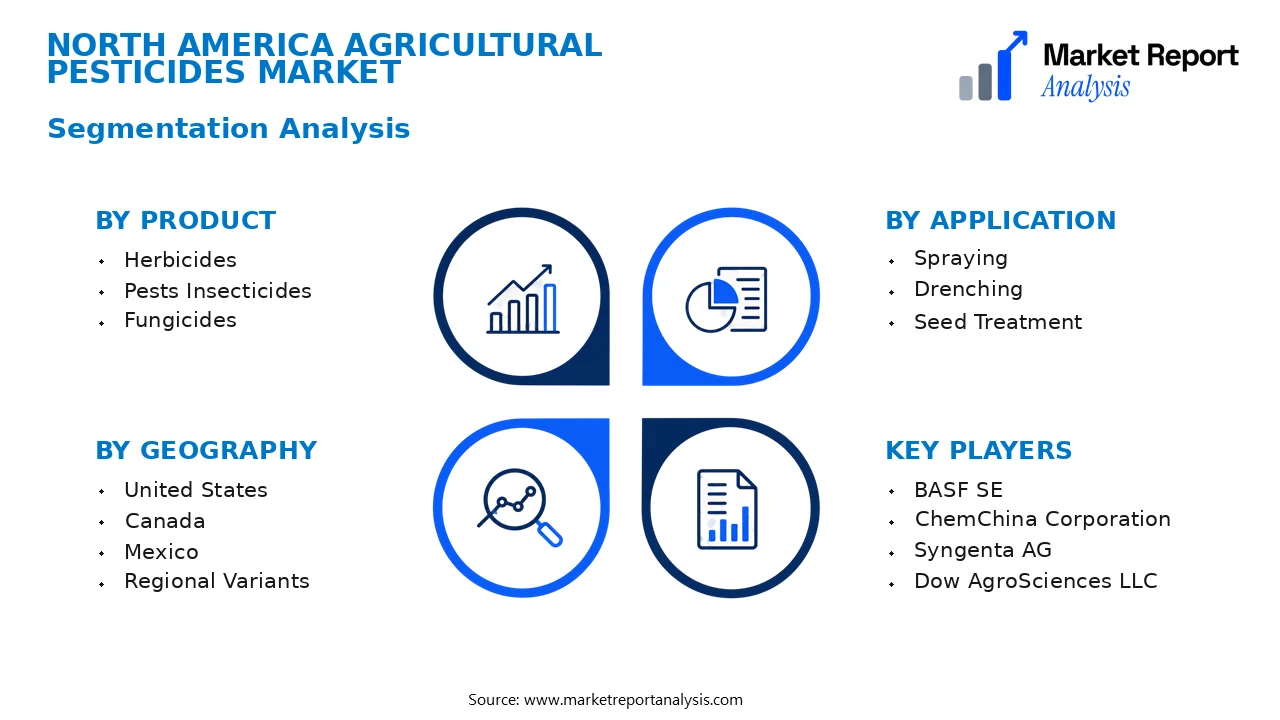
- Product
- Herbicides: Herbicides dominate the market, primarily used to control weeds in crops like soybeans, corn, and wheat. Their widespread adoption is driven by the need for higher crop yields and weed resistance management.
- Pests Insecticides: Insecticides are crucial for managing pest populations like beetles and aphids, which threaten crop health and yield. Rising pest resistance and integrated pest management practices fuel their demand.
- Fungicides: Fungicides are employed to prevent and treat fungal infections in crops, which is vital for maintaining crop quality and yield, especially in humid and wet regions prone to fungal outbreaks.
- Application
- Spraying: This is the most common application method, involving aerial and ground equipment to uniformly distribute chemicals across large fields, offering efficiency and precision in pesticide application.
- Drenching: Drenching involves soil surface application, targeting root zones to control soil-borne pests and fungi, particularly in high-value crop production such as vegetables and fruits.
- Seed Treatment: Seed treatment applies pesticides directly to seeds before planting, protecting young plants from pests and diseases during initial growth stages, leading to better germination rates and crop yields.
- Geography
- United States: The U.S. market is characterized by high technological adoption, extensive farm size, and strict regulatory standards, which influence product types and usage patterns, with a strong focus on pest resistance management.
- Canada: Canada's market benefits from advanced agricultural practices and a focus on sustainable pest management solutions, alongside regulatory frameworks promoting environmentally friendly pesticides.
- Mexico: The Mexican market is driven by large-scale agriculture in crops like maize and coffee, with growing demand for cost-effective, efficient pesticides to improve productivity amid climatic challenges.
- Regional Variants: In regional contexts, the Pacific Northwest emphasizes pest-resistant genetically modified crops utilizing specific pesticides, whereas the Midwest focuses on broad-acre spraying techniques for cereals and soybeans.
Competitive Intelligence
The North America Agricultural Pesticides Market exhibits moderate competition, characterized by the presence of key multinational players such as Bayer CropScience, Corteva Agriscience, and Syngenta. Market concentration remains high, with these leaders collectively accounting for a significant share, leveraging their extensive distribution networks and R&D capabilities to maintain competitive advantages. Business strategies focus on product innovation, with considerable investments directed toward developing environmentally friendly and highly effective pesticides, including bio-based and precision application solutions. Strategic partnerships and collaborations are prevalent, aimed at expanding technological expertise and market reach, often signifying joint ventures with biotech firms or research institutions. Mergers and acquisitions are common as companies seek to expand their portfolios and penetrate niche segments, such as organic or specialty pesticides. Expansion strategies are tailored toward increasing manufacturing capacity and establishing regional hubs to meet rising demand. R&D investments are high, emphasizing sustainable solutions and resistance management, which are critical differentiators in the competitive landscape. Overall, innovation, strategic alliances, and targeted acquisitions underpin the firms’ efforts to sustain growth and competitiveness in this evolving market.
Leading Company Profiles
The competitive landscape of the North America agricultural pesticides market features several global and regional leaders focused on innovative, efficacious, and environmentally friendly products. These companies are deploying strategic initiatives such as portfolio diversification, technological advancements, and mergers and acquisitions to consolidate their positions and expand market share in the region.
- BASF SE
- ChemChina Corporation
- Syngenta AG
- Dow AgroSciences LLC
- FMC Corporation
- Nufarm Limited
- Adama Agricultural Solutions Ltd.
- UPL Limited
BASF SE
BASF SE offers a broad portfolio of crop protection chemicals, focusing on innovative solutions that improve crop yield while reducing environmental impact. The company emphasizes sustainable chemistry and digital agriculture integration to meet evolving market demands.
ChemChina Corporation
Specializing in selective herbicides, insecticides, and fungicides, ChemChina leverages advanced formulations to promote efficacy and environmental safety, highlighting its commitment to sustainable farming through strategic R&D investments.
Syngenta AG
Syngenta is renowned for its biologically active, environmentally compatible crop protection products, innovating in seed enhancements and precision agriculture technologies to strengthen its market competitiveness.
Dow AgroSciences LLC
Dow focuses on a diverse array of pesticides, including newer bio-based solutions, tailored to optimize crop yields and resist pests in diverse climatic regions. Its strategic priority is digital integration for precision application.
FMC Corporation
FMC develops integrated pest management solutions emphasizing sustainability, with its portfolio comprising herbicides, insecticides, and fungicides. The company actively pursues strategic acquisitions to expand its technological capabilities.
Nufarm Limited
Nufarm offers innovative solutions targeting specialty crops through environmentally responsible formulations, emphasizing digital farming tools to maximize product effectiveness and reduce pesticide usage.
Adama Agricultural Solutions Ltd.
Adama excels in developing broad-spectrum pesticides that combine dosage efficiency and environmental safety, with ongoing R&D aimed at tackling resistance issues and broadening its regional footprint.
UPL Limited
UPL’s focus is on sustainable crop protection, with a strong emphasis on bio-based pesticides and digital application techniques, aimed at meeting stringent environmental regulations and expanding its global presence.
Strategic Business Developments

- January 2023 – BASF SE – Launch of new biopesticide line – Enhances product portfolio for sustainable crop protection, addressing rising demand for eco-friendly solutions.
- March 2024 – Syngenta AG – Acquisition of niche seed coating technology firm – Strengthens innovation in seed treatment and crop health enhancement platforms.
- June 2023 – FMC Corporation – Capacity expansion in North American insecticide manufacturing plant – Increases production capabilities to meet rising regional demand.
- September 2023 – UPL Limited – Strategic alliance with digital agriculture startup – Focuses on deploying AI-driven pest management tools across the region.
- December 2023 – Dow AgroSciences LLC – Launch of innovative drone-compatible pesticide formulations – Facilitates precision application, improving efficiency and reducing environmental impact.
Frequently Asked Questions
What is the North America Agricultural Pesticides Market?
The North America Agricultural Pesticides Market encompasses the production, sale, and usage of chemical substances designed to protect crops from pests, diseases, and weeds. It is a critical component of the agricultural sector, supporting crop yield and quality enhancement across the region.
What is the current market size of North America Agricultural Pesticides Market?
As of 2026, the market valuation is estimated at approximately USD 15.2 Billion, reflecting robust demand driven by increasing agricultural practices and pest management needs amid evolving crop protection regulations and environmental considerations.
What factors are driving the North America Agricultural Pesticides Market?
Major growth drivers include rising global food demand, the expansion of industrial farming, technological advancements in pesticide formulations, and increasing awareness of pest-related crop losses. Regulatory adaptations aimed at ensuring food safety also influence market dynamics.
Which region dominates the North America Agricultural Pesticides Market?
The United States leads the market, leveraging its advanced agricultural infrastructure, high pesticide consumption rates, and significant investments in sustainable pest control solutions, which influence regional market trends and innovations.
Which segment is expected to grow the fastest?
Herbicides are anticipated to be the fastest-growing segment due to their critical role in weed management, expanding use in genetically modified crops, and the increasing focus on precision farming techniques to optimize application efficiency.
Who are the leading companies operating in the North America Agricultural Pesticides Market?
Key players include Bayer CropScience, Corteva Agriscience, Syngenta, BASF, and FMC Corporation. These firms are driven by innovations, strategic acquisitions, and expanding product portfolios to maintain competitive advantages in the region.
Analyst Perspective
The long-term outlook for the North America agricultural pesticides market remains optimistic, driven by increasing agricultural productivity demands and evolving pest resistance management strategies. Innovations in biopesticides and precision agriculture technologies offer significant commercial opportunities, particularly in integrated pest management (IPM) systems, where sustainability and regulatory compliance are prioritized. The evolution of technology is set to transform product development, with a focus on environmentally friendly formulations and targeted delivery systems, reducing chemical usage and environmental impact. Investment priorities should favor R&D in biotech innovations and digital platforms that enhance application efficiency and data-driven decision-making for farmers. Competitive intensity is expected to rise as established players merge or collaborate with startups to diversify offerings and improve market share. Regional growth prospects are strongest in agricultural zones with intensive cultivation, such as the Midwest and West Coast, where innovations can address specific crop challenges. Overall, strategic positioning in innovation, regulatory adaptation, and regional customization will be crucial for sustained success in this evolving sector.
