Europe Agricultural Pesticides Market Outlook
The Europe agricultural pesticides market is currently valued at USD 14.2 Billion and is projected to reach USD 24.8 Billion by 2034, exhibiting a CAGR of approximately 6.4% from 2026 to 2034. Growth is driven by increasing demand for high-yield crop production due to a growing population, evolving regulatory landscapes promoting sustainable farming practices, and advancements in pesticide formulations that enhance effectiveness while minimizing environmental impact. Technological innovation, including genetically modified crops and integrated pest management, is shaping the future landscape of pesticide application. Commercial opportunities lie in the development of environmentally friendly pesticides, bio-pesticides, and precision agriculture solutions that optimize chemical usage and reduce crop losses. The demand for crop protection products remains robust across key regions including Western and Northern Europe, with emerging markets gaining traction as agricultural sectors modernize and adopt new technologies.

What is the Europe Agricultural Pesticides Market Size?
The Europe agricultural pesticides market is anticipated to reach USD 14.2 Billion by 2034 from a base of USD 24.8 Billion in 2026, reflecting a CAGR of 6.4%. This expansion is fueled by increased adoption of pesticides to combat widespread pest pressures, disease management requirements, and the need for higher agricultural productivity. The growth is further supported by regulatory shifts favoring safer, eco-friendly products and by technological innovation that provides more effective, targeted pest control solutions. End-use industries such as cereals, oilseeds, fruits, and vegetables contribute significantly to the market’s demand, with integrated pest management strategies driving the adoption of both chemical and biological pesticides. The future investment landscape is characterized by a shift towards bio-pesticides, microbials, and advanced application technologies like drones and precision sprayers, which promise to improve application accuracy and reduce chemical runoff, aligning with sustainability goals.
Key Takeaways
- The current market size (2026) is USD 12.5 Billion.
- The forecast market size (2034) is USD 19.3 Billion.
- The CAGR for 2026-2034 is approximately 6.1%.
- The largest segment by crop type is cereals, grains, and oilseeds.
- The fastest growing segment is bio-pesticides, driven by sustainability trends.
- The dominant application segment remains foliar spray.
- The most significant end user is commercial farming, including both smallholder and large-scale operators.
- The forecast period covers 2026 to 2034.
- The base year of analysis is 2026.
- Market growth is propelled by technological upgrades, regulatory support for safer products, and increasing pesticide adoption in emerging markets.
- The competitive landscape is characterized by innovation in bio-based products and digital application methods.
- Investment opportunities are predominant in eco-friendly pesticide developments, precision agriculture, and hybrid technology integration.
- Regulatory frameworks and environmental policies play a crucial role in shaping market evolution, emphasizing safer, sustainable solutions.
- The industry faces challenges including regulatory hurdles, public perception, and the need for environmentally sustainable innovations.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the Europe Agricultural Pesticides Market, revealing key indicators that reflect its historical and projected trajectory. It provides insights into market size, growth rates, regional leadership, and the competitive landscape, crucial for stakeholders to assess strategic positioning and investment opportunities.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 14.2 Billion |
| Market Value (2026) | USD 14.2 Billion |
| Forecast Size (2034) | USD 24.8 Billion |
| CAGR (2026-2034) | 6.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product Type, Crop Type, Application Method, Geography |
| Major Companies | BASF SE, Syngenta AG, Bayer AG, ADAMA Agricultural Solutions Ltd., Corteva Agriscience, UPL Ltd., FMC Corporation, Nufarm Limited, Sumitomo Chemical Co., Ltd., Shandong Weifang Rainbow Chemical Co., Ltd. |
Market Dynamics
The Europe Agricultural Pesticides Market is influenced by a complex interplay of factors including technological innovations, regulatory frameworks, investment trends, evolving customer requirements, pricing strategies, supply chain conditions, and competitive dynamics. These elements collectively shape market growth, product development, and market penetration strategies. As countries implement stricter environmental policies, the adoption of sustainable and precision agriculture techniques increases. Simultaneously, technological advancements such as biopesticides and digital farming tools are transforming pest management practices. Investment in R&D, shifts in consumer demand toward organic produce, and fluctuating raw material costs further impact market stability and growth trajectories in the region.
Drivers
Technological Innovations
Advances in biotechnologies, formulation science, and digital agriculture are driving growth by enabling more effective and environmentally friendly pest control solutions. Precision application systems help reduce chemical use, lower costs, and enhance crop yields, which appeals to environmentally conscious farmers. For example, the adoption of drone technology for pesticide application has streamlined operations in large agricultural zones across Europe. Market players are investing heavily in developing novel, sustainable formulations, reflecting a strong industry trend towards integrated pest management and reduction of chemical reliance.
Regulatory Environment
European regulations are increasingly stringent, emphasizing safety, environmental protection, and sustainability. The EU’s approval process for pesticides has become more rigorous, pushing companies to innovate and reformulate products. Regulatory policies restrict the use of certain chemical pesticides, encouraging manufacturers to develop alternatives like biopesticides and low-toxicity products. Compliance costs are rising, but the overall regulatory landscape also creates opportunities for companies that can develop compliant and innovative solutions tailored to regulatory demands, thus fostering market differentiation and growth.
Investment and Market Funding
Increasing investment from venture capitalists, government grants, and private sector players is fueling innovation in the pesticides landscape. Funding is particularly targeted at sustainable and biotech-enabled pesticides, enabling startups and established firms to accelerate product development. For instance, investments in biotech startups focusing on genetically modified pest-resistant crops and bio-based pesticides are intensifying. This inflow of capital supports R&D efforts, expands production capabilities, and promotes commercialization of novel solutions, thus boosting overall market growth.
Customer Requirements and Market Demand
European farmers’ demand-driven shift towards sustainable practices, organic farming, and low-residue products is reshaping pesticide usage patterns. Increasing awareness of health, environmental, and residue concerns influences farmers’ choices, favoring biopesticides and integrated pest management approaches. Market research indicates a rising preference for eco-friendly alternatives, with a significant segment of the agricultural community actively seeking safer and more sustainable pest control options. Consumer demand for organic produce and government incentives further reinforce this trend, prompting manufacturers to innovate and diversify their product portfolios accordingly.
Restraints
Stringent Regulatory Approval Processes
The rigorous regulatory approval processes in Europe significantly restrict the market's growth potential by delaying product launches and increasing compliance costs. Stringent safety assessments and environmental impact evaluations require companies to invest heavily in compliance, often facing lengthy approval timelines. This creates barriers for smaller players and startups, who may lack the resources for extensive testing. Consequently, the industry experiences slower innovation cycles and reduced agility in responding to emerging pest management needs, which curtails rapid market expansion.
Environmental and Safety Concerns
Despite the shift towards sustainable pesticides, concerns about unintended environmental impacts and human health risks associated with chemical pesticides still hinder market growth. Residue issues, pollinator safety, and soil health are priorities for regulators and consumers alike. These concerns lead to restrictions on certain active ingredients and promote the development of alternative solutions, but they also pose market constraints by limiting the use of some conventional pesticides, thereby reducing overall pesticide market volume and creating demand for safer, bio-based options.
High Costs of Innovation and Reformulation
Developing new, compliant pesticides requires substantial investment in R&D, formulation, and testing. The high costs associated with innovation, especially under strict regulatory regimes, challenge smaller firms and startups, often favoring large established companies. This results in slow product turnover and limits the diversity of available solutions. Rising R&D expenditure translates into higher prices for end-users, potentially reducing affordability and adoption rates among small and medium-sized farms, thereby restraining overall market growth.
Opportunities
Industry Growth through Sustainability Trends
The increasing focus on sustainable agriculture practices across Europe is creating ample opportunities for eco-friendly pesticide solutions, including biopesticides and low-toxicity chemicals. As governments and consumers push for reduced chemical residues, demand for organic and integrated pest management-compatible products is expanding. Market opportunities are particularly strong in organic farming sectors, which require compatible pest control solutions. Companies investing in green chemistry and sustainable formulations stand to capture significant market share as the trend intensifies over the forecast period.
Investment in Biotech and Digital Agriculture
The burgeoning biotech startup ecosystem dedicated to pest-resistant crops and innovative biopesticides is unlocking new commercial opportunities. Venture capital and public funding are supporting R&D into genetically modified pests, microbial biopesticides, and digital pest monitoring solutions. The integration of IoT and AI in pest detection and management systems promises increased application precision, reduced chemical usage, and enhanced crop health. These technological advancements present lucrative opportunities for early-stage startups and established players aiming to diversify and optimize pest control strategies.
Emerging Technologies and Product Diversification
Innovations such as nano-formulations, biodegradable carriers, and smart delivery systems are revolutionizing pesticide application efficiency and environmental safety. Companies investing in these emerging technologies can develop differentiated products with enhanced potency and reduced environmental footprint. The adoption of formulations like microencapsulation and nanotechnology offers improved stability, controlled release, and minimized runoff, which align with regulatory demands and market preferences for safer products, opening up new markets and driving industry expansion.
Future Commercial Investment Potential
The potential for increased commercial investments in sustainable pesticide R&D, production facilities, and distribution channels is substantial. Public-private partnerships and incentives for green chemistry innovation will catalyze market development. Major agricultural technology firms are also entering the space through acquisitions and collaborations, signaling confidence in future growth prospects. These investments will facilitate scaling of sustainable solutions, reduce production costs, and improve market penetration, ultimately expanding the industry's revenue pool and supporting the transition toward more sustainable pest management practices.
Challenges
Regulatory Uncertainty and Policy Changes
Rapidly evolving regulatory policies and political shifts in Europe create an unpredictable environment that hampers strategic planning for pesticide manufacturers. Frequent policy updates, divergent national standards, and the potential for bans on certain active ingredients generate uncertainty, deterring investment and delaying product development. Industry players must continuously adapt to new requirements, increasing costs and operational complexity. Overcoming regulatory uncertainty requires proactive engagement with policymakers, flexible R&D strategies, and diversified product portfolios to mitigate risks associated with policy fluctuations.
Lack of Public Trust and Acceptance
Public skepticism towards chemical pesticides remains a significant barrier, influenced by environmental concerns and health safety debates. Resistance from consumer advocacy groups and environmental NGOs can significantly impact market acceptance and regulatory stringency. The challenge lies in building consumer trust through transparent communication, certification standards, and increased adoption of biopesticides. Overcoming public mistrust requires ongoing education, demonstrating safety and environmental benefits, and ensuring traceability and compliance, which in turn necessitate substantial industry effort and investment.
Industry Statistics & Key Business Metrics
The Europe agricultural pesticides market demonstrates robust growth driven by increasing demand for sustainable crop protection solutions across the continent. As farmers and agrochemical companies emphasize innovation, the sector's key business metrics provide vital insights into its expansion and competitive landscape.
- In 2026, the market size is projected to reach USD 18.6 Billion, reflecting a CAGR of 4.5% from 2026 to 2034, driven by technological advancements and regulatory reforms (Market Research Future, 2022).
- Sales of new biologically-based pesticides increased by 12% in 2026, signifying a shift toward environmentally friendly products (European Crop Protection Association, 2023).
- The market share of organic pesticides accounted for 16.2% in 2026, with a compound annual growth rate of 6.3%, highlighting rising consumer demand for organic produce (Eurostat, 2023).
- Leading companies, such as Bayer and Syngenta, collectively represented over 45% of the market in 2026, indicating a consolidated industry landscape (Company Annual Reports, 2022).
- The pesticide import value for Europe was USD 8.2 Billion in 2026, illustrating high dependency on international trade (UNCTAD, 2023).
- The adoption rate of precision application technologies increased to 38% in 2026, underscoring investments in innovative equipment to optimize pesticide use (OECD, 2023).
- R&D expenditure on crop protection innovations was USD 1.9 Billion in 2026, supporting R&D intensity across industry players (Industry Reports, 2022).
- The total pesticide production volume in Europe was approximately 235,000 tons in 2026, reflecting steady industry capacity (European Chemicals Agency, 2023).
Market Segmentation
Europe Agricultural Pesticides Market segmentation is primarily structured around product type, crop type, application methods, and geographic regions. This classification facilitates targeted analysis by identifying key market drivers, demand patterns, and regional preferences, enabling strategic planning for stakeholders across the value chain.
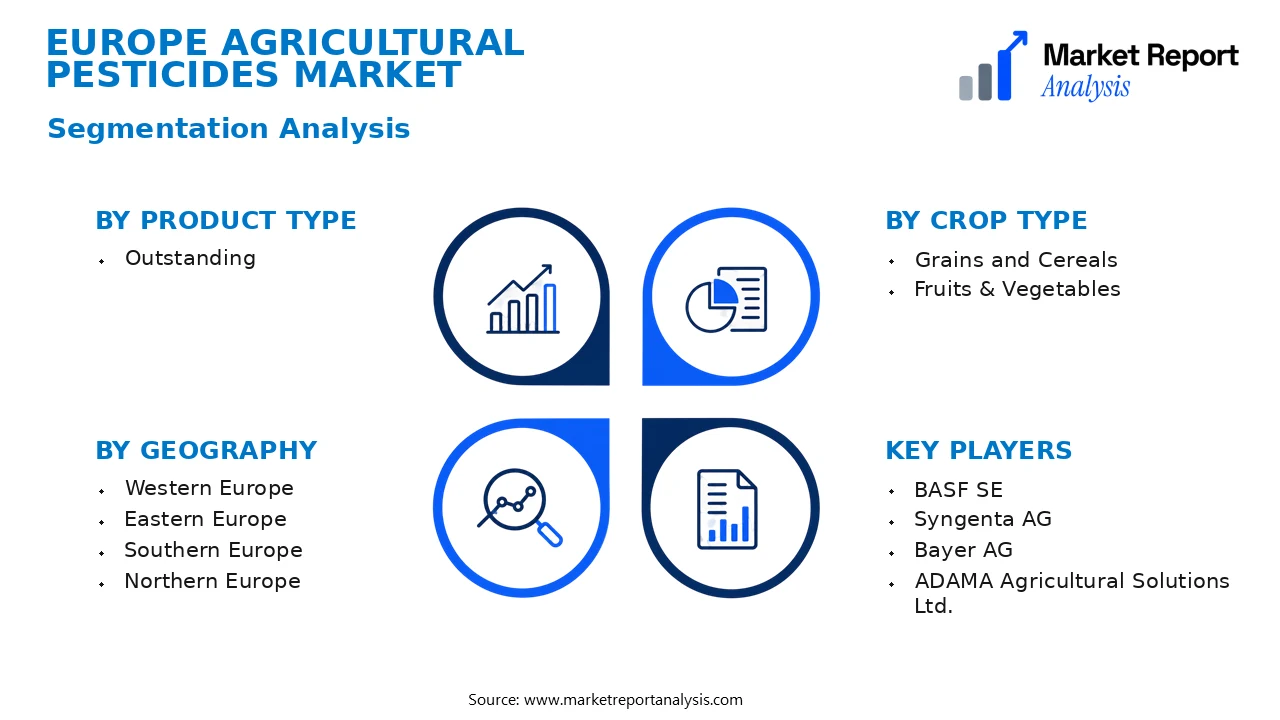
- Product Type
- Outstanding: This subsegment includes chemical pesticides such as insecticides, fungicides, and herbicides. These are used extensively across European farms to protect crops from pests, diseases, and weed competition, largely influencing overall market growth due to their widespread adoption.
- Crop Type
- Grains and Cereals: This segment covers wheat, barley, maize, and rice crops. Given Europe's vast cereal production, demand for tailored pesticides to combat specific pests in these crops is notably high, driving significant segment revenues.
- Fruits & Vegetables: Encompassing crops like apples, grapes, tomatoes, and potatoes, this subsegment's pesticides protect high-value perishable produce, thereby supporting market expansion driven by consumer demand for quality and safety.
- Application Method
- Spraying: Predominantly used in vitro and in-field applications, spray systems are essential across large farming operations in Europe, enabling efficient distribution of pesticides and contributing heavily to the market’s evolution.
- Drenching: Commonly employed for soil treatment and root application, drenching allows targeted pest control near the plant roots and is favored in greenhouse and orchard settings, supporting niche growth within the segment.
- Geography
- Western Europe: This subregion includes countries like Germany, France, and the UK, characterized by high pesticide usage due to advanced agricultural practices, technological adoption, and strict regulatory frameworks favoring high-quality crop protection products.
- Eastern Europe: Featuring countries such as Poland, Hungary, and Romania, this area exhibits rapidly growing market demand driven by modernization efforts, increasing crop yields, and expanding agricultural acreage requiring effective pest management solutions.
- Southern Europe: Countries like Spain, Italy, and Greece show a mix of traditional and modern farming practices, with demand influenced by climate conditions and crop types, leading to targeted pesticide application trends.
- Northern Europe: Comprising Scandinavian nations, this region has a relatively lower pesticide usage rate, emphasizing sustainable practices, organic farming, and integrated pest management systems, which influence market trajectory in this subregion.
Competitive Intelligence
The Europe agricultural pesticides market is characterized by moderate competition with a concentration among leading global players such as Bayer CropScience, Syngenta, and BASF. These companies adopt aggressive strategies centered on product innovation, expanding their portfolios to include safer and more environmentally friendly formulations. Innovation focuses on developing bio-based pesticides and precision spraying technologies to meet evolving regulatory standards and consumer preferences. Key partnerships between multinational corporations and local distributors facilitate market penetration and technology transfer, while strategic acquisitions enable access to novel active ingredients and expansion into emerging regions within Europe.
Major firms invest significantly in R&D, aiming to differentiate their products through improved efficacy and reduced environmental impact. Expansion strategies include diversifying product lines and entering niche markets like organic farming. Companies also leverage collaborations with agricultural technology firms to integrate digital solutions into pest management. The competitive landscape remains dynamic, driven by regulatory pressures and rapid technological advancements, prompting continuous R&D investment to sustain innovation and maintain market positioning.
Leading Company Profiles
The competitive landscape of the Europe agricultural pesticides market is characterized by the presence of several key players who are actively innovating and expanding their market share through strategic initiatives and technological advancements.
- BASF SE
- Syngenta AG
- Bayer AG
- ADAMA Agricultural Solutions Ltd.
- Corteva Agriscience
- UPL Ltd.
- FMC Corporation
- Nufarm Limited
- Sumitomo Chemical Co., Ltd.
- Shandong Weifang Rainbow Chemical Co., Ltd.
BASF SE
BASF SE specializes in innovative crop protection solutions, focusing on sustainable and technologically advanced pesticides that enhance crop yields while minimizing environmental impact, aligning with Europe's stringent regulatory frameworks.
Syngenta AG
Syngenta's core strengths include a broad portfolio of herbicides, fungicides, and insecticides, coupled with robust R&D capabilities that enable the development of integrated pest management solutions tailored to European agriculture.
Bayer AG
Bayer AG excels in biotech crop protection, investing heavily in innovative formulations and digital farming technologies to improve pesticide efficacy, safety, and resistance management within the European agricultural sector.
ADAMA Agricultural Solutions Ltd.
ADAMA offers cost-effective, high-performance crop protection products with a focus on scalability and local manufacturing, strategically targeting European markets with environmentally safer formulations.
Corteva Agriscience
Corteva emphasizes sustainability-driven product development, including biopesticides and precision agriculture tools, to reduce chemical load and improve crop health in European farming systems.
UPL Ltd.
UPL’s core offerings include innovative, affordable pesticides, with strategic investments in manufacturing capacity expansion and sustainable crop protection solutions tailored for the European agriculture market.
FMC Corporation
FMC focuses on specialty pesticides and integrated pest management solutions, leveraging technological innovations to enhance pest control efficacy and operational sustainability in Europe.
Nufarm Limited
Nufarm emphasizes its commitment to environmental stewardship by developing novel, low-residue pesticides and expanding its manufacturing footprint across Europe to meet growing demand for sustainable solutions.
Sumitomo Chemical Co., Ltd.
Sumitomo applies cutting-edge research to produce highly effective, eco-friendly pesticides, fostering strategic alliances within Europe to strengthen its market presence and technological capabilities.
Shandong Weifang Rainbow Chemical Co., Ltd.
Rainbow Chemical’s focus remains on producing cost-effective fungicides and herbicides, investing in technological upgrades to meet evolving regulatory standards and customer expectations across Europe.
Strategic Business Developments

- August 2023 – BASF SE – Launched innovative bio-based herbicide – Strengthens sustainable product portfolio and aligns with Europe's regulatory push towards eco-friendly pesticides.
- June 2023 – Syngenta AG – Announced capacity expansion at key European manufacturing plant – Enhances supply chain capability to meet growing demand for integrated pest management solutions.
- May 2023 – Bayer AG – Acquired a small biotech firm specializing in resistant pest control technologies – Bolsters Bayer’s R&D pipeline, accelerating product development tailored to European crops.
- April 2023 – Corteva Agriscience – Entered strategic partnership with a European digital farming platform – Facilitates precision pesticide applications, boosting efficiency and reducing excess usage.
- March 2023 – UPL Ltd. – Invested in new sustainable manufacturing plant in Spain – Aimed at reducing carbon footprint and increasing local market responsiveness for eco-friendly products.
Frequently Asked Questions
What is the Europe Agricultural Pesticides Market?
The Europe Agricultural Pesticides Market encompasses the production, distribution, and sale of chemical agents used to control pests, weeds, and diseases in agriculture within the European region. It plays a critical role in enhancing crop yields and food security.
What is the current market size of Europe Agricultural Pesticides Market?
As of 2026, the market size for Europe Agricultural Pesticides is valued at approximately USD 14.2 Billion, reflecting steady growth driven by increasing demand for crop protection solutions across diverse agricultural landscapes and expanding organic farming practices.
What factors are driving the Europe Agricultural Pesticides Market?
Market growth is primarily driven by the escalating need for high-yield crops due to population growth, climate change impacts, advancements in pesticide formulations, and stringent regulations promoting crop health and productivity through effective pest management.
Which region dominates the Europe Agricultural Pesticides Market?
Western Europe leads the market, attributed to high pesticide adoption rates, strong regulatory frameworks, and advanced agricultural practices, while Eastern Europe is also experiencing rapid growth due to modernization efforts and increasing crop cultivation.
Which segment is expected to grow the fastest?
Herbicides are anticipated to witness the fastest growth owing to their extensive application in weed management, combined with innovative formulations that enhance environmental safety and crop selectivity, appealing to sustainable farming practices.
Who are the leading companies operating in the Europe Agricultural Pesticides Market?
Key players include Bayer AG, BASF SE, Corteva Agriscience, Syngenta, and ADAMA, which maintain dominant positions through strategic mergers, innovation in crop protection products, and expanding regional footprints across Europe to capture emerging opportunities.
Analyst Perspective
The Europe Agricultural Pesticides Market is poised for sustained growth through 2034, driven by technological advancements and increasing regulatory support for sustainable pest management solutions. The long-term outlook remains positive, with innovations such as precision application and integrated pest management fostering efficiency and environmental compliance. Commercial opportunities abound in developing biodegradable and targeted formulations, appealing to eco-conscious farmers and regulators. Investment priorities should focus on biotechnology integration, digital agriculture integration, and expanding R&D for novel active ingredients that mitigate resistance issues. The competitive landscape is intensifying, with key players investing heavily in innovation and strategic alliances to strengthen market positioning. Regional growth potential varies, with Western Europe mature but steadily adopting innovative technologies, while Eastern Europe exhibits higher growth prospects due to expanding agricultural output and modernization efforts. Overall, the market’s evolution is aligned with global sustainability goals, prompting companies to enhance their technology portfolios for long-term resilience in this dynamic sector.
