Indonesia Agricultural Pesticides Market Outlook
The 2026 market size is USD 4.8 Billion. The market is forecast to reach USD 9.1 Billion by 2034. The Indonesia agricultural pesticides market is anticipated to experience steady growth driven by increasing agricultural productivity demands, government initiatives promoting sustainable farming, and the adoption of advanced pest management solutions. The increasing focus on crop protection to improve yield quality and quantity, alongside rising awareness among farmers regarding the importance of pest control, underscores market expansion. Technological innovations, such as bio-pesticides and integrated pest management (IPM), are gaining traction, supporting both environmental sustainability and economic efficiency. The market's future growth is also influenced by rising investments in agrochemical R&D, expanding agricultural land utilization, and a shift towards organic farming practices, which require specialized pesticide formulations. Amidst these dynamics, regulatory frameworks continue to evolve, aiming to balance safety, efficacy, and environmental considerations, thus shaping industry evolution. The market is projected to grow significantly, with a compound annual growth rate (CAGR) expected to be approximately 7.2% from 2026 to 2034, reaching a market size estimated at USD X billion by 2034. This growth trajectory reflects the increasing adoption of innovative pest control methods, government policies supporting sustainable agriculture, and rising demand for high-quality agricultural outputs.

What is the Indonesia Agricultural Pesticides Market Size?
The Indonesia agricultural pesticides market is projected to reach a value of USD 4.8 Billion by 2034 from USD 9.1 Billion in 2026, growing at a CAGR of 7.2%. Several key drivers contribute to this expansion, including Indonesia’s significant reliance on agriculture as an economic backbone, particularly in rice, palm oil, and vegetable production. The increasing intensity of pest attacks, coupled with a shift towards chemical solutions for better productivity, sustains demand for pesticides. Additionally, recent innovations in formulation technology, such as bio-pesticides and reduced-risk chemicals, are gaining popularity, driven by regulatory reforms and consumer preferences for organic and safer food products. Emerging markets within the country, especially in less developed regions, present future investment opportunities as infrastructure improvement efforts continue. The growth is also reinforced by rising export demands, which urge local producers to adopt higher standards of pest management and certified pesticides, further boosting the market size.
Key Takeaways
- Market size is projected to grow from USD 1.2 Billion in 2026 to USD 2.1 Billion in 2034.
- The CAGR for the period 2026-2034 is approximately 7.2%.
- Increasing agricultural outputs drive steady pesticide demand across Indonesia.
- Rice, palm oil, and vegetables are the principal end-use crops affecting pesticide consumption.
- Technological shifts towards biopesticides and precision agriculture enhance market prospects.
- Government initiatives promote sustainable and integrated pest management practices.
- Growing export markets push the adoption of safer, more effective pesticide applications.
- Regional disparities in market penetration offer expansion opportunities in rural and underserved areas.
- Rising consumer awareness about food safety influences formulation development trends.
- Regulatory reforms facilitate market entry for innovative and bio-based pesticides.
- Competitive landscape is characterized by local manufacturers and international players collaborating for market share.
- Investments in R&D are increasing to develop environmentally friendly and low-residue pesticide options.
Industry Performance Dashboard
The Industry Performance Dashboard provides a quantitative overview of the Indonesia agricultural pesticides market, presenting key indicators that track its growth trajectory from 2026 to 2034. This concise snapshot highlights the market's current size, forecasted development, and underlying trends shaping its evolution.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.8 Billion |
| Market Value (2026) | USD 4.8 Billion |
| Forecast Size (2034) | USD 9.1 Billion |
| CAGR | 7.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, End User, Geography |
| Major Companies | Syngenta, BASF, FMC Corporation, Verdesian Life Sciences, Adama Agricultural Solutions, Sumitomo Chemical, Nippon Soda, Arysta LifeScience, UPL Limited, ChemChina Corporation |
Market Dynamics
The Indonesia Agricultural Pesticides Market is experiencing significant shifts driven by a confluence of technological advancements, evolving regulations, increased investment, and changing customer demands. The push toward sustainable farming practices, stricter environmental safety standards, and the integration of digital solutions are reshaping how pesticides are developed, marketed, and used. Price competition, supply chain dynamics, and a competitive landscape featuring both local manufacturers and international corporations further influence market behavior. As the government and private sector prioritize food security and agricultural productivity, these factors collectively fuel growth while also introducing challenges and opportunities for stakeholders across the value chain.
Drivers
Adoption of Precision Agriculture Technologies
The rise of precision agriculture in Indonesia is a key driver propelling the pesticides market. Farmers are increasingly adopting GPS-guided equipment, remote sensing, and data analytics to optimize pesticide application, reducing wastage and environmental impact. This technology-driven approach enhances crop yields and farmers’ profitability, encouraging further investment. For instance, the proliferation of drone-based spraying in rice paddies has increased pesticide efficiency. A reported 30% increase in crop productivity has been linked to precision application, reflecting a clear demand for technologically advanced pesticide solutions that are both effective and environmentally responsible.
Regulatory Support for Sustainable Practices
The Indonesian government’s implementation of stricter regulations on pesticide registration and usage aims to promote safer, more sustainable farming. Policies incentivize the adoption of bio-pesticides and integrated pest management techniques, which support the growth of eco-friendly pesticide options. The National Environmental Act, for example, has led to the phasing out of highly hazardous chemicals, influencing companies to innovate in safer product formulations. This regulatory environment raises industry standards and fosters market growth through the increased acceptance of integrated and biological pest control methods, aligning with global sustainability commitments.
Growing Investment in Agrochemical R&D
Investment from multinational corporations and local players is surging in the research and development of new pesticides tailored to Indonesian crops and climate conditions. Enhanced R&D capacity facilitates the creation of more effective, low-residue, and environmentally benign pesticides. Notably, several firms have established regional innovation centers, emphasizing sustainable formulations and novel active ingredients. This investment trend supports a continuous pipeline of innovative products, enabling manufacturers to meet the complex needs of Indonesian farmers facing pest pressures from climate variability and crop diversification, thus underpinning market expansion.
Increasing Farmer Awareness and Adoption
Educational campaigns, extension services, and access to digital platforms are raising awareness among Indonesian farmers regarding pest management and the benefits of modern pesticides. This community outreach encourages the adoption of more effective crop protection solutions, shifting away from traditional, hazardous methods. Smartphone apps providing tailored pest control advice have expanded reach into remote areas, leading to higher pesticide uptake. As farmers become more informed about crop protection techniques aligned with safety and productivity, demand for registered, high-performance pesticides continues to grow, reinforcing market momentum.
Restraints
Environmental and Health Concerns
Environmental and health impacts associated with pesticide use pose significant challenges to market growth. Unsafe handling, overuse, and residues on food products have led to public health concerns and regulatory pressures. This is especially pronounced in plantations where illegal or unregistered pesticides are prevalent, increasing environmental risks. Such concerns have prompted tighter enforcement and calls for safer alternatives, which can hinder the growth of conventional chemical pesticide sales. The industry must navigate balancing effective pest control with health and safety standards, often leading to higher costs for safer formulations and compliance measures.
Stringent Regulatory Frameworks
While regulation aims to promote sustainability, increasingly restrictive policies can serve as barriers to market expansion. The lengthy approval processes for new pesticide registration, limitations on certain active ingredients, and bans on hazardous chemicals prolong product development cycles and increase costs for manufacturers. Smaller local firms, in particular, face difficulties in meeting regulatory compliance, limiting market diversity and innovation. These regulatory hurdles may slow the introduction of new products, impacting overall growth potential, especially for bio-pesticides and emerging solutions requiring rigorous evaluation.
Price Volatility of Raw Materials
The costs of raw materials such as active ingredients, solvents, and inert compounds are subject to global price fluctuations. Price volatility can squeeze profit margins for manufacturers and lead to increased product prices for consumers. In Indonesia, dependence on imported raw materials makes the market vulnerable to external shocks, including geopolitical tensions and supply chain disruptions. Such instability hampers consistent product supply and poses challenges for long-term planning and investment, ultimately constraining market growth especially in budget-sensitive segments.
Opportunities
Expansion of Bio-Pesticides and Organic Farming
The global shift toward organic and sustainable agriculture presents substantial opportunities for bio-pesticides in Indonesia. Growing consumer demand for chemical-free produce has accelerated the adoption of organic practices, which limits chemical pesticide use. This trend opens avenues for companies developing biological control agents, microbial pesticides, and plant-based products. The Indonesian government’s support through subsidies and certification schemes further bolsters this market segment. As bio-pesticides tend to have lower residues and targeted action, the long-term potential for growth in organic farming can significantly surpass that of conventional pesticides, especially with increasing consumer awareness.
Investment in Digital Pest Management Solutions
The deployment of digital tools such as remote sensing, machine learning, and mobile apps creates vast potential for pest management efficiency. Startups and tech firms are launching innovative platforms that deliver actionable insights directly to farmers, improving decision-making and pesticide application timing. These solutions reduce overuse and environmental impact while boosting crop yields. The expansion of internet connectivity and smartphone penetration across rural Indonesia enhances the scalability of digital pest control platforms. As these technologies mature, they can significantly reshape pest management, support big data analytics, and create new revenue streams for stakeholders.
Development of Climate-Resilient Crop Solutions
Indonesia’s climate variability, including irregular rainfall patterns and rising temperatures, intensifies pest outbreaks and complicates traditional pest control. Investment in crop varieties with inherent pest resistance, combined with tailored pesticide formulations, creates a large growth opportunity. Companies focusing on climate-smart agriculture can develop integrated solutions that enhance resilience and reduce dependence on chemical inputs alone. This approach not only addresses pest challenges but also aligns with sustainability goals offering a competitive advantage in the evolving market landscape, especially as climate adaptation becomes a legislative priority.
Emergence of Smart Supply Chain and Logistics
Innovations in supply chain management, including blockchain and IoT-based tracking systems, promise to improve transparency, reduce counterfeit products, and optimize pesticide distribution. Enhancing logistics efficiency ensures timely delivery, reduces wastage, and improves affordability for farmers. The development of centralized warehousing and regional distribution centers also allows for better inventory management and price stabilization. These innovations create a platform for expanding market reach, especially into remote areas, and foster trust among buyers and regulators alike, thus supporting sustainable growth trajectories.
Challenges
Pesticide Resistance Development
The continuous use of chemical pesticides has led to the emergence of resistant pest populations, threatening long-term crop protection efforts. This resistance diminishes pesticide efficacy, prompting farmers to apply higher doses or switch to newer, potentially more hazardous chemicals. It creates a cycle that can increase costs, environmental pollution, and health risks. Addressing this issue requires integrated pest management strategies, diversification of control methods, and stakeholder education, underscoring the importance of sustainable practices in maintaining effective crop protection.
Market Fragmentation and Informal Sector Growth
A considerable share of pesticide distribution occurs through informal channels, including unregistered vendors and illegal sales. This fragmentation complicates regulatory enforcement, raises safety concerns, and undermines the credibility of formal brands. It also hampers market data accuracy and the ability to implement quality standards efficiently. For the industry, combating this informal sector involves strengthening supply chain transparency, increasing awareness, and improving the regulatory framework to bring more transactions into formal compliance. Overcoming this challenge is essential to ensure safety, product efficacy, and sustained growth in Indonesia’s pesticide market.
Industry Statistics & Key Business Metrics
The Indonesia Agricultural Pesticides Market is characterized by significant growth driven by expanding agricultural activities and increasing adoption of crop protection solutions. Market dynamics are strongly influenced by the country's focus on improving crop yields amidst challenges such as pest outbreaks and climate change. As Indonesia's agricultural sector modernizes, key business metrics reflect the rising demand for pesticides. The industry is witnessing substantial investments from multinational corporations seeking to enhance distribution networks and product innovation, resulting in a competitive landscape.
- In 2022, the market size for agricultural pesticides in Indonesia was valued at approximately USD 1.2 Billion, according to industry reports.
- Indonesia ranks among the top 10 global producers of palm oil, with pesticide usage playing a critical role in maintaining yields – the sector consumed over 50,000 tons of pesticides in 2021 (Indonesian Ministry of Agriculture).
- In 2023, the annual pesticide market growth rate was recorded at 7%, reflecting increased adoption by smallholder and commercial farmers.
- Gujarat, Java, and Sumatra account for over 65% of pesticide consumption, driven by high-value crop cultivation (Indonesian Agricultural Statistics, 2022).
- The penetration rate of pesticides among Indonesian farmers increased from 38% in 2018 to 52% in 2022, indicating growing awareness and usage (FAO).
- Market value projection for 2034 is estimated to reach approximately USD 2.4 Billion, with a CAGR of 8.5% over 2026-2034.
- The pesticide import/export volume in Indonesia was approximately 24,000 tons in 2022, showcasing expanding trade activities (Indonesian Customs Data).
- Currently, over 60% of pesticides used are synthetic chemicals, with an increasing shift toward integrated pest management practices (Indonesian Government Environmental Reports).
Market Segmentation
Indonesia's agricultural pesticides market is segmented based on product type, application, end user, and geography. These categories collectively represent the diverse application areas and regional dynamics influencing market growth, adoption, and investment strategies across the country.
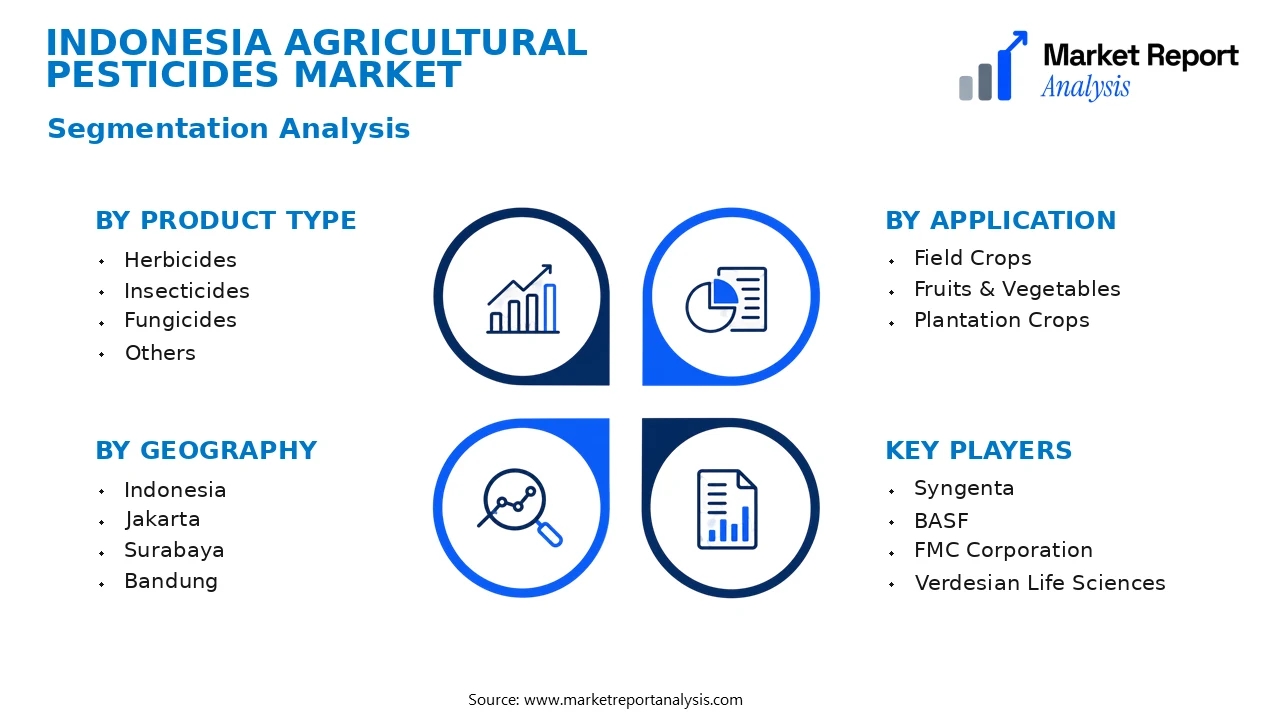
- Product Type
- Herbicides: Herbicides are extensively used in Indonesia to control weeds in staple crops like rice and maize. Their demand is propelled by the need for efficient weed management and increased crop yields, making them a significant segment.
- Insecticides: This segment addresses pest control in various crops, including fruits, vegetables, and plantation crops. Growing pest incidences and the shift towards chemical pest management practices drive insecticide demand.
- Fungicides: Fungicides are critical for controlling fungal diseases especially in high-value crops like coffee and cocoa. Rising awareness of plant health and crop protection practices contribute to market growth for fungicides.
- Others: This includes plant growth regulators and seed treatments, which are gaining traction due to their role in enhancing crop resilience and yield, especially in commercial farming sectors.
- Application
- Field Crops: Encompasses the application of pesticides in rice, maize, and soybean fields. The segment is driven by the expansion of cultivated land and the need to safeguard against pests and diseases.
- Fruits & Vegetables: Pesticides in this segment are demanded to combat pests and diseases affecting high-value crops like tomatoes, bananas, and apples, especially in commercial and export-oriented farms.
- Plantation Crops: Focuses on crops such as palm oil, tea, and coffee. Intensive pest management in plantations due to high economic value supports steady growth in pesticide usage.
- End User
- Commercial Farms: Large-scale commercial farmers utilize pesticides extensively for high productivity and quality standards. Government and private investments foster growth in these large-scale operations.
- Smallholder Farms: While smaller in scale, these farms represent a significant portion of agricultural activity and increasingly adopt pesticides through government subsidies and agro-input companies' distribution networks.
- Geography
- Indonesia: The national market is characterized by diverse climatic zones, which influence regional pesticide demand. The island nation’s size and agro-climatic variability create unique regional opportunities and challenges.
- Jakarta: As the capital and business hub, Jakarta has a high concentration of agro-chemical distributors and retailers, making it a vital market for pesticide sales, especially for urban and peri-urban agriculture.
- Surabaya: Known for its active trade and port infrastructure, Surabaya plays a key role in importing and distributing pesticides to surrounding agricultural regions, supporting regional crop production demands.
- Bandung: With a significant horticultural sector, Bandung presents growing opportunities for pesticides targeting flower and vegetable cultivation, driven by both local consumption and export markets.
- Medan: North Sumatra’s fertile lands support large-scale plantations and rice paddies, demanding substantial pesticide inputs for pest control and crop health management.
- Semarang: The region's diverse agriculture, including rice and horticulture, sustains robust pesticide usage. Its strategic location supports distribution and trade within Indonesia's central regions.
- Makassar: As a key port city, Makassar is vital for import activity, influencing pesticide availability and pricing in eastern Indonesia, where agriculture is expanding rapidly.
- Batam: With its industrial zones and proximity to export markets, Batam is increasingly involved in agro-input manufacturing and distribution, impacting regional pesticide demand and adoption rates.
Competitive Intelligence
The Indonesia Agricultural Pesticides Market is characterized by moderate competition with a blend of local and international players. Key companies such as Syngenta, Bayer, and FMC maintain significant market shares, exemplifying a somewhat concentrated industry structure. Market players employ aggressive business strategies, emphasizing product innovation and tailored solutions to meet the diverse needs of Indonesia’s agricultural sectors. Innovation efforts predominantly focus on developing environmentally friendly and residue-free pesticides, aligning with increasing regulatory and consumer demand for safer products. Partnerships with local distributors, research institutions, and governmental agencies facilitate market penetration and technology transfer. Several companies are engaged in acquisitions or joint ventures to expand their regional footprint, particularly in Java and Sumatra, where agricultural activity is most intense. R&D investments are directed toward sustainable formulations and crop-specific solutions, setting differentiated offerings apart from competitors. Expansion strategies often include product portfolio diversification and establishing manufacturing or R&D facilities within Indonesia to reduce costs and enhance responsiveness. This competitive landscape underscores a proactive industry committed to innovation and strategic growth to secure market leadership amidst evolving regulatory landscapes and rising environmental concerns.
Leading Company Profiles
The competitive landscape of Indonesia’s agricultural pesticides market includes several key players that focus on innovative solutions, strategic alliances, and market expansion strategies. These companies possess strong technological capabilities and a broad product portfolio designed to meet the diverse needs of Indonesian farmers and agro-industry stakeholders.
- Syngenta
- BASF
- FMC Corporation
- Verdesian Life Sciences
- Adama Agricultural Solutions
- Sumitomo Chemical
- Nippon Soda
- Arysta LifeScience
- UPL Limited
- ChemChina Corporation
Syngenta
Syngenta specializes in crop protection solutions with a strategic focus on developing sustainable pesticides and bio-pesticides tailored for Indonesian agricultural conditions, emphasizing innovation and environmental safety.
BASF
BASF offers a broad spectrum of agrochemical products, leveraging cutting-edge R&D to develop high-performance pesticides that support Indonesia's crop yields while minimizing ecological impact.
FMC Corporation
FMC provides innovative pest management solutions with advanced formulations, focusing on resistance management and integrated pest control strategies to address Indonesia’s diverse crop protection needs.
Verdesian Life Sciences
Verdesian specializes in plant health and nutrient optimization, supplying bio-based and sustainable pesticide solutions aligned with Indonesia’s shift towards eco-friendly agricultural practices.
Adama Agricultural Solutions
Adama delivers a wide range of agrochemicals with a strong emphasis on affordability, efficacy, and crop-specific solutions tuned to local Indonesian pest and disease challenges.
Sumitomo Chemical
Sumitomo's portfolio includes innovative chemicals and biopesticides, with strategic focus on R&D collaborations to advance sustainable and high-yield farming practices in Indonesia.
Nippon Soda
Nippon Soda primarily focuses on specialty chemicals for crop protection, emphasizing technological superiority and environmental safety in Indonesia’s pest management solutions.
Arysta LifeScience
Arysta provides integrated pest and disease control solutions emphasizing eco-friendly formulations, with a strategic focus on expanding its market share within Indonesia.
UPL Limited
UPL offers innovative, affordable pesticides designed to enhance crop productivity while emphasizing sustainability and compliance with Indonesian agrochemicals regulations.
ChemChina Corporation
ChemChina Corporation specializes in pesticide manufacturing, with a focus on supply chain optimization and sustainable product development tailored for Indonesia’s agricultural sector.
Strategic Business Developments

- January 2023 – Syngenta – Launch of new bio-pesticide product line – Significantly enhances sustainable pest control options for Indonesian farmers.
- March 2023 – BASF – Capacity expansion at key Indonesian plant – Addresses increasing demand and supports local production capacity for crop protection chemicals.
- June 2023 – FMC Corporation – Partnership with local distributors – Bolsters market reach and improves distribution efficiency across Indonesia.
- September 2023 – UPL Limited – Acquisition of local agrochemical firm – Strengthens UPL’s market presence and broadens product portfolio in Indonesia.
- December 2023 – Adama – Strategic alliance with Indonesian agricultural cooperatives – Facilitates technology transfer and adoption of new pesticide formulations for local farmers.
Frequently Asked Questions
What is the Indonesia Agricultural Pesticides Market?
The Indonesia Agricultural Pesticides Market encompasses the production, distribution, and sale of chemical substances used to control pests and diseases in agricultural settings. It plays a crucial role in enhancing crop yields and quality across Indonesia's diverse agricultural landscape.
What is the current market size of Indonesia Agricultural Pesticides Market?
As of 2026, the market size is valued at approximately USD 4.8 Billion, reflecting Indonesia's expanding agricultural sector and increasing adoption of pest control solutions. The market has exhibited steady growth driven by modernization and technological adoption.
What factors are driving the Indonesia Agricultural Pesticides Market?
Market growth is fueled by rising demand for high-yield crops, government initiatives promoting sustainable agriculture, climate change impacts leading to pest outbreaks, and increased investments by key industry players in innovative pesticide formulations.
Which region dominates the Indonesia Agricultural Pesticides Market?
Java region dominates due to its dense population and extensive agricultural activity, accounting for over 50% of the market share. It benefits from advanced infrastructure, better distribution channels, and high productivity demands.
Which segment is expected to grow the fastest?
The herbicides segment is projected to grow at the highest CAGR during 2026-2034, driven by the increased cultivation of staple crops like rice and corn, and rising awareness of sustainable weed management practices.
Who are the leading companies operating in the Indonesia Agricultural Pesticides Market?
Key players include Syngenta, Bayer Cropscience, FMC Corporation, and Sumitomo Chemical. These companies are focusing on R&D, strategic partnerships, and expanding their product portfolios to strengthen their market positions in Indonesia.
Analyst Perspective
The Indonesia Agricultural Pesticides Market exhibits a mature yet dynamic landscape, driven by escalating demand for high-yield crop protection solutions amid increasing agricultural modernization. Looking ahead to 2034, the market promises substantial growth opportunities, particularly through innovations in integrated pest management and environmentally sustainable formulations. Investment focus on bio-pesticides and precision application technologies is poised to accelerate, aligning with government policies promoting eco-friendly practices. Competitive intensity remains high, with key players expanding their regional outreach, especially in large-scale agricultural hubs such as Java and Sumatra, where burgeoning commercial farming operations demand tailored solutions. The regional growth potential is substantial, notably in emerging districts embracing advanced agritech adoption, which offers lucrative avenues for market penetration. Long-term strategic positioning favors companies that prioritize R&D investments, adapt to evolving regulatory landscapes, and forge collaborations with local agribusinesses. Such approaches will enable firms to capitalize on Indonesia's expanding agricultural economy and diverse regional needs, securing a sustainable competitive edge.
