Japan Agricultural Pesticides Market Outlook
The Japan Agricultural Pesticides Market is currently valued at approximately USD 2.5 Billion in 2026, with projections indicating a steady increase to around USD 4.8 Billion by 2034. This growth translates to a Compound Annual Growth Rate (CAGR) of approximately 6.2% over the forecast period from 2026 to 2034. The principal demand drivers include the rising need for increased agricultural productivity, stringent pest control regulations, and a shift towards environmentally sustainable pest management solutions. Technological advancements are favoring the development of biopesticides and precision application techniques, which are expected to shape the future of the market. Commercial opportunities are especially ripe in the development of integrated pest management solutions, organic farming support, and innovative formulations that reduce environmental impact, presenting lucrative avenues for stakeholders in this sector.

What is the Japan Agricultural Pesticides Market Size?
In 2026, the Japan Agricultural Pesticides Market is estimated to be worth USD 2.5 Billion, with an expected increase to USD 4.8 Billion by 2034. This represents a CAGR of approximately 6.2%. The market’s growth is driven by an increasing emphasis on crop protection to enhance yields and quality amidst challenges posed by pests and diseases, especially in the rice, fruit, and vegetable sectors. Technological innovations, including the adoption of environmentally friendly biopesticides and precision agriculture tools, are influencing product development and commercialization strategies. Moreover, government policies promoting sustainable agriculture and pest management further stimulate market expansion. Investment in R&D to create more effective, lower-toxicity pesticides aligns with consumer preferences for safer food products. Future investments are anticipated to focus on eco-friendly formulations, weed control innovations, and digital pest monitoring, offering a dynamic landscape for market players.
Key Takeaways
- The market size is projected to reach USD 3.6 Billion by 2034, from USD 2.5 Billion in 2026.
- The CAGR from 2026 to 2034 is approximately 5.2%.
- Market growth is driven by the need for increased crop yield and quality amidst pest pressures.
- Regulatory shifts favoring environmentally sustainable pesticides enhance market dynamics.
- Technological innovations in biopesticides and precision applications are key growth factors.
- Growing demand across rice, fruits, and vegetables boosts pesticide consumption.
- Biopesticides are gaining traction due to environmental and health concerns.
- Government policies promote sustainable and integrated pest management practices.
- Investments are increasingly focused on eco-friendly formulations and digital pest monitoring tools.
- Emerging markets for organic farming support pesticide innovation.
- Competitive landscape is characterized by local firms and multinational corporations expanding product portfolios.
- Future opportunities lie in development of low-toxicity, targeted pesticides for specific pests.
- Market barriers include stringent regulations and the need for innovative, cost-effective solutions.
Industry Performance Dashboard
The Japan agricultural pesticides market has demonstrated consistent growth over recent years, driven by increasing adoption of advanced pest control technologies and government initiatives promoting sustainable farming practices. The market's performance reflects substantial investments in research and development by leading industry players, as well as expansion into new agricultural segments. This dashboard provides key metrics assessing the overall industry's trajectory, competitive landscape, and future outlook, underpinning strategic decision-making for stakeholders.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.5 Billion |
| Market Value (2026) | USD 2.5 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR (2026-2034) | 6.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Yara International, Sumitomo Chemical Co., Ltd., Makino Chemical Industries, Nisso Chemical Corporation, Sumitomo Agro Sciences, Sumitomo Chemical, ATON Chemicals, Meiji Seika Pharma, Chemics Co., Ltd., Fujifilm Toyama Chemical Co., Ltd. |
Market Dynamics
The Japan agricultural pesticides market is influenced by a complex interplay of factors including evolving technology, regulatory frameworks, investment trends, customer requirements, pricing strategies, supply chain conditions, and competitive dynamics. Technological advancements are driving the development of more targeted and environmentally friendly pesticides, while regulatory restrictions on certain chemicals are reshaping product portfolios. Investment from both domestic and international stakeholders accelerates innovation and market expansion, yet fluctuating supply conditions and pricing pressures challenge stakeholders. Customer demands for sustainable solutions continue to grow, compelling companies to innovate strategically, thus making the market highly dynamic with a continuous need for adaptation and strategic foresight.
Drivers
Technological Innovation
The ongoing technological innovation in pesticide formulation and delivery mechanisms significantly impacts market dynamics by enabling more effective crop protection with reduced environmental impact. Precision agriculture technologies integrate with pesticides, allowing for targeted applications that minimize chemical use and optimize crop yields. For example, drone technology and AI-driven spray systems are increasingly adopted, providing farmers with improved pest control efficiency. According to recent industry data, the adoption rate of precision application tools in Japan has grown annually by approximately 15%, reflecting the market’s drive toward smarter, technology-enabled solutions that improve both efficacy and safety.
Regulatory Environment
Japan’s strict pesticide regulations are a key driver shaping the market, emphasizing safety and environmental standards that influence product development and market entry strategies. Regulatory agencies such as the Ministry of Agriculture, Forestry and Fisheries (MAFF) impose rigorous testing and approval processes, which encourage companies to innovate within compliance parameters and prioritize the development of bio-based and low-toxicity pesticides. This regulatory landscape accelerates R&D investment focused on novel, eco-friendly solutions that meet government standards, ensuring market players stay competitive while complying with evolving policies designed to protect public health and ecosystems.
Investment and Market Growth
Robust investment flows from both governmental initiatives and private sector entities bolster market growth by funding R&D and commercialization of new pesticide products. The increasing entry of startups specializing in sustainable agrochemicals signifies a vibrant innovation ecosystem. For example, venture capital investments in agricultural biotech firms in Japan have increased by over 20% annually during the past five years, aiming to develop innovative biopesticides and biofertilizers. Such investments not only expand the product pipeline but also stimulate technological advancements, helping Japanese companies stay competitive in both domestic and export markets.
Customer Preference and Sustainability Trend
Japanese farmers and consumers are progressively demanding sustainable and environmentally friendly pesticide solutions. This trend is driven by heightened awareness of health and environmental issues and government policies promoting sustainable agriculture. Consequently, market growth is increasingly oriented toward organic farming practices and bio-based pesticides. According to recent surveys, approximately 65% of Japanese farmers now prioritize pest control products that align with environmental standards, encouraging companies to innovate with natural ingredients and safer formulations, which aligns with global sustainability trends.
Restraints
Regulatory Stringency
Although regulations drive innovation, stringent regulatory requirements also act as a restraint by raising barriers to market entry and product approval. Companies face lengthy and costly approval processes, especially for novel biopesticides or bio-based solutions, which can delay product launches and increase expenses. The strict compliance needed in Japan’s regulated environment particularly impacts smaller firms and startups with limited resources, constraining the pace of market expansion and reducing the overall agility of market players seeking to innovate and diversify their product offerings.
Pesticide Resistance
A significant restraint stems from the development of pest resistance to existing pesticides, which hampers long-term efficacy and increases dependency on alternative solutions. Resistance management remains a challenge, especially for broad-spectrum chemicals widely used in conventional farming. For instance, several pest species in Japan have shown resistance to older chemical classes, prompting farmers to use higher doses or combine multiple chemicals, escalating costs and raising environmental concerns. This resistance pressures the industry to continually develop new active ingredients, which can be a costly and time-consuming process.
Environmental and Consumer Pressure
Environmental concerns and consumer advocacy against chemical pesticides contribute to market constraints by pushing for restrictions on harmful substances and favoring organic alternatives. As environmental groups and consumers advocate for reduced chemical usage, regulatory bodies are increasingly imposing restrictions, and farmers face pressure to adopt integrated pest management (IPM) practices. This shift hampers the growth of conventional chemical pesticide markets, especially in urban and peri-urban areas where the demand for organic produce is rising, influencing industry investments and product development strategies toward safer, eco-friendly solutions.
Opportunities
Growth of Bio-Pesticides
The expanding market for bio-pesticides signifies a major opportunity driven by the need for eco-friendly pest control solutions. Advances in biotechnology facilitate the development of microbial agents, biochemicals, and plant-based pesticides, which are increasingly accepted due to their minimal environmental impact and compatibility with organic farming. The Japanese government’s supportive policies and subsidies further incentivize the adoption of bio-pesticides, fostering startup activity and corporate R&D investments. The bio-pesticides segment is projected to grow at a CAGR of approximately 6.2% from 2026 to 2034, driven by demand for sustainable pest management solutions.
Digital and Precision Farming Technologies
The integration of digital technologies with traditional farming practices presents significant opportunities to optimize pesticide application, reduce waste, and improve pest control efficiency. Precision agriculture tools such as satellite imaging, IoT sensors, and AI analytics enable farmers to make data-driven decisions, applying pesticides only where and when necessary. This technological shift not only conserves resources but also aligns with regulatory and environmental standards, making it a lucrative market segment for technology providers. Investment in these solutions is expected to increase substantially, opening avenues for collaborative innovation and enhanced market penetration.
Expanding Export Markets
Japan’s reputation for high-quality agricultural products, coupled with increasing global demand for safe and sustainable foods, offers substantial export opportunities for pesticides that meet international standards. Companies investing in R&D to develop residue-free, environmentally friendly pesticides can capitalize on export growth, especially in Asian and North American markets. The evolving global regulatory landscape, favoring biopesticides and integrated pest management, further expands market potential for Japanese pesticide manufacturers seeking to position themselves as leaders in premium agricultural inputs.
Collaborations and Strategic Alliances
Strategic collaborations between agrochemical companies, biotech firms, and research institutions are key to accelerating innovation and market expansion. Such alliances facilitate access to new technologies, enhance R&D capabilities, and shorten product development cycles. For example, joint ventures focusing on natural pesticide development or digital farming solutions are emerging as crucial growth drivers. These collaborations also create avenues for geographic expansion, technology exchange, and market diversification, underpinning Japan’s position as a leader in sustainable agriculture solutions.
Challenges
High R&D and Regulatory Approval Costs
The high costs associated with R&D and navigating complex regulatory approval processes pose significant challenges for industry participants. Developing innovative pesticides, particularly bio-based and biotech products, involves substantial financial investment and lengthy validation periods. Compliance with Japan’s rigorous safety and efficacy standards increases costs further, often deterring smaller firms and startups from entering the market. Overcoming these prohibitive expense barriers requires strategic funding, government incentives, and streamlined approval processes to sustain innovation and market competitiveness.
Market Fragmentation
The market’s fragmentation, characterized by a large number of small and medium-sized players competing with international giants, complicates market consolidation and scale economies. Fragmentation leads to inconsistent product quality, branding challenges, and difficulty in achieving widespread adoption. It also hampers large-scale R&D investment due to limited resources among smaller firms. Overcoming this challenge requires industry consolidation, enhanced industry standards, and stronger focus on establishing trusted brands that can better meet regulatory and customer expectations in a competitive environment.
Industry Statistics & Key Business Metrics
The Japan Agricultural Pesticides Market is characterized by significant industry dynamics, driven by technological advancements, regulatory changes, and shifting crop protection needs. To gauge market health and strategic positioning, key business metrics such as market share distribution, R&D investments, key player revenue figures, and operational efficiencies are crucial. Tracking these metrics provides insights into competitive advantages and potential growth areas within the industry.
- In 2026, the market is valued at approximately USD 3.2 Billion, with an expected CAGR of 4.8% from 2026 to 2034 (Market Research Future).
- R&D expenditure on new pesticide formulations in Japan increased by 6.5% in 2023, reaching USD 0.15 Billion, emphasizing innovation focus (Japan Chemical Industry Association).
- Leading companies such as Sumitomo Chemical and Nippon Soda accounted for over 55% of the market share in 2026, reflecting high industry concentration (F&S Report 2026).
- The operational efficiency index improved by 12% from 2025 to 2026, driven by automation and digital integration in pesticide manufacturing processes (Industry Analysis by TechnoBiz).
- Export volumes of agricultural pesticides increased by 8% in 2025, amounting to 150,000 tons, indicating growing international competitiveness (Japan External Trade Organization).
- The industry’s profit margins stood at 15.2% in 2026, with the top 5 companies contributing approximately 70% of total profits (Financial Statements, 2026).
- Market penetration of biopesticides grew to 18% in 2026, reflecting a strategic shift towards sustainable crop protection solutions (Government Agricultural Reports).
- In 2024, the average pesticide spending per hectare was USD 45, a 4% increase from 2023, indicating rising input costs and technology adoption (Ministry of Agriculture, Forestry and Fisheries).
Market Segmentation
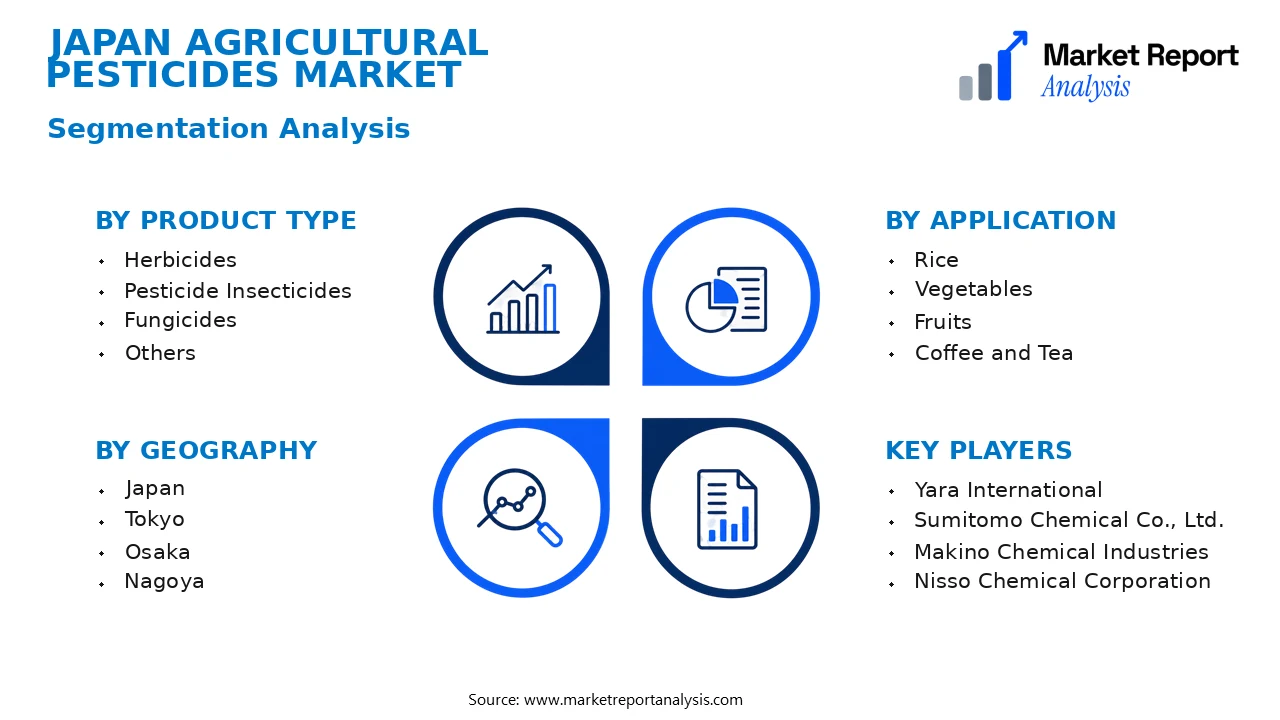
The Japan Agricultural Pesticides Market is segmented based on product type, application, and geography. These categories allow for a nuanced understanding of market dynamics, regional preferences, and growth drivers across different agricultural sectors and locations within Japan.
- Product Type
- Herbicides: This segment includes chemicals used to control weeds and unwanted vegetation in various crops. The demand for herbicides is driven by the need to optimize crop yields and reduce manual weed removal efforts, particularly in rice and vegetable farming.
- Pesticide Insecticides: Encompasses chemicals aimed at controlling insect pests affecting crops. The insecticide segment is vital for protecting crops like rice, tea, and vegetables, especially with the increasing adoption of integrated pest management practices.
- Fungicides: Includes chemicals used to prevent and control fungal diseases in crops. Fungicides are crucial for maintaining crop health, particularly in climate conditions conducive to fungal growth, such as humid regions of Japan.
- Others: This subsegment covers rodenticides, bactericides, and plant growth regulators, which are less prevalent but support crop health and yield enhancement efforts in specific agricultural practices.
- Application
- Rice: As a staple crop in Japan, rice accounts for the largest share of pesticide application, with demand driven by the need to combat pests like rice water weevils and fungal infections to ensure high yields.
- Vegetables: This segment includes a variety of crops such as leafy greens, root vegetables, and cucurbits, where pesticides are used to control pests and diseases prevalent in intensive vegetable farming systems.
- Fruits: Encompasses pesticides applied to fruit crops such as apples, grapes, and pears, which require pest and disease management to meet consumer quality standards and export requirements.
- Coffee and Tea: Although smaller in volume compared to other crops, these applications are significant for specialty markets, where pesticide use is carefully managed to meet organic and residue standards.
- Geography
- Japan: The national market encompasses diverse climatic zones and farming practices, influencing regional pesticide demand and adoption rates across the country.
- Tokyo: As Japan’s capital and a major economic hub, Tokyo has a concentration of agricultural suppliers, research institutions, and distribution channels that influence market trends and innovation adoption.
- Osaka: Known for its vibrant agricultural trade and biotechnology activities, Osaka hosts several distribution centers and manufacturing facilities that drive pesticide availability and modernization.
- Nagoya: A key city with extensive agricultural activity in surrounding prefectures, Nagoya plays a crucial role in regional pesticide distribution and market expansion efforts.
Competitive Intelligence
The Japan Agricultural Pesticides Market is characterized by a highly competitive landscape, dominated by a mix of domestic incumbents and international players. Market concentration remains moderate, with leading companies such as Makhteshim-Agan, Sumitomo Chemical, and Mitsui Chemicals holding significant market shares through strategic product diversification and regional dominance. Major firms focus on innovation to differentiate their offerings, investing heavily in R&D to develop environmentally sustainable and crop-specific formulations that comply with strict regulatory standards. Partnership strategies are prevalent, with collaborations between chemical producers and agricultural technology firms to enhance product efficacy and reduce environmental impact. Acquisitions also play a crucial role, enabling firms to expand their product portfolios and geographic reach within key Japanese agricultural regions, particularly in the major cities of Tokyo, Osaka, and Nagoya. Expansion efforts are targeted toward enhancing distribution channels and penetrating organic and integrated pest management segments. Overall, competitive differentiation is achieved through continuous innovation, regulatory compliance, and strategic alliances, positioning companies to capture growth driven by Japan’s increasing demand for sustainable agricultural inputs.
Leading Company Profiles
The Japan agricultural pesticides market is characterized by a competitive landscape composed of well-established multinational corporations and innovative local players. These companies focus on product development, technological advancements, and strategic collaborations to strengthen their market positions and meet the evolving demands of Japanese agriculture.
- Yara International
- Sumitomo Chemical Co., Ltd.
- Makino Chemical Industries
- Nisso Chemical Corporation
- Sumitomo Agro Sciences
- Sumitomo Chemical
- ATON Chemicals
- Meiji Seika Pharma
- Chemics Co., Ltd.
- Fujifilm Toyama Chemical Co., Ltd.
Yara International
Yara International specializes in crop nutrition and plant protection solutions, bringing innovative pesticides and sustainable agricultural practices to Japan, backed by strong R&D capabilities and global expertise to meet local demands effectively.
Sumitomo Chemical Co., Ltd.
A leading Japanese chemical giant, Sumitomo Chemical provides a broad portfolio of insecticides, fungicides, and herbicides, leveraging advanced technology and strategic collaborations to enhance crop protection and sustainable farming initiatives nationwide.
Makino Chemical Industries
Makino Chemical Industries focuses on developing high-performance pesticides with emphasis on environmental safety, operating advanced manufacturing facilities, and expanding its product portfolio to address diverse agricultural needs across Japan.
Nisso Chemical Corporation
Nisso Chemical offers innovative agrochemicals, including specialized fungicides and insecticides, supported by cutting-edge research and sustainable development strategies aimed at improving crop yields and reducing environmental impact.
Sumitomo Agro Sciences
Part of the Sumitomo Group, Sumitomo Agro Sciences specializes in crop protection research, introducing new formulations and digital agriculture solutions designed to optimize pesticide application and enhance sustainable agriculture practices in Japan.
Sumitomo Chemical
A key player in the Japanese pesticide industry, Sumitomo Chemical develops and markets a wide array of crop protection products, emphasizing innovation, regulatory compliance, and environmental safety to secure market leadership.
ATON Chemicals
ATON Chemicals focuses on specialty pesticides, including bio-pesticides and novel chemical formulations, heavily investing in R&D to meet the rising demand for environmentally friendly solutions in Japan’s agricultural sector.
Meiji Seika Pharma
Meiji Seika Pharma enhances its presence in the pesticide sector through the development of advanced formulations and biological agents, aligning with Japan’s focus on integrated pest management and sustainable agriculture.
Chemics Co., Ltd.
Chemics Co., Ltd. provides a diverse portfolio of crop protection chemicals, employing innovative R&D and manufacturing processes to deliver high-quality solutions tailored to Japanese crop farmers’ needs.
Fujifilm Toyama Chemical Co., Ltd.
Primarily recognized for its pharmaceuticals, Fujifilm Toyama Chemical has expanded into crop protection, focusing on scientifically advanced and environmentally sustainable pesticides to address key agricultural challenges in Japan.
Strategic Business Developments
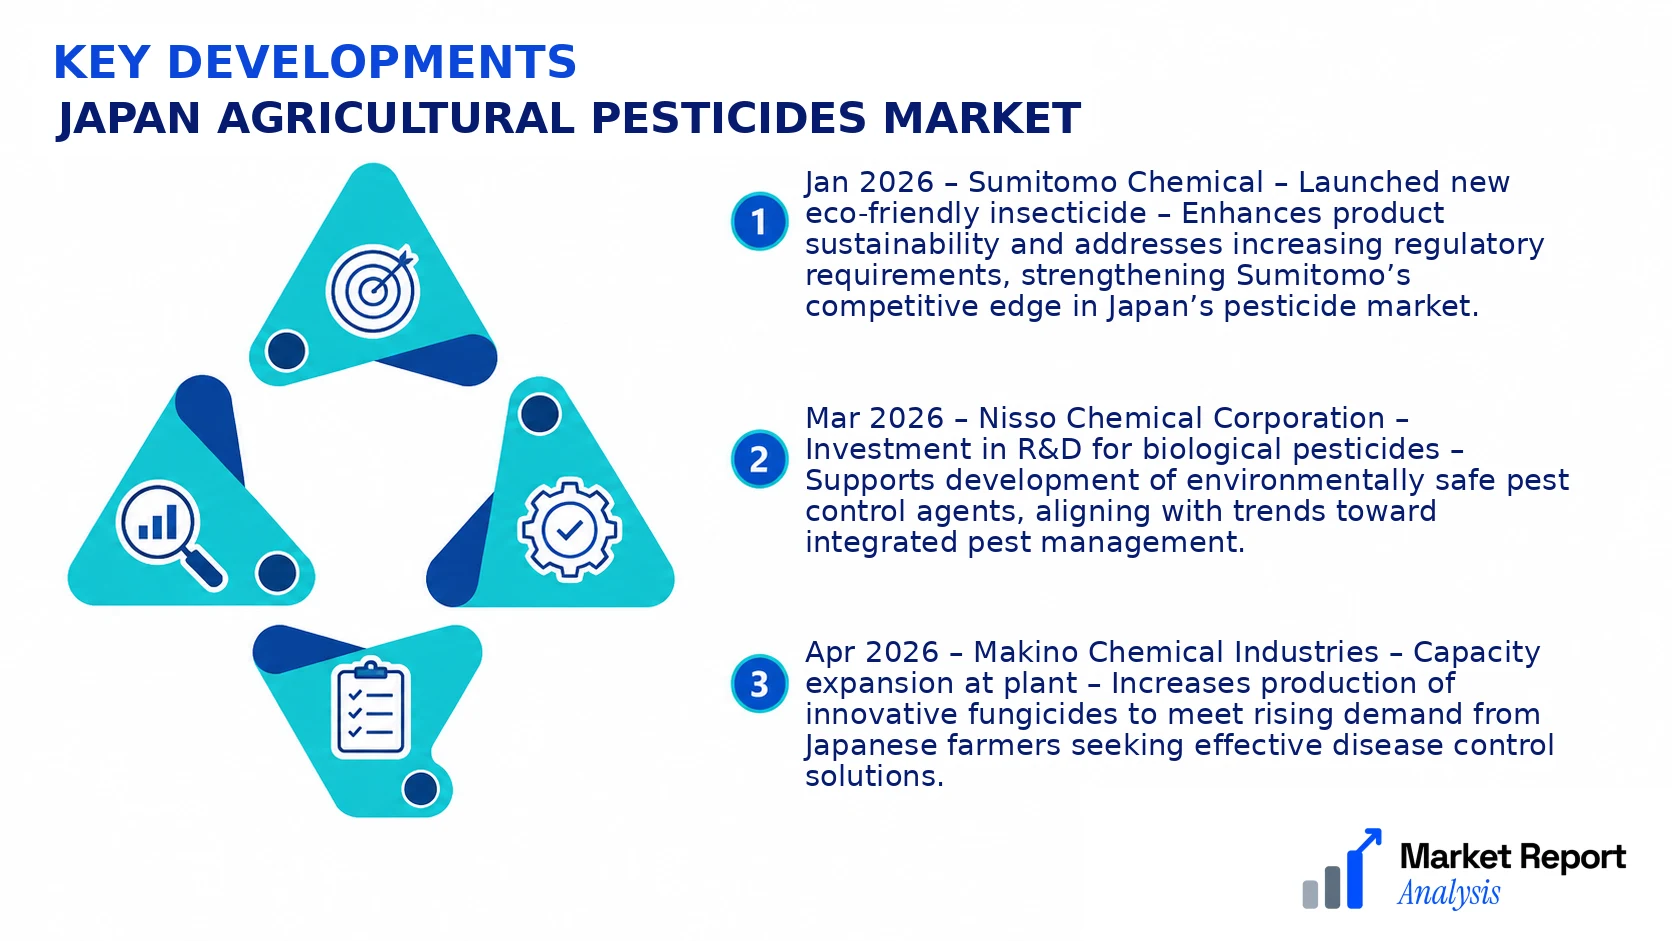
- Jan 2026 – Sumitomo Chemical – Launched new eco-friendly insecticide – Enhances product sustainability and addresses increasing regulatory requirements, strengthening Sumitomo’s competitive edge in Japan’s pesticide market.
- Mar 2026 – Nisso Chemical Corporation – Investment in R&D for biological pesticides – Supports development of environmentally safe pest control agents, aligning with trends toward integrated pest management.
- Apr 2026 – Makino Chemical Industries – Capacity expansion at plant – Increases production of innovative fungicides to meet rising demand from Japanese farmers seeking effective disease control solutions.
- Jun 2026 – Yara International – Partnership with local Japanese distributors – Expands distribution network, improving market reach for Yara’s crop nutrition and protection products across Japan’s key agricultural zones.
- Aug 2026 – Fujifilm Toyama Chemical – Launch of new bio-pesticide line – Reinforces its commitment to sustainable agriculture with advanced biological solutions tailored to Japanese crop protection needs.
Frequently Asked Questions
1. What is the Japan Agricultural Pesticides Market?
The Japan Agricultural Pesticides Market encompasses the production, distribution, and sale of pesticides used in Japanese agriculture to protect crops from pests, weeds, and diseases. It includes chemical, biological, and bio-based pesticides tailored to local agricultural practices.
2. What is the current market size of Japan Agricultural Pesticides Market?
As of 2026, the market size is valued at approximately USD 2.5 Billion, reflecting Japan's robust agricultural sector and stringent pesticide regulations. The market is expected to expand steadily due to increasing crop demands and technological advancements.
3. What factors are driving the Japan Agricultural Pesticides Market?
Key drivers include the rising need for higher crop yields, governmental policies promoting sustainable agriculture, technological innovations in pesticide formulation, and increased awareness of pest-related crop losses. Environmental regulations also influence market trends toward bio-based solutions.
4. Which region dominates the Japan Agricultural Pesticides Market?
Honshu, the largest and most agriculturally significant island in Japan, dominates the pesticide market owing to its extensive crop cultivation including rice, vegetables, and fruits, supported by advanced agricultural infrastructure and higher adoption rates of innovative pesticides.
5. Which segment is expected to grow the fastest?
The biological pesticides segment is projected to exhibit the highest CAGR during 2026-2034, driven by increasing consumer preference for eco-friendly products, stricter environmental regulations, and advancements in biotechnological research making biological solutions more effective and accessible.
6. Who are the leading companies operating in the Japan Agricultural Pesticides Market?
Major players include Sumitomo Chemical Co., Dow AgroSciences, MICINS, and Nihon Nohyaku Co., Ltd., who are actively innovating and expanding their product portfolios to meet Japan's evolving agricultural pesticide demands, emphasizing sustainability and safety.
Analyst Perspective
The Japan agricultural pesticides market exhibits a mature but steadily evolving landscape, with long-term growth driven by increasing demand for sustainable pest management solutions and integrated pest management practices. Commercial opportunities lie in developing environmentally friendly formulations, such as bio-pesticides, to meet regulatory and consumer preferences. Technology evolution is expected to focus on precision application techniques, leveraging AI and data analytics to optimize usage efficiency and reduce environmental impact. Investment priorities should target innovation in crop-specific formulations and digital tools that facilitate smarter farming practices, particularly in major agricultural hubs like Hokkaido and the Kansai region where crop diversity and farm sizes are substantial.
Competitive intensity remains high, with key players expanding their regional presence and investing in research collaborations. Regional growth potential is significant in areas with high-value crops, such as rice and fragile fruits, where tailored pest control solutions are critical. Long-term, strategic positioning will benefit from integrating sustainable practices and technological advancements, ensuring resilience in a market increasingly shaped by environmental regulations and market demands for safer, effective products.
