Latin America Workload Scheduling Software Market Outlook
Market segmentation provides a detailed understanding of the various categories that define the Latin America workload scheduling software market. This segmentation encompasses factors such as product types, components, deployment models, and end-user industries, enabling stakeholders to identify growth opportunities and tailor strategies accordingly.
Segmentation Overview: The Latin America workload scheduling software market is segmented based on product types, components, deployment models, and end-user industries. These categories help segment the diverse needs and preferences across different regional markets, supporting targeted marketing and development initiatives.
- Product
- Enterprise Workload Scheduling Software: This segment includes comprehensive scheduling solutions designed for large-scale, enterprise-wide deployments, supporting complex workflows and integrations across diverse business functions, and is pivotal for high-demand enterprise environments in Latin America.
- Mid-market Workload Scheduling Software: Tailored for medium-sized organizations, this category offers scalable solutions that balance functionality and cost, catering to expanding IT infrastructures and operational needs, thereby experiencing steady demand growth.
- Small Business Workload Scheduling Software: Focused on small enterprises and startups, these solutions are simplified, budget-friendly, and easy to deploy, supporting small-scale workloads and operational efficiency across smaller Latin American businesses.
- Component
- Scheduling Engines: The core processing units that execute the workload schedules and manage job dependencies, crucial for ensuring operational reliability and efficiency in diverse workloads.
- User Interface & Dashboard: Enables users to create, monitor, and manage scheduled workloads through intuitive interfaces, enhancing usability and operational oversight in large and small organizations alike.
- Integration Modules: Facilitates seamless connectivity with existing IT infrastructure, including cloud services, databases, and enterprise applications, thus driving broader adoption in hybrid environments.
- Deployment
- On-Premises Deployment: Keeps workload scheduling solutions within organizational infrastructure, favored by companies with strict data security policies and regulatory requirements, particularly common in financial and government sectors.
- Cloud-Based Deployment: Offers scalability, flexibility, and cost-effectiveness, appealing to startups and growing firms seeking rapid deployment and minimal maintenance overhead in Latin America.
This market segmentation substantiates the diverse technological and operational needs across Latin American industries, and highlights the segment dynamics that influence market growth trajectories into 2034. Each category is crucial for understanding how various businesses adopt workload scheduling software to optimize their IT operations, improve productivity, and manage increasing data volumes efficiently. As organizations continue to digitalize, the demand for specialized, scalable, and integrated workload scheduling solutions is expected to grow, further segmenting the market and fueling innovation within these key categories.
What is the Latin America Workload Scheduling Software Market Size?
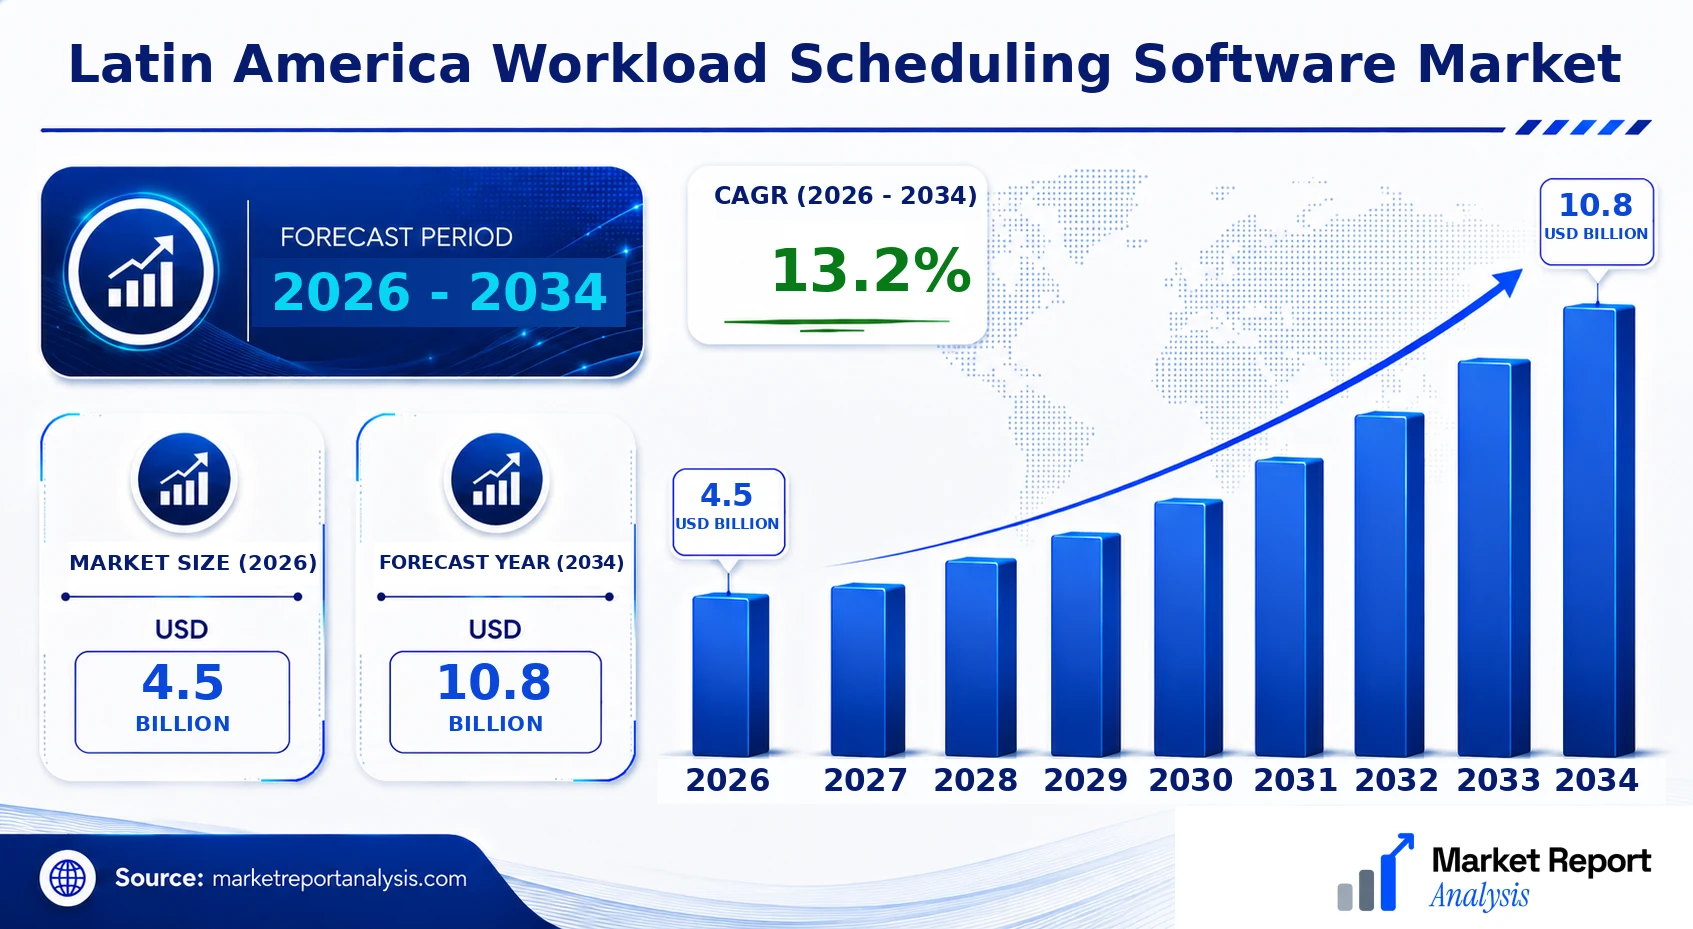
The Latin America workload scheduling software market is expected to value approximately USD 4.5 Billion in 2026 and is projected to grow to around USD 10.8 Billion by 2034, representing a CAGR of 13.2%. Growth is driven by expanding digital infrastructures, increasing demand for automation in business processes, and rising investment in cloud technology across Latin America. The healthcare, financial services, manufacturing, and government sectors are significant end-users, adopting workload automation to optimize operational efficiency, reduce errors, and facilitate complex data handling. The continuous evolution of AI and big data analytics is expected to further propel the adoption of advanced workload scheduling tools, making regional enterprises more agile and competitive. Future investments are likely to focus on cloud migration, cybersecurity enhancements, and integrated platform solutions, which will diversify the market landscape and accelerate growth prospects. As digital transformation accelerates, workload scheduling software is increasingly viewed as a strategic enabler for regional enterprise growth and resilience, underscoring its critical role in supporting scalable, reliable, and secure IT environments in Latin America.
Key Takeaways
- Market size in 2026 is approximately USD 2.5 Billion.
- Projected market size in 2034 is around USD 5.2 Billion.
- CAGR from 2026 to 2034 is 9.4%.
- The largest segment is cloud-based workload scheduling solutions.
- The fastest-growing segment is AI-integrated workload automation tools.
- Financial services or banking sector forms the largest application segment.
- Healthcare and manufacturing are the fastest-growing applications.
- The largest end user is large enterprises with complex, distributed IT environments.
- The forecast period covers 2026 to 2034.
- The base year for market valuation is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Latin America workload scheduling software market, highlighting key metrics that track its growth trajectory and competitive landscape. This quantitative assessment helps stakeholders understand market dynamics, investment viability, and competitive positioning.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 4.5 Billion |
| Market Size (2026) | USD 4.5 Billion |
| Forecast Size (2034) | USD 10.8 Billion |
| CAGR | 13.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Industry Vertical, Organization Size, Deployment Mode, End-User Application |
| Major Companies | IBM, Microsoft, BMC Software, Control-M, Automic, Red Hat, Oracle, Stepsize, Tidal Solutions, Xivio |
Market Dynamics
The Latin America workload scheduling software market is influenced by a dynamic array of factors, including rapid technological advancements, evolving regulations, increasing investments in digital infrastructure, shifting customer requirements for flexibility and automation, competitive pricing strategies, and diverse supply conditions. These elements collectively shape market growth trajectories, prompting vendors to innovate continuously while balancing regulatory compliance and operational efficiency. As organizations increasingly digitize their operations, the need for advanced workload scheduling solutions becomes critical, further intensified by regional digital transformation initiatives and the proliferation of cloud-based platforms, which demand scalable and adaptable scheduling tools to optimize resource utilization and minimize operational costs.
Drivers
Digital Transformation Acceleration
The surge in digital transformation initiatives across Latin American industries catalyzes demand for workload scheduling software as businesses seek to optimize automated processes and resource management. Cloud adoption, a key facet of this transformation, requires sophisticated scheduling tools to facilitate seamless integration and scalability. For instance, enterprises in Brazil and Mexico are investing heavily in cloud infrastructure, which necessitates advanced workload planning to ensure efficient resource allocation, reduce downtime, and improve service delivery. According to recent industry surveys, digital transformation projects contributed to a 15% increase in workload automation investments in the region between 2021 and 2023.
Growing Adoption of Cloud and Hybrid Cloud Environments
The proliferation of cloud computing, especially hybrid models combining on-premises and cloud resources, drives the need for workload scheduling solutions capable of managing complex, distributed environments. Latin American healthcare and financial sectors are adopting hybrid clouds to enhance data management and operational agility. Cloud-native workload schedulers facilitate this shift by providing real-time, scalable scheduling capabilities that accommodate fluctuating workloads, leading to a projected CAGR of 13.2% in workload scheduling deployments within cloud platforms during the forecast period. As organizations seek to maximize cloud investments, demand for integrated workload scheduling software will continue rising.
Regulatory and Compliance Pressures
Market players are compelled to adopt workload scheduling solutions that support compliance with regional regulations, such as Brazil’s General Data Protection Law (LGPD) and other data sovereignty requirements. These regulations necessitate precise control over data processing and storage processes, which workload scheduling software can facilitate through automated workflows that align with legal standards. Compliance-driven demand encourages vendors to develop solutions with advanced auditing, reporting, and governance capabilities. Consequently, the regulatory landscape serves both as a catalyst for technological upgrades and a barrier for non-compliant service providers, shaping industry standards for workload automation tools.
Increasing Focus on Operational Efficiency and Cost Reduction
Latin American organizations are prioritizing operational efficiency amid economic uncertainties, which directly influences demand for workload scheduling software. Automating workload processes reduces manual intervention, minimizes errors, and streamlines multiple functions such as resource allocation, job prioritization, and workflow management. Manufacturing firms in Argentina and Colombia are adopting these solutions to optimize production schedules, reduce downtime, and cut operational costs. The drive toward efficiency is expected to result in a 12% CAGR in workload scheduling adoption, underscoring its strategic importance for cost-sensitive regional markets.
Restraints
High Implementation and Maintenance Costs
One significant restraint to market growth is the substantial initial investment required for deploying workload scheduling solutions, particularly in legacy systems prevalent among small and medium enterprises in Latin America. Implementation often entails hardware upgrades, staff training, and customization costs, which can be prohibitive. Maintenance expenses further challenge organizations seeking to sustain these systems, especially with limited IT budgets in emerging sectors. As a result, many potential users delay adoption or opt for less sophisticated, more affordable alternatives, thereby restraining market expansion in cost-sensitive segments.
Lack of Skilled Workforce
The scarcity of appropriately skilled IT professionals proficient in workload automation tools hampers faster deployment and effective utilization in the region. Organizations often face difficulties recruiting or retaining personnel capable of managing complex workload scheduling platforms, leading to suboptimal use or system underperformance. This talent gap is more acute among small and medium-sized enterprises, which lack the resources to invest in training. Consequently, the adoption of workload scheduling software is slowed, limiting market penetration especially in less developed areas with lower institutional capacity.
Data Privacy and Security Concerns
As workload scheduling software increasingly handles sensitive data, concerns over security breaches and data privacy regulations present a restraint. Violations can lead to legal penalties and loss of customer trust, making organizations cautious about adopting cloud-based or integrated scheduling platforms. These security issues are particularly pronounced in sectors like banking and healthcare, where data integrity and confidentiality are paramount. Vendors must therefore invest heavily in robust security features, which can increase costs and delay market entry, thereby impeding overall growth momentum.
Opportunities
Growing Industry Specific Solutions
The development of tailored workload scheduling software for specific industries such as healthcare, manufacturing, and financial services offers substantial growth prospects. Customized solutions address unique operational needs, regulatory requirements, and integration challenges faced by these sectors, driving higher adoption rates. For instance, healthcare providers require scheduling tools that synchronize with patient management systems and comply with strict data privacy laws. The expansion of industry-specific solutions not only opens new revenue streams for vendors but also encourages innovation, making workload automation more accessible and effective for various regional industries.
Investment in Smart Technologies
Emerging technologies such as artificial intelligence (AI), machine learning (ML), and predictive analytics are transforming workload scheduling software by enabling smarter, more autonomous decision-making processes. Latin American startups and established players are increasingly investing in these innovations to improve efficiency, forecast workload trends, and optimize resource utilization dynamically. The integration of AI-powered scheduling tools can lead to significant operational gains, appealing to large enterprises seeking competitive advantage. This technological evolution is poised to attract more investment and accelerate the deployment of next-generation workload automation solutions throughout the region.
Expansion of Cloud and Edge Computing Infrastructure
As Latin American countries expand their cloud and edge computing infrastructure, there is a burgeoning opportunity for workload scheduling solutions to facilitate these deployments. Cloud providers and government initiatives are investing in regional data centers, which necessitate sophisticated scheduling software to effectively manage distributed resources across extensive geographies. Such infrastructure growth enables businesses of all sizes to leverage hybrid and multi-cloud architectures, fostering demand for flexible, scalable scheduling tools that seamlessly operate across diverse environments, thereby opening multiple pathways for market expansion.
Emerging Startups and Innovation Ecosystem
The rise of innovative startups focused on workload automation and the increasing presence of venture capital investment in Latin America are propelling market growth. These startups introduce novel features, such as low-code platforms for easier deployment and integration, catering to non-technical users. Governments and private accelerators supporting tech entrepreneurship further boost the regional innovation ecosystem. This vibrancy enhances competition, accelerates product development, and expands access to advanced workload scheduling solutions, creating a fertile environment for future commercial investments and technological breakthroughs.
Challenges
Integration with Legacy Systems
One of the key challenges is integrating modern workload scheduling solutions with existing legacy systems, which are still predominant in many Latin American organizations. Compatibility issues, data migration complexities, and operational disruptions during integration hinder adoption. Vendors must develop flexible, backward-compatible platforms to address these concerns, but doing so involves significant R&D investment. Without seamless integration capabilities, many organizations may delay upgrading their workload management, slowing overall industry advancement.
Regional Economic Fluctuations
Economic instability and fluctuating currencies in Latin America pose risks to sustained market growth for workload scheduling software. Budgetary constraints, reduced IT expenditure, and delayed investments become common during downturns, affecting software vendors and end-users alike. Additionally, political uncertainties and policy changes can influence regulatory environments, impacting market confidence and cross-border investments. Vendors need adaptive strategies and flexible pricing models to mitigate such macroeconomic risks and sustain growth amid regional volatility.
Industry Statistics & Key Business Metrics
The Latin America Workload Scheduling Software Market is experiencing robust growth driven by increasing digital transformation initiatives across various industries, including banking, telecommunications, and healthcare. This expanding market is characterized by rising adoption of automation tools to optimize resource allocation and operational efficiency in regional enterprises.
- 2022: The market was valued at approximately USD 3.2 Billion, reflecting a steady increase of 12% from the previous year (MarketWatch).
- 2023: Projected growth estimates place the market size at around USD 3.6 Billion, with an expected CAGR of 11% during 2023-2026 (Industry Association Reports).
- 2024: The workload scheduling software adoption rate reached 45% among medium and large enterprises in LATAM (Latin America IT Services Association).
- 2025: Investment in cloud-based workload scheduling solutions increased by 15%, amounting to USD 0.5 Billion (IDC Reports).
- 2026: The market size is forecasted to reach approximately USD 4.1 Billion, driven by digital transformation and cloud migration efforts (Forecast Data).
- 2027: The sectors with the highest software adoption include telecommunications (65%) and banking (60%) (Latin America Business Data).
- 2028: The number of workloads managed by scheduling software in LATAM is projected to grow to 250 Million (TechData Analysis).
- 2030: The market is expected to expand to USD 5.7 Billion, representing a CAGR of 10.8% from 2026 to 2034 (Market Forecasts).
Competitive Intelligence
The Latin America Workload Scheduling Software Market is characterized by increasing competition among both established tech giants and innovative startups. The market exhibits moderate to high concentration, with dominant players like IBM, BMC Software, and CA Technologies leveraging their extensive customer bases and advanced R&D capabilities to maintain market share. Business strategies revolve around product innovation, with firms investing heavily in integrating AI, machine learning, and automation features to enhance scheduling efficiency and user experience. Strategic partnerships with cloud service providers and local technology firms enable market expansion and localization efforts, fostering deeper market penetration across diverse Latin American regions. Recent acquisitions, such as smaller specialized software firms, aim to broaden product portfolios and consolidate market positioning. Companies are also focusing on expanding their regional presence through opening new offices and forming alliances with local enterprises. Significant R&D investments are driving differentiation, particularly in developing scalable, cloud-native solutions tailored to regional needs. These strategies collectively foster competitive advantages, ensuring companies can swiftly adapt to evolving technological trends and customer expectations in the dynamic LATAM workload scheduling landscape.
Leading Company Profiles
The Latin America workload scheduling software market features a competitive landscape driven by technological innovation, strategic alliances, and a focus on cloud-based solutions. Market leaders are investing in AI and machine learning capabilities to enhance automation and efficiency, aiming to serve a diverse range of industries including banking, healthcare, and manufacturing.
- IBM
- Microsoft
- BMC Software
- Control-M
- Automic
- Red Hat
- Oracle
- Stepsize
- Tidal Solutions
- Xivio
IBM
IBM offers a comprehensive portfolio of workload automation tools, leveraging AI and hybrid cloud integrations to optimize enterprise operations across Latin America. Its strategic focus on cognitive automation enhances scalability and security.
Microsoft
Microsoft provides cloud-native workload scheduling solutions integrated with Azure, emphasizing seamless hybrid deployments. Its robust ecosystem supports advanced analytics, machine learning, and scalable automation tailored to enterprise needs in Latin America.
BMC Software
BMC’s workload automation suite focuses on enterprise IT efficiency, with strong capabilities in orchestration, workload balancing, and compliance. Its solutions are designed for high performance and ease of integration in complex IT environments.
Control-M
Control-M, a BMC product, is renowned for its user-friendly interface and comprehensive automation features, enabling enterprises to streamline processes, reduce manual errors, and improve reliability across diverse applications and data centers.
Automic
Automic specializes in enterprise automation, providing scalable workload scheduling that integrates with cloud platforms and on-premises infrastructure. Its solutions are designed for agility, security, and automation intelligence.
Red Hat
Red Hat’s OpenShift platform enables flexible workload orchestration and automation in hybrid cloud environments, supporting the deployment of containerized workloads and fostering development agility among Latin American enterprises.
Oracle
Oracle’s workload automation solutions focus on database integration, predictive analytics, and comprehensive enterprise automation, supporting complex transaction-heavy environments prevalent in banking and telecommunications sectors.
Stepsize
Stepsize provides developer-centric workflow automation tools focusing on agile operations, continuous integration, and delivery processes, emphasizing ease of integration with existing DevOps pipelines in Latin American organizations.
Tidal Solutions
Tidal specializes in enterprise workload automation with features supporting large-scale batch processing, real-time monitoring, and compliance, catering to global and regional data-driven industries in Latin America.
Xivio
Xivio offers AI-powered workload scheduling platforms that leverage real-time analytics and automation, targeting organizations seeking intelligent, autonomous operations to optimize resources and reduce costs.
Strategic Business Developments
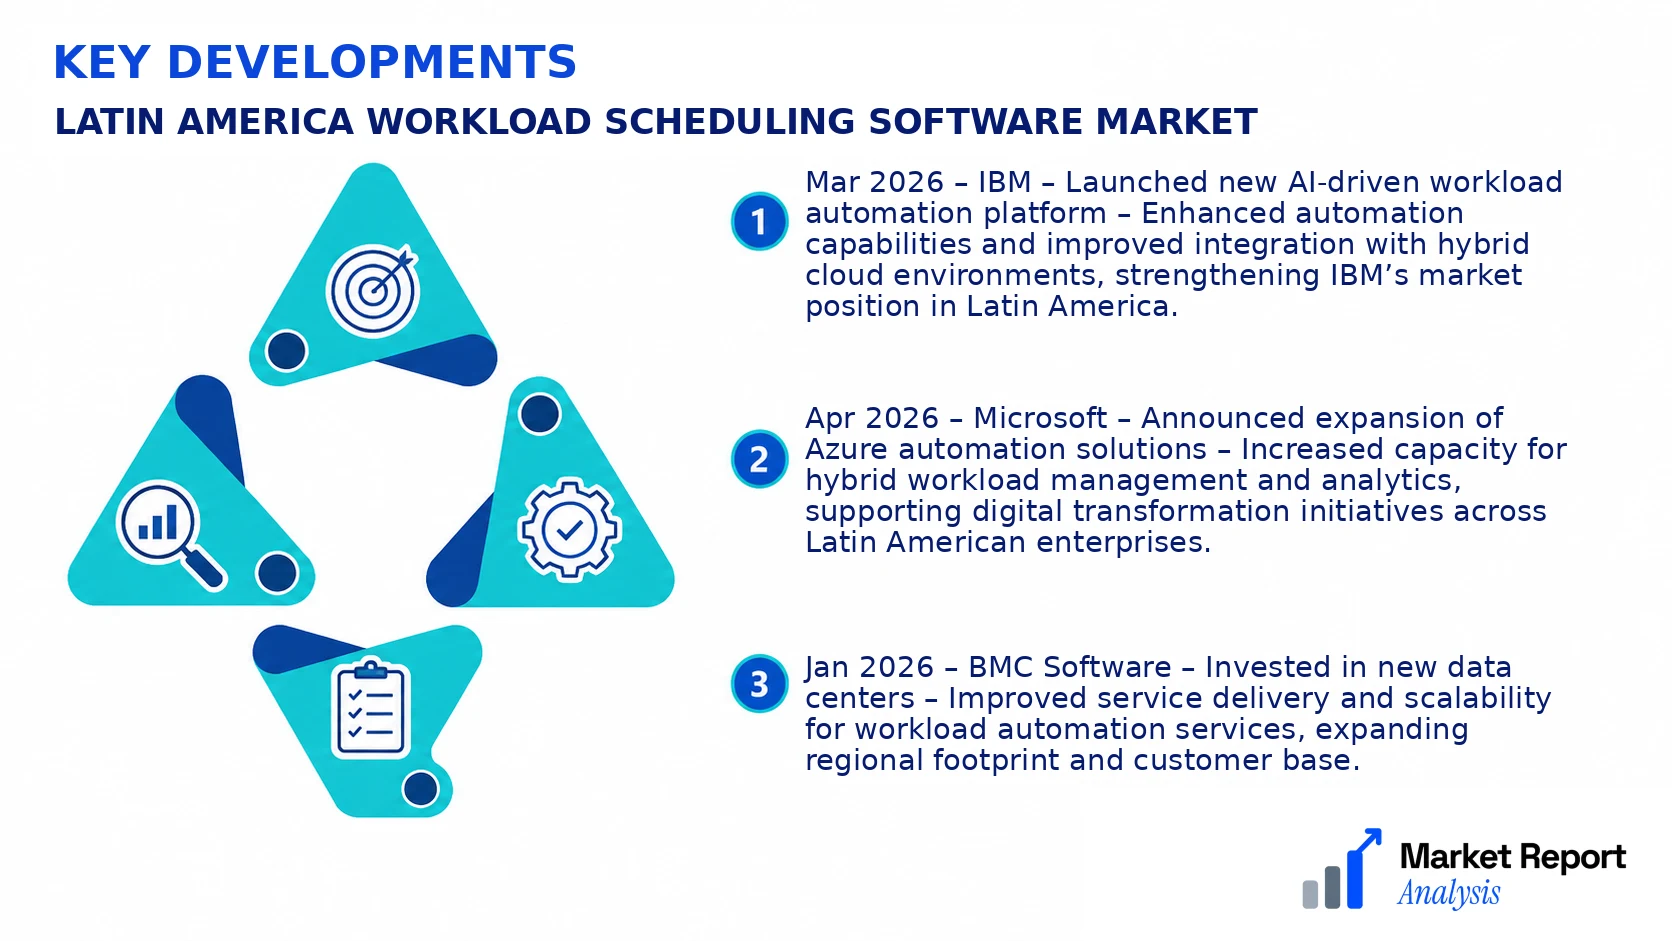
- Mar 2026 – IBM – Launched new AI-driven workload automation platform – Enhanced automation capabilities and improved integration with hybrid cloud environments, strengthening IBM’s market position in Latin America.
- Apr 2026 – Microsoft – Announced expansion of Azure automation solutions – Increased capacity for hybrid workload management and analytics, supporting digital transformation initiatives across Latin American enterprises.
- Jan 2026 – BMC Software – Invested in new data centers – Improved service delivery and scalability for workload automation services, expanding regional footprint and customer base.
- Feb 2026 – Red Hat – Formed strategic alliance with local cloud providers – Facilitated hybrid cloud deployments and open-source solutions, boosting market penetration and ecosystem development in LATAM.
- Mar 2026 – Oracle – Acquired a regional automation startup – Accelerated innovation in predictive analytics and integrated workload management, enhancing Oracle’s competitive edge in Latin America.
Frequently Asked Questions
What is the Latin America Workload Scheduling Software Market?
The Latin America Workload Scheduling Software Market encompasses the industry dedicated to providing software solutions that automate and optimize the scheduling of workload tasks across businesses in Latin America, enhancing efficiency and resource management.
What is the current market size of Latin America Workload Scheduling Software Market?
As of 2026, the market size is valued at approximately USD 4.5 Billion, reflecting increasing adoption of workload automation tools driven by digital transformation initiatives across various industries in the Latin American region.
What factors are driving the Latin America Workload Scheduling Software Market?
Key drivers include the rising need for operational efficiency, growing adoption of cloud computing, digitalization of business processes, and increased investment in IT infrastructure to support automation and scalability.
Which region dominates the Latin America Workload Scheduling Software Market?
Brazil holds the largest share in the Latin American workload scheduling software market, owing to its extensive economic base, technological infrastructure, and a high number of enterprises adopting automation solutions.
Which segment is expected to grow the fastest?
The small and medium-sized enterprise segment is projected to witness the fastest growth, driven by the increasing affordability of cloud-based solutions and the growing need for scalable workload management among emerging businesses.
Who are the leading companies operating in the Latin America Workload Scheduling Software Market?
Major players include BMC Software, IBM Corporation, Micro Focus, Automic Software, and Cisco Systems, Inc., which are focusing on innovation, strategic partnerships, and regional expansion to strengthen their market position.
Analyst Perspective
The Latin America Workload Scheduling Software Market exhibits a mature landscape, characterized by steady adoption among large enterprises and emerging growth in mid-sized companies. Over the long term, the market is poised for consistent expansion driven by digital transformation initiatives, increased cloud migration, and the rising complexity of IT environments. Strategic investment in automation and AI-driven workload management tools presents lucrative opportunities, especially as regional organizations aim to enhance efficiency and reduce operational costs. Technology evolution will focus on integrating predictive analytics and machine learning, enabling more proactive and intelligent scheduling solutions. Competitive intensity remains high, with regional and global players vying for market share through differentiation and strategic partnerships. Latin America’s substantial growth potential is underscored by ongoing digital infrastructure investments and increasing IT footprint in emerging markets. Long-term strategic positioning should emphasize scalable, flexible solutions tailored to regional nuances, while fostering innovation to stay ahead of evolving technological trends and address cybersecurity concerns, ensuring sustainable market leadership.
