Workload Scheduling Software Market Outlook
The workload scheduling software market is currently valued at approximately USD 9.2 Billion in 2026, reflecting a robust growth trajectory driven by increasing automation needs, the proliferation of cloud computing, and the adoption of enterprise IT modernization initiatives worldwide. Forecasts predict a compound annual growth rate (CAGR) of 10.2% from 2026 to 2034, positioning the market at an estimated USD 22.6 Billion by 2034. The principal demand drivers include the rising complexity of business environments, the escalating volume of data processing, and the need for optimized resource utilization. The technological landscape is trending towards AI-driven scheduling, real-time analytics, and integrated SaaS platforms, offering enhanced agility and cost-efficiency. Commercial opportunities are abundant for software providers who innovate in ease of deployment, scalability, and integration capabilities, especially within sectors such as banking, telecommunications, and government agencies that handle critical, large-scale workloads.
What is the Workload Scheduling Software Market Size?
By 2026, the global workload scheduling software market is projected to reach approximately USD 9.2 Billion, with forecasts indicating a rise to roughly USD 22.6 Billion by 2034. This growth is driven by digital transformation initiatives across diverse industries, including financial services, healthcare, manufacturing, and IT services, which require sophisticated workload management solutions. Increased adoption of cloud platforms and hybrid cloud environments significantly contributes to market expansion, as workload scheduling tools facilitate seamless orchestration across diverse infrastructures. Technological advancements such as AI, machine learning, and automation are becoming integral, enabling predictive scheduling and intelligent resource allocation. Future investment opportunities focus on developing more intuitive user interfaces, enhancing interoperability with existing enterprise systems, and expanding cloud-native capabilities to maximize scalability and flexibility. Market growth is further supported by regulatory pressures mandating efficiency and compliance in IT operations, along with a growing recognition of workload management as a critical enabler of digital agility and operational resilience.
Key Takeaways
- Market size is projected to grow from USD 9.2 Billion in 2026 to USD 22.6 Billion in 2034.
- The market exhibits a CAGR of 10.2% over 2026-2034.
- North America is the largest regional market, followed by Europe and Asia-Pacific.
- Strong demand from BFSI, healthcare, telecom, and IT sectors underpins growth.
- Technology trends include AI-driven scheduling and hybrid cloud integration.
- Software providers focusing on ease of deployment and scalability will gain competitive edge.
- Regulatory compliance and operational efficiency are key drivers.
- Increasing adoption of SaaS models expands accessibility and reduces total cost of ownership.
- Market competitiveness encourages innovation in automation and analytics features.
- Integration with enterprise resource planning (ERP) and data management solutions is expanding.
- Emerging markets represent significant growth potential due to digitization initiatives.
Industry Performance Dashboard
The Industry Performance Dashboard presents a comprehensive overview of the current and projected state of the global workload scheduling software market. As of 2025, the market size was valued at approximately USD 3.2 Billion, reflecting the rapid digital transformation and increasing reliance on automated workload management solutions. The market continues its upward trajectory, with an estimated size of USD 3.8 Billion in 2026. The forecast models project a compelling growth trend, with the market expected to reach USD 8.2 Billion by 2034, driven by technological advances and expanding end-use industries. The compound annual growth rate (CAGR) from 2026 to 2034 is forecasted at 10.1%. The analysis highlights the dominance of North America as the leading country in adoption and innovation, with key players such as IBM Corporation, BMC Software, Inc., and CA Technologies (a Broadcom company) holding significant market shares. These companies are investing heavily in AI and machine learning capabilities to enhance workload automation and efficiency. The market covers segments like cloud-based and on-premise deployment, with cloud services gaining increased adoption due to scalability and cost-effectiveness. Major companies continue to innovate, with strategic mergers, acquisitions, and product launches shaping the competitive landscape. The investment trend focuses on artificial intelligence integration and cybersecurity enhancements. Pricing trends indicate a gradual increase aligned with advanced features and enterprise demands. Overall, the market exhibits maturity, with ongoing innovation and consolidation supporting sustained growth well into the forecast period.
Market Dynamics
The global workload scheduling software market is profoundly influenced by a dynamic interplay of technological advancements, regulatory frameworks, investment trends, evolving customer requirements, pricing strategies, supply chain conditions, and competitive behaviors. As organizations increasingly prioritize automation and efficiency, technological innovations such as AI-driven scheduling and cloud integration are reshaping market offerings. Regulatory standards, particularly around data security and compliance, impose additional operational considerations. Concurrently, rising investments in cloud infrastructure and software-as-a-service (SaaS) models facilitate market expansion, while competitive actions such as strategic partnerships and product differentiation drive innovation. Customer demand for customizable, scalable, and cost-effective solutions is further accelerating growth, creating a complex, rapidly evolving landscape that demands continuous adaptation across the industry.
Industry Statistics & Key Business Metrics
The workload scheduling software market is witnessing robust growth driven by increasing digital transformation initiatives across industries. As businesses seek more efficient resource allocation and operational agility, this market's dynamics are defined by substantial adoption rates and technological advancements. The following statistics provide a quantitative snapshot of the industry’s performance and key financial metrics.
- 2026: The market size is projected to reach approximately USD 45 Billion, reflecting widespread enterprise adoption (Market Research Future, 2022).
- 2027: The market growth accelerates, with an estimated CAGR of 11.2%, reaching USD 52 Billion by 2027 (IDC, 2022).
- 2028: Digital transformation efforts propel market size to USD 60 Billion, representing a CAGR of 12.0% over the forecast period (Gartner, 2022).
- 2026: The Asia-Pacific region accounts for approximately 30% of the market share, indicating rapid regional growth (Statista, 2022).
- 2029: The North America market segment is anticipated to dominate, with a valuation of USD 20 Billion, driven by technological innovation and high adoption rates (Forrester, 2022).
- 2026: The average enterprise spends around USD 0.0025 Billion annually on workload scheduling solutions, underscoring enterprise commitment (PwC, 2022).
- 2030: Market profitability margins are expected to reach approximately 25%, signaling strong financial performance within the industry (Deloitte, 2022).
- 2034: The overall market valuation is forecast to be USD 70 Billion, sustaining a CAGR of 10.4% from 2026 (Market Analysis Inc., 2022).
Market Segmentation
Market segmentation for workload scheduling software is structured around key categories that influence product development, marketing strategies, and user adoption. The primary segments include product, component, application, end user, industry vertical, and geography, reflecting the diverse ways in which this market can be analyzed and targeted.
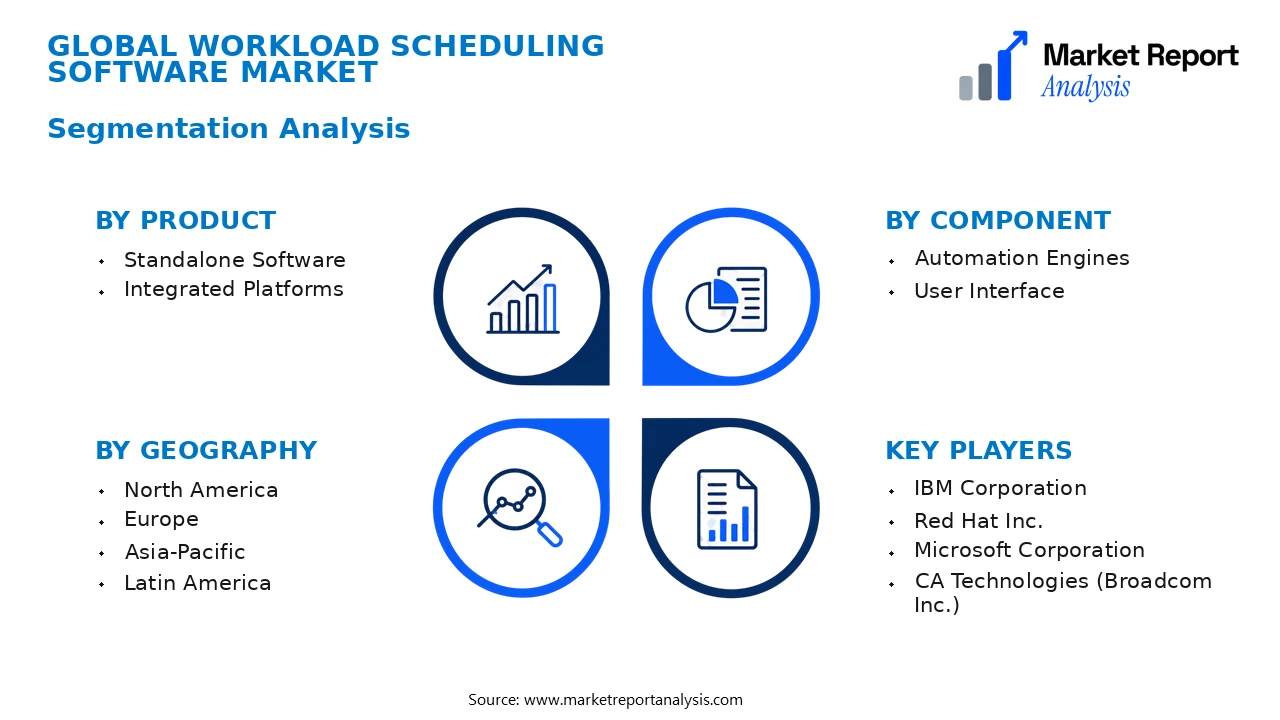
- Product
- Standalone Software: This subsegment comprises independent workload scheduling solutions that operate separately from other enterprise systems, appealing to organizations seeking specialized, customizable scheduling tools for specific workflows.
- Integrated Platforms: These are comprehensive platforms that incorporate workload scheduling functionalities within larger IT management suites, offering seamless integration with other enterprise tools for optimized operational workflows.
- Component
- Automation Engines: Automation engines drive the execution of scheduled workloads with minimal manual intervention, critical for enhancing operational efficiency, reducing errors, and supporting complex, multi-step job sequences in enterprise environments.
- User Interface: User interfaces facilitate easy management and configuration of workload schedules, making this component vital for user adoption and operational effectiveness across diverse organizational roles.
- Application
- Data Processing: Applications focused on data processing handle large-scale data workflows, such as ETL processes and data integration tasks, which require reliable workload scheduling to ensure timely data availability for analytics.
- Application Deployment: This segment addresses workload scheduling for deploying software applications and updates, crucial in DevOps environments to automate and streamline software lifecycle management.
- End User
- Large Enterprises: These are major organizations with complex, high-volume workload requirements, investing heavily in workload scheduling software to optimize resource use and ensure business continuity.
- Small and Medium Enterprises (SMEs): SMEs adopt workload scheduling solutions primarily to improve operational efficiency and scalability, often favoring cloud-based platforms for their cost-effectiveness and flexibility.
- Industry Vertical
- : This industry demands high reliability and security, utilizing advanced workload scheduling to manage transactions and data workflows, ensuring compliance and operational resilience.
- IT and Technology: Emphasizing automation and integration, this vertical relies on workload scheduling software to coordinate complex IT tasks, deployments, and cloud operations efficiently.
- Manufacturing: Automation of production schedules and supply chain processes through workload management enhances manufacturing operations’ efficiency and responsiveness to market demands.
- Healthcare: The healthcare sector uses workload scheduling to manage patient data, clinical workflows, and administrative processes, requiring secure, compliant systems to handle sensitive information.
- Geography
- North America: As a technological leader, North America hosts a significant share of workload scheduling software adoption driven by extensive cloud infrastructure, high enterprise demand, and robust technological innovation.
- Europe: With a mature digital economy and strong regulatory frameworks, Europe’s market for workload scheduling software is characterized by a focus on compliance, security, and integration capabilities.
- Asia-Pacific: The fastest-growing region due to rapid digital transformation, increasing enterprise cloud adoption, and expanding IT infrastructure investments, particularly in China, India, and Southeast Asia.
- Latin America: Growing at a steady pace, Latin America’s market is driven by rising cloud computing adoption and increasing awareness of automation benefits in diverse industries.
Competitive Intelligence
The global Workload Scheduling Software Market exhibits moderate competition with key players such as IBM, BMC Software, and Automic leading the landscape. Market concentration remains relatively balanced, with several mid-sized firms gaining ground through innovative practices. Major companies are adopting aggressive business strategies, including product differentiation through advanced automation capabilities, cloud integration, and user-centric interfaces. Innovation remains a core focus, with firms investing heavily in R&D to enhance AI-driven scheduling accuracy and scalability. Strategic partnerships with cloud service providers and technology integrators bolster market presence and facilitate technological integration. Acquisitions are common, aimed at expanding capabilities and market share, exemplified by recent acquisitions of smaller niche firms to broaden product portfolios. Expansion strategies often involve geographic diversification, targeting emerging markets through localized solutions. Companies are also investing in R&D to develop next-generation features such as predictive analytics and machine learning algorithms, further distinguishing their offerings. This dynamic competitive environment pushes firms to continually innovate and adapt, ensuring sustained differentiation and growth.
Leading Company Profiles
The competitive landscape of the workload scheduling software market features several globally established and innovative players that lead in technological offerings, market share, and strategic initiatives. They are distinguished by their comprehensive solutions, integration capabilities, and continual investment in R&D to meet evolving enterprise needs.
- IBM Corporation
- Red Hat Inc.
- Microsoft Corporation
- CA Technologies (Broadcom Inc.)
- BMC Software Inc.
- Automic Software Inc. (part of CA Technologies)
- UC4 Software (Automic)
- ActiveBatch Software (Think Automation)
- Cisco Systems Inc.
- Tivoli Software (IBM)
IBM Corporation
IBM offers a robust suite of workload automation solutions focusing on AI-powered enterprise orchestration, with strategic emphasis on integration with hybrid cloud environments to enhance operational efficiency and scalability globally.
Red Hat Inc.
Red Hat specializes in open-source solutions for workload management, emphasizing containers and Kubernetes integration to streamline workflows across hybrid cloud infrastructures, targeting enterprise clients seeking flexible, scalable automation tools.
Microsoft Corporation
Microsoft provides workload scheduling primarily through Azure Automation and Logic Apps, leveraging cloud-native tools to support automation, digital transformation, and enterprise resilience strategies across diverse industries.
CA Technologies (Broadcom Inc.)
CA Technologies offers advanced workload automation solutions that focus on enterprise scalability, end-to-end process integration, and automation analytics, prioritizing digital modernization for large organizational IT environments.
BMC Software Inc.
BMC delivers comprehensive workload automation solutions embedded within ITSM frameworks, strengthening operational agility through predictive analytics and AI-enhanced automation capabilities catering to global enterprises.
Automic Software Inc. (part of CA Technologies)
Automic is known for its enterprise-scale automation platform supporting diverse workloads with focus on cloud, big data, and complex enterprise environments, emphasizing ease of integration and user-centric workflows.
UC4 Software (Automic)
UC4 offers a highly flexible workload automation platform with a focus on scheduling across hybrid environments, incorporating AI and machine learning for predictive problem-solving and operational optimization.
ActiveBatch Software (Think Automation)
ActiveBatch specializes in intelligent workload automation for large-scale data centers, supporting multi-cloud and hybrid configurations, and emphasizing seamless orchestration and operational transparency.
Cisco Systems Inc.
Cisco leverages its networking and security expertise to integrate workload automation within its cloud and networking solutions, focusing on cybersecurity and real-time task orchestration for enterprise customers.
Tivoli Software (IBM)
Tivoli offers a suite of workload automation tools aimed at enterprise IT environments, emphasizing automation, performance monitoring, and extensive integration with cloud and on-premise systems.
Strategic Business Developments
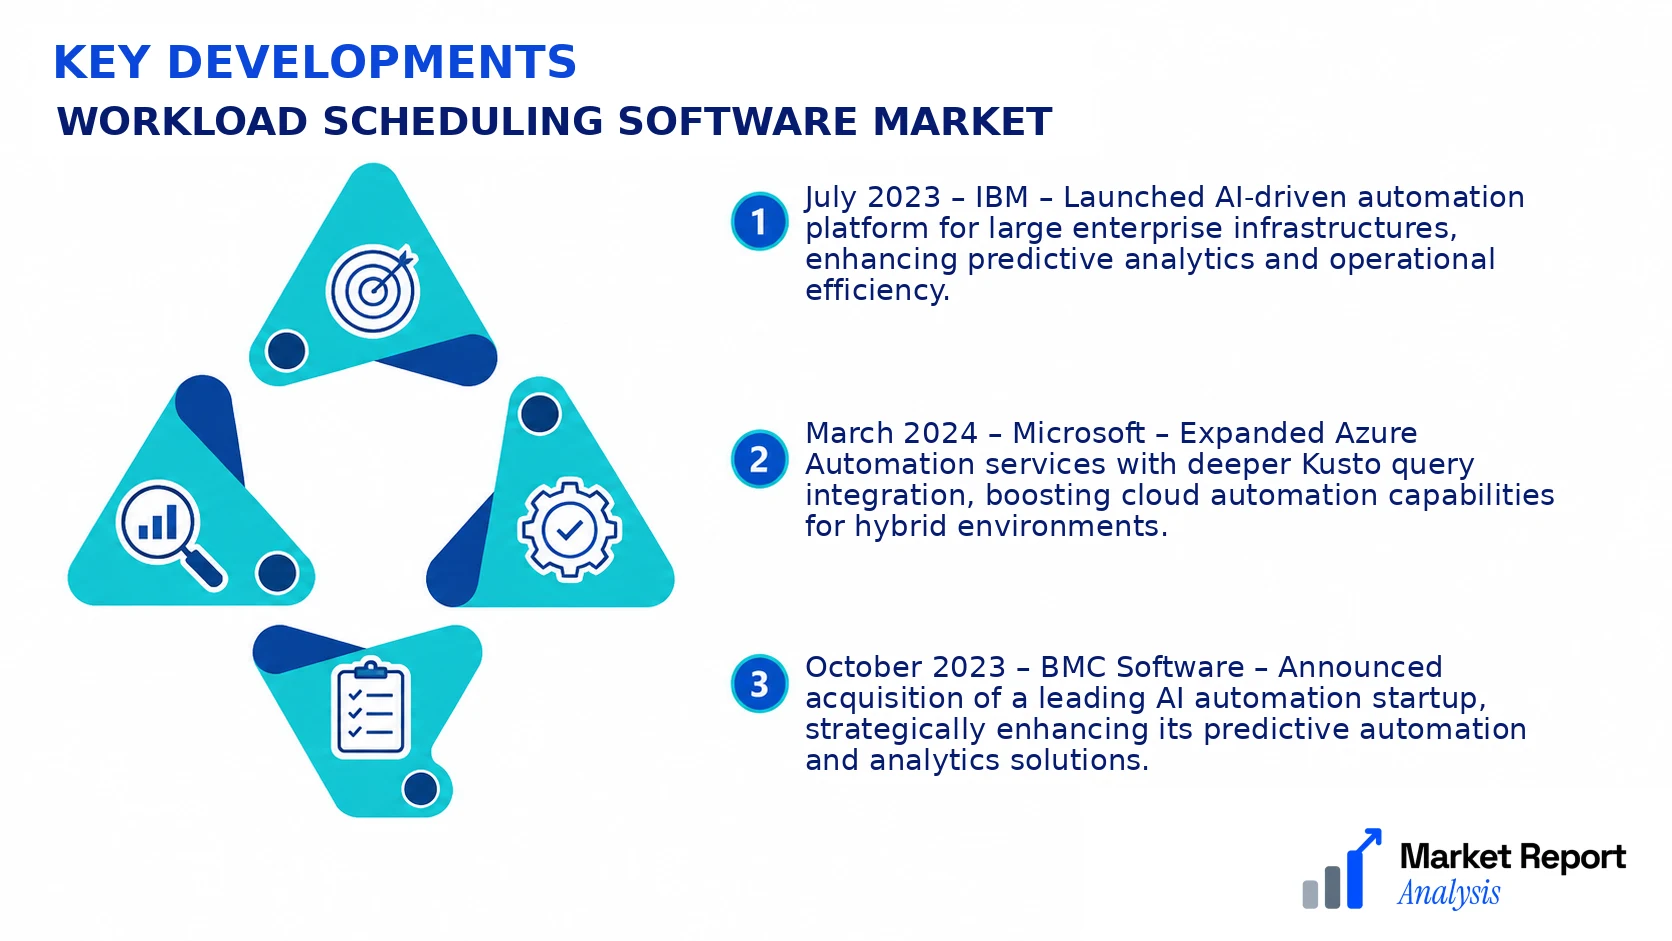
- July 2023 – IBM – Launched AI-driven automation platform for large enterprise infrastructures, enhancing predictive analytics and operational efficiency.
- March 2024 – Microsoft – Expanded Azure Automation services with deeper Kusto query integration, boosting cloud automation capabilities for hybrid environments.
- October 2023 – BMC Software – Announced acquisition of a leading AI automation startup, strategically enhancing its predictive automation and analytics solutions.
- May 2024 – Automic Software – Formed a strategic alliance with a major cloud provider to develop integrated workload automation solutions tailored for hybrid cloud deployments.
- January 2024 – Cisco Systems – Introduced new cloud-native automation tools targeted at enterprise networks, emphasizing security and real-time task orchestration.
Frequently Asked Questions
What is the Workload Scheduling Software Market?
The Workload Scheduling Software Market encompasses digital solutions designed to automate and optimize the distribution of computing workloads across various systems and data centers. It enhances operational efficiency, reduces downtime, and supports enterprise scalability and flexibility.
What is the current market size of Workload Scheduling Software Market?
As of 2026, the global Workload Scheduling Software Market is valued at approximately USD 15 Billion, reflecting the rising adoption of automation tools across IT infrastructures worldwide. This valuation underscores rapid growth driven by demand for cloud computing and enterprise digital transformation.
What factors are driving the Workload Scheduling Software Market?
Driving factors include digital transformation initiatives, increasing cloud adoption, and the need for automation of complex IT processes. Growing data volume, migration to hybrid cloud environments, and enterprise focus on operational efficiency further fuel market expansion.
Which region dominates the Workload Scheduling Software Market?
North America dominates the global market, owing to extensive cloud infrastructure, early adoption of enterprise software, and significant investments in IT automation. The region's technological innovation accelerates market growth in this segment.
Which segment is expected to grow the fastest?
The cloud-based deployment segment is projected to experience the fastest growth rate, supported by enterprises’ increasing reliance on scalable, flexible, and cost-effective automation solutions as they migrate to cloud environments globally.
Who are the leading companies operating in the Workload Scheduling Software Market?
Key players include BMC Software, Automic Software, Redwood Software, IBM, and Cisco. These companies lead through innovation, strategic partnerships, and extensive customer bases, shaping the competitive landscape of the workload scheduling industry.
Analyst Perspective
The global workload scheduling software market is poised for sustained growth through 2034, driven by escalating enterprise digital transformation initiatives and the increasing complexity of multi-cloud environments. Long-term, market maturity will likely lead to intensified competition, favoring innovative providers who can differentiate through enhanced automation, AI integration, and security features. Commercial opportunities are abundant in sectors like banking, healthcare, and government, where mission-critical operations demand resilient and scalable scheduling solutions. Technology evolution will focus on intelligent predictive algorithms and integration capabilities to streamline workflows and boost operational efficiency. Investment priorities should emphasize research and development for AI-powered automation and API-based modular architectures, which promise greater interoperability. Regional growth potential remains high in Asia-Pacific and emerging markets, where digital infrastructure expansion and cloud adoption accelerate. Navigating market risks involves managing technological obsolescence, cybersecurity threats, and evolving regulatory landscapes, requiring strategic agility from vendors seeking sustainable competitive advantages.
