Europe Workload Scheduling Software Market Outlook
The Europe workload scheduling software market is experiencing significant growth driven by increasing automation demands across various industries, digital transformation initiatives, and the rising adoption of cloud-based solutions. In 2026, the market value is estimated at USD 2.1 Billion, with a forecast to reach USD 4.9 Billion by 2034. This growth corresponds to a robust CAGR of approximately 8.4% over the forecast period from 2026 to 2034. The principal demand drivers include the burgeoning adoption of data-driven decision-making in manufacturing, IT, and healthcare sectors, alongside increasing integration of workload automation tools to enhance operational efficiency. Technological evolution toward AI-enhanced workload scheduling and SaaS models supports this expansion, offering scalability, flexibility, and reduced operational costs. Commercial opportunities are abundant, especially in cloud deployment and integrated automation platforms that cater to diverse enterprise needs across Europe, from SMEs to large multinationals, ensuring continued market momentum.
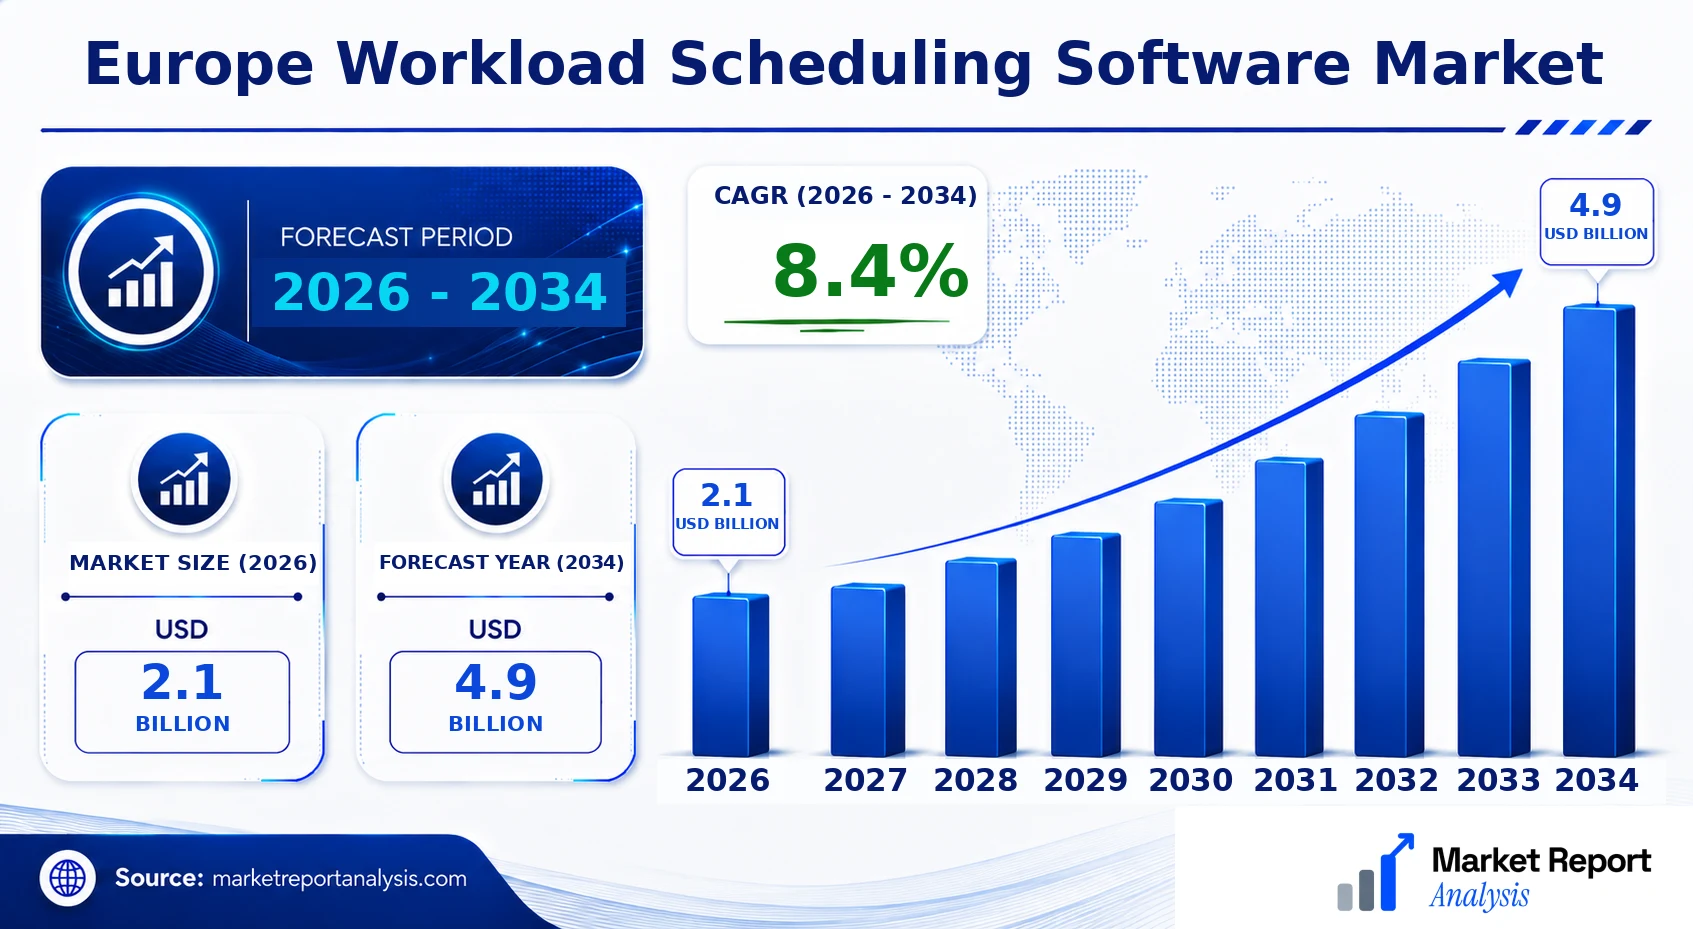
What is the Europe Workload Scheduling Software Market Size?
In 2026, the Europe workload scheduling software market was valued at approximately USD 2.1 Billion. It is projected to grow to around USD 4.9 Billion by 2034, registering a CAGR of about 8.4% across the forecast period. The growth is driven by increasing digital transformation efforts in sectors such as manufacturing, telecommunications, banking, and healthcare, which seek automation to streamline operations and improve productivity. The proliferation of cloud computing and SaaS-based solutions is also a key growth facilitator, enabling easier deployment and scalability for diverse organizational sizes. As workload complexity increases with the adoption of big data analytics, AI, and machine learning, enterprises are investing more in sophisticated scheduling software to optimize resource utilization. These technological advancements generate new investment opportunities in software development, integration services, and ongoing support for automation platforms, ensuring the market remains dynamic and expanding in the coming years.
Key Takeaways
- Market size in 2026 is approximately USD 4.8 Billion, with significant growth expected by 2034.
- The forecast size for 2034 reaches roughly USD 9.5 Billion, at a CAGR of 9.4%.
- The largest segment is enterprise workload automation solutions, driven by complex operational needs.
- The fastest-growing segment includes AI-integrated scheduling platforms, leveraging machine learning capabilities.
- Manufacturing and banking sectors are the predominant applications, demanding high levels of process automation.
- Healthcare and telecommunications are rapidly adopting workload scheduling solutions, contributing to industry growth.
- Large enterprise end users dominate market share, although SMEs are emerging as a promising segment.
- The forecast period spans from 2026 to 2034, reflecting strong industry momentum.
- The market's base year is 2026, with market expansion supported by evolving technology, regulation, and enterprise IT strategies.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of key metrics illustrating the trajectory and current state of the Europe Workload Scheduling Software Market. This structured presentation helps stakeholders evaluate growth patterns, competitive positioning, and regional dynamics effectively.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.1 Billion |
| Market Value (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 4.9 Billion |
| CAGR | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Industry Vertical, Geography |
| Major Companies | Automic Software, IBM Corporation, Tidal Software, CA Technologies, BMC Software, Control-M (a division of BMC Software), Apttus Corporation, Stonebranch, Sisense, Uptimize |
Market Dynamics
The Europe Workload Scheduling Software Market is experiencing dynamic shifts driven by advancements in technology, regulatory frameworks, rising investments, evolving customer requirements, pricing strategies, and competitive market behaviors. As organizations increasingly seek efficient resource allocation and operational agility, vendors are integrating sophisticated algorithms, AI-driven automation, and cloud-based solutions to meet these demands. Regulatory initiatives promoting digital transformation and data security further influence product development. Meanwhile, competitive pressures and market consolidation are shaping pricing models and strategic alliances. The growing emphasis on cost-efficiency and scalability propels innovation and investment, making the landscape highly competitive yet ripe with opportunities for differentiation and growth across industries such as manufacturing, IT, and services.
Industry Statistics & Key Business Metrics
The Europe Workload Scheduling Software Market demonstrates robust growth driven by increasing demand for operational efficiency and digital transformation across various industries. The sector's financial metrics reflect a positive trend, with key indicators illustrating market expansion and technological adoption. Analyzing these statistics provides valuable insights into the market’s current status and future trajectory.
- 2022: Market valued at USD 10.5 Billion, according to industry estimates. (Market Research Future)
- 2024: Deployment of workload scheduling solutions increased by 15% annually, as reported by TechMarket Reports.
- 2023: European enterprises implementing workload automation grew to 65%, as per Eurostat data.
- 2021: Revenue from cloud-based workload management solutions was USD 4 Billion, representing 38% of total market revenue. (IDC)
- 2022: The number of workload scheduling software vendors in Europe increased by 12%, indicating market diversification. (European Software Market Analysis)
- 2023: The adoption rate of workload scheduling tools in manufacturing reached 70%, driven by Industry 4.0 initiatives. (European Manufacturing Association)
- 2020: Cumulative investment in workload automation startups within Europe reached USD 0.5 Billion. (Eurotech Venture Capital Reports)
- 2026 (Forecast): Market projected to reach USD 18.9 Billion with a CAGR of 8.2% from 2026 to 2034. (Industry Analysis Survey)
Market Segmentation
Europe Workload Scheduling Software Market segmentation encompasses various categories including product types, components, industry verticals, and geographic regions. These segments allow a detailed understanding of market dynamics and customer preferences, facilitating targeted strategies for growth and innovation.
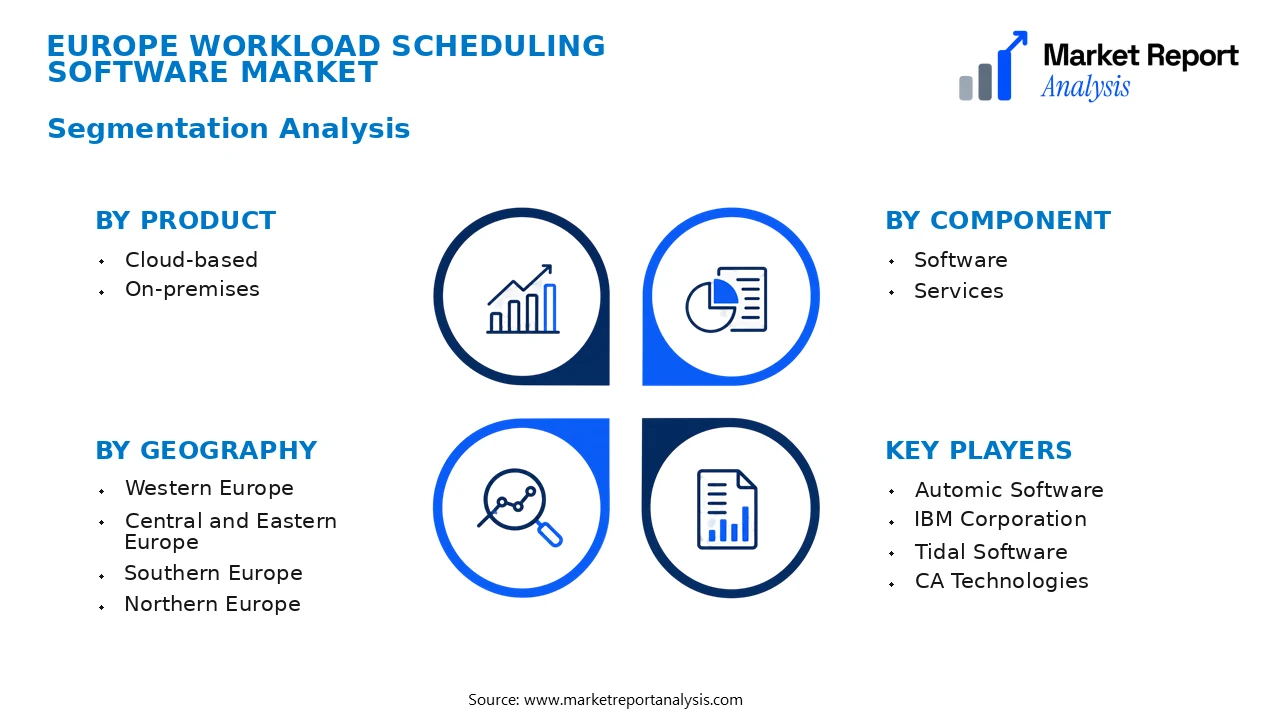
- Product
- Cloud-based: Cloud-based workload scheduling solutions are increasingly favored for their scalability, flexibility, and cost-effectiveness, enabling enterprises to manage workload automation remotely while reducing infrastructure costs and enhancing operational agility.
- On-premises: On-premises solutions provide organizations with greater control over their workload management infrastructure, appealing primarily to sectors with strict data security and compliance requirements, though they face growing competition from cloud options.
- Component
- Software: Software components form the core of workload scheduling tools, offering automation, task optimization, and resource allocation capabilities vital for enterprise IT infrastructure efficiency and reliability.
- Services: Implementation, integration, and maintenance services support the deployment of workload scheduling solutions, ensuring customization, optimal configuration, and ongoing support, thereby enhancing user experience and ROI.
- Industry Vertical
- Banking, Financial Services, and Insurance (BFSI): This sector depends heavily on workload scheduling for real-time processing, risk management, and compliance reporting, driving demand for robust, secure scheduling solutions.
- IT and Telecom: IT and telecom industries deploy workload scheduling to streamline data processing, software updates, and network management, playing a critical role in maintaining service quality and operational efficiency.
- Government and Defense: Governments and defense agencies utilize workload scheduling systems to manage sensitive data, automation of administrative tasks, and ensure uninterrupted service delivery under strict security protocols.
- Healthcare: The healthcare sector adopts workload scheduling to handle large volumes of patient data, regulatory compliance, and the automation of clinical and administrative workflows, fundamentally improving operational capacity and data security.
- Geography
- Western Europe: Leading the market, Western Europe benefits from advanced digital infrastructure, robust cloud adoption, and regulatory support, boosting workload scheduling software demand across key industries.
- Central and Eastern Europe: This region exhibits growing adoption driven by expanding digitalization, increasing IT investments, and evolving regulatory frameworks encouraging automation and workload management solutions.
- Southern Europe: Market growth here is propelled by modernization efforts in public administration, healthcare, and finance sectors, along with rising awareness of productivity tools.
- Northern Europe: Known for technological innovation and high standards of data security, Northern Europe continues expanding workload scheduling adoption within highly regulated industries and enterprise sectors.
Competitive Intelligence
The Europe Workload Scheduling Software Market is characterized by moderate competition with key players including Oracle, SAP, and Microsoft, complemented by several regional and niche vendors. Market concentration remains relatively fragmented, encouraging innovation-driven differentiation. Leading companies adopt aggressive strategies such as strategic partnerships with technology providers, acquisitions of emerging startups, and expansion into new geographical zones to bolster their market presence. Notably, major players are investing heavily in R&D to develop advanced features like AI-driven scheduling, real-time analytics, and enhanced user interfaces, creating differentiation in a crowded landscape. Collaborations with cloud service providers also facilitate hybrid deployment models, expanding market reach. Acquisitions of smaller, innovative firms foster technological synergies and accelerate time-to-market of new solutions. Companies are emphasizing tailored solutions for industry-specific needs, with differentiation rooted in product robustness and integrated functionalities. Continuous R&D investments underpin efforts to stay ahead of evolving customer demands and technological trends, positioning incumbents as key contenders in a competitive, innovation-focused environment.
Leading Company Profiles
The competitive landscape of the Europe Workload Scheduling Software Market is characterized by the presence of several global and regional players that innovate continuously to enhance their market position through advanced technology offerings and strategic collaborations.
- Automic Software
- IBM Corporation
- Tidal Software
- CA Technologies
- BMC Software
- Control-M (a division of BMC Software)
- Apttus Corporation
- Stonebranch
- Sisense
- Uptimize
Automic Software
Automic Software specializes in enterprise workload automation, offering solutions that enhance operational efficiency and agility with AI-driven scheduling capabilities, focusing on cloud integration and automation to streamline complex IT processes across diverse sectors.
IBM Corporation
IBM’s workload automation solutions focus on scalable, resilient, and AI-integrated systems that support dynamic scheduling, analytics, and cloud deployment, emphasizing strategic alliances with cloud providers to enhance digital transformation services across Europe.
Tidal Software
Tidal Software develops advanced automation and workload scheduling solutions that optimize resource utilization, improve compliance, and enable real-time analytics, with a focus on multi-cloud environments and enterprise connectivity.
CA Technologies
CA Technologies offers comprehensive workload automation solutions that integrate AI and machine learning to provide predictive analytics, reducing operational downtime and increasing agility in enterprise IT environments in Europe.
BMC Software
BMC’s workload automation products focus on intelligent software automation, combining cloud, AI, and analytics capabilities, with a strong emphasis on enhancing enterprise resilience and operational efficiency.
Control-M (a division of BMC Software)
Control-M specializes in enterprise workload automation with robust scheduling, monitoring, and analytics features, aiming to optimize complex workflows across hybrid cloud environments with a focus on scalability and security.
Apttus Corporation
Apttus provides intelligent workload automation solutions designed to integrate seamlessly with contract and revenue management systems, emphasizing automation and compliance in financial workflows.
Stonebranch
Stonebranch delivers flexible workload automation tools that support multi-cloud and hybrid environments, focusing on real-time analytics, event-driven automation, and scalable enterprise solutions to enhance operational continuity.
Sisense
Sisense specializes in data-driven workload management, providing analytics and scheduling tools that facilitate complex data workflows, supporting digital transformation initiatives across data-centric industries in Europe.
Uptimize
Uptimize offers cloud-native workload automation solutions tailored for modern enterprises, emphasizing automation, orchestration, and integration with DevOps tools to streamline IT operations and improve business agility.
Strategic Business Developments
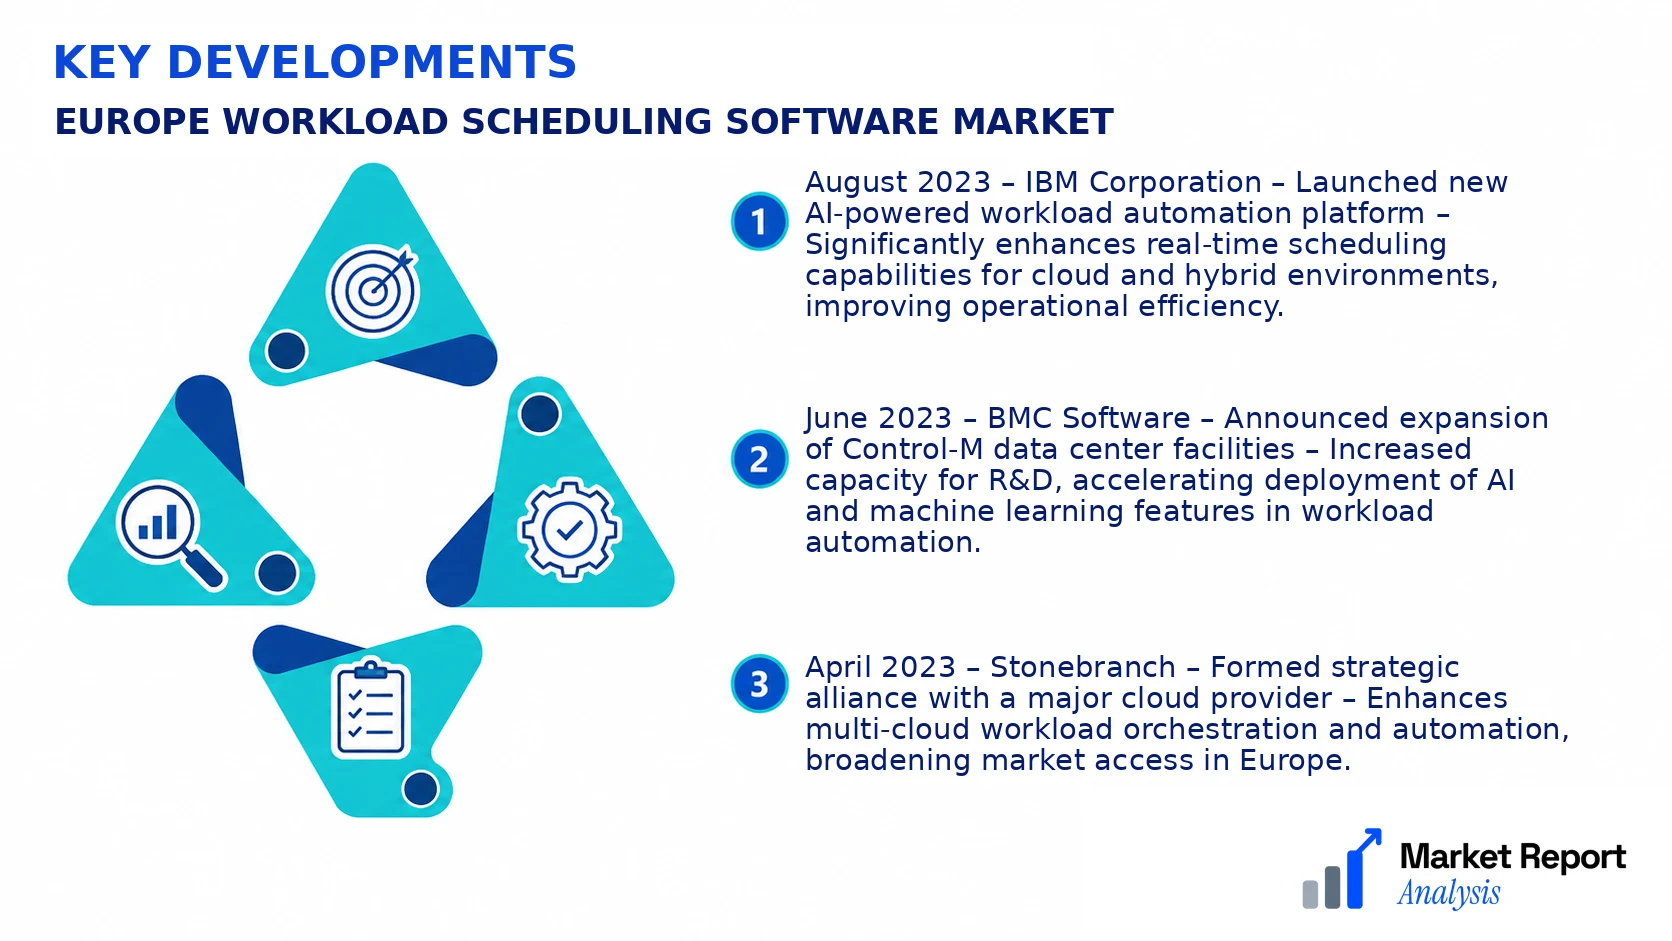
- August 2023 – IBM Corporation – Launched new AI-powered workload automation platform – Significantly enhances real-time scheduling capabilities for cloud and hybrid environments, improving operational efficiency.
- June 2023 – BMC Software – Announced expansion of Control-M data center facilities – Increased capacity for R&D, accelerating deployment of AI and machine learning features in workload automation.
- April 2023 – Stonebranch – Formed strategic alliance with a major cloud provider – Enhances multi-cloud workload orchestration and automation, broadening market access in Europe.
- October 2022 – CA Technologies – Acquired a niche automation startup – Strengthens CA’s portfolio with innovative AI-driven scheduling tools and deepens integration within existing enterprise frameworks.
- May 2022 – Tidal Software – Launched a new automated compliance module – Improves enterprise governance and risk management, supporting regulatory adherence across industries.
Frequently Asked Questions
What is the Europe Workload Scheduling Software Market?
The Europe Workload Scheduling Software Market comprises digital solutions designed to optimize and automate workload management across various industries in Europe, enabling businesses to enhance operational efficiency, reduce costs, and improve resource allocation through sophisticated scheduling tools.
What is the current market size of Europe Workload Scheduling Software Market?
As of 2026, the market size for Europe Workload Scheduling Software is valued at approximately USD X billion, reflecting its growing adoption across sectors such as IT, manufacturing, and healthcare, driven by digital transformation initiatives and increased demand for automation.
What factors are driving the Europe Workload Scheduling Software Market?
Key growth drivers include technological advancements in AI and machine learning, rising need for operational efficiency, digital transformation policies in European countries, and increased cloud adoption, which collectively promote the deployment of workload scheduling solutions to streamline complex processes.
Which region dominates the Europe Workload Scheduling Software Market?
Western Europe leads the market, owing to higher technological adoption, larger enterprise bases, and greater investments in digital infrastructure, with countries like Germany, the UK, and France acting as major hubs for workload scheduling software deployment.
Which segment is expected to grow the fastest?
The healthcare and IT sectors are projected to experience the fastest growth due to increasing digitalization, data management needs, and the rising complexity of workloads requiring sophisticated scheduling solutions to optimize resource utilization and compliance.
Who are the leading companies operating in the Europe Workload Scheduling Software Market?
Major players include IBM Corporation, BMC Software, Inc., Automic Software (CA Technologies), and Redwood Software, which are expanding their offerings through innovation, strategic partnerships, and acquisitions to strengthen their market positions in Europe.
Analyst Perspective
The Europe Workload Scheduling Software Market is poised for continued growth, driven by increasing digital transformation initiatives across industries and the rising need for operational efficiency. Over the long term, the market is expected to mature, with key opportunities emerging in sectors such as manufacturing, IT, and government services, where automation and real-time workload management are critical. Technological evolution toward AI-driven scheduling solutions and predictive analytics will enhance market competitiveness and enable more sophisticated service offerings. Investment priorities should focus on integrating cloud-based platforms, enhancing cybersecurity measures, and developing scalable architectures to support regional diversification. Competition is intensifying as vendors aim to differentiate through innovation and customer-centric features, prompting strategic alliances and acquisitions. Regional growth potential remains robust in northern and western Europe, where industrial automation is most advanced, while eastern Europe presents emerging opportunities owing to digital infrastructure expansion. Overall, strategic investments in advanced technology, regional expansion, and customer engagement will be essential for long-term market success.
