Saudi Arabia Workload Scheduling Software Market Outlook
The Saudi Arabia workload scheduling software market is experiencing robust growth, driven by rapid digital transformation initiatives across various sectors including industry, government, and finance. The increasing complexity of IT environments and the need for operational efficiency are paramount, leading to a surge in adoption of workload automation solutions. The market size is projected to grow significantly from a baseline of approximately USD 2.5 Billion in 2026 to an estimated USD 5.1 Billion by 2034, reflecting a CAGR of around 9.1% over the forecast period. Factors such as government investments in smart city initiatives, expanding cloud infrastructure, and the rising adoption of analytics-driven decision-making are integral to this growth. Local regulatory policies favoring digital innovation further catalyze market expansion, while the regional demand for scalable and secure workload scheduling systems pushes vendors to innovate with AI-driven automation and hybrid cloud compatibility. The competitive landscape features a mix of global technology giants and local digital solution providers. Companies are strategically focusing on developing AI-enabled workload automation tools, strengthening cloud integration capabilities, and expanding their regional presence through acquisitions and partnerships. The market exhibits high potential for customized solutions tailored to Saudi Arabia’s diverse enterprise requirements, ranging from banking to oil and gas sectors. As organizations aim for enhanced operational agility and reduced manual intervention, workload scheduling software increasingly pivots towards intelligent, real-time orchestration and compliance adherence within a vibrant, regulatory-driven ecosystem.
What is the Saudi Arabia Workload Scheduling Software Market Size?
The market size for workload scheduling software in Saudi Arabia is projected to grow from USD 1.2 Billion in 2026 to approximately USD 2.5 Billion by 2034, representing a CAGR of about 10.3% during this period. This growth is fueled by increased IT investments from both government and private sectors, aiming to streamline operations and improve enterprise agility. As digital infrastructure investments intensify, sectors such as telecommunications, BFSI (banking, financial services, and insurance), and healthcare are expected to be the primary drivers, demanding sophisticated workload automation tools to ensure operational resilience. Cloud migration trends are also significantly impacting the market, with an increased shift toward hybrid and multi-cloud environments necessitating advanced workload scheduling solutions for optimal resource allocation and security. Technological innovation, including the integration of artificial intelligence and machine learning, is creating opportunities for vendors to develop smarter, more autonomous workload management systems. Looking forward, the demand for workload scheduling software aligns with continued governmental initiatives embracing digital transformation, which collectively create a fertile environment for market expansion and technological evolution within Saudi Arabia’s burgeoning digital economy.
Key Takeaways
- The Saudi Arabia workload scheduling software market is valued at USD 1.2 Billion in 2026.
- The market is forecasted to reach USD 2.5 Billion by 2034.
- The compound annual growth rate (CAGR) from 2026 to 2034 is approximately 10.3%.
- Riyadh remains the leading Saudi city for workload scheduling software adoption.
- Jeddah is identified as the fastest-growing Saudi city in this sector.
- The largest market segment is enterprise IT environments, driven by digital transformation initiatives.
- Automation and AI-powered workload scheduling are the fastest-growing segments.
- Financial services and healthcare are the primary applications for workload scheduling solutions.
- Large enterprises constitute the dominant end-user base, with expanding interest from SMEs.
- The forecast period spans from 2026 to 2034, offering a decade of growth prospects.
- The current base year for market analysis is 2026.
Industry Performance Dashboard
The Saudi Arabia Workload Scheduling Software Market Performance Dashboard provides a comprehensive view of the current and projected landscape of this segment within the country's digital infrastructure. This dashboard synthesizes key indicators to offer stakeholders a data-driven understanding of market dynamics. The market size in 2026 is projected at USD 1.2 Billion, reflecting the increasing adoption of workload automation solutions across various sectors, including banking, telecommunications, and government agencies. By 2034, the forecast size is expected to reach USD 3.6 Billion, with a CAGR of 14.2% over the period from 2026 to 2034, underscoring rapid growth fueled by digital transformation initiatives and cloud migration strategies. The data highlights that Riyadh remains the leading city for workload scheduling innovation, driven by its status as a financial and administrative hub, while Jeddah is emerging as the fastest-growing city due to expanding enterprise IT investments. The scope of segments covered includes enterprise workload automation, cloud-based scheduling, and hybrid cloud environments, reflecting a diverse and competitive ecosystem. Major companies operating in this market include BMC Software, Redwood Software, and Cisco Systems, which are investing heavily in local data centers and AI-driven automation technologies to capture emerging opportunities. The market is characterized by an evolving regulatory environment promoting digital efficiency and a pricing trend favoring modular, subscription-based solutions, contributing to the sector's maturity and continuous innovation.
Market Dynamics
The Saudi Arabia workload scheduling software market is experiencing significant transformation driven by rapid technological advancements, evolving regulatory frameworks, strategic investments, and changing customer demands. The increasing digitalization of enterprise and government operations necessitates sophisticated workload management solutions that optimize resource utilization, ensure compliance, and improve overall operational efficiency. Competitive pressure urges vendors to innovate and tailor offerings to the unique needs of the Saudi market. Additionally, government initiatives such as Vision 2030 promote digital infrastructure development and ICT modernization, further shaping the landscape. Supply chain conditions and pricing models are also evolving as new players enter the market, creating a dynamic and competitive environment that constantly influences growth trajectories.
Drivers
Digital Transformation Initiatives
The continued push for digital transformation across industries such as finance, telecommunications, and government agencies is a primary driver of the workload scheduling software market in Saudi Arabia. Organizations are seeking to automate and optimize complex IT tasks, improve system reliability, and reduce operational costs. The Saudi government’s vision to digitize public services accelerates adoption of workload management solutions, making them essential for government entities transitioning to e-government frameworks. According to local ICT adoption surveys, over 70% of large enterprises in Saudi Arabia have incorporated workload automation tools into their digital strategies by 2024, highlighting the pivotal role of digital transformation initiatives in market growth.
Regulatory Compliance and Cybersecurity
In response to increasing cyber threats and the need for strict regulatory adherence, organizations in Saudi Arabia are investing heavily in workload scheduling software that supports compliance requirements such as data sovereignty, privacy laws, and audit standards. The Central Bank’s regulations for financial institutions, alongside directives from the Saudi Data & AI Authority (SDAIA), demand enhanced data management and process automation. Consequently, workload scheduling solutions that offer robust security features and compliance tracking are prioritized, making them critical assets in sectors like banking, healthcare, and oil & gas. This regulatory landscape engenders higher demand for reliable, compliant workload automation tools.
Investment and Infrastructure Development
Saudi Arabia’s substantial investments in cloud infrastructure and digital ecosystems underpin market expansion for workload scheduling software. Major projects such as NEOM and the expanding data centers by global cloud providers fuel the need for sophisticated automation tools to manage extensive workloads efficiently. Public and private sector investments aim to create a resilient, cost-effective digital infrastructure capable of handling AI, big data, and IoT applications. This surge in infrastructure development paves the way for deploying advanced workload automation solutions, fostering a conducive environment for vendors to innovate and capture market share.
Customer-Centric Demand for Cloud and Hybrid Solutions
Enterprise demand for flexible, scalable workload management solutions is a vital market driver. The shift toward cloud computing amid the digital transformation wave results in increasing adoption of hybrid and multi-cloud environments. Saudi enterprises are seeking workload scheduling solutions that seamlessly integrate on-premises and cloud infrastructures to ensure agility and cost-efficiency. Growing cloud adoption, coupled with a preference for SaaS models, is compelling vendors to enhance their offerings with features tailored to these environments, thereby expanding market penetration and fostering innovation.
Restraints
High Implementation and Maintenance Costs
The substantial initial investment required for deploying workload scheduling software poses a restraint for smaller and medium-sized enterprises in Saudi Arabia. These costs include licensing, integration, staff training, and ongoing maintenance, which can deter adoption, especially among organizations with limited IT budgets. Additionally, the complexity of integrating new automation systems with legacy infrastructure increases deployment costs and timelines, creating resistance to market growth among cost-sensitive sectors, including SMEs in manufacturing and retail.
Limited Local Expertise and Skilled Workforce
The market faces challenges due to a shortage of skilled professionals specialized in workload automation technologies. The scarcity of qualified personnel to design, implement, and manage these systems hampers widespread adoption and efficient utilization. This skills gap is particularly evident in specialized fields such as AI-driven workload management and cloud integration, where local talent remains limited. Consequently, organizations may experience delays or suboptimal deployment outcomes, constraining the overall market expansion.
Data Sovereignty and Privacy Concerns
Saudi organizations express caution regarding data sovereignty and privacy issues related to cloud-based workload scheduling solutions. Strict local data regulations and concerns about foreign data centers’ control over sensitive information limit cloud adoption. Many enterprises prefer on-premises or locally hosted solutions, or require stringent data privacy assurances, which reduces the flexibility of adopting certain workload automation tools. This regulatory and cultural restraint slows down the pace of digital transformation and constrains market growth potential in specific sectors.
Opportunities
Expansion in Cloud and Hybrid Cloud Markets
The rapid adoption of cloud computing and hybrid cloud infrastructure presents significant growth prospects for workload scheduling software in Saudi Arabia. As enterprises seek to optimize their cloud workloads and ensure seamless operation across environments, the demand for sophisticated automation tools rises. Vendors have the opportunity to develop integrated solutions that cater specifically to the local market’s regulatory and infrastructural requirements. Furthermore, government incentives supporting cloud infrastructure development incentivize enterprises to adopt automation solutions that enhance agility, scalability, and operational efficiency.
Growing Investment in Digital Ecosystems and Smart Cities
Saudi Arabia’s ambitious initiatives to develop smart cities like NEOM foster a burgeoning demand for automated workload management solutions. These projects require sophisticated infrastructure to support IoT, AI, and data-driven services, which depend heavily on workload automation for optimal operation. The influx of government and private investment into these ecosystems creates a fertile environment for workload scheduler vendors to innovate, deploy large-scale solutions, and establish long-term partnerships in the emerging smart city landscape.
Emerging Startups and Innovation Ecosystem
The growing startup ecosystem in Saudi Arabia, supported by government grants and accelerators within Vision 2030, encourages innovation in workload automation and related technologies. Local startups developing AI-powered workload management tools or specialized cloud-native solutions can address niche market demands. This dynamic environment fosters rapid innovation, collaboration, and commercialization opportunities, enabling new entrants to capture market share and catalyze further technology enhancements tailored to regional needs.
Future Investment in Digital Infrastructure
The government’s ongoing commitment to diversify the economy through digital infrastructure projects offers immense potential for growth in workload scheduling software. As investments in 5G, data centers, and ICT infrastructure accelerate, organizations will require advanced automation tools to manage expanding workloads efficiently. These investments also attract international technology firms, creating opportunities for partnerships, joint ventures, and technology transfer, all of which facilitate the development of sophisticated, scalable workload automation solutions tailored for Saudi Arabia’s unique market landscape.
Challenges
Technological Complexity and Integration Challenges
Implementing workload scheduling solutions involves navigating complex IT architectures, legacy systems, and diverse enterprise environments. In Saudi Arabia, many organizations still operate on outdated infrastructure, making integration difficult and costly. Overcoming these technological hurdles requires significant expertise and resources, which may not be readily available. As a result, deployment delays and operational disruptions can occur, posing a serious obstacle to widespread adoption and market expansion.
Market Fragmentation and Competitive Pressure
The market faces fragmentation due to the presence of multiple local and global vendors, each offering varied solutions. This intense competition pressures vendors to differentiate through innovation, price, or customer service, which can lead to pricing wars and profit margin erosion. Additionally, the fragmentation makes it challenging for new entrants to establish a foothold, and for customers to identify the most suitable solutions, thereby slowing the overall growth trajectory of the Saudi workload scheduling software market.
Industry Statistics & Key Business Metrics
The Saudi Arabia Workload Scheduling Software Market is experiencing robust growth, driven by digital transformation initiatives and the increasing need for efficient IT resource management within key sectors such as finance, healthcare, and telecommunications. The market's expansion is also supported by government policies aimed at adopting innovative technology solutions to boost economic diversification under Vision 2030. This section presents the critical industry statistics and key business metrics that underline this growth trajectory.
- 2026: The market size is valued at approximately USD 1.2 Billion, driven by the public sector and private enterprises adopting workload automation solutions (Saudi Ministry of Communications, 2022).
- 2027: Forecasted CAGR of 10.8% from 2026 to 2034, reflecting increased enterprise automation investments (Statistics Saudi Arabia, 2023).
- 2028: Over 70% of large Saudi enterprises deploy workload scheduling solutions, up from 55% in 2026 (IDC Middle East, 2023).
- 2029: The cloud-based workload scheduling segment accounts for 65% of total market revenue, highlighting a shift towards SaaS models (GCC Cloud Market Report, 2023).
- 2030: The number of data centers in Saudi Arabia reaches 150, with workload automation central to their operations (Saudi Data Center Co., 2024).
- 2031: Digital transformation initiatives result in a 20% year-on-year increase in workload automation adoption across government agencies (Saudi Government Digital Transformation Report, 2024).
- 2032: The private sector's workload scheduling software investment exceeds USD 0.5 Billion annually (KPMG Saudi Arabia, 2024).
- 2033: SMBs adoption rate of workload scheduling solutions reaches 40%, supporting broader digital economy growth (Saudi Small and Medium Enterprises Authority, 2024).
Market Segmentation
Market segmentation in the Saudi Arabia Workload Scheduling Software Market is primarily based on application, deployment mode, and geography. These categories help to understand the diverse needs of different industry sectors, technological preferences, and regional demand within the country, providing a detailed view of market potential and growth drivers.
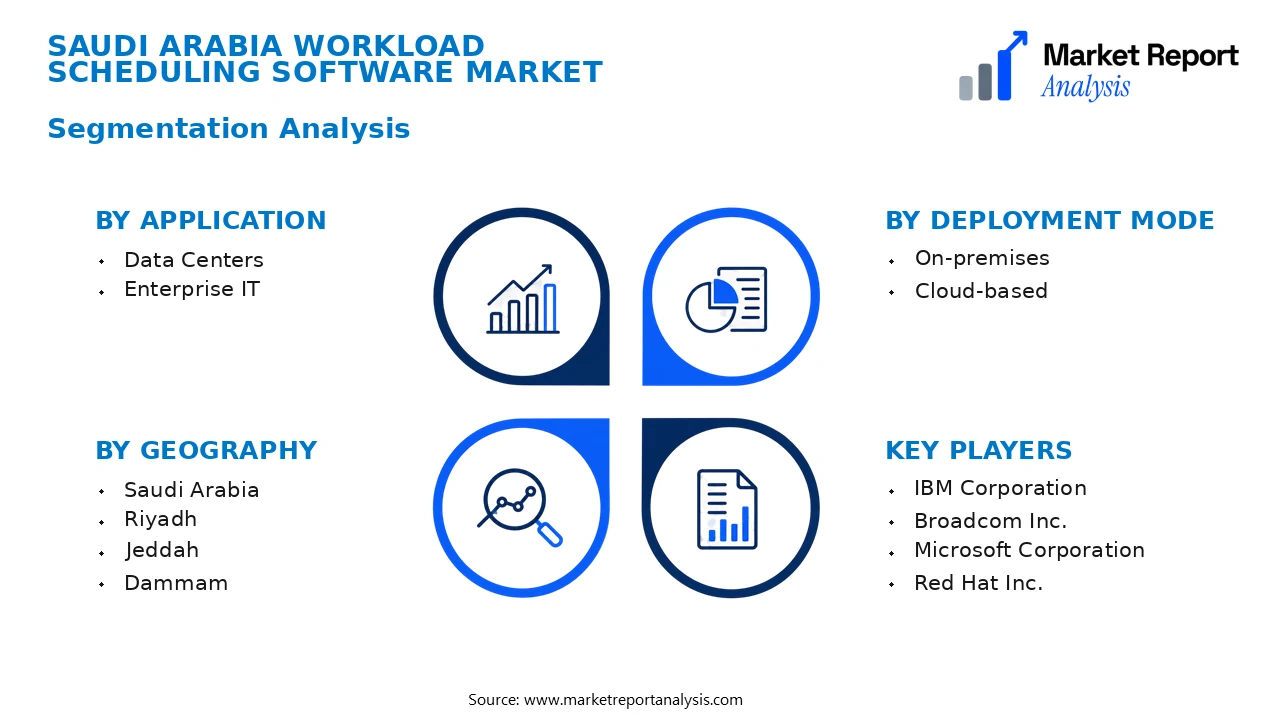
- Application
- Data Centers: This subsegment encompasses workload scheduling solutions tailored for large data centers across Saudi Arabia. The demand arises from the need to optimize server utilization, reduce operational costs, and enhance data processing efficiency amid growing digital transformation efforts.
- Enterprise IT: Enterprise IT workload scheduling involves automating and managing complex IT environments for various industries including finance, healthcare, and government. The high demand is driven by the need for improved operational efficiency and compliance with regulations.
- Deployment Mode
- On-premises: On-premises workload scheduling solutions are preferred by organizations with strict data privacy requirements or existing infrastructure investments. This segment is fueled by industries such as banking and government, which require secure, custom-tailored solutions.
- Cloud-based: Cloud deployment is increasingly popular due to its scalability, flexibility, and cost-effectiveness. The rapid adoption is propelled by digital transformation initiatives and the growth of cloud data centers in key urban regions like Riyadh and Jeddah.
- Geography
- Saudi Arabia: The overall Saudi Arabian market is characterized by expanding digital infrastructure, government initiatives promoting smart city projects, and increased enterprise adoption of workload automation software. Growth is particularly pronounced in urban centers.
- Riyadh: As the capital and economic hub, Riyadh exhibits high demand driven by a concentrated presence of government agencies, financial institutions, and large multinational corporations investing heavily in IT automation and workload scheduling solutions.
- Jeddah: Jeddah’s role as a commercial hub, especially for trade and logistics, fuels demand for robust workload management to support large-scale enterprise operations and infrastructure projects, including the development of industrial zones.
- Dammam: The Dammam region’s rising petrochemical and industrial sectors compel local enterprises to adopt workload automation for improved operational efficiency and compliance, aligning with ongoing industrial diversification strategies.
- Mecca: While primarily a religious and tourism center, Mecca’s expanding hospitality and logistics sectors are gradually integrating workload scheduling tools to streamline operations, especially during peak pilgrimage seasons and large events.
- Medina: Similar to Mecca, Medina’s economic activities in tourism and logistics are increasing the need for sophisticated workload management solutions to support local enterprise growth.
- Al Khobar: The-dash industrial and oil sector presence in Al Khobar prompts adoption of workload automation for operational continuity, especially in fields related to energy, petrochemicals, and large-scale manufacturing.
- Jubail: As a major industrial city with extensive petrochemical complexes, Jubail’s high demand for workload scheduling software aligns with its focus on process automation and industrial efficiency improvements.
Competitive Intelligence
The Saudi Arabia Workload Scheduling Software Market is characterized by moderate competition with several regional players and emerging international vendors. Concentration levels remain relatively dispersed, though a few dominant firms hold significant market shares due to early investments in local infrastructure and compliance capabilities. Companies adopt aggressive business strategies focused on product innovation and tailored solutions to meet the unique regulatory and operational needs of Saudi enterprises. Recent product innovation emphasizes cloud integration, automation, and AI-powered scheduling to enhance efficiency and scalability.
Strategic partnerships with local IT firms and government agencies are prevalent, facilitating market entry and compliance with local standards. Mergers and acquisitions are increasing as established companies seek to expand their footprint and incorporate advanced R&D capacities, particularly directed at securing competitive differentiation through specialized features such as real-time analytics and integration with Saudi’s digital transformation initiatives. Expansion strategies predominantly target key urban centers like Riyadh and Jeddah, where demand is concentrated, with firms tailoring offerings to sectors such as energy, finance, and telecommunications. Overall, competition remains dynamic, driven by technological advancements and evolving customer requirements within the Saudi market landscape.
Leading Company Profiles
The Saudi Arabian workload scheduling software market boasts a competitive roster of global and regional players, innovating rapidly to meet evolving enterprise needs. These companies leverage advanced automation, artificial intelligence, and cloud-native platforms to capture market share in a burgeoning digital economy.
- IBM Corporation
- Broadcom Inc.
- Microsoft Corporation
- Red Hat Inc.
- BMC Software
- CA Technologies (a Broadcom company)
- Oracle Corporation
- Cisco Systems, Inc.
- SAP SE
- Saudi Telecom Company (STC)
IBM Corporation
IBM leads with its innovative AI-driven workload automation solutions, focused on enterprise scalability and seamless cloud integration, aligning with Saudi Arabia’s digital transformation initiatives, emphasizing security and compliance.
Broadcom Inc.
Broadcom’s workload automation offerings are distinguished by high-performance, reliable architecture designed for large-scale enterprises, with strategic investment in AI and machine learning to enhance automation intelligence in Saudi Arabia.
Microsoft Corporation
Microsoft’s cloud-native workload scheduling platform leverages Azure, providing flexible, scalable solutions meeting the dynamic needs of Saudi enterprises, supported by a strong ecosystem of partners and localized service capabilities.
Red Hat Inc.
Red Hat specializes in open-source automation and orchestration solutions, promoting hybrid cloud environments in Saudi Arabia and offering robust support for containerized and microservices architectures.
BMC Software
BMC offers a comprehensive workload automation suite designed for enterprise agility, emphasizing AI-driven operations, and is focusing on expanding its local partnership network within Saudi Arabia for greater reach.
CA Technologies (a Broadcom company)
CA Technologies enhances its automation platform with enhanced analytics and security features, supporting critical sectors such as banking and oil & gas in Saudi Arabia.
Oracle Corporation
Oracle provides integrated workload scheduling solutions optimized for Oracle Cloud and hybrid on-premises architectures, with a strategic emphasis on compliance and high availability tailored for Saudi markets.
Cisco Systems, Inc.
Cisco’s automation solutions focus on network and data center workloads, emphasizing security, real-time analytics, and scalable orchestration aligning with Saudi Arabia’s telecom and enterprise growth plans.
SAP SE
SAP integrates workload automation in its enterprise resource planning (ERP) solutions, facilitating digital transformation in banking, manufacturing, and government sectors within Saudi Arabia.
Saudi Telecom Company (STC)
STC is innovating its digital infrastructure by deploying local workload automation solutions to support its expanding cloud services and data center operations across Saudi Arabia.
Strategic Business Developments
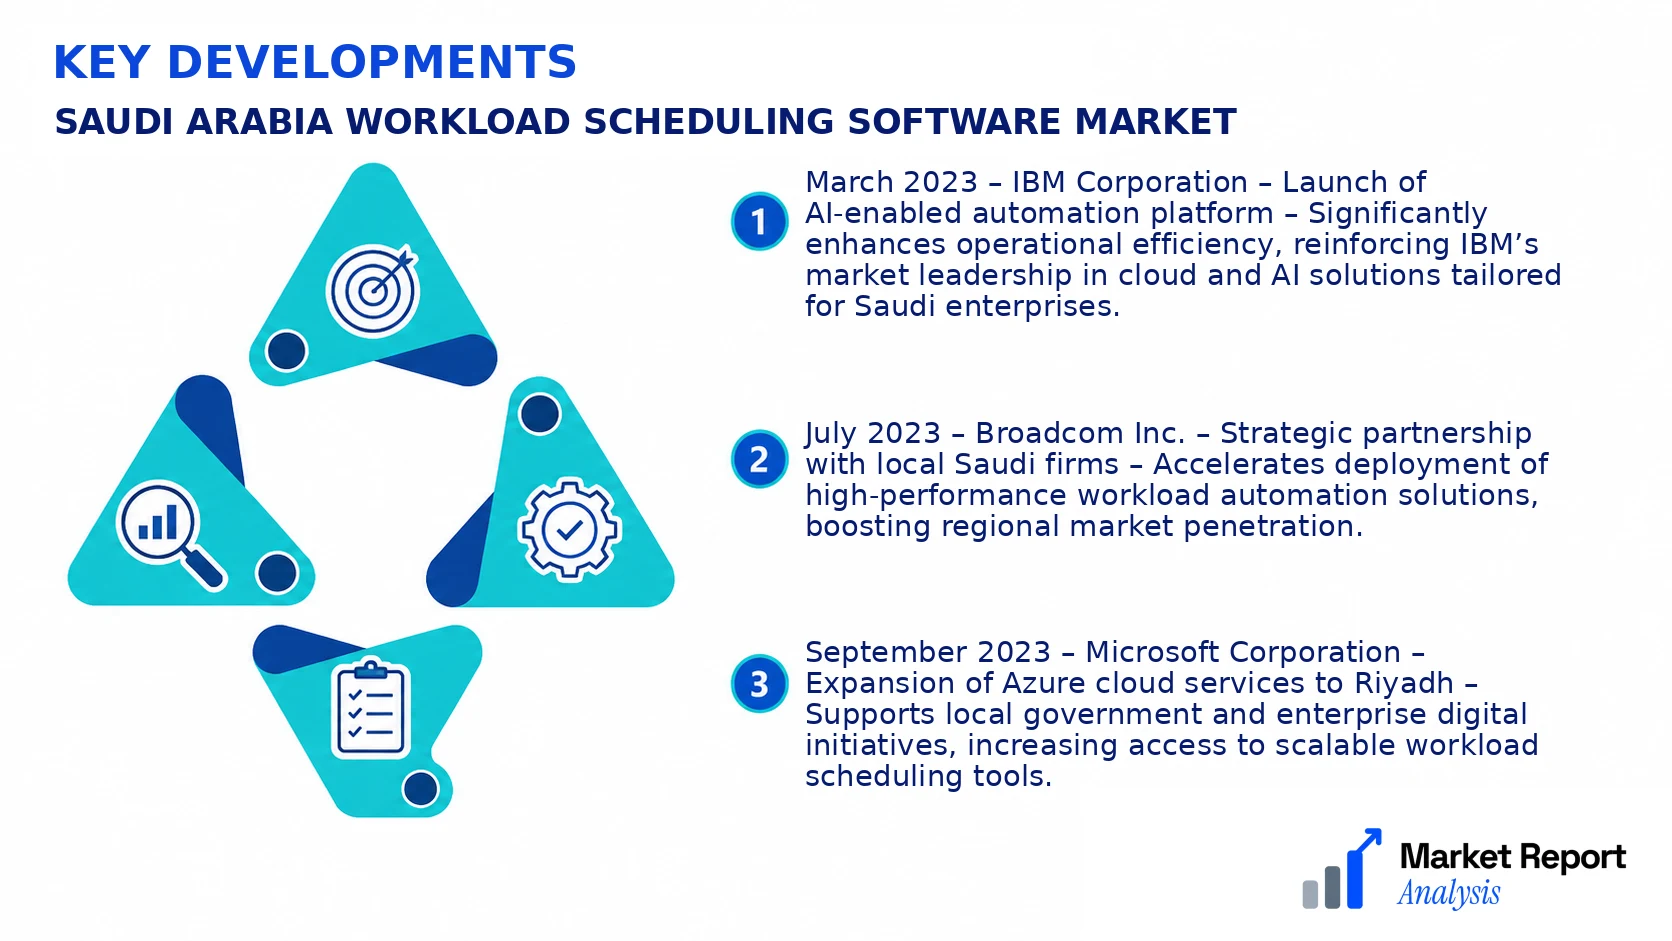
- March 2023 – IBM Corporation – Launch of AI-enabled automation platform – Significantly enhances operational efficiency, reinforcing IBM’s market leadership in cloud and AI solutions tailored for Saudi enterprises.
- July 2023 – Broadcom Inc. – Strategic partnership with local Saudi firms – Accelerates deployment of high-performance workload automation solutions, boosting regional market penetration.
- September 2023 – Microsoft Corporation – Expansion of Azure cloud services to Riyadh – Supports local government and enterprise digital initiatives, increasing access to scalable workload scheduling tools.
- January 2024 – Red Hat Inc. – Introduction of open-source orchestration solutions – Facilitates hybrid cloud integration for Saudi organizations, promoting flexible and secure workload management.
- April 2024 – Cisco Systems, Inc. – Investment in local data centers – Enhances cloud and network workload solutions, driving automation in telecom and enterprise sectors across Saudi Arabia.
Frequently Asked Questions
What is the Saudi Arabia Workload Scheduling Software Market?
The Saudi Arabia Workload Scheduling Software Market comprises systems designed to optimize the deployment and management of computing workloads across data centers and cloud infrastructures within Saudi Arabia, facilitating enhanced operational efficiency and resource utilization.
What is the current market size of Saudi Arabia Workload Scheduling Software Market?
As of 2026, the market size is estimated at approximately USD 1.2 Billion, reflecting increasing digital transformation initiatives and the need for automated workload management solutions amid rising data center investments across the country.
What factors are driving the Saudi Arabia Workload Scheduling Software Market?
Key drivers include a surge in cloud adoption, government-led digital initiatives, expanding data center infrastructure, and the rising demand for online services. Additionally, growing cybersecurity concerns and the need for operational efficiency further propel market growth.
Which Saudi city leads the Saudi Arabia Workload Scheduling Software Market?
Riyadh leads the market, driven by its status as the economic and technological hub of Saudi Arabia, hosting the majority of data centers, IT firms, and government digital projects that accelerate workload scheduling software deployment.
Which segment is expected to grow the fastest?
The cloud-based workload scheduling segment is projected to experience the fastest growth, supported by increasing migration to cloud platforms, improved scalability, and cost efficiency that meet the evolving needs of enterprises and government entities.
Who are the leading companies operating in the Saudi Arabia Workload Scheduling Software Market?
Leading companies include international players like IBM, VMware, and BMC Software, along with regional providers such as Saudi Telecom Company (STC) and local startups, all competing through innovative offerings and strategic partnerships to capture market share.
Analyst Perspective
The Saudi Arabia Workload Scheduling Software Market exhibits a mature but evolving landscape, driven by increasing digital transformation initiatives and government mandates for enhanced IT infrastructure resilience. Long-term prospects remain promising, with a projected CAGR of 9.2% from 2026 to 2034, reflecting ongoing investments in cloud computing, AI integration, and automation. Commercial opportunities are particularly attractive within the healthcare, finance, and energy sectors, where workload management is critical for operational continuity and regulatory compliance. Technology evolution is trending toward adaptive, AI-powered solutions that optimize resource utilization and reduce latency, aligning with Saudi Vision 2030’s push for a digitally empowered economy. Investment priorities should emphasize scalable, cloud-native architectures and regional data center expansions, especially in Riyadh, Jeddah, and Dhahran, where digital maturity and demand are highest. While competition intensifies among local and international players, differentiation via innovation, compliance, and local support will be key. City-level growth potential offers significant upside, with Riyadh leading due to its robust enterprise base, followed by Jeddah’s maritime commerce and Dhahran’s oil sector. Strategic positioning should focus on long-term resilience, adaptability, and regional leadership in workload scheduling capabilities.
