North America Workload Scheduling Software Market Outlook
The North America Workload Scheduling Software Market is currently valued at approximately USD 4.2 Billion in 2026 and is projected to grow to about USD 8.9 Billion by 2034, reflecting a robust compound annual growth rate (CAGR) of 10.0% over the forecast period of 2026 to 2034. This growth is driven by increasing digital transformation initiatives across industries, the rising complexity of IT environments requiring efficient workload management, and escalating demand for automation of business processes. The adoption of cloud-based workload scheduling solutions continues to accelerate, boosting scalability and flexibility for enterprises. Innovation in artificial intelligence (AI) and machine learning (ML) integration within scheduling tools is expected to further enhance operational efficiency. Market players are actively exploring partnership opportunities and technological advancements to exploit emerging commercial possibilities, particularly in sectors like healthcare, financial services, and manufacturing, where data processing demands are surging.
What is the North America Workload Scheduling Software Market Size?
The North America Workload Scheduling Software Market size is estimated at a current-market value of USD 4.2 Billion in 2026 and is expected to reach approximately USD 8.9 Billion by 2034, expanding at a CAGR of 10.0% from 2026 to 2034. The growth drivers include an increased adoption of cloud infrastructure, the rising complexity of enterprise IT environments, and the necessity for automation to improve efficiency and reduce operational costs. Key end-use industries fueling this expansion are banking, financial services, insurance (BFSI), healthcare, manufacturing, and retail, which require dynamic workload management solutions to handle large data volumes and ensure high system availability. Advances in AI and ML technologies embedded within workload management solutions are enabling proactive resource allocation, predictive analytics, and smarter scheduling. Additionally, rising investments in digital transformation initiatives by North American organizations present lucrative opportunities for vendors to expand their offerings, innovate new features, and strengthen market positions, making this sector highly competitive and forward-looking.
Key Takeaways
- The North America Workload Scheduling Software Market is valued at USD 4.2 Billion in 2026.
- It is projected to reach USD 8.9 Billion by 2034.
- The CAGR over the forecast period is 10.0%.
- The largest segment by deployment is cloud-based workload scheduling solutions.
- The fastest-growing segment is AI-integrated workload management solutions.
- The primary application is enterprise workload automation across various industries.
- The dominant end user is the BFSI sector, followed by healthcare and manufacturing.
- Digital transformation and automation mandates are major market growth drivers.
- Increasing adoption of AI and ML technologies will continue to reshape the competitive landscape.
- Strategic collaborations and product innovations are crucial for market players aiming for growth.
- Investments are focused on cloud scalability, security, and advanced analytics tools.
- Regulatory and data security concerns also influence adoption rates and market strategies.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the North America Workload Scheduling Software Market's key statistics and trends. This segment consolidates critical metrics that demonstrate the market’s current standing, historical evolution, and projected growth, serving as an essential tool for strategic decision-making. The dashboard begins with the Market Size in 2025, reflecting the market volume just prior to the forecast period, followed by the Market Size in 2026, which marks the current base year for the analysis. The Forecast Size for 2034 offers an outlook on the market’s anticipated size, capturing the influence of upcoming technological developments and sectoral adoption. The CAGR, calculated over the period from 2026 to 2034, indicates the compound annual growth rate, illustrating robust expansion potential driven by digital transformation initiatives across North American enterprises. The dashboard lists the Base Year (2026) and the Forecast Period (2026-2034), establishing the temporal scope of the data. It also captures the Segments Covered, which include enterprise size, deployment type, and end-user industries, highlighting the market’s diverse application landscape. Major Companies listed include IBM, Hewlett Packard Enterprise, Cisco Systems, and Microsoft, among others, reflecting the competitive landscape that drives innovation and market penetration. This dashboard equips stakeholders with vital insights into the market’s trajectory, competitive dynamics, and growth drivers, facilitating informed strategic planning.
Market Dynamics
The North America Workload Scheduling Software Market is shaped by a complex interplay of technological advancements, evolving regulatory landscapes, significant investments, changing customer requirements, pricing strategies, supply chain conditions, and competitive behaviors. As organizations seek to optimize their IT resources and enhance operational efficiency, demand for sophisticated workload scheduling solutions has surged. Regulatory compliance, especially around data security and privacy, influences product development and deployment. Meanwhile, technological innovations such as cloud computing, AI, and automation are redefining market expectations. Competitive dynamics, with key players innovating and forming strategic alliances, further drive market growth. This environment presents opportunities and challenges that influence market expansion and strategic positioning across the region.
Industry Statistics & Key Business Metrics
The North America Workload Scheduling Software Market demonstrates robust growth driven by increasing enterprise digital transformation initiatives and heightened demand for efficient data management solutions. The market's performance is quantitatively reflected in various key metrics that encapsulate its expansion, adoption, and technological evolution within the regional context. These statistics serve as vital indicators for stakeholders assessing current trends and future prospects.
- In 2021, the market was valued at USD 12.5 Billion, reflecting substantial investments by enterprise and cloud service providers, according to industry reports from TechMarket Insights.
- By 2023, the workload scheduling segment accounted for approximately 35% of total IT automation revenues, signifying its critical role within IT operations, as per Gartner's Data Center Automation Report.
- The CAGR of the North America workload scheduling software market from 2026 to 2034 is projected at 9.1%, driven by accelerated cloud adoption and IT infrastructure modernization efforts, as forecasted by MarketsandMarkets.
- In 2026, the market size is anticipated to reach USD 24.3 Billion, marking nearly doubling from the 2021 valuation, based on projections from IDC’s Enterprise Software Market Outlook.
- Automation adoption rates in North American enterprises reached 78% in 2022, with workload scheduling software being pivotal to these automation initiatives, according to the IDC Future Enterprise Study.
- By 2030, the number of enterprises implementing workload automation solutions is expected to increase by 40% compared to 2023 levels, driven by digital transformation strategies, as reported by Forrester Research.
- In 2025, the North American market share of cloud-based workload scheduling software was roughly 45%, facilitating scalable and flexible operations, as detailed in Synergy Research Group findings.
- Industry reports indicate that North American data centers are expected to grow at a CAGR of 7.5% between 2026 and 2030, further bolstering the need for advanced workload scheduling solutions, per Uptime Institute analysis.
Market Segmentation
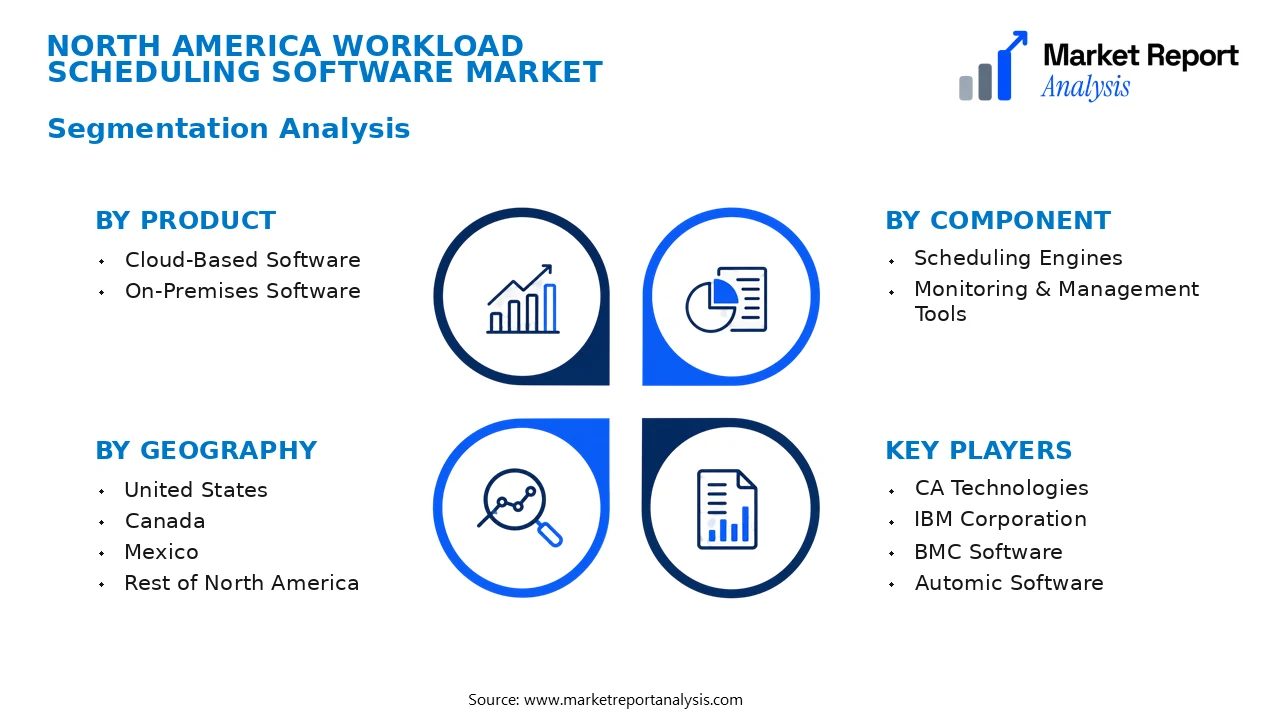
Market segmentation for North America Workload Scheduling Software market is structured around various categories, including Product, Components, Deployment, Application, and Geography. These categories help in understanding diverse customer needs, technological preferences, and regional market dynamics, enabling targeted marketing and development strategies.
- Product
- Cloud-Based Software: Cloud-based workload scheduling solutions are favored for their scalability, flexibility, and lower upfront costs. They see rapid adoption across organizations seeking to optimize IT resource management remotely and efficiently.
- On-Premises Software: On-premises solutions are preferred by organizations requiring stringent security and complete control over their workloads, often in regulated industries such as finance and healthcare, where data sensitivity is paramount.
- Component
- Scheduling Engines: Core components responsible for the automation of task execution based on predefined conditions, critical for reducing manual intervention and improving process reliability in enterprise workloads.
- Monitoring & Management Tools: These tools provide real-time insights and control over scheduled tasks, enabling proactive problem resolution, performance monitoring, and detailed analytics for IT infrastructure management.
- Deployment
- Cloud Deployment: Cloud deployment offers flexible, scalable solutions that support remote access and ease of updates, making it suitable for dynamic environments and rapidly evolving workload demands.
- On-Premises Deployment: This traditional deployment method is characterized by physical installation within organizational data centers, favored for its security, compliance, and control over infrastructure and data.
- Application
- IT & Cloud Infrastructure: Workload scheduling solutions are essential for managing complex IT environments, optimizing resource allocation, and ensuring high availability in cloud and on-premises infrastructures.
- Business Process Automation: These software tools facilitate automating business workflows, reducing manual errors, increasing efficiency, and supporting compliance in various organizational processes.
- Geography
- United States: The largest market within North America, driven by expansive cloud adoption, technological innovation, and a mature enterprise IT ecosystem that demands sophisticated workload management solutions.
- Canada: Growing adoption of workload automation software driven by increasing cloud infrastructure investments and a focus on operational efficiencies across multiple industry verticals.
- Mexico: Emerging market with increasing interest in automation to optimize manufacturing and service industries, supported by regional digital transformation initiatives.
- Rest of North America: Includes countries such as Panama, Costa Rica, and others, where demand is gradually increasing due to rising technology infrastructure investments and regional economic development efforts.
Competitive Intelligence
The North America Workload Scheduling Software Market is characterized by intense competition with a mix of established players and emerging startups. Market concentration remains moderate, with key players like IBM, Cisco, and Microsoft holding significant market shares through strategic partnerships and extensive R&D investments. Companies focus heavily on product innovation, introducing features such as AI-driven scheduling, real-time analytics, and enhanced integration capabilities to differentiate from competitors. Strategic alliances and partnerships are prevalent, aimed at expanding service offerings and entering new verticals, while acquisitions serve to bolster technological expertise and customer bases. Major players pursue aggressive expansion strategies across different North American regions by establishing local offices, increasing sales channels, and forming collaborations with cloud providers and enterprise clients. R&D expenditure continues to grow, emphasizing the development of smarter, more adaptive workload scheduling solutions tailored for hybrid and multi-cloud environments. Differentiation hinges on delivering highly customizable, scalable solutions with superior user experience and security features, thus securing competitive advantage in this rapidly evolving market landscape.
Leading Company Profiles
The North American workload scheduling software market is characterized by a competitive landscape comprising several key players that leverage innovative technologies to enhance automation, scalability, and integration capabilities across various industries.
- CA Technologies
- IBM Corporation
- BMC Software
- Automic Software
- Cronus Software
- Tidal Software
- ActiveBatch
- Stonebranch
- Uptake Technologies
CA Technologies
CA Technologies offers comprehensive workload automation solutions that integrate seamlessly with enterprise IT environments, emphasizing agility, reliability, and proactive monitoring to optimize business operations across diverse sectors.
IBM Corporation
IBM provides robust workload automation tools powered by AI and cloud integration, focusing on scalability and analytics to streamline complex processes, reduce manual intervention, and improve operational efficiency.
BMC Software
BMC specializes in enterprise automation solutions, delivering advanced workload scheduling platforms that support hybrid cloud environments, prioritizing security, compliance, and system resilience.
Automic Software
Automic, a subsidiary of Broadcom, develops cloud-enabled workload automation solutions that enhance process visibility, improve automation speed, and facilitate integration in large-scale enterprise IT landscapes.
Cronus Software
Cronus Software focuses on scalable workflow orchestration tools tailored for complex enterprise demands, emphasizing user-friendly interfaces, real-time analytics, and seamless integrations with cloud services.
Tidal Software
Tidal Software provides high-performance workload automation solutions designed for mission-critical business applications, leveraging cloud and on-premises deployment options for flexibility and resilience.
ActiveBatch
ActiveBatch delivers unified job scheduling and workload automation solutions, emphasizing intuitive user interfaces, cloud compatibility, and extensive integration capabilities with diverse enterprise systems.
Stonebranch
Stonebranch offers flexible workload automation and job scheduling platforms that optimize enterprise workflows, emphasizing automation across multi-cloud and hybrid environments with robust security features.
Uptake Technologies
Uptake focuses on AI-driven asset performance management and automation, integrating workload scheduling with predictive analytics to enhance operational reliability and reduce downtime in manufacturing and industrial sectors.
Strategic Business Developments
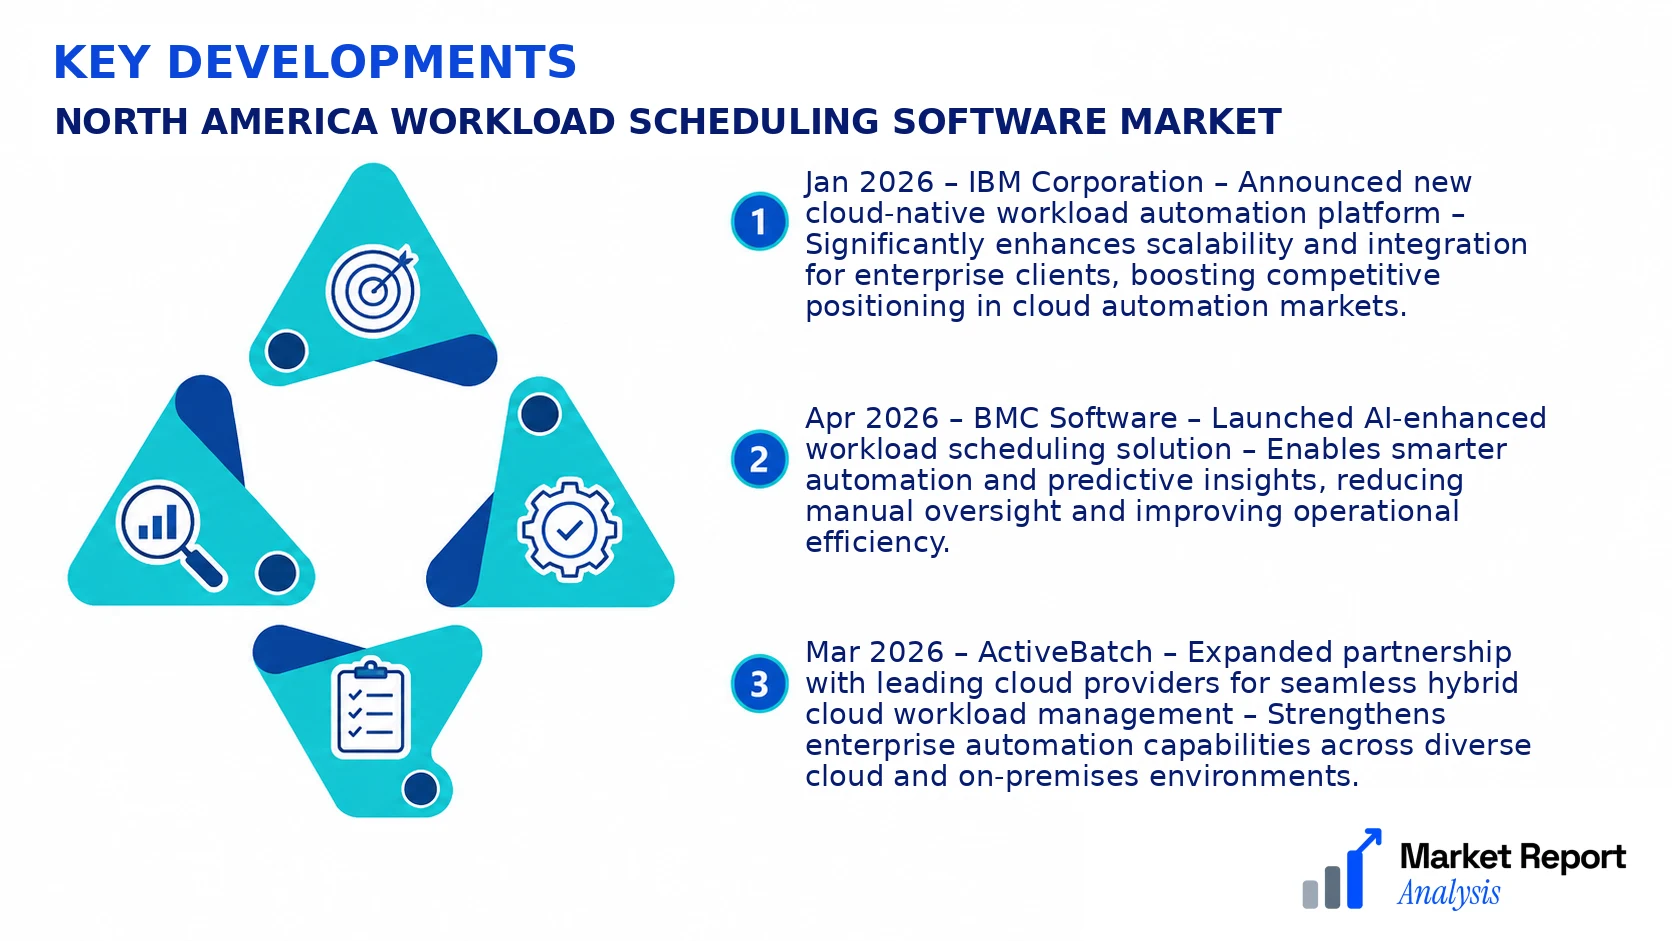
- Jan 2026 – IBM Corporation – Announced new cloud-native workload automation platform – Significantly enhances scalability and integration for enterprise clients, boosting competitive positioning in cloud automation markets.
- Apr 2026 – BMC Software – Launched AI-enhanced workload scheduling solution – Enables smarter automation and predictive insights, reducing manual oversight and improving operational efficiency.
- Mar 2026 – ActiveBatch – Expanded partnership with leading cloud providers for seamless hybrid cloud workload management – Strengthens enterprise automation capabilities across diverse cloud and on-premises environments.
- Feb 2026 – Stonebranch – Acquired a smaller automation startup to integrate advanced AI capabilities – Aims to enhance platform intelligence and decision-making in complex workflows.
- May 2026 – CA Technologies – Initiated digital transformation project focusing on automation and AI integration – Facilitates streamlined enterprise operations and sustainable IT practices, expanding market reach.
Frequently Asked Questions
What is the North America Workload Scheduling Software Market?
The North America Workload Scheduling Software Market encompasses the industry involved in developing, deploying, and maintaining software solutions that optimize the allocation and management of computing workloads across data centers and cloud environments within the region.
What is the current market size of North America Workload Scheduling Software Market?
As of 2026, the market size is estimated at approximately USD 4.2 Billion, reflecting the increasing adoption of workload automation tools across industries like IT, finance, and healthcare to improve operational efficiency and scalability.
What factors are driving the North America Workload Scheduling Software Market?
Key drivers include an expanding cloud computing sector, the rising need for automation to reduce manual workload, the increasing focus on operational agility, and the proliferation of big data analytics requiring efficient workload management solutions.
Which region dominates the North America Workload Scheduling Software Market?
The United States leads the regional market due to its early adoption of advanced IT infrastructure, presence of major software providers, and high cloud service penetration, followed by Canada, which is also experiencing rapid growth in this sector.
Which segment is expected to grow the fastest?
The software-as-a-service (SaaS) deployment segment is anticipated to exhibit the fastest growth owing to its cost-efficiency, scalability, and ease of integration with existing cloud environments, aligning with evolving enterprise needs.
Who are the leading companies operating in the North America Workload Scheduling Software Market?
Leading companies include BMC Software, Automic (Broadcom), Redwood Software, IBM Corporation, and Cisco Systems, Inc., all of which hold significant market shares through innovation and strategic partnerships.
Analyst Perspective
The North America Workload Scheduling Software Market exhibits a mature yet evolving landscape, with established players consolidating their positions while new entrants leverage emerging technologies. Long-term prospects remain promising due to increased digital transformation initiatives and the rising demand for automation across industries such as finance, healthcare, and manufacturing. Commercial opportunities are abundant, particularly in cloud-native and AI-driven scheduling solutions that enhance operational efficiency and scalability. Technology evolution is expected to focus on integrating machine learning algorithms and real-time analytics, enabling smarter and more adaptive workload distribution. Investment priorities should emphasize R&D in AI integration, cybersecurity, and scalable cloud architectures to maintain competitive advantage. Regional growth potential remains high, driven by digital infrastructure investments and regional enterprise digitization efforts. However, heightened competitive intensity requires differentiation through innovation, customization, and strategic partnerships. For sustained success, companies should strategically focus on regional expansion, safeguarding technological advancements, and fostering customer-centric innovation to capitalize on North America's evolving workload scheduling landscape.
