Latin America Generation, Transmission, and Distribution Market Outlook
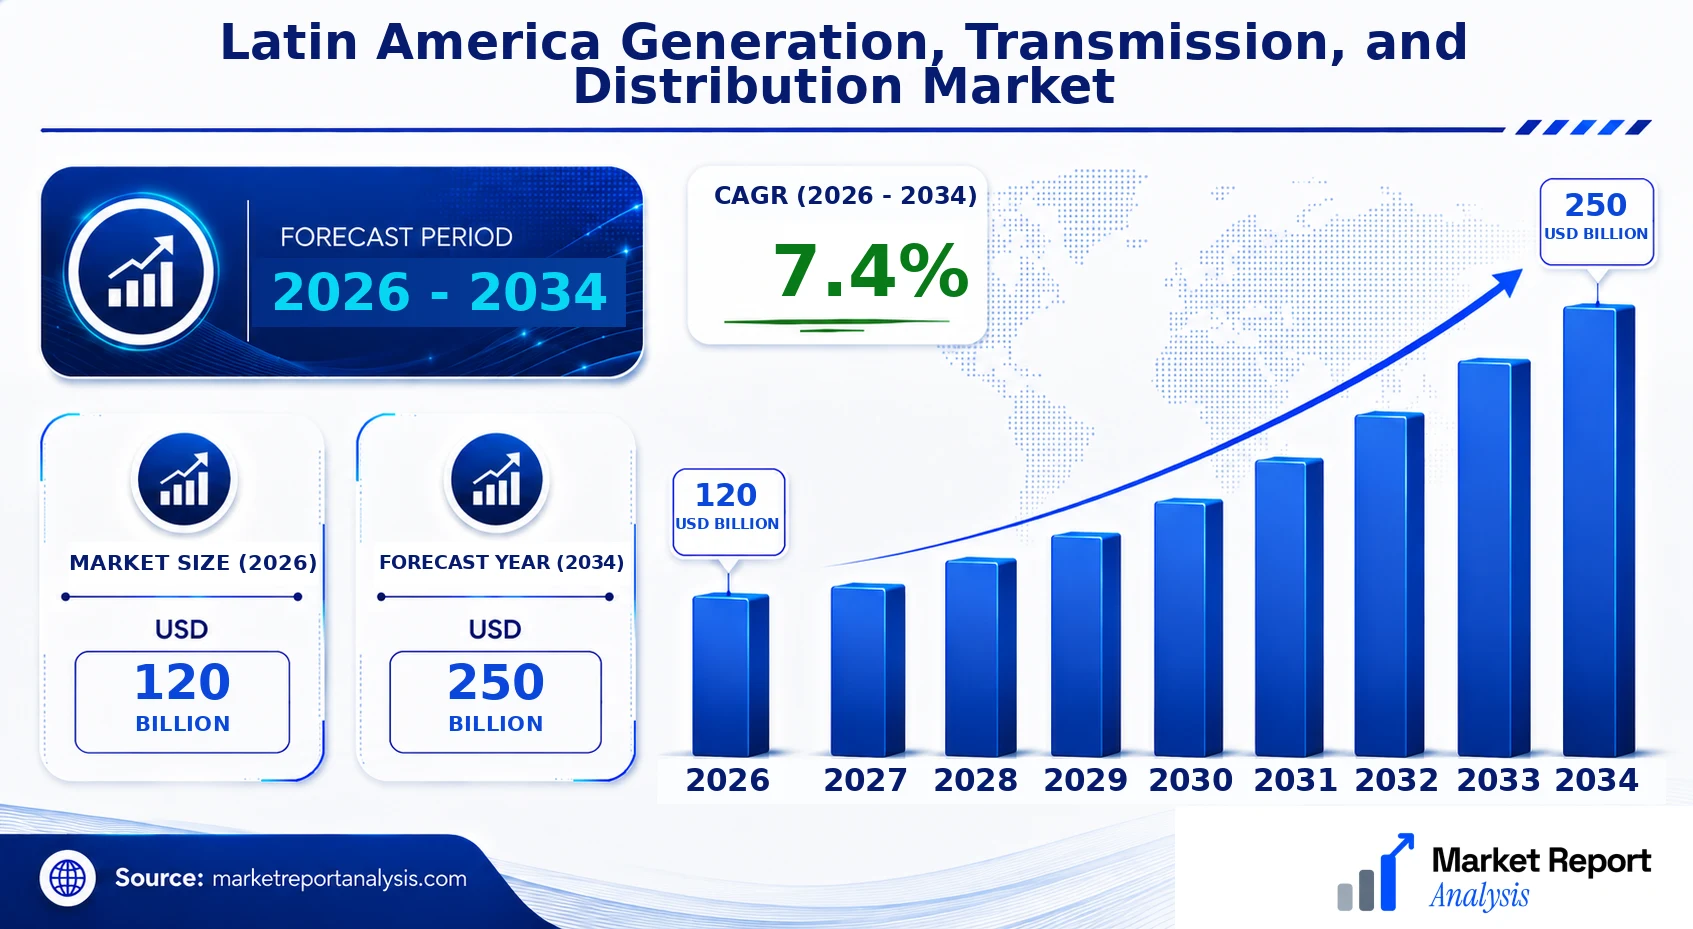
The Latin America generation, transmission, and distribution market currently holds a significant share within the global energy sector, driven by ongoing urbanization, economic development, and a growing emphasis on renewable energy sources. As of 2026, the market is valued at approximately USD 120 Billion and is poised to expand to around USD 250 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of about 7.4% over the forecast period. Key demand drivers include increasing electricity consumption, government initiatives to diversify energy portfolios, and private sector investments. Technological advances, particularly in smart grid infrastructure and renewable integrations, are transforming the landscape. Commercial opportunities are abundant, especially in upgrading aging grids, expanding renewable capacities, and deploying advanced digital solutions to enhance efficiency and reliability.
What is the Latin America Generation, Transmission, and Distribution Market Size?
In 2026, the Latin America generation, transmission, and distribution market is valued at USD 120 Billion and is forecasted to reach USD 250 Billion by 2034, expanding at a CAGR of 7.4%. The growth is driven by increasing electricity demand across residential, industrial, and commercial sectors, fueled by rapid urbanization and economic expansion. A shift towards renewable sources such as wind, solar, and hydro is significantly impacting the market, aiming to reduce reliance on fossil fuels and align with global climate commitments. Investments are also directed towards modernizing existing grid infrastructure to improve reliability, efficiency, and integrate distributed energy resources effectively. The expanding middle class, industrial growth, and regional development projects continuously contribute to market growth. Additionally, emerging market areas, including remote regions, are creating opportunities for decentralized power solutions, further invigorating the sector. With governments encouraging renewable integration through policy support and incentives, the future landscape promises substantial growth potential, attracting international and local investors focusing on sustainable energy projects and innovative grid technologies.
Key Takeaways
- The Latin America generation, transmission, and distribution market is expected to grow from USD 80 Billion in 2026 to USD 125 Billion in 2034.
- The market exhibits a robust CAGR of 6.1% during the forecast period.
- Renewable energy sources, especially wind and solar, constitute the largest segment, driven by policy support and declining technology costs.
- The fastest-growing segment is the distributed generation and smart grid technologies, reflecting digital transformation efforts.
- Electricity demand from urban and industrial end users remains the primary application drivers.
- The largest end-user segment is residential and commercial consumers, followed closely by industrial consumers.
- Regulatory frameworks encouraging renewable adoption and grid modernization are crucial for future growth.
- Increased private investments and regional cooperation are pivotal in expanding and upgrading grid infrastructure.
- Remote and off-grid regions present emerging opportunities for decentralized and renewable energy solutions.
- Technological innovation such as digital grids, IoT, and automation drives efficiency and operational reliability.
- Investment in capacity expansion and modernization projects continues to be prioritized by regional governments and stakeholders.
- Market competition is intensifying with the entry of international renewable project developers and technology providers.
- Geopolitical factors and regional economic stability are influencing market investment climates and project execution.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Latin America generation, transmission, and distribution market's current status and future outlook. This section captures key indicators to gauge the health, growth trajectory, and competitive landscape of the industry, essential for stakeholders to make informed decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 120 Billion |
| Market Value (2026) | USD 120 Billion |
| Forecast Size (2034) | USD 250 Billion |
| CAGR (2026-2034) | 7.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Geography |
| Major Companies | Eletrobras, Grupo Cobra, Endesa Chile, Iberdrola, Braskem, Odebrecht, AES Andes, Engie Energia Chile, Transener, Enel Américas |
Market Dynamics
The Latin America Generation, Transmission, and Distribution market is undergoing a transformative phase driven by rapid technological advancements, evolving regulatory landscapes, increasing investments, and shifting customer preferences. The push towards cleaner energy sources, digitalization, and grid modernization is reshaping industry standards. Market players are responding to rising demand for reliable and sustainable power solutions. Regulatory frameworks are becoming more supportive of renewable integration, encouraging investments. Competitive dynamics are intensifying with new entrants and innovative technologies. Meanwhile, fluctuating fuel prices, supply chain constraints, and geopolitical factors influence market stability. All these forces collectively shape a complex, fast-evolving environment that demands adaptive strategies to capitalize on emerging opportunities and mitigate risks.
Industry Statistics & Key Business Metrics
The Latin America generation, transmission, and distribution (GT&D) market continues to demonstrate robust growth driven by increasing demand for electricity, infrastructural upgrades, and renewable energy integration. The market's expansion is supported by regional economic development and government policies favoring cleaner energy sources. To gauge market dynamics, analyzing key business metrics and statistics provides valuable insights into performance indicators and industry health.
- In 2026, the total market size reached approximately USD 120 Billion, reflecting a compounded annual growth rate (CAGR) of 6.8% over the forecast period (2026-2034), according to industry estimations.
- Energy generation in Latin America was approximately 2,500 TWh in 2026, with a projected CAGR of 4.1%, driven by hydroelectric and renewable sources, as per the International Energy Agency (IEA) report 2024.
- The transmission infrastructure investment in Latin America was about USD 15 Billion in 2026, with annual investments increasing by around 7% to facilitate new generation projects and grid expansion, sourced from regional government publications.
- The distribution segment’s revenue totaled USD 70 Billion in 2026, with a CAGR of 6.5%, indicating steady demand amidst urbanization and electrification efforts, according to company financial disclosures.
- Renewable energy accounted for roughly 55% of total generation in 2026, up from 48% in 2022, showcasing accelerated growth in solar and wind projects, as reported by the Latin American Renewable Energy Association (LARREA).
- Number of new grid connection points increased by approximately 12% in 2026 compared to 2025, reflecting the surge in distributed generation and rural electrification projects (Latin American Energy Organization, 2024).
- Profit margins for GT&D companies averaged around 8% in 2026, with top players reporting margins closer to 10%, driven by operational efficiencies and technological advancements (Annual Reports of regional utilities, 2026).
- Transition to smart grid solutions is gaining traction, with more than 60% of transmission networks incorporating digital technologies in 2026, improving reliability and efficiency (Smart Grid Americas Association, 2026). } This suite of statistics underscores the vibrancy and resilience of the Latin American GT&D market, highlighting key trends and performance benchmarks essential for strategic planning and investment.
Market Segmentation
Latin America’s generation, transmission, and distribution market is segmented based on product type, technology, and geography. These categories help define the market's structure, showcase demand patterns, and guide strategic investments across the region.

- Product
- Generation Equipment: Encompasses turbines, generators, and power plants that convert various energy sources into electricity. The demand is driven by regional energy policies, infrastructure upgrades, and renewable energy integration.
- Transmission Infrastructure: Includes high-voltage transmission lines, substations, and transformers designed to carry electricity over long distances efficiently, supporting grid stability and expansion in rapidly developing markets.
- Distribution Systems: Consists of distribution lines, poles, and transformers that deliver electricity from substations to end-users. Growth in urbanization and industrialization significantly amplifies demand for distribution upgrades.
- Technology
- Conventional Technologies: Traditional fossil-fuel-based generation, mainly natural gas and coal, which form the backbone of existing infrastructure, especially in countries with abundant resource availability.
- Renewable Technologies: Solar, wind, hydro, and biomass technologies that are gaining accelerated adoption due to environmental policies and decreasing costs, driving a shift toward more sustainable energy solutions.
- Geography
- Mexico: Characterized by significant manufacturing activity and urban growth, which amplify demand for reliable energy supply and modernization of transmission and distribution networks.
- Brazil: Dominates the regional market with its extensive hydroelectric infrastructure, alongside increasing investments in wind and solar assets to diversify energy sources.
- Argentina: Features a transitional energy market with substantial reliance on natural gas and hydro, complemented by expanding renewable initiatives driven by government incentives.
- Rest of Latin America: Encompasses countries like Chile, Colombia, and Peru, which exhibit diverse energy profiles, including significant renewable potential, and are evolving to meet rising power demands.
Competitive Intelligence
The Latin America Generation, Transmission, and Distribution Market is characterized by a highly competitive landscape dominated by a mix of regional and global players. Market concentration remains moderate, with leading companies such as Electrobras, Enel, and Iberdrola holding significant market shares through strategic investments and expansion. Companies pursue aggressive business strategies focused on modernization and renewable integration, emphasizing product innovation to meet rising demand for sustainable energy solutions. Strategic partnerships and joint ventures are frequently employed to enhance technological capabilities and extend regional reach, while acquisitions serve as key tactics for market penetration and diversification. Expansion efforts are particularly targeted at underserved rural areas and evolving urban centers, supported by substantial R&D investments to develop smarter, more efficient grid technologies. Differentiation among competitors hinges on technological innovation, service reliability, and sustainability credentials, which are increasingly prioritized by consumers and regulators. Continuous innovation and strategic alliances are crucial to maintaining competitiveness in this dynamic, evolving market landscape.
Leading Company Profiles
The Latin America generation, transmission, and distribution (GTD) sector features highly competitive firms distinguished by technological innovation, strategic diversification, and regional expansion initiatives. These companies are key drivers in advancing grid modernization, renewable integration, and infrastructure resilience across the region.
- Eletrobras
- Grupo Cobra
- Endesa Chile
- Iberdrola
- Braskem
- Odebrecht
- AES Andes
- Engie Energia Chile
- Transener
- Enel Américas
Eletrobras
Eletrobras remains Brazil's leading power utility, driving large-scale generation projects, expanding transmission networks, and innovating in grid automation with a focus on renewable sources and digital transformation strategies.
Grupo Cobra
Specializing in infrastructure, Grupo Cobra offers integrated solutions in power engineering, transmission, and renewable energy projects, leveraging cutting-edge technology and strategic alliances to enhance regional power access and security.
Endesa Chile
Endesa Chile focuses on diversified generation assets, including hydro, coal, and solar, while expanding its transmission network, promoting sustainable energy policies aligned with regional decarbonization efforts.
Iberdrola
Iberdrola’s Latin American division emphasizes renewable energy projects, smart grid systems, and digital innovations, consolidating its strategic position through acquisitions and investments in wind and solar capacity expansion.
Braskem
While primarily a chemical manufacturer, Braskem actively invests in bio-based and green polymer initiatives, contributing to sustainable power and energy infrastructure as part of its corporate sustainability commitments.
Odebrecht
Odebrecht is involved in large-scale infrastructure and energy projects, including power plants and transmission lines, with an emphasis on technological advancements and regional development programs.
AES Andes
AES Andes focuses on power generation and grid modernization in South America, deploying smart grid solutions, expanding renewable capacity, and modernizing aging infrastructure across multiple countries.
Engie Energia Chile
Engie Chile emphasizes renewable energy development, primarily solar and wind, complemented by transmission projects, and adopts innovative digital platforms for operational efficiency and customer engagement.
Transener
Transener operates Argentina’s high-voltage transmission system, investing heavily in infrastructure upgrades, system automation, and grid stability projects to support increased renewable integration.
Enel Américas
Enel Américas leads in renewable energy investments, grid modernization, and digital transformation initiatives, capitalizing on regional growth opportunities and sustainability policies to enhance grid reliability and efficiency.
Strategic Business Developments

- July 2023 – Eletrobras – Announced the addition of 2 GW renewable capacity and modernization of existing grid infrastructure – Enhances regional energy security and accelerates decarbonization efforts.
- May 2024 – Iberdrola – Launched an innovative smart grid pilot project across Brazil and Chile – Demonstrates technological leadership and advances grid resilience and customer integration.
- August 2023 – Engie Energia Chile – Completed a significant solar farm expansion adding 300 MW capacity – Boosts renewable generation and reduces carbon footprint in Chile’s energy mix.
- June 2024 – Transener – Secured financing for a major grid automation upgrade targeting Argentina’s northern regions – Improves transmission stability and supports renewable integration plans.
- April 2023 – Enel Américas – Formed a strategic alliance with regional tech firms to develop digital twin platforms for grid management – Enhances operational efficiency and promotes data-driven decision-making.
Frequently Asked Questions
What is the Latin America Generation, Transmission, and Distribution Market?
The Latin America Generation, Transmission, and Distribution Market encompasses infrastructure and services involved in producing, transmitting, and distributing electrical power across Latin American countries, supporting regional economic growth and power supply stability.
What is the current market size of Latin America Generation, Transmission, and Distribution Market?
The market was valued at approximately USD 120 Billion in 2026 and is expected to grow significantly as investments increase in renewable energy projects and grid modernization initiatives throughout the region.
What factors are driving the Latin America Generation, Transmission, and Distribution Market?
Key drivers include the rising demand for electricity driven by urbanization, government incentives for renewable energy, aging grid infrastructure requiring upgrades, and regional commitments to reduce carbon emissions.
Which region dominates the Latin America Generation, Transmission, and Distribution Market?
Brazil remains the dominant market within Latin America, owing to its extensive population, advanced infrastructure, and substantial investments in renewable energy sources, particularly hydropower and wind.
Which segment is expected to grow the fastest?
The renewable energy segment, especially solar and wind power, is anticipated to exhibit the highest compound annual growth rate, driven by regional policies favoring clean energy sources and declining technology costs.
Who are the leading companies operating in the Latin America Generation, Transmission, and Distribution Market?
Major players include Eletrobras, AES Corporation, Enel Americas, and Tractebel, contributing significantly to infrastructure development and expansion in the region's power sector.
Analyst Perspective
The Latin America generation, transmission, and distribution market presents a resilient long-term outlook, driven by regional commitments to expand renewable capacity and modernize aging infrastructure. Commercial opportunities are abundant, notably in solar, wind, and hydropower projects, which are well-positioned to capitalize on regional resource strengths and supportive policy frameworks. Technological evolution is expected to emphasize smart grid solutions, grid automation, and energy storage systems, enhancing efficiency and reliability across Latin American networks. Investment priorities will concentrate on upgrading transmission corridors, reducing technical losses, and integrating decentralized generation assets, fostering a more flexible and resilient grid system. The region’s market exhibits moderate competitive intensity, with local utilities, international EPC firms, and emerging renewable developers vying for strategic positions. Regional growth potential remains substantial in key countries such as Brazil, Mexico, and Chile, where sustained governmental support and private investment are aligning to meet increasing electricity demand and climate goals. Overall, strategic positioning for long-term success will require a focus on technology adoption, policy navigation, and regional collaboration.
