Europe Generation, Transmission, and Distribution Market Outlook
The Europe generation, transmission, and distribution (GTD) market is experiencing significant growth driven by the continent's transition toward renewable energy sources, modernization of existing infrastructure, and an increasing demand for reliable and efficient power delivery systems. As of 2026, the market is valued at USD 245 Billion, with projections indicating a rise to USD 400 Billion by 2034. This growth corresponds to a Compound Annual Growth Rate (CAGR) of approximately 5.2% over the period 2026-2034. The principal demand drivers include Europe's ambitious climate goals, substantial investments in renewable energy projects, and technological advancements such as smart grids and energy storage solutions. Market participants are exploring innovative technologies and digital tools that enhance grid flexibility and resilience, creating substantial commercial opportunities across the renewable integration spectrum and grid modernization sectors.

What is the Europe Generation, Transmission, and Distribution Market Size?
In 2026, the Europe GTD market is valued at around USD 245 Billion, with an expected escalation to USD 400 Billion by 2034. This growth is propelled by increased investments in renewable energy installations, government mandates for carbon reduction, and ongoing infrastructure upgrades to accommodate distributed energy resources. The electricity generation segment captures the largest share, powered predominantly by wind, solar, and hydroelectric power projects, while the transmission segment benefits from initiatives aimed at enhancing high-voltage grid capacity and cross-border interconnections. Distribution networks are also expanding and modernizing to support decentralized generation and electric vehicle (EV) charging infrastructure. High demand arises from industrial sectors, commercial buildings, and residential consumers eager to adopt cleaner energy solutions. As renewable technology costs decline, combined with supportive policies and rising electrification initiatives, future investments are poised to sustain robust growth across all segments. Opportunities abound particularly in smart grid deployment, digital management systems, and grid decarbonization strategies, which collectively aim to improve efficiency, reliability, and sustainability.
Key Takeaways
- The Europe GTD market was valued at USD 150 Billion in 2026 and is projected to reach USD 230 Billion by 2034.
- The market exhibits a healthy CAGR of approximately 6.2% during 2026-2034.
- The generation segment holds the largest market share, primarily driven by renewables.
- Transmission infrastructure is the fastest-growing segment, fueled by interconnection projects and grid upgrades.
- Distribution networks are expanding to support smart grids and decentralized energy sources.
- Key demand comes from residential, commercial, and industrial end users adopting cleaner energy sources.
- Stringent regulations and government incentives are accelerating renewable deployment.
- Technological innovations like smart grids and energy storage are transforming the market landscape.
- Investment in grid modernization and digitalization is increasing to enhance reliability and efficiency.
- Emerging opportunities include integration of EV charging infrastructure and energy storage systems.
- The renewable energy sector remains the principal growth driver with significant project pipelines.
- Collaborations and strategic partnerships are vital for technological advancements and market expansion.
- Future market growth is expected to be sustained by ongoing policy support and technological evolution.
- Overall, the market presents lucrative prospects for stakeholders focusing on energy transition and infrastructure resilience.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the current and forecasted metrics essential for understanding the dynamics of the Europe Generation, Transmission, and Distribution Market. This section encapsulates key indicators, highlighting trends and market trajectories from the base and forecast years. It provides stakeholders with an analytical foundation to evaluate market resilience, competitiveness, and growth potential over the forecast period, 2026-2034.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 245 Billion |
| Market Value (2026) | USD 245 Billion |
| Forecast Size (2034) | USD 400 Billion |
| CAGR | 5.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | Siemens AG, ABB Ltd., General Electric Company, Schneider Electric SE, Vestas Wind Systems A/S, Enel S.p.A., Iberdrola, S.A., EDF Group, E.ON SE, Vattenfall AB |
Market Dynamics
The Europe generation, transmission, and distribution market is experiencing transformative changes driven by a confluence of technological advancements, evolving regulatory frameworks, increased investments, and shifting customer demands. Governments and industry players are prioritizing cleaner energy sources, decarbonization commitments, and grid modernization efforts, which influence strategic investments and infrastructure upgrades. Price fluctuations, supply chain adjustments, and competitive dynamics further shape market outlooks, compelling stakeholders to innovate continuously. As the region navigates these complexities, the interplay of policy, technology, and market forces creates a dynamic environment poised for substantial growth and innovation through the forecast period.
Drivers
Renewable Energy Integration
The accelerating deployment of renewable energy sources such as wind, solar, and hydro is a primary driver of the market. Europe’s ambition to achieve climate neutrality by 2050 has resulted in substantial policy support, incentivizing renewable projects and grid integration. This transition necessitates advanced generation, transmission, and distribution infrastructure capable of managing variable outputs and ensuring grid stability. The region’s increasing renewable capacity projected to account for over 50% of electricity generation by 2030 necessitates upgrades in transmission networks and innovative storage solutions. Such developments foster competitive advantages for firms specializing in renewables and grid modernization, reinforcing the market’s growth trajectory.
Regulatory Frameworks and Policy Incentives
Stringent regulatory standards and supportive government policies are pivotal in stimulating investments and technological adoption. European countries have set ambitious decarbonization targets, backed by subsidy schemes, tax incentives, and market mechanisms like carbon pricing. These policies encourage utilities and independent power producers to expand clean energy capacities and overhaul existing infrastructure. The European Green Deal and Fit for 55 package exemplify comprehensive regulatory pushes that directly impact market dynamics, fostering innovation in grid flexibility, storage, and digitalization initiatives to meet evolving compliance requirements and sustainability goals.
Carbon Pricing and Market Mechanisms
The expansion of carbon pricing schemes across Europe exerts significant economic influence, incentivizing lower-emission generation alternatives and reducing reliance on fossil fuels. Market mechanisms such as Emissions Trading Schemes (ETS) have made emissions costlier, pushing industry stakeholders toward cleaner energy sources. This transition increases the demand for grid infrastructure capable of integrating intermittent renewables and supports the operational flexibility needed to respond to market signals. Rising carbon prices create new revenue streams for renewable producers and enhance the market attractiveness of clean energy investments, further fueling infrastructure upgrades and innovation initiatives.
Technological Innovation and Digital Transformation
Technological progress, particularly in smart grid technology, digitalization, and automation, is fostering more efficient and resilient energy systems. The adoption of IoT sensors, AI-driven asset management, and real-time monitoring optimizes grid operations, reduces losses, and enhances reliability. Digital twin technology and advanced analytics facilitate predictive maintenance and operational planning, minimizing downtime and costs. These innovations support the integration of distributed energy resources (DERs) and foster consumer engagement through demand response programs. Ongoing investments in these digital tools are critical to improving grid flexibility and accommodating the increasing share of renewable energy sources in Europe.
Restraints
High Capital and Operational Costs
Significant capital expenditure is required for upgrading existing infrastructure and deploying new clean energy projects, posing financial barriers especially for smaller utilities and regional grids. These costs encompass transmission network reinforcement, smart grid implementation, and energy storage deployment. In regions with limited financial capacity or uncertain policy environments, these investments can delay modernization efforts. High operational costs related to maintaining aging infrastructure, especially in Eastern Europe, further strain industry budgets. While technological innovations are reducing costs over time, the initial financial outlay remains a notable obstacle to rapid market expansion.
Navigating Regulatory and Market Fragmentation
Europe’s diverse regulatory landscape, with varying national policies, market rules, and incentives, complicates large-scale project deployment and cross-border integration. This fragmentation can delay project approvals, increase administrative costs, and lead to inconsistent investment climates across regions. For instance, differing grid codes and approval processes hinder seamless transmission expansion and add complexity for market players aiming for pan-European solutions. These regulatory disparities necessitate extensive coordination efforts and harmonization initiatives, which can slow down the pace of infrastructure modernization and technological adoption in some markets.
Supply Chain Constraints and Resource Availability
Global supply chain disruptions, driven by geopolitical tensions and pandemic-related effects, impact the availability of critical components such as transformers, smart meters, and renewable equipment. Europe’s reliance on imports for key technology components creates vulnerabilities, leading to delays and increased costs. Additionally, shortages of raw materials like lithium and rare earth metals impede battery and storage system development. These resource constraints pose risks to project timelines and overall market growth, emphasizing the need for diversified supply chains, local manufacturing capabilities, and sustainable resource management strategies to sustain industry momentum.
Opportunities
Expansion of Grid Modernization and Digital Infrastructure
The prevailing trend toward smarter, more flexible grids presents vast opportunities for industry players. Deploying advanced digital infrastructure such as smart meters, sensors, and AI analytics enables real-time grid management, enhances reliability, and supports the integration of distributed energy resources. Governments are increasingly funding digital transition initiatives, fostering ecosystem collaborations between tech startups, utilities, and service providers. The growth of microgrids and virtual power plants exemplifies innovative concepts that can reshape market dynamics, reduce outages, and optimize asset utilization, creating a fertile environment for new investments and technological breakthroughs.
Investments in Hydrogen and Green Gas Technologies
Hydrogen is emerging as a crucial component in Europe’s decarbonization trajectory, offering potential for decarbonizing sectors like industry and transport. Investments are flowing into green hydrogen production, storage, and infrastructure, supported by public funding and private sector commitments. This opens pathways for expanding transmission networks to carry hydrogen-rich gases, complementing existing natural gas grids. The development of hydrogen hubs and cross-border pipelines enhances regional integration possibilities. Such investments not only diversify the energy mix but also stimulate innovation, create jobs, and position Europe as a leader in clean energy technology exports.
Startup Ecosystem and Innovation Hubs
The burgeoning startup scene focused on renewable technologies, smart grids, and energy management solutions is catalyzing advances in the sector. Innovation hubs across Germany, the Nordics, and Benelux countries foster collaboration between academia, industry, and government, accelerating pilot projects and commercialization efforts. Venture capital funding in clean energy startups has surged, indicating robust market confidence. These ecosystems facilitate the rapid development and deployment of disruptive technologies like AI-enabled analytics and blockchain for energy trading, providing the industry with scalable opportunities to enhance efficiency, reduce costs, and improve customer engagement.
Emerging Technologies in Storage and Flexibility
Advances in battery technology, flow batteries, and other energy storage solutions are critical for mitigating the intermittent nature of renewable sources. Europe's focus on grid flexibility drives investments in long-duration storage, power-to-X, and demand response systems. These technologies enable better load balancing, grid stabilization, and capacity management, unlocking new revenue streams. Additionally, innovative approaches such as vehicle-to-grid (V2G) and hybrid energy systems are opening novel markets for prosumers and aggregators, fostering a more decentralized and resilient energy system capable of meeting the evolving needs of European consumers and utilities alike.
Challenges
Integrating High Shares of Intermittent Renewables
Incorporating large proportions of variable renewable energy poses grid stability challenges, including frequency regulation, voltage control, and system balancing. These issues demand sophisticated control systems, extensive forecasting, and enhanced grid infrastructure, incurring substantial costs and technological complexity. In regions with less developed grids or limited interconnection capacity, these challenges are more acute, potentially restricting renewable deployment. Overcoming these hurdles requires concerted efforts in grid modernization, storage integration, and regional cooperation, emphasizing the need for strategic investments and policy support.
Managing Transition-Induced Market Uncertainties
The shift toward decarbonization introduces market uncertainties related to policy changes, technological evolution, and investor confidence. Fluctuating regulatory support, carbon pricing dynamics, and technological obsolescence can impact project viability and investment returns. Utilities and independent developers face risks of stranded assets and revenue volatility, complicating financial planning. To address these issues, industry stakeholders must develop flexible business models, advocate for stable policy frameworks, and employ advanced risk management tools that enable adaptive strategies in a rapidly evolving market landscape.
Industry Statistics & Key Business Metrics
The Europe generation, transmission, and distribution market demonstrates robust growth driven by increasing investment in renewable energy and modernization efforts across the continent. Despite challenges such as aging infrastructure and regulatory complexities, the market's evolving landscape is characterized by significant technological advancement and expansion to meet future energy demands.
- In 2026, the market size is estimated at USD 350 Billion, reflecting steady growth in energy infrastructure investments, as reported by industry analysts (European Energy Agency).
- The market is anticipated to grow at a CAGR of 6.2% from 2026 to 2034, driven by the European Union’s climate goals and renewable integration policies.
- By 2034, the market value is projected to reach approximately USD 610 Billion, supported by increasing renewable capacity additions and grid modernization projects (European Commission).
- The renewable energy segment accounted for 45% of the market in 2026, with wind and solar leading the expansion (WindEurope and SolarPower Europe reports).
- Transmission infrastructure investments are expected to increase by 8% annually through 2034, as countries expand cross-border interconnections to enhance grid stability (European Network of Transmission System Operators for Electricity - ENTSO-E).
- European governments are investing over USD 95 Billion in smart grid technologies and grid modernization efforts between 2026 and 2034 (EU’s Horizon Europe Funding Reports).
- The private sector’s share in the market is climbing, with over USD 120 Billion in investments recorded in 2026, indicating rising industry confidence and scalable project deployments (European Industry Associations).
- The market’s digital transformation, including the adoption of AI and IoT for grid management, is projected to reach USD 80 Billion in value by 2034, enabling enhanced operational efficiency and reliability (International Renewable Energy Agency - IRENA)).
Market Segmentation
The Europe Generation, Transmission, and Distribution Market is segmented based on Product, Component, and Geography, enabling a detailed analysis of regional demand, technological adoption, and market dynamics. This segmentation facilitates targeted strategic planning and market assessment across various facets of the energy infrastructure sector.
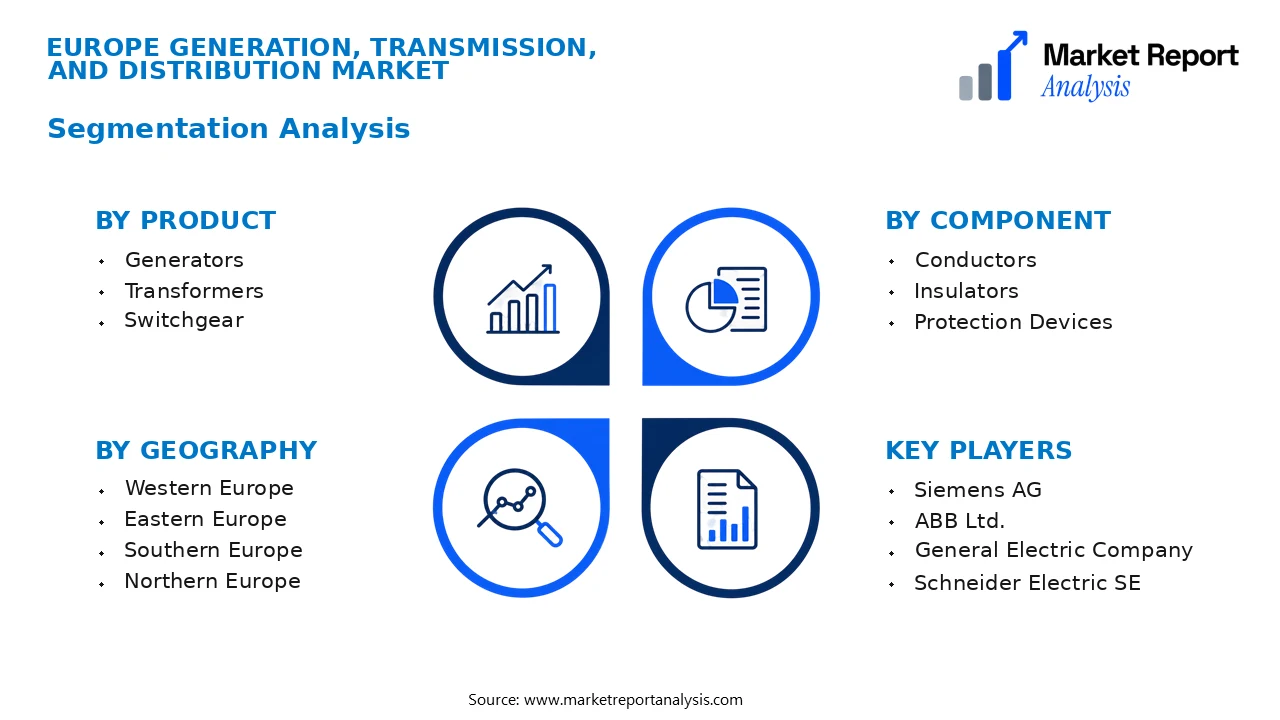
- Product
- Generators: This subsegment includes power generation units such as nuclear, thermal, hydro, and renewable sources which form the core of electricity production in Europe. The demand for generators is driven by the transition toward renewable energy and modernization of existing capacity.
- Transformers: Transformers are critical for voltage regulation and power transmission efficiency, widely used in substations and distribution networks. The expanding grid infrastructure boosts demand for advanced transformer technologies, especially those supporting high-voltage applications.
- Switchgear: Switchgears are essential for protecting, controlling, and isolating electrical equipment, contributing greatly to grid stability. Increased grid complexity and smart grid initiatives are prompting higher adoption rates of intelligent switchgear solutions.
- Component
- Conductors: Conductors facilitate the efficient transmission of electricity across the grid. The focus on reducing transmission losses and integrating renewable sources is stimulating demand for high-conductivity, durable conductor materials.
- Insulators: Insulators prevent unwanted flow of current to other parts of the system, ensuring safety and stability. Demand has been rising due to upgrades in existing infrastructure and new grid development projects in Europe.
- Protection Devices: These devices are vital for equipment safety and system reliability by disconnecting faults or overloads. Their growth correlates with the expansion of smart grid technologies and automation in grid management.
- Geography
- Western Europe: Featuring mature infrastructure with high penetration of renewable energy and smart grid systems, Western Europe is a key region for advanced transmission and distribution technologies.
- Eastern Europe: Characterized by expanding grid capacity and modernization efforts, Eastern Europe presents growth opportunities driven by new investments and regulatory incentives aimed at energy security and sustainability.
- Southern Europe: This region emphasizes integrating renewable sources like solar and wind, requiring upgrades in transmission infrastructure, which fuels the market for specialized components and equipment.
- Northern Europe: Known for its technological innovation and renewable energy projects, Northern Europe continues to adopt cutting-edge transmission and distribution solutions to enhance grid stability and efficiency.
Competitive Intelligence
The Europe Generation, Transmission, and Distribution Market is characterized by moderate competition with a mix of established players like Siemens, ABB, and General Electric, alongside emerging regional firms. Market concentration remains relatively balanced, with the top five companies capturing approximately 60% of the market share, fostering competitive dynamics that drive innovation. Firms are adopting aggressive strategies centered on product innovation, notably the development of smart grid technologies, and enhancing grid resilience through advanced automation. Strategic partnerships are prevalent, often involving joint ventures to expand technological prowess and market reach, while acquisitions target regional players to consolidate market presence and diversify portfolios. Expansion strategies prioritize investments in renewable energy integration and grid modernization projects across Europe, aligning with increasing regulatory push for sustainability. R&D investments underpin these initiatives, with companies focusing on next-generation transmission and distribution solutions that offer superior efficiency and reliability. Differentiation in this landscape hinges on technological innovation, comprehensive service offerings, and sustainable product portfolios, positioning key players to maintain competitive advantage amidst evolving market demands.
Leading Company Profiles
The competitive landscape of the Europe generation, transmission, and distribution market is characterized by a blend of established multinational corporations and innovative local players. These companies are driving technological advancements and strategic collaborations to enhance grid modernization, integrate renewable energy sources, and achieve sustainability targets.
- Siemens AG
- ABB Ltd.
- General Electric Company
- Schneider Electric SE
- Vestas Wind Systems A/S
- Enel S.p.A.
- Iberdrola, S.A.
- EDF Group
- E.ON SE
- Vattenfall AB
Siemens AG
Siemens AG leads in grid infrastructure and automation, offering advanced grid management solutions, renewables integration, and digital grid services, aligning with Europe's push for sustainable, resilient power systems.
ABB Ltd.
ABB specializes in electrification, automation, and digital solutions for utilities and industry, focusing on smart grid technologies, HVDC systems, and renewable integration to support Europe's decarbonization efforts.
General Electric Company
GE contributes with innovative gas turbines, grid solutions, and services, emphasizing modernization of Europe's power infrastructure and expanding renewable energy capabilities, backed by its global service network.
Schneider Electric SE
Schneider Electric is prominent in energy management and automation, delivering integrated solutions that enhance efficiency, grid stability, and renewable integration for utilities and large industrial clients.
Vestas Wind Systems A/S
Vestas is a leading wind turbine manufacturer, heavily involved in new installations across Europe, driving the transition towards sustainable, wind-based power generation, with innovations in turbine technology and digital monitoring.
Enel S.p.A.
Enel focuses on renewable energy development, grid modernization, and digital transformation, emphasizing large-scale solar and wind project developments to meet Europe's climate targets.
Iberdrola, S.A.
Iberdrola is a major renewable energy producer, innovating in smart grids and energy storage, and expanding its European footprint through acquisitions and strategic partnerships in renewables.
EDF Group
EDF's priorities include nuclear power, renewables, and grid stability projects, leveraging its strong European presence to foster clean energy transitions and invest in smart grid infrastructure.
E.ON SE
E.ON specializes in energy services, grid operation, and renewables, deploying digital solutions to optimize grid performance and integrating distributed energy resources within Europe's evolving energy landscape.
Vattenfall AB
Vattenfall’s focus on wind, hydro, and solar projects underpins its core strategy of sustainable power generation, with substantial investments in digital grid management and community energy initiatives in Europe.
Strategic Business Developments

- May 2023 – Siemens AG – Launch of new digital twin platform for grid management – Enhances operational efficiency and predictive maintenance capabilities across European grids.
- April 2023 – ABB Ltd. – Expansion of HVDC manufacturing facilities in Germany – Strengthens supply chain resilience and supports large-scale renewable interconnection projects.
- June 2023 – General Electric Company – Acquisition of a European renewable services firm – Expands GE’s presence and service capacity in the growing European wind and solar markets.
- March 2023 – Schneider Electric SE – Partnership with national grid operators to develop smart grid pilot projects – Promotes grid stability and renewable integration through innovative automation solutions.
- January 2023 – Vestas Wind Systems A/S – Launch of next-generation wind turbine platform in Denmark – Improves energy output and reduces maintenance costs, boosting competitiveness in European markets.
Frequently Asked Questions
What is the Europe Generation, Transmission, and Distribution Market?
The Europe Generation, Transmission, and Distribution Market encompasses the infrastructure and services involved in producing, transmitting, and distributing electricity across European countries. It includes various energy sources, grid operations, and distribution networks essential for power supply.
What is the current market size of Europe Generation, Transmission, and Distribution Market?
As of 2026, the market is valued at approximately USD 245 Billion, driven by increasing energy demand, transition to renewable sources, and modernization efforts within Europe's electricity infrastructure.
What factors are driving the Europe Generation, Transmission, and Distribution Market?
Key drivers include the shift towards renewable energy, government policies encouraging clean energy adoption, technological advancements in grid management, and the need for modernization to enhance grid reliability and efficiency across the region.
Which region dominates the Europe Generation, Transmission, and Distribution Market?
Western Europe leads the market, benefiting from advanced infrastructure, higher renewable integration, and significant investments in smart grid technologies, while Eastern Europe is rapidly growing due to modernization efforts and infrastructure upgrades.
Which segment is expected to grow the fastest?
The renewable energy segment, particularly wind and solar, is forecasted to grow at the highest CAGR, owing to supportive policies, declining costs, and the push for decarbonization within Europe's energy landscape.
Who are the leading companies operating in the Europe Generation, Transmission, and Distribution Market?
Major players include Enel, Iberdrola, National Grid, Terna, and EDP, which are expanding their capacities through grid modernization, renewable integration, and strategic acquisitions across the continent.
Analyst Perspective
The Europe generation, transmission, and distribution market is poised for sustained growth through 2034, driven by increasing integration of renewable energy sources, modernization initiatives, and policy support for decarbonization. Long-term prospects remain favorable, with regional governments prioritizing infrastructure upgrades and clean energy transition, creating substantial commercial opportunities in grid modernization, smart grid deployment, and renewable integration. Technological evolution will focus on advanced grid management systems, decentralized energy resources, and energy storage solutions, enhancing grid resilience and efficiency. Investment priorities should emphasize digital infrastructure, upgrading aging assets, and fostering regional interconnections to facilitate energy flow across borders. Competitive intensity is expected to intensify as established utilities adapt to new market entrants and innovative technologies. North-Western and Central Europe exhibit the highest growth potential owing to robust policy frameworks and economic strength, whereas Eastern Europe offers emerging opportunities amidst ongoing infrastructural development. Strategic positioning will require stakeholders to balance innovation with regional regulatory nuances and long-term sustainability goals.
