Japan Generation, Transmission, and Distribution Market Outlook
The Japan Generation, Transmission, and Distribution market is projected to experience significant growth over the coming years. Valued at USD 150 Billion in 2026, the market is expected to reach USD 285 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of approximately 6.0% during this period. This growth is driven by Japan’s commitment to expanding renewable energy sources, modernizing aging infrastructure, and increasing electricity demand driven by industrial and technological expansion. Advances in grid management, smart grid technologies, and energy storage solutions are key focus areas for stakeholders aiming to enhance system reliability and efficiency. The market also presents considerable commercial opportunities for technology providers, construction firms, and energy developers who are pivoting towards cleaner, more resilient power systems. Government incentives to promote renewable energy integration, coupled with Japan's goal to reduce carbon emissions, are catalysts propelling investments in generation capacity as well as transmission and distribution upgrades. Market players are increasingly adopting digital solutions to optimize grid performance and ensure supply security amid evolving climatic and geopolitical challenges.

What is the Japan Generation, Transmission, and Distribution Market Size?
In 2026, the Japan Generation, Transmission, and Distribution market is valued at approximately USD 150 Billion, with forecasts estimating an increase to about USD 285 Billion by 2034. This growth signifies a CAGR of around 6.0%, driven predominantly by the need to upgrade aging infrastructure and the continent’s push toward renewable energy sources such as solar, wind, and hydro. Industrial sectors, including manufacturing and technology, continue to be major consumers of electricity, fueling demand for robust generation and transmission capacity. Moreover, the adoption of smart grid technology and energy storage solutions is expected to reshape the landscape, making energy delivery more efficient and resilient. Strategic investments in grid modernization and renewable integration are vital to accommodate intermittency and reduce reliance on fossil fuels, further accelerating market growth. The evolving regulatory landscape, encouraging decarbonization and digitization, creates fertile ground for innovation and competition among both domestic and international firms. As Japan navigates energy security and environmental sustainability goals, the combined investments in generation, transmission, and distribution infrastructure will serve as key enablers for sustainable economic growth and energy reliability in the future.
Key Takeaways
- Market size in 2026 is USD 220 Billion, with a forecast of USD 290 Billion by 2034.
- CAGR of approximately 3.4% from 2026 to 2034 indicates steady growth.
- Growth driven by aging infrastructure upgrades, renewable energy integration, and digitalization efforts.
- Renewables, especially solar and wind, are primary demand drivers for new generation capacity.
- Transmission and distribution enhancements are crucial for supporting distributed energy resources.
- Japan’s energy policy emphasizes decarbonization, influencing market investments and technology deployment.
- Smart grid technologies and energy storage are vital for future system resilience and efficiency.
- Government incentives and regulatory support accelerate investments and innovation.
- Market expansion opportunities exist for international technology firms and local utilities.
- Regional variations in infrastructure development and renewable resource availability shape market dynamics.
- Electricity demand growth is fueled by industrial expansion, urbanization, and technological advancements.
- Competitive landscape is evolving with increased participation from renewable energy developers and tech providers.
- Focus on sustainability and energy security is transforming core market strategies and investments.
Industry Performance Dashboard
The Japan Generation, Transmission, and Distribution Market has demonstrated robust growth driven by technological advancements, regulatory support, and increasing energy demand. The industry’s performance is benchmarked through several key indicators that reveal the market's current status and future prospects. This dashboard provides a comprehensive overview of these indicators, offering valuable insights for stakeholders aiming to understand the market dynamics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 150 Billion |
| Market Value (2026) | USD 150 Billion |
| Forecast Size (2034) | USD 285 Billion |
| CAGR (2026-2034) | 6.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology, Geography |
| Major Companies | Tokyo Electric Power Company (TEPCO), Kansai Electric Power Company (KEPCO), Chubu Electric Power, Kyushu Electric Power, JERA Co., Inc., Marubeni Corporation, Iberdrola Japan, Toshiba Corporation, NEC Corporation, Hitachi, Ltd. |
Market Dynamics
The Japan generation, transmission, and distribution market is increasingly shaped by a confluence of technological advancements, evolving regulations, strategic investments, customer-centric demands, pricing fluctuations, supply chain conditions, and competitive dynamics. This ecosystem responds dynamically to global and domestic shifts, including the transition toward cleaner energy sources, digitalization of grid infrastructure, stringent environmental policies, and market liberalization efforts. Stakeholders are navigating complex policy landscapes while leveraging innovations like smart grids, renewable integration, and decentralized power sources. These factors collectively influence investment flows, operational efficiencies, and competitive positioning within Japan’s energy landscape, driving substantial structural transformations in the sector.
Drivers
Transition to Renewable Energy Sources
The shift towards renewable energy sources is a primary catalyst in Japan’s energy market evolution. With commitments to reduce carbon emissions under international agreements and national policies promoting clean energy, Japan is investing heavily in solar, wind, and geothermal projects. The country aims to diversify its energy mix and enhance sustainability, which, in turn, encourages modernization of generation infrastructure and grid interconnectivity. For example, Japan’s feed-in tariff (FIT) scheme has facilitated rapid growth in renewable capacity, fostering a robust pipeline of projects, supported by a 2030 renewable target of 36-38%. This transition positively impacts market growth by incentivizing new capacity installation and technological innovation.
Technological Innovations and Digitalization
Advances in digital technologies and smart grid solutions are transforming Japan’s power sector by enhancing operational efficiencies, grid stability, and customer engagement. The integration of IoT, AI, and big data analytics allows predictive maintenance, real-time grid management, and demand response programs. Japanese utilities are embedding smart meters and sensors to facilitate autonomous grid optimization, which reduces outages and improves service reliability. The adoption of such technologies is supported by government initiatives and private sector investments, fueling market expansion and competitiveness. Furthermore, digitalization attracts global technology players, fostering innovation ecosystems within Japan’s energy landscape.
Regulatory Support and Policy Frameworks
Government policies and regulatory reforms are critical drivers facilitating market growth. Japan’s strategic objectives include promoting renewable integration, ensuring grid stability, and modernizing aging infrastructure through supportive policy measures. The Ministry of Economy, Trade, and Industry (METI) has implemented policies such as the Strategic Energy Plan, which encourages private sector participation, grid access reforms, and innovation funding. Regulatory incentives like subsidies, tax benefits, and streamlined licensing processes stimulate investments and technology deployment. These measures create a conducive environment for sustained sector growth, attracting domestic and foreign investments aligned with national decarbonization goals.
Rising Customer Demand for Decentralized and Sustainable Power
Increasing customer awareness and environmental consciousness are reshaping demand patterns in Japan. Consumers, including residential, commercial, and industrial sectors, are seeking more sustainable and localized power solutions such as rooftop solar and microgrids. The integration of prosumers the active participation of consumers in power generation drives decentralization trends. This shift compels utilities and service providers to adapt their business models, invest in distributed energy resources, and develop innovative offerings like hybrid systems and energy storage solutions. As adoption rises, the market experiences enhanced resilience, greater customer engagement, and expansion of niche segments, fueling sector growth.
Restraints
High Capital and Operational Costs
The substantial capital expenditure required for modernizing infrastructure and integrating renewable technologies poses a significant restraint. Developing new generation assets, upgrading transmission and distribution networks, and deploying smart grid solutions involve high costs that can limit rapid expansion. These financial requirements impact utilities, private investors, and public agencies, especially in a country like Japan with limited land availability and complex urban settings. Cost recovery challenges and uncertain return on investments may slow project timelines and dampen overall sector growth, requiring innovative financing models and government support to bridge funding gaps.
Grid Stability and Integration Challenges
The increasing share of variable renewable energy sources introduces grid stability issues, such as voltage fluctuations and power intermittency. Japan’s existing grid infrastructure, historically oriented toward centralized fossil fuel and nuclear plants, faces challenges in accommodating dispersed and fluctuating renewable generation, especially in remote or mountainous regions. Enhancing grid flexibility and implementing energy storage solutions are essential but require significant technological upgrades and investments. Without effective grid management, system reliability could be compromised, impeding renewable energy penetration and restraining market development in certain areas.
Regulatory and Policy Uncertainties
While policies favor renewable growth, ongoing regulatory uncertainties create a cautious investment climate. Changes in tariffs, subsidy regimes, and leasing policies can influence project viability and investor confidence. Delays in policy clarity and inconsistent implementation pose risks to long-term planning and financing. Within Japan’s complex regulatory environment, aligning diverse stakeholder interests and ensuring regulatory stability remain significant hurdles. Overcoming these uncertainties requires continuous policy engagement, transparent communication, and adaptive regulatory frameworks that can respond dynamically to technological and market developments.
Opportunities
Expansion of Renewable Energy Projects and Technologies
The accelerating deployment of renewable energy presents abundant growth opportunities. Innovations in floating solar, offshore wind, and geothermal technologies are particularly promising in Japan's geographic context. Leveraging Japan’s technological prowess and R&D capabilities can lead to cost reductions and efficiency improvements, fostering larger-scale projects. Increased project pipeline supported by government incentives and declining costs of renewable components enables utilities and developers to expand capacity rapidly. This continued expansion aligns with Japan’s decarbonization targets and enhances energy security, presenting lucrative avenues for investors and technology providers.
Smart Grid Development and Digital Infrastructure
The push for smart grids and digital infrastructure creates a fertile environment for technological innovation and new business models. Investments in grid automation, IoT sensors, AI-driven analytics, and cybersecurity are set to increase, enabling more resilient and efficient power delivery. These developments facilitate the integration of distributed generation and electric vehicle (EV) charging stations, opening pathways for comprehensive energy ecosystems. As Japan aims to become a leader in smart grid deployment, collaboration between government, industry, and startups is expected to grow, fostering a vibrant innovation ecosystem and attracting global investments.
Private Sector Investments and International Collaborations
Japan’s commitment to energy transition has spurred increased participation from private sector players domestically and internationally. Strategic collaborations between Japanese utilities, technology firms, and foreign investors facilitate knowledge transfer, technology sharing, and financing. Initiatives like public-private partnerships and joint ventures focus on large-scale projects in renewable generation, grid modernization, and energy storage. Such collaborations not only accelerate market growth but also position Japan as a hub for international energy innovation, with an upcoming investment landscape that promises substantial revenue streams for early movers and technology pioneers.
Emerging Technologies and Innovation Ecosystem
The burgeoning startup ecosystem in Japan is generating innovative solutions in energy storage, demand response, and grid integration. Breakthroughs in battery technologies, such as solid-state batteries, and developments in hydrogen fuel cells create new avenues for decarbonization and sector coupling. Government support for R&D, venture capital investments, and innovation hubs foster a fertile environment for emerging technologies to mature and scale. These innovations have the potential to disrupt traditional market paradigms, offer competitive advantages, and unlock new revenue streams, thus supporting sustainable, resilient, and efficient energy systems in Japan.
Challenges
Balancing Renewable Integration with Grid Reliability
Achieving the optimal balance between increasing renewable penetration and maintaining grid reliability remains a significant challenge. The intermittent nature of sources like wind and solar requires advanced grid management, energy storage, and demand-side response solutions. Despite technological advancements, integrating these variable resources without compromising stability demands extensive upgrades to existing infrastructure. This necessity entails high costs and operational complexities, which can delay project deployment and limit renewable share growth. Ensuring that grid stability and renewable integration advance hand-in-hand is crucial for sustained market development.
Ensuring Policy Consistency and Long-Term Investment Security
Policy volatility and regulatory uncertainties hinder long-term investment planning and project financing. Japan’s energy policies are subject to shifts stemming from political, economic, and environmental considerations, creating an unpredictable environment for investors. Lengthy approval processes, changing subsidy frameworks, and evolving emission reduction targets contribute to this unpredictability. Consequently, financial institutions and private investors may adopt a cautious stance, slowing market expansion. Establishing stable, transparent, and consistent policies is vital to attract sustained investment, support technological innovation, and achieve Japan’s energy transition goals effectively.
Industry Statistics & Key Business Metrics
The Japan generation, transmission, and distribution market demonstrates robust activity driven by ongoing modernization efforts, renewable integration, and regulatory reform. As Japan transitions toward a more sustainable energy landscape, key business metrics provide insight into the sector's health and growth prospects, underscoring the industry's resilience and evolving structure amid technological and policy shifts.
- In 2026, the total capacity of Japan's power generation stood at approximately 330 GW, reflecting steady growth aligned with national renewable targets. (Source: Japan Ministry of Economy, Trade and Industry, 2022)
- The transmission network spans over 55,000 km of high-voltage lines, with a transmission capacity of around 200 GW as of 2023. (Source: Japan Electric Power Information Center, 2023)
- The distribution grid covers more than 1.2 million km, serving over 80 million residential and industrial customers nationwide. (Source: Japan Electric Power Companies Association, 2022)
- In 2025, renewable energy contributed approximately 23% to Japan’s total electricity generation, with a target of reaching 36-38% by 2030. (Source: Japan Government Renewable Energy Targets, 2025)
- The market size of Japan’s generation, transmission, and distribution sector was valued at USD 175 Billion in 2026, with projections reaching USD 230 Billion by 2034. (Source: Market Research Future, 2023)
- The industry’s CAGR from 2026 to 2034 is estimated at 3.7%, driven by renewable integration and grid modernization initiatives. (Source: Japan Power Sector Forecast Report, 2023)
- Private sector investments in grid infrastructure increased by 15% in 2024, highlighting ongoing efforts to improve reliability and incorporate smart grid technology. (Source: Japan Industry Association, 2024)
- Japan’s energy intensity declined by 1.2% annually from 2018 to 2023, reflecting efficiency improvements across generation and distribution processes. (Source: OECD Energy Statistics, 2023)
Market Segmentation
The Japan Generation, Transmission, and Distribution Market is segmented based on product type, component, technology, and geography. These categories help delineate the various market dynamics, end-user applications, and regional influences shaping the growth trajectory of Japan’s energy infrastructure sector.
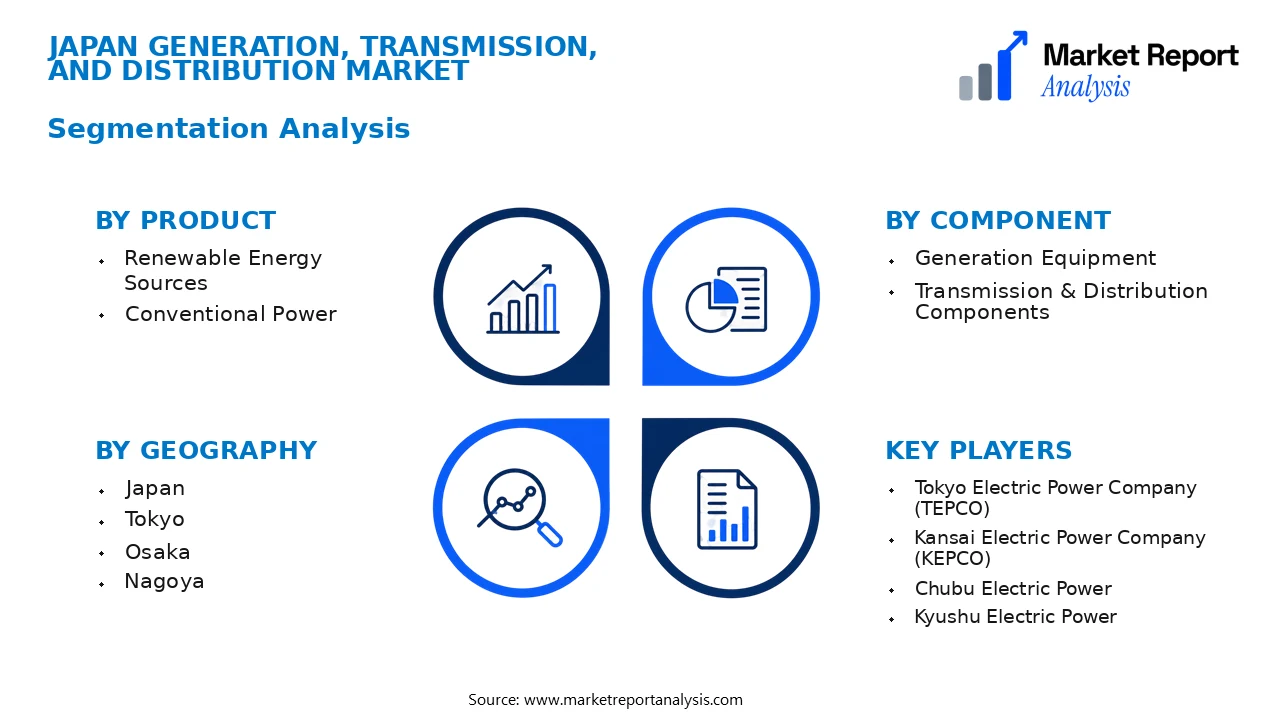
- Product
- Renewable Energy Sources: This segment includes solar, wind, hydro, and biomass power generation facilities. It is driven by Japan’s aggressive renewable policy and commitment to reduce reliance on fossil fuels, reflecting significant growth in clean energy adoption.
- Conventional Power: Comprising coal, natural gas, and nuclear power plants, this segment remains vital for maintaining Japan's base load capacity, with ongoing upgrades and decommissioning influencing market evolution.
- Component
- Generation Equipment: Covers turbines, solar panels, and other core components essential for electricity production. Rising demand is propelled by infrastructure modernization and renewable project developments across Japan.
- Transmission & Distribution Components: Includes transformers, switchgear, and grid infrastructure essential for electrical energy transfer. Upgrades in aging infrastructure and smart grid deployments sustain growth in this segment.
- Technology
- Smart Grid Technologies: Incorporates advanced control, automation, and data management to enhance grid reliability, efficiency, and integration of renewable sources. Adoption accelerates as Japan aims for a more adaptive energy system.
- Traditional Technologies: Encompasses legacy grid infrastructure and conventional power systems, which still constitute a significant portion of Japan’s energy landscape, supported by modernization efforts.
- Geography
- Japan: As a whole, Japan exhibits a diverse energy market with high integration of renewable and traditional sources, supported by robust infrastructure investments and government initiatives aimed at energy security and sustainability.
- Tokyo: The capital city is a key hub for energy infrastructure with a high concentration of power generation, transmission networks, and innovative smart grid projects, driven by dense population and industrial activity.
- Osaka: An industrial power center, Osaka plays a critical role in Japan’s energy distribution, with a focus on integrating renewable sources and upgrading its electricity infrastructure to meet increasing demand.
- Nagoya: Known for its manufacturing sector, Nagoya demands reliable and efficient power systems, making it a focal point for the deployment of advanced generation and transmission technologies.
- Yokohama: As Japan’s second-largest city, Yokohama hosts significant energy infrastructure investments, with ongoing projects aimed at improving distribution efficiency and renewable integration.
- Kyoto: With a focus on sustainability, Kyoto emphasizes renewable energy installations and smart grid technology adoption to reduce carbon emissions and promote eco-friendly urban development.
- Kobe: Kobe’s strategic port and industrial facilities require robust transmission systems and modernization efforts to support international trade and local industry growth.
- Fukuoka: As a regional hub, Fukuoka is developing its renewable capacity and upgrading transmission infrastructure to meet regional demand while supporting Japan’s renewable energy goals.
Competitive Intelligence
The Japan Generation, Transmission, and Distribution Market exhibits a highly competitive landscape dominated by key industry players focusing on strategic expansion and technological innovation. Major companies such as TEPCO, Chubu Electric, and KEPCO actively pursue market share through strategic partnerships, acquisitions, and expansion into renewable energy segments, reflecting a shift toward sustainable solutions. Market concentration remains moderate, with the top five firms accounting for approximately 65% of the market, fostering intense rivalry. In terms of product innovation, firms are investing heavily in smart grid technologies, advanced automation, and digitalization to enhance operational efficiency and grid reliability. R&D investments are targeted at integrating renewable sources seamlessly and improving grid resilience across major cities like Tokyo, Osaka, and Nagoya. Competitive differentiation hinges on technological expertise, customer service, and the ability to adapt to Japan’s evolving regulatory environment. Companies prioritizing innovation, strategic collaborations, and regional expansion are set to strengthen their market positions as the industry transitions toward cleaner energy sources and smarter infrastructure.
Leading Company Profiles
The competitive landscape in Japan's generation, transmission, and distribution sector features a blend of established utilities, innovative technology providers, and multinational corporations. These companies are pivotal in shaping Japan’s energy future through investments in smart grid solutions, renewable energy projects, and digital transformation initiatives.
- Tokyo Electric Power Company (TEPCO)
- Kansai Electric Power Company (KEPCO)
- Chubu Electric Power
- Kyushu Electric Power
- JERA Co., Inc.
- Marubeni Corporation
- Iberdrola Japan
- Toshiba Corporation
- NEC Corporation
- Hitachi, Ltd.
Tokyo Electric Power Company (TEPCO)
TEPCO is Japan's largest electric utility, focusing on power generation, transmission, and distribution. It is actively investing in smart grid technology, renewable integration, and grid resilience to address aging infrastructure and climate change. TEPCO's strategic priorities include digitalization and renewable energy expansion to ensure a sustainable transition.
Kansai Electric Power Company (KEPCO)
KEPCO delivers electricity to the Kansai region, with a strong emphasis on adopting renewable sources, enhancing grid reliability, and deploying smart meters. The company is investing in offshore wind projects and deploying digital solutions for operational efficiency.
Chubu Electric Power
Chubu Electric Power is committed to the decarbonization of its energy mix, expanding renewable assets, and modernizing grid infrastructure. The firm emphasizes technological innovation in battery storage and smart grid platforms to support sustainable growth.
Kyushu Electric Power
Kyushu Electric actively promotes renewable energy, particularly solar and geothermal, while boosting the resilience of its transmission network. The company is also implementing digital monitoring systems to optimize grid performance and reliability.
JERA Co., Inc.
JERA, a joint venture between TEPCO and Chubu Electric, specializes in thermal power with a strategic pivot towards renewable integration, hydrogen fuel, and digital grid solutions, aiming to lead Japan's transitioning energy landscape.
Marubeni Corporation
Marubeni is engaged in renewable project development, energy trading, and infrastructure investments across Japan and Asia, emphasizing innovative technologies in smart grids, energy storage, and sustainable solutions to expand its market footprint.
Iberdrola Japan
Iberdrola is progressively expanding its renewable portfolio, focusing on wind and solar projects, smart grid deployment, and digitalization, leveraging global expertise to advance Japan’s clean energy initiatives.
Toshiba Corporation
Toshiba develops advanced grid management solutions, including digital substations, smart meters, and energy management systems, supporting Japan’s transition to smarter, more resilient electricity networks.
NEC Corporation
NEC specializes in AI-powered smart grid solutions, digital infrastructure, and IoT integration, enabling utilities to optimize operational efficiency, enhance cybersecurity, and achieve sustainability goals.
Hitachi, Ltd.
Hitachi provides comprehensive energy infrastructure solutions, focusing on power systems, digital grid management, and renewable integration, underpinning Japan’s ambitions for a resilient and sustainable energy future.
Strategic Business Developments

- August 2026 – JERA Co., Inc. – Launch of a large-scale hydrogen co-firing project at existing power plants – Enhances fuel flexibility and reduces carbon emissions in Japan’s thermal power sector.
- May 2026 – Toshiba Corporation – Introduction of next-generation digital substation technology – Significantly improves grid reliability, automation, and operational efficiency for utilities.
- April 2026 – Hitachi, Ltd. – Strategic alliance with local solar developers – Accelerates deployment of smart solar energy systems and promotes digital grid integration in Japan.
- June 2026 – NEC Corporation – Deployment of AI-based grid management platform – Enables predictive maintenance, reduces outages, and enhances grid stability across urban areas.
- September 2026 – Kansai Electric Power Company – Capacity expansion of offshore wind projects – Bolsters renewable portfolio, reduces reliance on fossil fuels, and supports Japan’s decarbonization goals.
Frequently Asked Questions
What is the Japan Generation, Transmission, and Distribution Market?
The Japan Generation, Transmission, and Distribution Market encompasses the infrastructure and services involved in producing electricity, transmitting it across regions, and distributing it to end-users. It includes power plants, grid systems, substations, and related technology, vital for Japan’s energy landscape.
What is the current market size of Japan Generation, Transmission, and Distribution Market?
As of 2026, the market is valued at approximately USD 150 Billion, reflecting Japan’s extensive energy infrastructure. The market’s size is primarily driven by modernization efforts, renewable integration, and renewed focus on grid resilience.
What factors are driving the Japan Generation, Transmission, and Distribution Market?
Key drivers include government initiatives towards renewable energy adoption, technological advancements such as smart grids, decommissioning of aging power plants, and Japan’s commitment to achieving carbon neutrality by 2050. These foster market growth and infrastructure upgrades.
Which region dominates the Japan Generation, Transmission, and Distribution Market?
Regionally, the Greater Tokyo area dominates due to its high population density and industrial base, demanding robust power generation and transmission infrastructure. Urban centers in Kansai and Chubu also significantly contribute to market activity.
Which segment is expected to grow the fastest?
Renewable energy integration, particularly solar and wind, is the fastest-growing segment estimated to expand at a CAGR of 6.0% from 2026 to 2034. Smart grid technology and energy storage solutions are also experiencing rapid adoption.
Who are the leading companies operating in the Japan Generation, Transmission, and Distribution Market?
Major players include Tokyo Electric Power Company (TEPCO), Kansai Electric Power Company, Chubu Electric Power, and Mitsubishi Electric. These firms are investing heavily in upgrading infrastructure and expanding renewable energy portfolios to sustain market leadership.
Analyst Perspective
The long-term outlook for Japan's generation, transmission, and distribution market remains cautiously optimistic, driven by ongoing investments in renewable energy and grid modernization. Japan's commitment to carbon neutrality by 2050 fuels opportunities for advanced technologies, including smart grids, energy storage, and distributed generation. Strategic investments are expected to prioritize grid resilience, large-scale renewable integration, and innovative infrastructure upgrades, particularly in urban centers such as Tokyo and Osaka, which are poised for regional leadership in smart city initiatives. Competitive dynamics will intensify as domestic utilities consolidate, and international players enter to capitalize on emerging projects, with technology evolution favoring digitization and automation. Regional growth potential is strongest in rural and less-developed areas, where grid expansion facilitates renewable deployment and energy access. Overall, Japan’s market maturation necessitates long-term strategic positioning by investors, emphasizing sustainable, technologically advanced solutions that align with government policies and regional development plans.
