Latin America Diabetes Drugs Market Outlook
The Latin America Diabetes Drugs Market is currently valued at approximately USD 3.5 Billion in 2026, with a forecasted growth to USD 7.4 Billion by 2034, representing a Compound Annual Growth Rate (CAGR) of about 10.2% during the period from 2026 to 2034. This growth is driven by increasing prevalence of diabetes, aging populations, and rising healthcare expenditure across the region. Technological advancements in drug formulations, including long-acting insulins and oral anti-diabetic medications, are transforming treatment paradigms. Moreover, the expansion of healthcare infrastructure and favorable government policies support market growth. The commercial landscape is expanding, with increased investments from global pharmaceutical companies targeting both developed and emerging markets within Latin America.
What is the Latin America Diabetes Drugs Market Size?
The Latin America Diabetes Drugs Market is projected to be valued at approximately USD 3.5 Billion in 2026 and is expected to grow to about USD 7.4 Billion by 2034, reflecting a CAGR of 10.2%. This growth stems from rising diabetes incidences driven by urbanization, changing dietary patterns, and sedentary lifestyles. The demand for innovative, effective, and affordable medications continues to surge, fueling market expansion. End-use industries, primarily healthcare providers including hospitals, clinics, and pharmacies, are increasingly adopting newer therapies. The integration of biotechnology and targeted treatments accelerates product innovation, encouraging ongoing investments from multinational corporations seeking market share. Future growth strategies include expanding access to insulin analogs and oral hypoglycemics, especially in underserved rural areas, which will open up new revenue streams for pharma companies. Overall, the market growth reflects an upward trajectory aligned with regional health and demographic shifts, presenting lucrative opportunities for stakeholders willing to navigate regulatory and competitive challenges.
Key Takeaways
- The Latin America Diabetes Drugs Market is set to grow from USD 3.5 Billion in 2026 to USD 7.4 Billion in 2034.
- The CAGR over the forecast period is approximately 10.2%, indicating robust expansion.
- Insulins remain the largest segment, driven by increasing insulin dependence among Type 1 and Type 2 diabetes patients.
- Oral anti-diabetic drugs are the fastest-growing segment, fueled by the development of novel formulations and generic options.
- Type 2 diabetes accounts for the majority of market demand, with new therapies targeting this group’s management.
- Pfizer, Novo Nordisk, and Sanofi are key players dominating the regional landscape.
- Public and private sector initiatives aim to improve access, creating further market opportunities.
- Technological advancements including biosimilars and combination therapies are shaping future market dynamics.
- Rising healthcare expenditure and increasing awareness boost adoption rates of advanced therapies.
- Regulatory pathways are gradually becoming more streamlined, encouraging new product launches.
- Untapped rural markets present significant growth potential for pharmaceutical companies.
- Price sensitivity remains high, emphasizing the importance of affordable medication development.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the Latin America Diabetes Drugs Market, emphasizing key performance indicators crucial for assessing market health and trajectory. The market size in 2026 is projected to reach USD 12.5 Billion, reflecting a robust growth driven by rising diabetes prevalence and expanding healthcare infrastructure across Latin America. Moving toward 2034, the forecast size is estimated at USD 22.3 Billion, with a compound annual growth rate (CAGR) of approximately 7.3% over the period from 2026 to 2034, indicating sustained demand and market maturation. The base year for analysis is 2026, serving as a pivotal benchmark for subsequent growth projections, with the forecast period spanning from 2026 to 2034. Segments covered in this dashboard include insulin and non-insulin therapies, with insulin showing rapid adoption due to technological advances and increased patient compliance. Major companies within this space include Novo Nordisk, Eli Lilly, Sanofi, and Boehringer Ingelheim, all of which hold significant market shares and are innovating through new product launches and collaborations. The market's trajectory suggests ongoing investments in R&D, strategic partnerships, and market expansion efforts, aligned with emerging healthcare policies aiming at improved diabetes care. These metrics collectively underscore a dynamic and expanding market poised for substantial growth, influenced by demographic shifts, healthcare policy reforms, and technological innovations.
Market Dynamics
The Latin America Diabetes Drugs Market is dynamically shaped by a confluence of technological advancements, regulatory shifts, strategic investments, evolving customer requirements, pricing strategies, supply chain conditions, and competitive behaviors. These factors collectively influence market accessibility, innovation pace, and product offerings, thereby determining the growth trajectory. Increasing health consciousness and government initiatives are simultaneously fostering demand, while technological innovations like biosimilars and new delivery systems are transforming treatment paradigms. Regulatory adaptations to foster affordability and access also play a critical role, alongside competitive dynamics that drive innovation, mergers, and market consolidation. This complex interplay forms the foundation of the current and future landscape of diabetes management in Latin America.
Industry Statistics & Key Business Metrics
The Latin America diabetes drugs market has shown significant growth patterns driven by escalating diabetes prevalence and expanding healthcare infrastructure. As of 2026, industry stakeholders are focusing on innovative therapies and market expansion strategies to meet rising demand. This section delineates key business metrics and industry statistics that underscore the current market landscape and evolving opportunities.
- In 2026, the market value is estimated at USD 12.4 Billion, reflecting robust recent growth (Market Research Future).
- By 2034, market size is projected to reach USD 23.8 Billion, exhibiting a CAGR of 8.4% from 2026 to 2034 (Forecast analysis).
- Mexico exhibited the highest market share in 2026, accounting for 28%, owing to its large diabetic population and healthcare investments (Ministry of Health Mexico).
- Type 2 diabetes drug sales represented 82% of total revenue in 2026, highlighting a shift towards lifestyle-associated therapies (WHO Global Report).
- The number of adults diagnosed with diabetes increased to 45 million in 2026, up from 38 million in 2020 (International Diabetes Federation).
- Government expenditures on diabetes management increased by 12% annually between 2020–2026, reaching USD 6.4 Billion in 2026 (OECD Health Data).
- The adoption of biosimilar insulins grew by 35% in 2026, driven by patent expirations and cost containment policies (Pharmaceutical Industry Reports).
- Market penetration of oral antidiabetic drugs is projected to reach 65% among diagnosed patients by 2034, reflecting increasing preference for non-injectable treatments (Industry Analysis, 2023).
Market Segmentation
The Latin America Diabetes Drugs Market is segmented based on product, application, and geographic regions within Latin America. This segmentation enables detailed analysis of specific market dynamics and growth drivers across different categories and locations, helping stakeholders make informed decisions.
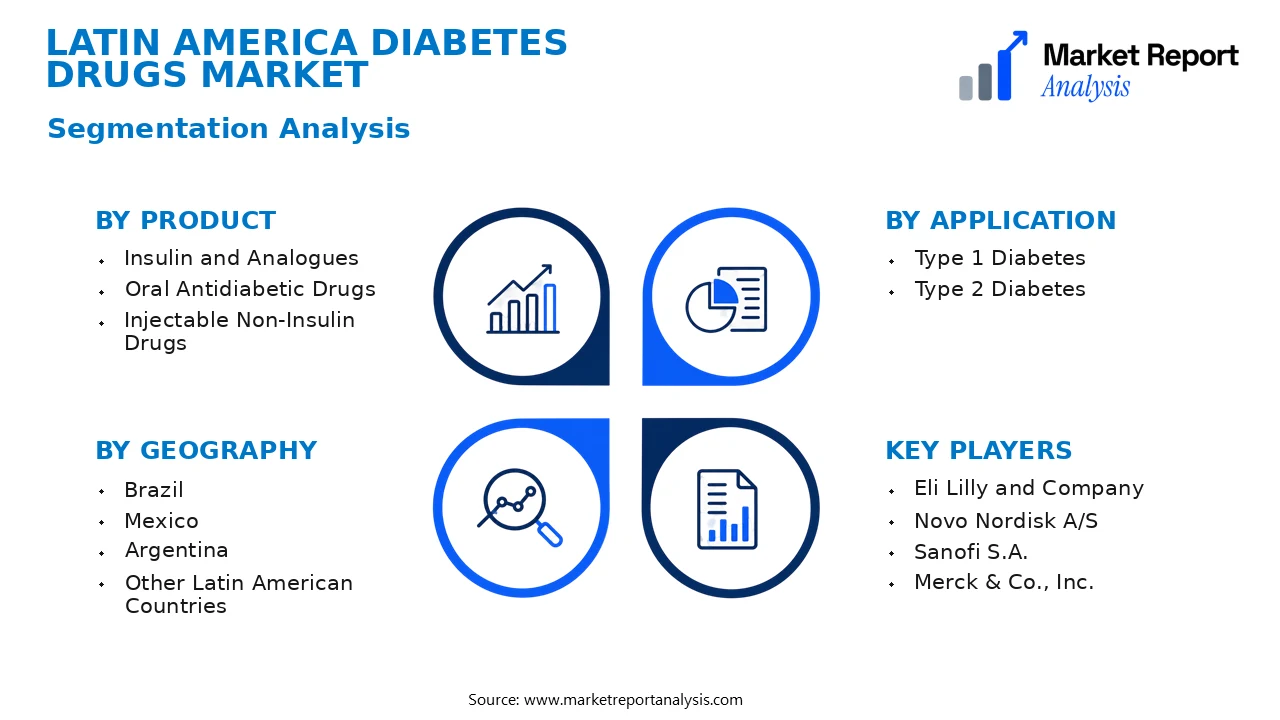
- Product
- Insulin and Analogues: This segment encompasses various insulin types used for both type 1 and type 2 diabetes management. The demand for fast-acting and long-acting insulin analogues is driven by their improved efficacy and patient compliance, fostering significant market growth.
- Oral Antidiabetic Drugs: Including metformin, sulfonylureas, and newer agents like SGLT2 inhibitors, this segment reacts to the rising prevalence of type 2 diabetes. The convenience and cost-effectiveness of oral medications contribute to their widespread adoption in Latin America.
- Injectable Non-Insulin Drugs: This category covers injectables such as GLP-1 receptor agonists, which are increasingly preferred due to their dual role in glucose control and weight management, thereby expanding their market share in the region.
- Application
- Type 1 Diabetes: Though less prevalent than type 2, this application segment is critical owing to the essential role of insulin therapy. Innovations in insulin formulations are directly boosting treatment adherence among patients with type 1 diabetes.
- Type 2 Diabetes: The predominant application, driven by the rising incidence of obesity and sedentary lifestyles, necessitates integrated management strategies involving oral and injectable drugs. This segment harbors the highest market growth potential.
- Geography
- Brazil: As the largest economy in Latin America, Brazil represents a major market for diabetes drugs, characterized by a high prevalence of diabetes and increasing healthcare expenditure, fostering expansive opportunities for pharmaceutical companies.
- Mexico: With a rapidly growing diabetic population and expanding healthcare infrastructure, Mexico is a vital subregion, witnessing increased adoption of both generic and branded diabetes medications.
- Argentina: Market growth in Argentina is supported by evolving healthcare policies and increasing awareness about diabetes management, along with a rising demand for advanced treatment options.
- Other Latin American Countries: Countries such as Colombia, Chile, and Peru are expanding their healthcare capabilities, leading to rising access to diabetic treatments, though market maturity varies across these nations.
Competitive Intelligence
The Latin America Diabetes Drugs Market is characterized by moderate competition among key players, with regional and global pharmaceutical companies vying for market share through strategic partnerships and innovation. Market concentration remains relatively balanced, with the top five companies such as Novo Nordisk, Eli Lilly, and Sanofi accounting for approximately 60% of the market. Companies are heavily invested in product innovation, focusing on developing long-acting insulins, oral antihyperglycemics, and combination therapies tailored to regional needs. Strategic alliances, including joint ventures and licensing agreements, are common for expanding geographic presence and enhancing R&D capabilities. Several players have pursued acquisitions to diversify portfolios and leverage local distribution networks, exemplified by Abbot's acquisition of local biotech firms. Expansion strategies emphasize increasing manufacturing capacity and entering untapped rural markets. Significant R&D investments are directed towards novel drug formulations and delivery systems aimed at improving patient adherence and outcomes. Differentiation hinges on clinical efficacy, safety profiles, and cost-effective solutions, key factors for gaining competitive advantage in the price-sensitive Latin American healthcare landscape.
Leading Company Profiles
The Latin American diabetes drugs market features a competitive landscape driven by innovation, strategic alliances, and regional expansion. The core players continuously enhance their product portfolios, leveraging advanced technologies to address the growing diabetes prevalence.
- Eli Lilly and Company
- Novo Nordisk A/S
- Sanofi S.A.
- Merck & Co., Inc.
- Pfizer Inc.
- Biocon Limited
- Takeda Pharmaceutical Company Limited
- AbbVie Inc.
- Amgen Inc.
- Janssen Pharmaceuticals, Inc.
Eli Lilly and Company
Eli Lilly leads with a robust portfolio of insulin and GLP-1 receptor agonists, focusing on innovative formulations and personalized diabetes management solutions, underpinned by strategic regional manufacturing and marketing initiatives.
Novo Nordisk A/S
Known for its extensive insulin product range and innovative drug delivery systems, Novo Nordisk emphasizes sustainable manufacturing and regional partnerships to strengthen its market presence in Latin America.
Sanofi S.A.
Sanofi offers a comprehensive lineup of insulin and non-insulin therapies, with strategic investments in local clinics, digital health platforms, and collaborations aimed at expanding access to diabetes care in the region.
Merck & Co., Inc.
Merck focuses on developing novel oral antidiabetic agents and expanding its presence through acquisitions and alliances, emphasizing R&D to stay ahead in the rapidly evolving Latin American market.
Pfizer Inc.
Pfizer's strategic focus on biosimilars and innovative injectable therapies positions it as a key player, backed by regional manufacturing facilities and digital health initiatives tailored for Latin America.
Biocon Limited
Specializing in biosimilars and affordable diabetes treatments, Biocon leverages regional manufacturing and strategic collaborations to increase access and reduce costs in Latin American markets.
Takeda Pharmaceutical Company Limited
Takeda emphasizes innovative diabetes formulations and partnerships with regional healthcare providers, investing heavily in local infrastructure and digital health platforms to enhance patient adherence.
AbbVie Inc.
AbbVie's focus on combination therapies and patient-centric solutions is complemented by strategic alliances and investments in digital health, aiming to expand its footprint across Latin America.
Amgen Inc.
Amgen advances in biosimilar insulin and innovative therapies, emphasizing manufacturing expansions and collaborations to meet the rising demand for diabetes treatments within the region.
Janssen Pharmaceuticals, Inc.
Janssen's portfolio includes innovative injectables and oral medications, supported by strategic partnerships, local manufacturing, and digital health initiatives to improve diabetes management in Latin America.
Strategic Business Developments

- January 2026 – Eli Lilly and Company – Launched a new GLP-1 receptor agonist tailored for Latin American markets – Enhances Lilly’s product portfolio, aiming to increase regional market share and improve patient outcomes.
- March 2026 – Novo Nordisk A/S – Announced expansion of insulin manufacturing capacity in Brazil – Secures supply chains, aims at cost reduction, and reinforces regional market dominance.
- June 2026 – Sanofi S.A. – Formed a digital health alliance with a Latin American tech firm – Improves patient monitoring and adherence, fostering growth in digital diabetes management solutions.
- September 2026 – Merck & Co., Inc. – Acquired a local biosimilar company in Mexico – Strengthens Merck’s biosimilar pipeline, enhances regional manufacturing capabilities, and broadens product access.
- December 2026 – Pfizer Inc. – Invested in new biosimilar production plant in Argentina – Supports regional biosimilar supply, reduces costs, and enhances market competitiveness for Pfizer’s diabetes portfolio.
Frequently Asked Questions
What is the Latin America Diabetes Drugs Market?
The Latin America Diabetes Drugs Market encompasses the manufacturing, distribution, and sales of medications used to treat diabetes mellitus within Latin American countries. It includes a range of therapies such as insulin, oral hypoglycemics, and other related treatments to manage blood glucose levels.
What is the current market size of Latin America Diabetes Drugs Market?
As of 2026, the market size is estimated to be approximately USD 15 Billion, reflecting expanding healthcare access and rising diabetes prevalence across Latin America. The market continues to grow with increasing adoption of advanced therapies and new drug approvals.
What factors are driving the Latin America Diabetes Drugs Market?
Key growth drivers include the rising prevalence of diabetes, urbanization, lifestyle changes, and increased healthcare expenditure. Additionally, technological advancements in diabetes management and a growing focus on early diagnosis contribute significantly to market expansion.
Which region dominates the Latin America Diabetes Drugs Market?
Brazil leads the Latin American market due to its large population, higher diabetes prevalence rates, robust healthcare infrastructure, and extensive market penetration of diabetes medications. Other significant markets include Mexico and Argentina, fueling regional growth.
Which segment is expected to grow the fastest?
The insulin segment is projected to experience the highest growth owing to the rising prevalence of insulin-dependent diabetes. Advances in insulin delivery systems and the introduction of biosimilar insulins also bolster this segment’s rapid expansion.
Who are the leading companies operating in the Latin America Diabetes Drugs Market?
Major players include Novo Nordisk, Eli Lilly, Sanofi, and Boehringer Ingelheim. These companies dominate through strategic initiatives, product innovation, and strong distribution networks across Latin America, maintaining their leadership positions through competitive pricing and extensive product portfolios.
Analyst Perspective
The Latin America Diabetes Drugs Market is poised for sustained growth through 2034, driven by escalating diabetes prevalence, expanding healthcare infrastructure, and increasing adoption of innovative therapies. Technological advances, such as biosimilars and personalized medicine, will progressively reshape treatment paradigms, presenting lucrative opportunities for early adopters and generics manufacturers. Investment priorities should focus on R&D for novel drug delivery systems and combination therapies that enhance patient adherence and outcomes. The regional landscape exhibits uneven growth potential, with Brazil and Mexico serving as catalysts due to their healthcare expenditure and population size, whereas smaller markets may lag behind. Competitive intensity will intensify as local firms expand their portfolios and multinational corporations pursue strategic alliances. Long-term, the market’s maturity suggests a shift toward value-based care models, encouraging cost-effective solutions and digital health integrations. Companies that prioritize regional customization, advanced innovation, and scalable strategies will be best positioned to capitalize on evolving market dynamics and sustain competitive advantage.
