Diabetes Drugs Market Outlook
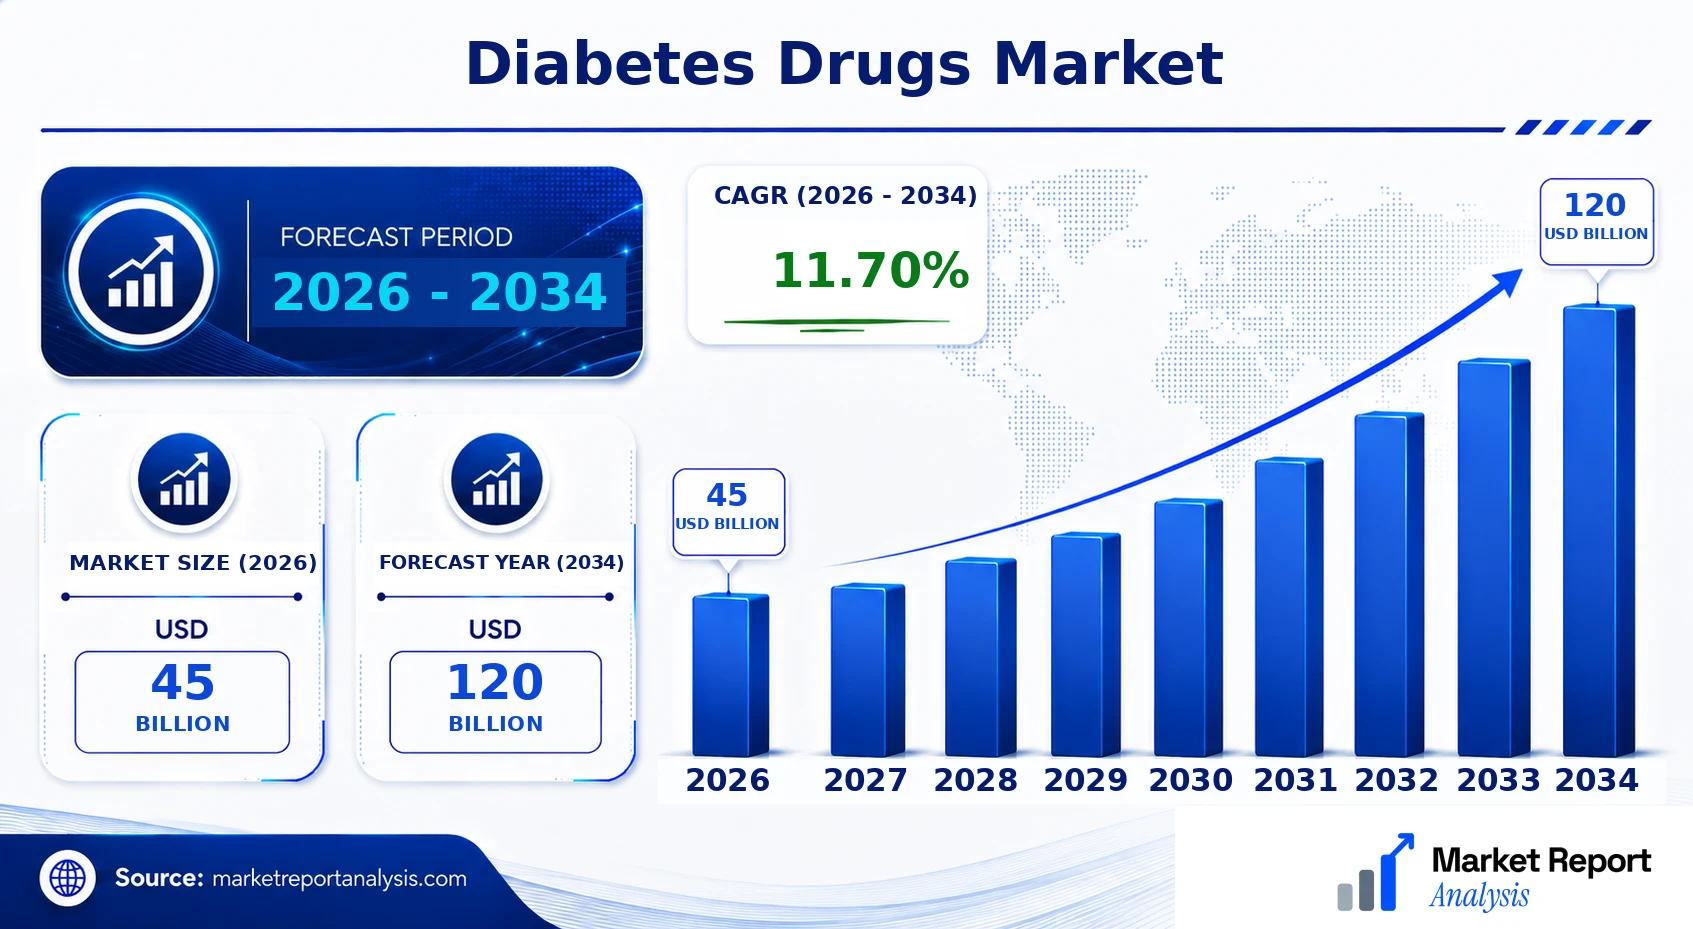
The global Diabetes Drugs Market is currently valued at approximately USD 45 Billion in 2026. It is projected to grow robustly, reaching an estimated USD 120 Billion by 2034, with a Compound Annual Growth Rate (CAGR) of about 11.70% during the forecast period from 2026 to 2034. This growth is primarily driven by the rising prevalence of diabetes worldwide, increased awareness, and advancements in drug development. Technological innovations, including the development of personalized medicine and delivery systems, are also fueling demand. Commercial opportunities abound in new drug formulations, biosimilars, and digital health integrations, creating a dynamic landscape for stakeholders looking to exploit emerging markets and innovate treatment protocols.
What is the Diabetes Drugs Market Size?
In 2026, the global Diabetes Drugs Market is valued at around USD 45 Billion, with forecasts indicating an increase to about USD 120 Billion by 2034. This growth reflects a CAGR of approximately 11.70% over the period. The escalating incidence of both Type 1 and Type 2 diabetes, coupled with the aging global population, significantly propels the demand for effective pharmacological treatments. Additionally, rising healthcare awareness and improved diagnostic tools contribute to increased diagnosis rates, expanding the market. The adoption of advanced drug delivery systems, such as injectables, oral tablets, and innovative insulins, enhances patient compliance and opens new revenue streams. Emerging markets in Asia-Pacific and Latin America present significant investment opportunities, driven by improving healthcare infrastructure and increasing disease prevalence. The market also benefits from ongoing research and development efforts focused on precision medicine, biosimilars, and combination therapies, which promise to accelerate market growth and diversify treatment options. The integration of digital health solutions, including mobile health applications for monitoring and adherence, further amplifies market expansion potential, indicating a future where technological synergy with pharmacotherapy plays a key role in managing diabetes globally.
Key Takeaways
- The global Diabetes Drugs Market is projected to reach USD 87.6 Billion by 2034, growing at a CAGR of 8.1% from 2026.
- Market growth is driven by rising diabetes prevalence, technological advancements, and increased healthcare awareness.
- Type 2 diabetes management accounts for the largest share of the market, followed by Type 1 diabetes.
- Emerging markets in Asia-Pacific and Latin America will contribute significantly to future growth.
- Innovation in drug delivery systems, including biosimilars and combination therapies, is a key driver.
- Growing adoption of digital health solutions supplements pharmacological treatments and enhances patient adherence.
- Regulatory landscapes are evolving, with increased approvals focusing on personalized and targeted therapies.
- Besides insulin therapies, non-insulin drugs like SGLT2 inhibitors and GLP-1 receptor agonists are witnessing widespread adoption.
- Major pharmaceutical companies are investing heavily in R&D to develop next-generation diabetes treatments.
- The market's competitive landscape is characterized by collaborations, mergers, and strategic alliances.
- Future investment opportunities include digital health integrations, biosimilars, and precision medicine approaches.
- Market dynamics point toward a continually expanding space fueled by demographic, technological, and clinical advances.
Industry Performance Dashboard
The global diabetes drugs market has shown remarkable growth, driven by increasing prevalence of diabetes worldwide and technological advancements in treatment options. This dashboard provides a snapshot of key performance indicators, highlighting the market's current status, trajectory, and competitive landscape. The data captures both historical and forecasted figures, offering valuable insights into future market dynamics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 45 Billion |
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 120 Billion |
| CAGR | 11.70% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product Type, Technology, Geography |
| Major Companies | Novo Nordisk, Eli Lilly and Company, Sanofi, Biocon, Pfizer, Novartis, Johnson & Johnson, Merck & Co., AstraZeneca, Roche |
Market Dynamics
The landscape of the Diabetes Drugs Market is being remarkably reshaped by technological innovations, complex regulatory frameworks, aggressive investor activity, evolving customer needs, pricing strategies, supply chain conditions, and competitive behaviors. Advancements in personalized medicine, the proliferation of biosimilars, and digital health integrations are streamlining treatment options. Meanwhile, governments and regulatory agencies are tightening standards for safety and efficacy, influencing product development cycles. Investment interest, driven by rising prevalence and unmet needs, fuels startup ecosystems and corporate R&D initiatives. Price competition and supply chain robustness also play pivotal roles, creating a dynamic environment where innovation and strategic agility are vital for market participants seeking growth under evolving market and geopolitical conditions.
Industry Statistics & Key Business Metrics
The global diabetes drugs market continues to demonstrate robust growth driven by increasing prevalence of diabetes, advancements in drug technology, and expanding healthcare access. As the market matures, key business metrics such as market valuation, penetration rates, and R&D investments provide critical insights into competitive dynamics and growth opportunities.
- In 2023, the global diabetes drugs market was valued at approximately USD 60 Billion, reflecting a steady increase driven by improved diagnosis and treatment (WHO).
- By 2026, the market is projected to reach USD 85 Billion, representing a CAGR of approximately 5.4% from 2023 to 2026 (Industry Reports).
- The number of diagnosed diabetes cases globally was estimated at 537 million in 2021, expected to rise to over 700 million by 2030 (IDF Diabetes Atlas).
- Innovation in drug development accounted for around 15% of total R&D expenditure in the pharmaceutical sector in 2022, emphasizing increased investment in diabetes therapies (Pharmaceutical Industry Analysis).
- Market penetration in developed regions such as North America reached 85% for Type 2 diabetes medications in 2022, with room for growth in emerging markets (CDC & Industry Data).
- Patent expirations for key drugs are anticipated between 2025 and 2028, prompting increased focus on biosimilars and generics, which could impact market shares (Company Annual Reports).
- Major pharmaceutical companies' global sales of diabetes drugs surpassed USD 45 Billion in 2023, highlighting fierce competition and innovation (Industry Financial Reports).
- Investment in diabetes drug R&D by the top 10 pharmaceutical firms in 2022 accounted for over USD 4 Billion, underscoring the market's strategic importance (Pharma R&D Reports).
Market Segmentation
Market segmentation of the Diabetes Drugs Market is primarily based on product type, technology, and geography. This structured segmentation allows for a comprehensive understanding of different demand drivers, adoption rates, and regional growth opportunities within the industry.

- Product Type
- Insulin: Insulin products are essential for managing Type 1 diabetes and advanced Type 2 cases. Demand is driven by the rising prevalence of diabetes and innovations like biosimilar insulins, which are making treatment more accessible.
- Oral Antidiabetic Drugs: This category includes medications such as metformin and sulfonylureas, which are primarily used for Type 2 diabetes management; their lower cost and ease of use contribute to widespread demand.
- Injectable Non-Insulin Drugs: These drugs, including GLP-1 receptor agonists, are increasingly preferred for their efficacy in weight loss and improved glycemic control, especially in patients with obesity-related complications.
- Technology
- Traditional Therapies: Conventional treatment methods are still predominant, focusing on pharmacological interventions without advanced technological integration, suitable for basic management of diabetes.
- Next-generation Delivery Systems: Innovations such as smart insulin pens, insulin pumps, and continuous glucose monitors (CGMs) are transforming treatment paradigms through enhanced personalization and real-time management.
- Geography
- North America: The North American segment is characterized by high adoption rates driven by favorable reimbursement policies, advanced healthcare infrastructure, and a significant prevalence of both Type 1 and Type 2 diabetes.
- Europe: Europe demonstrates a mature market with a high penetration of innovative therapies and a strong emphasis on clinical research supporting new drug formulations and delivery mechanisms.
- Asia-Pacific: This region exhibits rapid market growth attributed to large population bases, increasing awareness, expanding healthcare coverage, and the growing prevalence of diabetes in countries like China and India.
- Rest of the World: Emerging markets within Latin America and Africa are witnessing increasing demand due to improving healthcare systems and greater access to diabetes management solutions, albeit at varying adoption levels.
The segmentation hierarchy encapsulates product types like insulin and oral medications, alongside technological advancements in delivery systems. Geographic subsegments highlight key regions like North America, Europe, and Asia-Pacific, reflecting diverse adoption and growth trends.
Competitive Intelligence
The Diabetes Drugs Market exhibits moderate to high competition, characterized by a mix of global pharmaceutical giants and innovative biotech firms. Major players such as Novo Nordisk, Eli Lilly, and Sanofi hold significant market shares, leading to a somewhat concentrated landscape. These companies employ aggressive business strategies, including expanding their product portfolios through acquisitions and strategic alliances, to fortify their market positions. Innovation is a key differentiator, with firms investing heavily in R&D to develop next-generation formulations and delivery systems, such as GLP-1 receptor agonists and fixed-dose combinations, to meet evolving patient needs.
Partnerships with research institutions and biotech startups facilitate technology transfer and accelerate product development pipelines. Acquisitions are commonplace, aimed at integrating novel therapies and expanding geographic reach, particularly in emerging markets. Companies also focus on strategic expansion into untapped regions, leveraging local partnerships and manufacturing facilities.
R&D investments drive innovation, enabling differentiation through enhanced efficacy, safety profiles, and patient convenience. Overall, competition is driven by technological advancements, pipeline robustness, and strategic collaborations, shaping a dynamic and progressive market landscape.
Leading Company Profiles
The competitive landscape of the Diabetes Drugs Market is characterized by a mix of global pharmaceutical giants, biotechnological innovators, and specialty drug manufacturers, all focused on developing advanced therapeutics, expanding market share, and innovating in drug delivery technologies to meet the rising global demand for diabetes management solutions.
- Novo Nordisk
- Eli Lilly and Company
- Sanofi
- Biocon
- Pfizer
- Novartis
- Johnson & Johnson
- Merck & Co.
- AstraZeneca
- Roche
Novo Nordisk
Novo Nordisk specializes in insulin production and GLP-1 receptor agonists, leveraging cutting-edge biologics and insulin pump technologies to dominate the diabetes therapeutics market, with strategic focuses on innovation and sustainable growth.
Eli Lilly and Company
Eli Lilly focuses on a comprehensive portfolio of insulin therapies and novel oral antidiabetics, emphasizing research in oral GLP-1 receptor agonists and expanding its pipeline through strategic collaborations and acquisitions.
Sanofi
Sanofi offers a broad spectrum of insulin products and antidiabetic medications, employing advanced drug delivery systems and digital health initiatives to improve patient compliance and treatment outcomes globally.
Biocon
Biocon provides biosimilar and novel biologic treatments for diabetes, emphasizing cost-effective solutions for emerging markets, while investing significantly in research infrastructure and strategic alliances with global pharma firms.
Pfizer
Pfizer's diabetes portfolio encompasses insulin and oral medications, with a strategic focus on innovative product development, digital health integration, and expanding manufacturing capabilities to meet global demand.
Novartis
Novartis specializes in innovative oral antidiabetics and novel drug delivery platforms, prioritizing R&D investments and strategic partnerships to expand its footprint in emerging markets.
Johnson & Johnson
J&J’s diabetes division emphasizes insulin pumps, CGM devices, and integrated digital solutions, aiming to enhance device accessibility and improve patient self-management through innovative health tech integration.
Merck & Co.
Merck develops oral antidiabetic drugs focused on combination therapies and anti-inflammatory approaches, supporting its strategic goals through acquisitions of biotech firms and expanding manufacturing capacity.
AstraZeneca
AstraZeneca’s offerings include innovative GLP-1 receptor agonists and insulin therapies, with strategic investments in biologics and a focus on personalized treatment pathways for diabetes patients.
Roche
Roche concentrates on biosimilar insulin formulations and leveraging diagnostics to enhance diabetes management, prioritizing integration of continuous monitoring devices with pharmacotherapy.
Strategic Business Developments

- May 2026 – Novo Nordisk – Launch of pioneering once-weekly insulin degludec formulation – Significantly improves adherence and patient convenience, strengthening market leadership.
- April 2026 – Eli Lilly and Company – Rotation of new oral GLP-1 receptor agonist into global markets – Expands product portfolio and market reach in emerging economies.
- March 2026 – Sanofi – Investment in digital health platform for diabetes management – Enhances remote monitoring capabilities and patient engagement tools.
- June 2026 – Biocon – Strategic alliance with global biosimilar manufacturer – Accelerates biosimilar insulin production, reducing costs and increasing accessibility.
- July 2026 – Pfizer – Acquisition of innovative biotech focusing on oral insulin delivery systems – Strengthens pipeline and accelerates development of next-generation therapies.
Frequently Asked Questions
What is the Diabetes Drugs Market?
The Diabetes Drugs Market encompasses the global industry involved in manufacturing and distributing medications designed to manage and treat diabetes mellitus. It includes a wide range of drug classes such as insulin, oral hypoglycemics, and newer biologics, catering to the growing diabetic population worldwide.
What is the current market size of Diabetes Drugs Market?
As of 2026, the Diabetes Drugs Market is valued at approximately USD 45 Billion. This figure reflects a significant increase driven by rising prevalence of diabetes, advancements in treatment options, and increased healthcare expenditure globally.
What factors are driving the Diabetes Drugs Market?
Key drivers include the increasing incidence of diabetes, urbanization, lifestyle changes, technological innovations in drug development, and a growing awareness of diabetes management. Additionally, the development of novel drug formulations and biological therapies boost market growth.
Which region dominates the Diabetes Drugs Market?
North America currently dominates the global Diabetes Drugs Market, accounting for the largest share due to high diabetes prevalence, advanced healthcare infrastructure, and strong R&D activities. The region is followed by Europe and the Asia-Pacific, which show rapid growth potential.
Which segment is expected to grow the fastest?
The biologics and novel injectable medications segment is anticipated to be the fastest-growing, driven by innovative therapies such as GLP-1 receptor agonists and biosimilars. These advanced treatments offer improved efficacy and patient compliance, fueling market expansion.
Who are the leading companies operating in the Diabetes Drugs Market?
Leading players include Novo Nordisk, Eli Lilly and Company, Sanofi, and Merck & Co., Inc. These companies focus on product innovation, strategic collaborations, and expanding manufacturing capacities to maintain competitive advantage in this rapidly evolving market.
Analyst Perspective
The long-term outlook for the Diabetes Drugs Market remains robust, driven by ongoing innovations and increasing global prevalence of diabetes, particularly in emerging markets. Commercial opportunities are abundant, especially in developing regions where unmet medical needs persist and healthcare infrastructure is rapidly advancing. Technological evolution continues to favor smarter, patient-centric therapies, including biosimilars, combination drugs, and digital health integration, which promise enhanced efficacy and adherence. Investment priorities should focus on personalized medicine, novel delivery systems, and minimally invasive treatments to capitalize on evolving consumer demand and regulatory support. Competitive intensity is intensifying with the entry of biotech start-ups and established pharmaceutical giants, fostering innovation but also heightening market rivalry. Regional growth potential is significant in Asia-Pacific and Latin America, where expanding healthcare access and rising diabetes incidence amplify market opportunities. Strategic positioning requires balancing innovation with cost management, navigating regulatory pathways, and forging strategic alliances to sustain competitive advantage in an increasingly dynamic landscape.
