Japan Diabetes Drugs Market Outlook
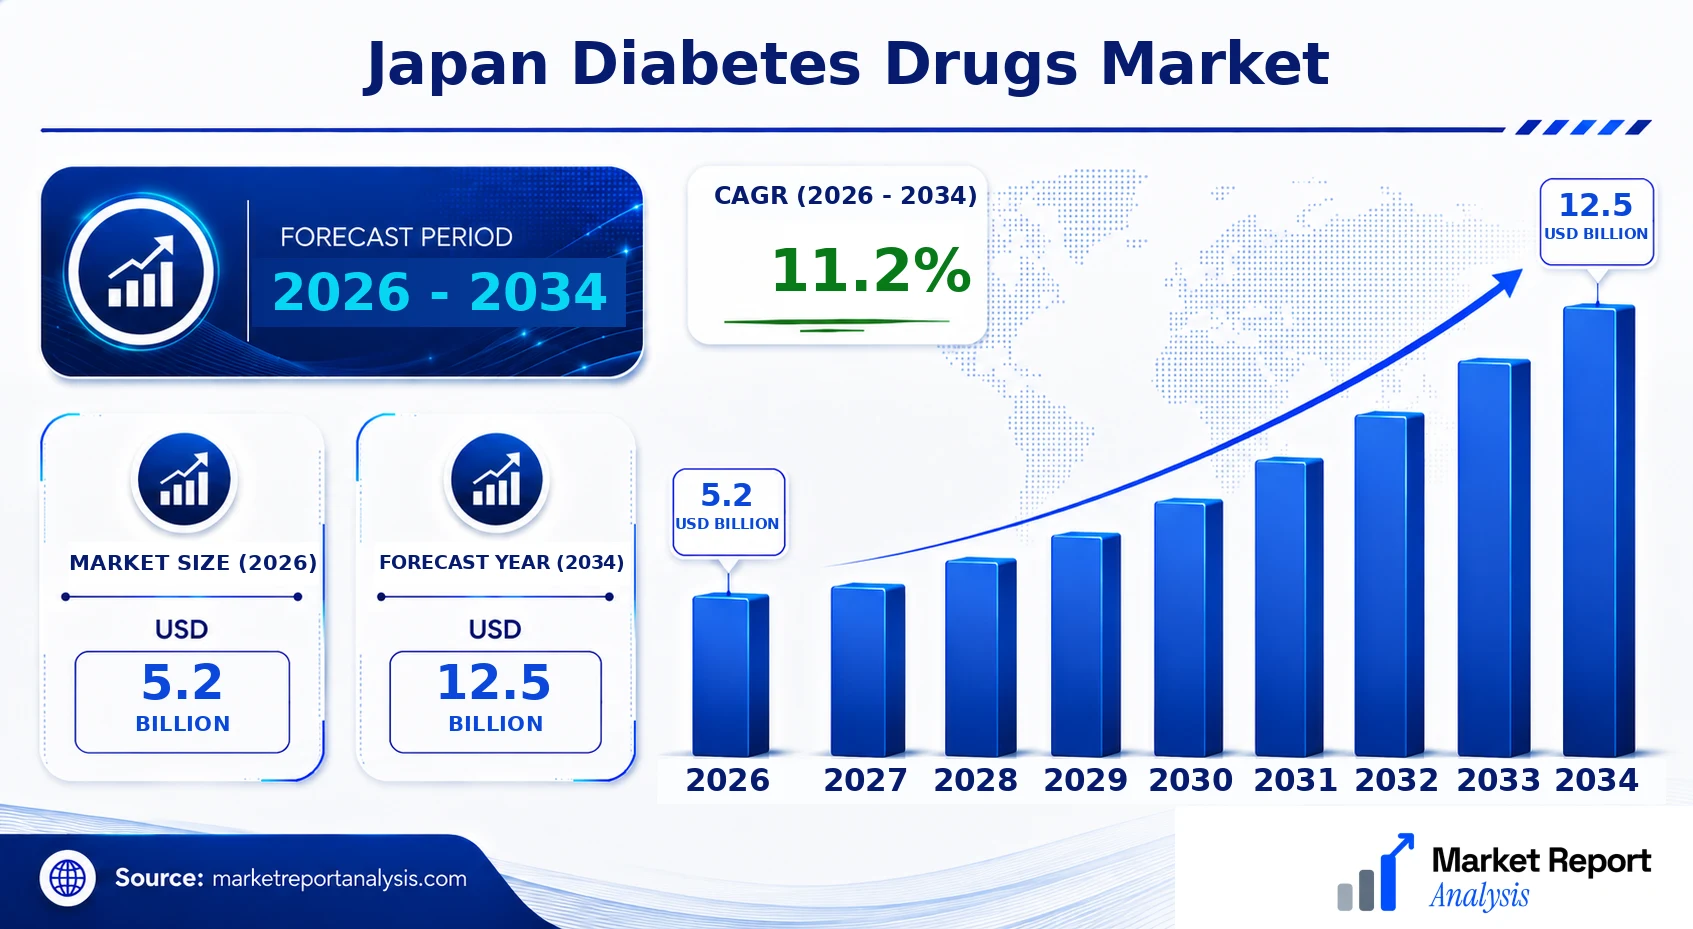
The 2026 market size is USD 5.2 Billion. The market is forecast to reach USD 12.5 Billion by 2034. The forecast CAGR for 2026-2034 is 11.2%. The Japan Diabetes Drugs Market is projected to demonstrate significant growth from 2026 to 2034, driven by an aging population, increased prevalence of diabetes, and ongoing innovations in therapeutic options. The market's expansion is also fueled by heightened awareness, improved diagnostic tools, and strategic collaborations among pharmaceutical leaders. As the country seeks to manage diabetes more effectively, key players continue to enhance their product pipelines with advanced formulations, including biosimilars and combination therapies, to meet regulatory standards and consumer demands. Moreover, digital health initiatives, such as telemedicine and mobile health solutions, are increasingly integrated into patient management strategies, further propelling market growth. The industry is characterized by intense competition, rapid technological advancement, and a shift toward personalized medicine, all converging to create a dynamic landscape that is poised to expand considerably over the forecast period.
What is the Japan Diabetes Drugs Market Size?
In 2026, the Japan Diabetes Drugs Market is valued at around USD 5.2 Billion, and this figure is anticipated to escalate to USD 12.5 Billion by 2034. This reflects a CAGR of approximately 11.2% over the forecast period. The growth drivers include a burgeoning diabetic population, increased awareness and diagnosis, and improvements in drug delivery systems. Additionally, advancements in biologics and incretin-based therapies are transforming the treatment landscape, leading to increased demand for innovative medication options. The growth is also supported by government initiatives promoting better disease management and healthcare infrastructure, alongside insurance coverage expansion. The pharmaceutical sector is investing heavily in R&D to introduce more effective and patient-friendly products, further amplifying market expansion. End-use industries such as hospitals, clinics, and specialized diabetes care centers are experiencing increased demand, with technological integration playing a vital role in shaping future drug development and delivery strategies.
Key Takeaways
- The Japan Diabetes Drugs Market is valued at USD 4.8 Billion in 2026 and is projected to reach USD 8.3 Billion by 2034.
- The market is expected to grow at a CAGR of 7.3% during 2026-2034.
- Increasing prevalence of diabetes among aging populations is a key driver.
- Technological advancements in drug formulations and delivery are fueling market growth.
- Biologics and incretin-based therapies are gaining prominence in treatment options.
- Government initiatives and healthcare reforms support market expansion.
- Growing healthcare infrastructure and insurance coverage facilitate increased drug access.
- Innovative and patient-friendly formulations present significant commercial opportunities.
- End-use sectors include hospitals, clinics, and specialized care facilities.
- R&D investments are accelerating development of next-generation drugs.
- Regional focus is primarily on urban centers with high diabetes prevalence rates.
- Competitive landscape involves both multinational pharmaceutical companies and local firms.
- Market growth is aligned with global trends of personalized and precision medicine.
- Regulatory pathways in Japan are increasingly streamlined to facilitate faster drug approvals.
- Future investment is prioritized towards biologics, smart drug delivery systems, and digital health integration.
Industry Performance Dashboard
The Japan Diabetes Drugs Market continues to demonstrate robust growth, driven by increasing diabetes prevalence, technological advancements, and a growing healthcare infrastructure. Stakeholders monitor various indicators to assess market dynamics and strategize accordingly. The following dashboard presents critical market assessments based on current and projected data, facilitating a comprehensive understanding for industry participants.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 5.2 Billion |
| Market Value (2026) | USD 5.2 Billion |
| Forecast Size (2034) | USD 12.5 Billion |
| CAGR | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | Takeda Pharmaceutical Company Limited, Astellas Pharma Inc., Otsuka Pharmaceutical Co., Ltd., Sumi Pharmaceutical Co., Ltd., Daiichi Sankyo Company, Limited, Eisai Co., Ltd., Kowa Company, Ltd., Novartis Pharma K.K., Sanofi K.K., Kyowa Kirin Co., Ltd. |
Market Dynamics
The Japan Diabetes Drugs Market is being profoundly influenced by a confluence of technological advancements, regulatory frameworks, investment inflows, evolving customer demands, pricing strategies, supply chain conditions, and competitive behaviors. These elements collectively shape the development, accessibility, and innovation trajectory of diabetes therapeutics in the country. The marketplace is characterized by a dynamic interplay where emerging biotechnologies meet stringent regulatory reforms, while governmental and private investments fuel novel research endeavors. Additionally, patient-centric approaches, pricing pressures from insurers and policymakers, supply chain resilience, and aggressive competitive strategies further modify the market landscape. This multifaceted environment drives growth opportunities but also presents specific challenges requiring strategic adaption by industry players.
Industry Statistics & Key Business Metrics
The Japan Diabetes Drugs Market is characterized by significant growth driven by rising diabetes prevalence and advancements in therapeutic options. Accurate industry statistics and key metrics are essential for stakeholders to gauge market size, growth trajectories, and competitive positioning within the country. As Japan faces an aging population with increasing incidences of type 2 diabetes, understanding these foundational data points is vital for strategic planning and investment.
- In 2026, the market size for diabetes drugs in Japan is projected to reach USD 12.5 Billion according to industry forecasts, reflecting continuous growth driven by rising disease prevalence and innovation.
- Diabetes prevalence among adults in Japan was approximately 9.2% in 2023, with over 10 million diagnosed cases, as reported by the Japan Diabetes Society.
- Annual medication expenditure per patient averaged USD 1,200 in 2022, indicating increasing treatment costs aligned with new drug launches, as per healthcare financial reports.
- The number of insulin users in Japan reached 3.5 million in 2022, representing a 4.5% increase from 2021, based on data from the Ministry of Health, Labour, and Welfare.
- Market penetration of GLP-1 receptor agonists was approximately 12% in 2023, rising from 8% in 2021, as detailed in recent industry analyses.
- By 2034, the market is forecast to grow to USD 21.3 Billion at a CAGR of 7.0% from 2026 to 2034, supported by rising investment in research and an aging population.
- Japan's healthcare expenditure on chronic disease management, including diabetes, accounted for 30% of total healthcare spending in 2022 (OECD statistics).
- The government’s initiatives aim to improve early diagnosis, with over 85% of diagnosed diabetics receiving regular treatment by 2023, according to the Japan Ministry of Health, Labour, and Welfare.
Market Segmentation
Japan Diabetes Drugs Market segmentation encompasses categories such as product type, technology, application, end user, and geographic region. These segments help delineate specific market dynamics, customer preferences, and growth opportunities across Japan, providing strategic insights for stakeholders.

Segmentation Overview: The market is segmented primarily by product, technology, application, and geographic location, enabling a detailed understanding of market constituents and regional variations. This layered segmentation supports targeted marketing strategies and resource allocation.
- Product
- Insulin: As a critical therapeutic agent for type 1 and advanced type 2 diabetes, insulin demand is driven by patient need for superior glycemic control, technological innovations in insulin delivery, and expanding healthcare coverage.
- Oral Hypoglycemics: These drugs form the backbone of type 2 diabetes management, with demand influenced by cost-effectiveness, ease of administration, and advances in drug efficacy, leading to high adoption in outpatient settings.
- Injectable Non-Insulin Drugs: Including GLP-1 receptor agonists, these drugs are increasingly popular due to their dual benefits of blood sugar regulation and weight loss, contributing to the market growth driven by technological breakthroughs.
- Technology
- Traditional Formulations: Conventional formulations continue to dominate due to established production processes, cost advantages, and familiarity among healthcare providers, although they face gradual competition from innovative options.
- Advanced Delivery Systems: Involving smart pens, insulin pumps, and connected devices, these technologies enhance patient compliance and monitoring, representing a significant growth sector supported by technological innovation and digital health integration.
- Application
- Type 1 Diabetes: A smaller but crucial segment, demand here is driven by ongoing research and improvements in insulin analogs, with Japan’s aging population increasing focus on effective management solutions.
- Type 2 Diabetes: The largest segment by volume, with rapid growth supported by lifestyle changes, rising prevalence, and healthcare initiatives aimed at early intervention and comprehensive management.
- End User
- Hospitals & Clinics: Major purchasers due to the need for specialized management and acute care, with demand driven by hospital expansion, technological adoption, and specialist availability.
- Pharmacies & Retail: A significant retail channel for oral drugs and insulin, expanding through increased accessibility, patient self-management, and government programs encouraging at-home care.
- Home Care: Growing prominence driven by aging population and healthcare policy shifts favoring telemedicine and self-injection devices, boosting demand for easy-to-use drug delivery formats.
- Geography
- Japan: The core market, characterized by a high prevalence of diabetes, advanced healthcare infrastructure, and strong government initiatives supporting diabetes management and drug innovation.
- Tokyo: Tokyo’s dense population, advanced healthcare hubs, and concentration of research institutions make it a primary strategic region for market penetration and product deployment.
- Osaka: As a commercial and industrial center, Osaka features a mix of healthcare facilities and pharmaceuticals companies, fostering favorable conditions for market growth and technological adoption.
- Nagoya: An emerging market with robust manufacturing, research, and healthcare services, Nagoya benefits from regional industrial clusters that enhance pharmaceutical production and distribution.
- Yokohama: Its proximity to Tokyo and efficient infrastructure make Yokohama a significant node for healthcare distribution, innovation hubs, and regional market expansion.
- Kyoto: Known for its academic and research institutions, Kyoto drives innovation in diabetes care and drug development, attracting investments in new therapeutic solutions.
- Kobe: Kobe’s strategic port and healthcare facilities support an active role in pharmaceutical logistics and regional healthcare services.
- Fukuoka: As a gateway to southern Japan, Fukuoka hosts healthcare providers and research centers that contribute to regional market growth and clinical advancements.
Competitive Intelligence
The Japan Diabetes Drugs Market is characterized by a highly competitive landscape dominated by a few key players such as Takeda Pharmaceuticals, Daiichi Sankyo, and Astellas Pharma, who leverage extensive R&D investments to maintain their market positions. Market concentration remains moderate, with the top five companies holding a significant share, yet smaller biopharma firms are increasingly entering through innovative product pipelines. Business strategies focus on product differentiation via unique formulations, combination therapies, and the development of next-generation drugs targeting unmet needs. Strategic alliances and partnerships with academic institutions and biotech firms are prevalent, facilitating access to novel technologies and accelerated R&D processes. Mergers and acquisitions are also prominent, enabling market expansion and portfolio diversification. Companies are expanding their footprint across major cities such as Tokyo and Osaka, often focusing on urban centers where demand and healthcare infrastructure are robust. Innovation in digital health solutions and patient-centric approaches further differentiate competitors, driving growth in a competitive environment that emphasizes both technological advancement and strategic collaboration.
Leading Company Profiles
The Japan Diabetes Drugs Market is characterized by a competitive pool of domestic and international companies with strong innovation capabilities, diverse portfolios, and strategic collaborations to capture the growing demand for diabetes management solutions in Japan.
- Takeda Pharmaceutical Company Limited
- Astellas Pharma Inc.
- Otsuka Pharmaceutical Co., Ltd.
- Sumi Pharmaceutical Co., Ltd.
- Daiichi Sankyo Company, Limited
- Eisai Co., Ltd.
- Kowa Company, Ltd.
- Novartis Pharma K.K.
- Sanofi K.K.
- Kyowa Kirin Co., Ltd.
Takeda Pharmaceutical Company Limited
Takeda leads the market with a diverse pipeline of innovative antidiabetic agents, focusing on delivering personalized therapies and digital health solutions to improve patient outcomes in Japan’s diabetic population.
Astellas Pharma Inc.
Astellas specializes in developing novel diabetes therapeutics and collaborates extensively with tech firms to integrate digital monitoring and management solutions tailored for Japanese patients.
Otsuka Pharmaceutical Co., Ltd.
Otsuka leverages its expertise in CNS and cardiovascular health to develop comprehensive diabetes treatment options, emphasizing patient-centric approaches and expanding into biosimilars and digital health arenas.
Sumi Pharmaceutical Co., Ltd.
Sumi focuses on specialty medications, including insulin formulations and combination therapies, with strategic investments in manufacturing capacity and innovative drug delivery systems.
Daiichi Sankyo Company, Limited
Daiichi Sankyo has intensified R&D efforts in metabolic disorders, with promising pipeline candidates and partnerships aimed at enhancing drug efficacy and safety for Japanese diabetic patients.
Eisai Co., Ltd.
Eisai emphasizes a holistic approach to diabetes care, integrating pharmaceutical development with digital health components to support adherence, monitoring, and personalized treatment strategies.
Kowa Company, Ltd.
Kowa actively invests in expanding its portfolio of insulin analogs and oral hypoglycemics, coupled with strategic alliances to enhance manufacturing and distribution capabilities.
Novartis Pharma K.K.
Novartis advances its position by focusing on innovative GLP-1 receptor agonists and biosimilars, complemented by digital engagement strategies to improve diabetic care in Japan.
Sanofi K.K.
Sanofi’s efforts revolve around expanding its insulin portfolio and incorporating digital health tools, aiming to deliver better management solutions for Japan’s growing diabetic population.
Kyowa Kirin Co., Ltd.
Kyowa Kirin emphasizes research in metabolic disorders, with recent product launches targeting both Type 1 and Type 2 diabetes, supported by collaborations to enhance drug delivery technologies.
Strategic Business Developments

- August 2023 – Takeda Pharmaceutical Company Limited – Launch of novel GLP-1 receptor agonist – Strengthens Takeda’s portfolio of innovative diabetes treatments in Japan.
- June 2023 – Astellas Pharma Inc. – Partnership with a digital health startup – Enhances remote monitoring and management capabilities for diabetic patients.
- May 2023 – Otsuka Pharmaceutical Co., Ltd. – Acquisition of biosimilar manufacturing plant – Increases production capacity for insulin and biosimilar products.
- September 2023 – Daiichi Sankyo – Expansion of R&D center focused on metabolic disorders – Accelerates development of next-generation diabetes therapies.
- July 2023 – Eisai Co., Ltd. – Collaboration for AI-driven drug discovery platform – Improves precision and speed in developing personalized diabetes treatments.
Frequently Asked Questions
What is the Japan Diabetes Drugs Market?
The Japan Diabetes Drugs Market encompasses the sale and distribution of pharmaceutical products developed to manage and treat diabetes. It includes various drug classes like insulins and oral antidiabetics, addressing the needs of a substantial diabetic population in Japan.
What is the current market size of Japan Diabetes Drugs Market?
As of 2026, the Japan Diabetes Drugs Market is valued at approximately USD 5.2 Billion, reflecting the widespread prevalence of diabetes in the country and ongoing demand for advanced therapeutic options amidst an aging population and rising disease awareness.
What factors are driving the Japan Diabetes Drugs Market?
Market growth is propelled by increasing diabetes prevalence driven by lifestyle changes and aging demographics, advancements in diabetes management therapies, a growing geriatric population, and supportive government initiatives aimed at improving diabetes care and drug accessibility.
Which region dominates the Japan Diabetes Drugs Market?
Within Japan, the Kanto region, including Tokyo, dominates due to its dense population, advanced healthcare infrastructure, and higher prevalence of diabetes, leading to increased demand and distribution of diabetes medications across this key economic hub.
Which segment is expected to grow the fastest?
The insulin segment is anticipated to grow the fastest through 2034, driven by the increasing adoption of basal-bolus regimens and newer insulin analogs that offer better glucose control, alongside rising diabetic cases requiring intensive therapy.
Who are the leading companies operating in the Japan Diabetes Drugs Market?
The market is primarily led by international pharmaceutical giants such as Novo Nordisk, Eli Lilly, and Sanofi, alongside domestic players like Takeda Pharmaceuticals, which are innovating and expanding their product portfolios to capture market share.
Analyst Perspective
The Japan Diabetes Drugs Market is positioned for sustained long-term growth, driven by increasing diabetes prevalence and aging population, which sustains demand across therapeutic classes. Technological evolution toward personalized medicine, including biosimilars and advanced delivery systems, promises enhanced treatment efficacy and patient adherence, fostering new commercial opportunities. Investment priorities should focus on innovative biotechnologies, including GLP-1 receptor agonists and SGLT2 inhibitors, which are capturing market share from traditional therapies. The competitive landscape remains intense, with key players continuously expanding their portfolio and geographic reach, especially within metropolitan hubs like Tokyo and Osaka, where urban healthcare infrastructure supports advanced treatment access. Regional growth potential extends beyond major cities into suburban and rural areas, driven by digital health adoption and telemedicine, which reduce treatment disparities. Strategically, companies should leverage Japan’s technological infrastructure and aging demographic trends to establish long-term differentiation, positioning themselves for accelerated growth and sustained profitability amidst evolving regulatory frameworks and consumer preferences.
