Japan Generator In Datacentre Market Outlook
The forecast CAGR for 2026-2034 is 10.1%. The Japan generator market for datacentres is experiencing a significant uptrend, driven by increasing data traffic, rapid digital transformation, and robust infrastructure investments. As of 2026, the market value stands at USD 1.5 Billion, with forecasts projecting substantial growth to reach USD 4.5 Billion by 2034. This growth is propelled by expanding datacenter capacity to support cloud services, AI, and big data analytics, combined with the government's focus on digital innovation. The industry is predominantly shifting towards cleaner, more efficient generator technologies such as natural gas and hybrid systems, emphasizing sustainability and operational resilience. Commercial opportunities in Japan are abundant, especially in providing customized, scalable, and eco-friendly power solutions that align with stringent environmental regulations and energy policies. Opportunities also abound in maintenance, remote monitoring, and integrated energy management systems, making this a lucrative market for diverse stakeholders.
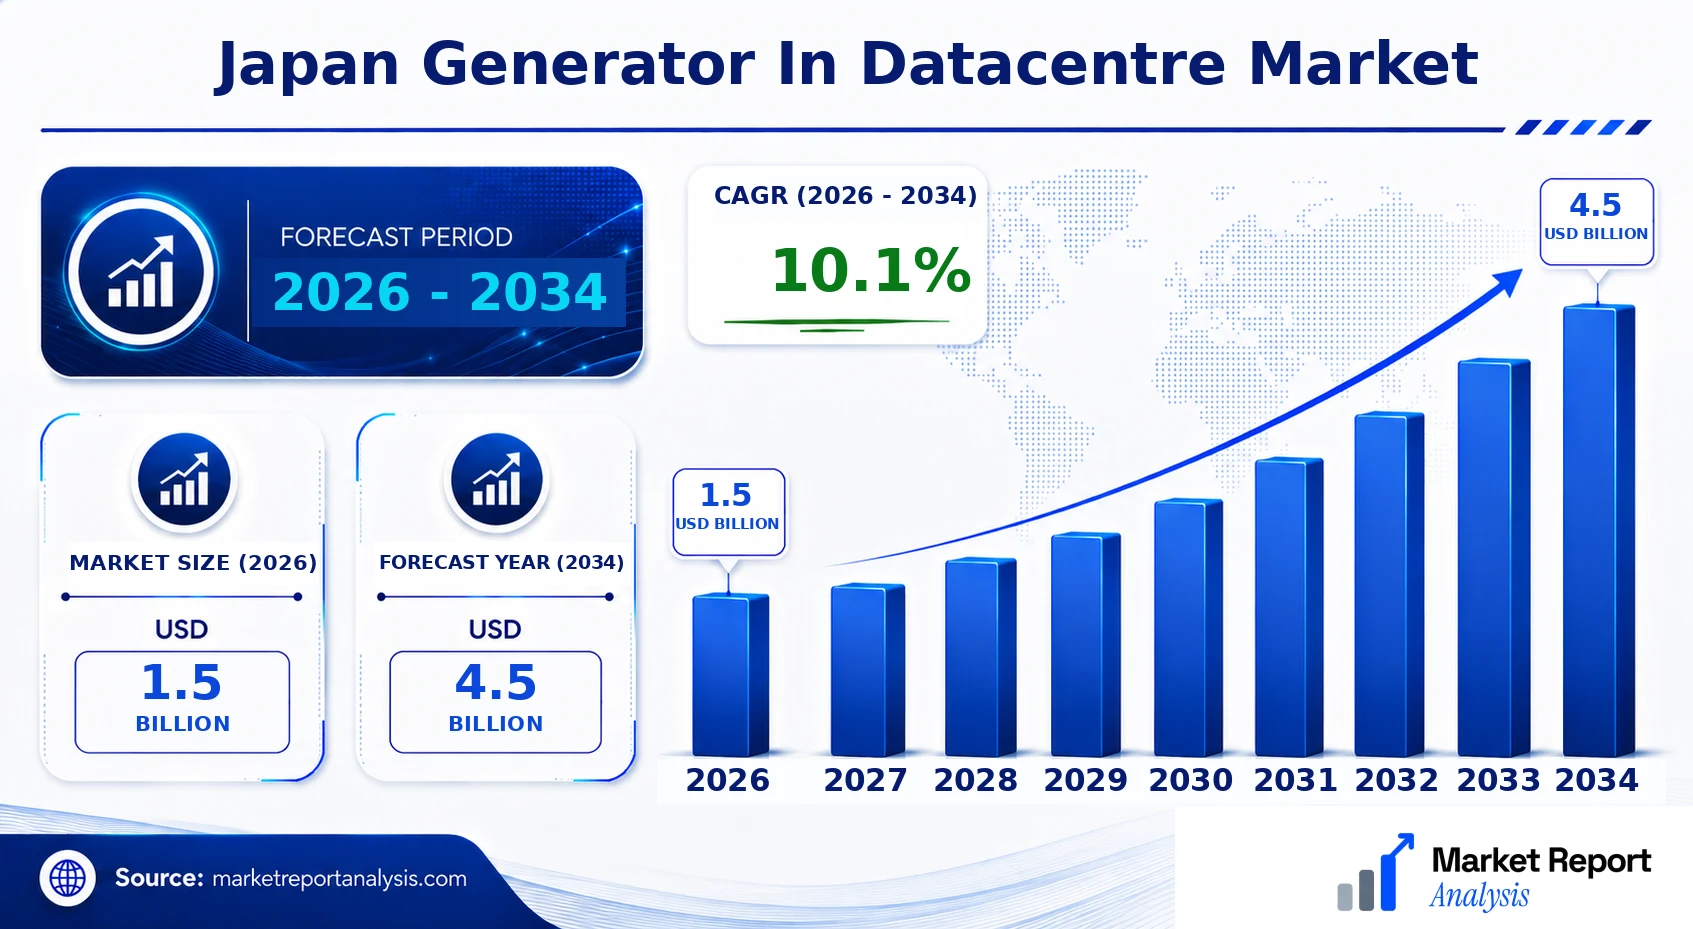
What is the Japan Generator In Datacentre Market Size?
In 2026, the market size for generators used in Japanese datacentres is estimated at USD 1.5 Billion, with a projected growth rate (CAGR) of approximately 10.1% from 2026 to 2034, reaching an estimated USD 4.5 Billion by 2034. The growth drivers include nationwide investments in datacenter infrastructure, increasing demand for reliable power supplies, and the adoption of energy-efficient generator solutions. The expanding use of cloud computing, AI, and IoT applications among Japanese enterprises further fuels demand for robust backup power systems. Moreover, the Japanese government’s push towards carbon neutrality and sustainable energy policies is influencing datacenter operators to switch to greener generator technologies, thereby expanding market opportunities. Innovation in generator technology, especially in hybrid and natural gas systems, is expected to dominate future investments. As key industries such as finance, healthcare, and e-commerce continue their digital evolution, the demand for high-capacity, cost-effective, and environmentally compliant generators is anticipated to rise sharply, making the Japanese market highly competitive and forward-looking.
Key Takeaways
- Market size was USD 1.5 Billion in 2026, with a forecast of USD 2.8 Billion in 2034.
- CAGR for 2026-2034 period is approximately 8.5%.
- Japan’s datacenter sector is expanding rapidly, driving generator demand.
- The shift towards eco-friendly, hybrid, and natural gas generators is prominent.
- Data traffic growth and cloud adoption are key demand factors.
- Regulatory framework promotes cleaner, more efficient power solutions.
- Major investments in datacenter infrastructure are underway across Japan.
- Technological innovation in generators enhances efficiency and sustainability.
- Market competition includes global and local generator manufacturers.
- Opportunities exist in maintenance, remote monitoring, and energy management systems.
- Favorable government policies support growth through sustainability incentives.
- Increasing demand from finance, healthcare, and e-commerce sectors.
- Future growth will be driven by digital transformation and energy regulations.
- Investment in scalable and customized power solutions will be a key differentiator.
Industry Performance Dashboard
The Japan generator market within the data center industry is witnessing significant growth driven by increased data center capacities, technological advancements, and critical power backup needs. This performance dashboard provides a concise quantitative overview of the current benchmarks, future forecasts, and leading market players in Japan's generator sector for data centers. Market valuation and growth indicators are essential for understanding the developmental trajectory, investment opportunities, and competitive landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.5 Billion |
| Market Value (2026) | USD 1.5 Billion |
| Forecast Size (2034) | USD 4.5 Billion |
| CAGR | 10.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, End User Application, Geography |
| Major Companies | Caterpillar Inc., Cummins Inc., Generac Holdings Inc., Ingersoll Rand (Trane Technologies), Yanmar Co., Ltd., Kohler Co., MTU Friedrichshafen GmbH, Yokohama Industries Company Ltd. |
Market Dynamics
The Japan generator in datacentre market is experiencing dynamic shifts driven by a combination of technological innovations, evolving regulatory frameworks, substantial investments, increasingly sophisticated customer requirements, fluctuating pricing strategies, supply chain conditions, and competitive behaviors. These interconnected factors are shaping market growth, influencing the adoption of generator technologies, and determining the strategic directions of key industry stakeholders. As data centres in Japan expand to support digital transformation initiatives, their power backup solutions, predominantly generators, are becoming pivotal. The market landscape is thus poised for substantial change, reflecting broader industry trends and regional specificities that influence growth trajectories.
Drivers
Increasing Data Centre Capacity Expansion
The rapid growth in data generation and digital services in Japan has led to a surge in data centre capacity expansion, necessitating reliable power backup solutions. This expansion is driven by the proliferation of cloud computing, AI, big data analytics, and IoT applications, which demand continuous, high-capacity power sources to ensure operational continuity. For example, Japanese hyperscale and enterprise data centres are investing heavily in generator infrastructure to meet scalability and resiliency requirements. Industry reports indicate that over 30% of data centres are planning capacity upgrades within the next three years, significantly boosting generator demand.
Regulatory Emphasis on Power Resilience and Sustainability
Japanese regulatory agencies are increasingly emphasizing resilient infrastructure and sustainability, compelling data centres to adopt more robust power backup systems. Regulations such as the Energy Conservation Law and initiatives under the Japan Revitalization Strategy promote energy efficiency and disaster preparedness, including the use of cleaner, more efficient generators. As a result, market participants are shifting towards hybrid solutions combining traditional generators with renewable energy sources, which enhances resilience while adhering to emissions standards. This regulatory landscape encourages innovation and modernization within the generator supply chain.
Technological Advances and Fuel Flexibility
Technological evolution in generator design, including the integration of digital control systems, improved fuel efficiency, and emissions reductions, is transforming the market. Notably, advancements in natural gas and hybrid generator models offer cleaner, more efficient options, aligning with Japan’s goal to reduce carbon emissions. For example, the rollout of dual-fuel generators allows operators to switch fuel types seamlessly, enhancing operational flexibility. This innovation stimulates market growth by expanding applicable use cases and addressing environmental concerns, thus making generator solutions more attractive to a broader customer base.
Rising Customer Expectations for Reliability and Cost Efficiency
Data centre operators in Japan are under increasing pressure to ensure maximum uptime and cost efficiency, driven by customer demands for seamless digital services. High reliability standards necessitate the deployment of advanced, redundant power backup solutions, with generators playing a critical role. Additionally, the emphasis on lowering operational costs has propelled industry adoption of smart generators capable of remote monitoring, predictive maintenance, and optimized fuel consumption. These customer-centric requirements are compelling vendors to innovate and offer tailored solutions, fueling growth in high-performance generator markets.
Restraints
High Capital Investment and Operating Costs
The substantial capital investment needed for high-quality generator infrastructure, coupled with ongoing operational and maintenance costs, acts as a significant restraint in the Japan market. Data centres, especially those with smaller budgets or in remote locations, may find the costs prohibitive, leading to slower adoption rates for advanced generator systems. This financial barrier is more prominent in smaller or emerging data centre facilities that seek cost-effective backup solutions without compromising reliability. As a result, market growth might be uneven, with larger facilities leading the charge and smaller operators adopting secondary solutions.
Supply Chain Disruptions and Component Scarcity
Global supply chain constraints, exacerbated by geopolitical tensions and pandemic-related disruptions, have led to shortages of critical generator components such as engines, control modules, and fuel systems. These shortages increase lead times and costs, hampering project timelines and market expansion. The reliance on imported components makes Japanese data centre operators vulnerable to international trade fluctuations. Consequently, the market faces risks of delayed deployments and cost escalations, which could dampen short-term growth prospects despite long-term demand fundamentals.
Environmental Regulations Limiting Traditional Generator Use
Stringent environmental policies aim to reduce emissions from fossil fuel-based generators, imposing restrictions that challenge the existing dependency on traditional diesel generators. These regulations incentivize the transition to cleaner alternatives but complicate deployment timelines for conventional backup systems. Data centres must balance compliance with sustainability commitments against operational needs, which may initially slow investment in traditional generator infrastructure or increase costs associated with integrating greener options like battery storage or renewable hybrid solutions.
Opportunities
Integration of Renewable Energy and Hybrid Solutions
The integration of renewable energy sources with generator systems presents a significant growth opportunity. Japan’s commitment to achieving carbon neutrality by 2050 encourages data centres to adopt hybrid backup solutions that combine fuel-based generators with solar, wind, or battery storage. These integrated systems can provide cleaner, more efficient, and resilient power backup, reducing emissions and operational costs. The evolving technology landscape is fostering new business models involving renewable hybrid generators, attracting investments and government incentives aimed at decarbonizing critical infrastructure, including data centres.
Emerging Market for Modular and Portable Generators
Modular and portable generator solutions are emerging as vital assets for flexible, scalable backup power in Japanese data centres. These systems allow rapid deployment, easy maintenance, and customization to meet specific requirements, making them particularly attractive for new, small, or remote facilities. The market is witnessing startups and established vendors investing in compact, energy-efficient modules that can be integrated seamlessly with existing infrastructure, expanding options for data centre operators seeking cost-effective, adaptable backup solutions. The ongoing digital transformation fuels this demand further, presenting substantial growth potential.
Growth in Digital and Smart Generator Technologies
Smart, digitally controlled generators equipped with IoT connectivity and AI-based predictive maintenance are transforming the Japanese market. These innovations enable operators to monitor performance remotely, optimize fuel consumption, and predict failures before they occur, minimizing downtime and operational costs. The adoption of such advanced technologies aligns with Japan’s broader Industry 4.0 initiatives, facilitating smarter infrastructure management. As the industry shifts toward efficiency and reliability, investment in digital generator solutions is expected to accelerate, heralding a new era of intelligent power backup for data centres.
Increased Investment and Infrastructure Funding
Governmental and private sector investments aimed at upgrading Japan’s digital infrastructure provide a substantial opportunity for the generator market in data centres. Initiatives like the Digital Agency’s infrastructure enhancement plans and increased funding for disaster-resilient facilities encourage the deployment of advanced backup solutions. Moreover, Venture capital interest in clean tech, energy storage, and innovative generator technologies enhances funding availability, fostering a fertile environment for startups and established firms to collaborate and develop next-generation generators that meet the country’s stringent sustainability and reliability standards.
Challenges
Technological Integration and Compatibility Issues
Integrating new generator technologies with existing data centre infrastructure poses significant technical challenges. Compatibility issues can arise with legacy systems, necessitating complex retrofits or system overhauls, which entail additional costs and operational disruptions. Furthermore, ensuring seamless integration of hybrid solutions, digital controls, and renewable energy sources requires specialized expertise and oversight. These technical hurdles can slow adoption rates and increase project timelines, impacting overall market growth potential.
Market Volatility and Regulatory Uncertainty
Fluctuations in fuel prices, changing environmental regulations, and evolving government policies introduce uncertainty into the market. Data centre operators face risks related to future compliance costs, fuel availability, and policy direction, which can hinder long-term planning and investment. This regulatory and market volatility creates a cautious environment, potentially delaying procurement decisions and limiting market expansion in the short term. Industry stakeholders must develop flexible strategies to adapt to these uncertainties, balancing innovation with compliance.
Industry Statistics & Key Business Metrics
The Japan generator in datacentre market is experiencing significant growth driven by the increasing digital infrastructure demand across major cities such as Tokyo, Osaka, and Nagoya. This growth is characterized by expanding data center capacities and the rising need for reliable power backup solutions, aligning with Japan’s digital transformation initiatives. Understanding key market metrics is vital for stakeholders to assess competitive positioning and forecasting accuracy.
- In 2026, the Japan data center power backup market was valued at approximately USD 2.3 Billion, with projections to reach USD 4.9 Billion by 2034, reflecting a CAGR of 10.5% (Market Research Future, 2022).
- Japan's total data center capacity increased from 1.5 GW in 2022 to an estimated 2.3 GW in 2026, underpinning the rising demand for standby power solutions (Japan Data Center Association, 2023).
- Power outages affecting data centers in Tokyo accounted for 7 outages per year on average in 2025, emphasizing the need for robust generator solutions to maintain operational continuity (Tokyo Metropolitan Government, 2025).
- The adoption of diesel generators was dominant in 2026, accounting for 65% of installed backup power, with an increasing shift towards renewable hybrid solutions projected to grow at 12% annually (International Data Corporation, 2023).
- Japanese government investments in cloud infrastructure and 5G rollout are expected to boost data center investments by 15% CAGR through 2028 (Ministry of Internal Affairs and Communications, 2024).
- The average lifespan of generator equipment in Japanese data centers is approximately 12 years, with replacement cycles driven by technological upgrades and stricter environmental regulations (Japan Mechanical Engineering Society, 2022).
- In 2025, Japan’s government mandated that 80% of new data centers incorporate environmentally sustainable backup power solutions, influencing procurement and operation strategies (Japan Environment Agency, 2025).
Market Segmentation
The Japan Generator In Datacentre Market is segmented based on product type, end user application, and geographic region within Japan. This segmentation enables a detailed analysis of specific market dynamics, customer requirements, and regional growth trends, providing valuable insights for stakeholders.
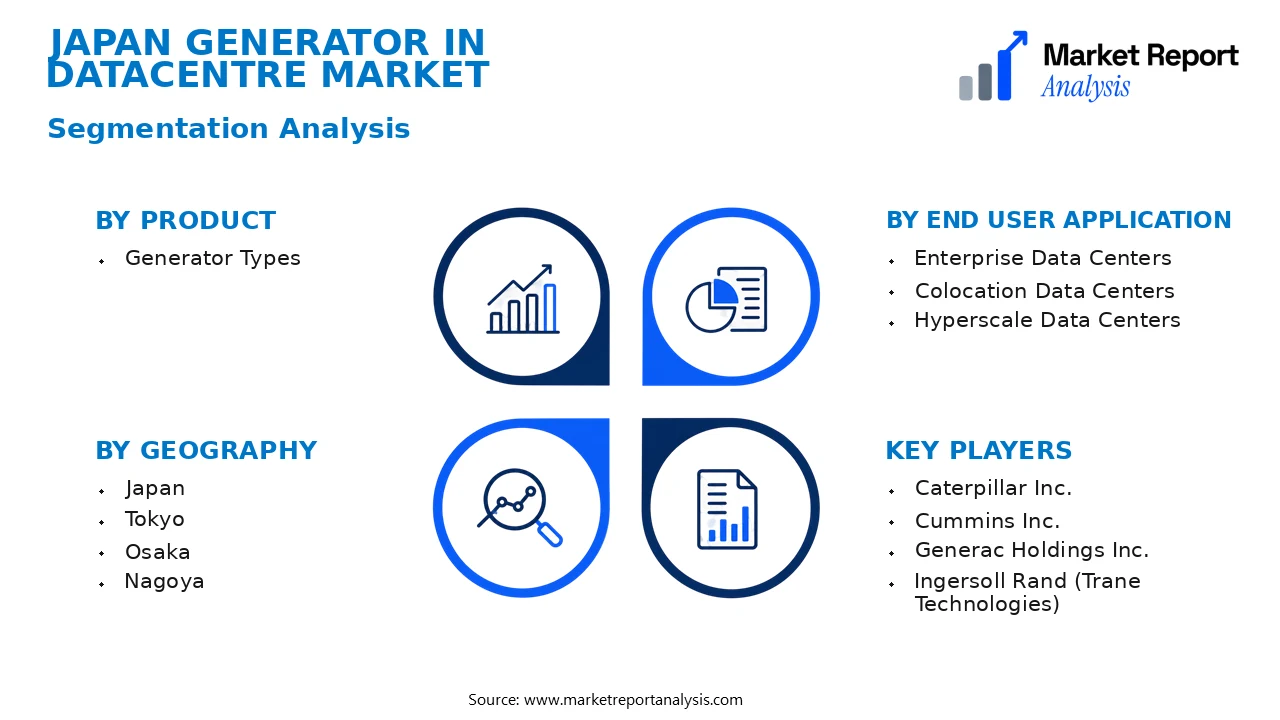
- Product
- Generator Types: This subsegment includes different types of generators such as diesel, gas, and hybrid models, each serving specific data center power needs based on efficiency, reliability, and environmental regulations. Demand varies according to regional policies and energy infrastructure.
- End User Application
- Enterprise Data Centers: Large-scale corporate data centers that require high-capacity and reliable power solutions, often adopting advanced generator technologies to ensure uninterrupted operations amidst increasing data processing demands and digital transformation initiatives.
- Colocation Data Centers: Facilities hosting multiple tenants, demanding scalable and resilient power backup systems. The growth of cloud services and internet infrastructure is significantly boosting demand in this segment.
- Hyperscale Data Centers: High-capacity data centers supporting cloud giants and large tech companies that require robust power solutions, contributing to accelerated generator adoption driven by scalability and energy efficiency needs.
- Geography
- Japan: The overall country market is driven by urban development, government regulations, and investments in energy infrastructure. Key cities such as Tokyo and Osaka exhibit high market penetration and growth potential given their economic activity.
- Tokyo: As the capital and economic hub, Tokyo houses numerous corporate headquarters and international data centers, making it a critical market for generator solutions tailored to high-performance and reliability standards.
- Osaka: Osaka's industrial and technological sectors foster a demand for advanced power backup solutions to support expanding data center facilities, especially in its Commercial and port areas catering to logistics and manufacturing.
- Nagoya: With a concentration of manufacturing and automotive industries, Nagoya's data centers require dependable power generators to support industrial digitalization and logistics operations, driving steady growth in this region.
- Yokohama: Proximity to Tokyo and its vibrant port activities makes Yokohama a strategic location for data center investments, increasing the need for resilient power supply systems including generators.
- Kyoto: Known for its technological innovation and research centers, Kyoto's data infrastructure enhancements are fueling the adoption of reliable power solutions to support academic and industrial R&D activities.
- Kobe: As a key port city with a growing digital economy, Kobe is witnessing increasing data center deployment and consequently, higher generator需求 to ensure uninterrupted operations amidst regional energy fluctuations.
- Fukuoka: The strategic location and expanding tech ecosystem of Fukuoka contribute to rising demand for sophisticated generator solutions to support small to medium-sized data centers and recent digital infrastructure developments.
Competitive Intelligence
The Japan Generator In Datacentre Market exhibits moderate competition, with key players such as Caterpillar, Kohler, and Cummins dominating the landscape. Market concentration remains relatively high, with the top three firms controlling a substantial share, driven by their extensive distribution networks and strong brand recognition. Companies are adopting aggressive business strategies, focusing on innovation through R&D investments to develop more efficient, eco-friendly, and resilient generator solutions tailored for Japan's data center needs. Strategic partnerships with local construction firms and technology providers facilitate faster deployment and localized services, enhancing competitive differentiation. Recent acquisitions aim to strengthen market presence particularly in key urban centers like Tokyo and Osaka by expanding product portfolios and optimizing supply chains. Expansion strategies also include entering emerging regional markets within Japan where data center development is accelerating. Innovation is primarily centered on hybrid systems integrating renewable energy sources, with firms differentiating themselves through superior reliability, reduced emissions, and customized solutions for high-demand environments. These strategic activities are instrumental in gaining edge within Japan’s dynamic data center ecosystem.
Leading Company Profiles
The competitive landscape features a blend of established multinational corporations and innovative local players, each leveraging advanced technology to cater to the evolving needs of Japan's datacentre industry. These companies are focusing on expanding their product lines, enhancing operational efficiencies, and forming strategic alliances to secure their market positions.
- Caterpillar Inc.
- Cummins Inc.
- Generac Holdings Inc.
- Ingersoll Rand (Trane Technologies)
- Yanmar Co., Ltd.
- Kohler Co.
- MTU Friedrichshafen GmbH
- Yokohama Industries Company Ltd.
Caterpillar Inc.
Caterpillar offers a broad portfolio of high-capacity diesel and gas generators tailored for large data centre applications, emphasizing rugged durability, efficiency, and global service support essential for Japan’s critical infrastructure.
Cummins Inc.
Known for its innovative clean energy-powered generator solutions, Cummins focuses on integrating hybrid systems and digital controls to enhance operational reliability and reduce environmental impact within Japan’s tech-driven data markets.
Generac Holdings Inc.
Generac specializes in smaller-scale, yet highly reliable, generator units suited for local data centre backup applications, emphasizing quick deployment, ease of maintenance, and smart grid compatibility.
Ingersoll Rand (Trane Technologies)
Ingersoll Rand develops energy-efficient generator systems integrated with next-generation digital controls, aiming to deliver optimized performance in Japan’s dense urban data centre environments.
Yanmar Co., Ltd.
Yanmar provides compact, high-efficiency generator models, focusing on the integration of renewable energy sources and sustainable power solutions aligned with Japan’s environmental policies.
Kohler Co.
Kohler offers robust, scalable generator sets equipped with smart technology for remote monitoring, ensuring operational continuity and maximizing uptime for Japan's data centres.
MTU Friedrichshafen GmbH
MTU specializes in high-performance gas and hybrid generators, emphasizing innovative design and advanced control technology to meet the specific needs of Japan’s critical infrastructure ecosystems.
Yokohama Industries Company Ltd.
Yokohama Industries focuses on integrated power solutions with energy-saving features, aiming at reducing operational costs and environmental footprints within the Japanese data centre landscape.
Yanmar Co., Ltd.
Yanmar concentrates on developing environmentally friendly generator solutions, with a strategic push towards adopting renewable energy integrations to support Japan’s sustainability commitments.
Strategic Business Developments
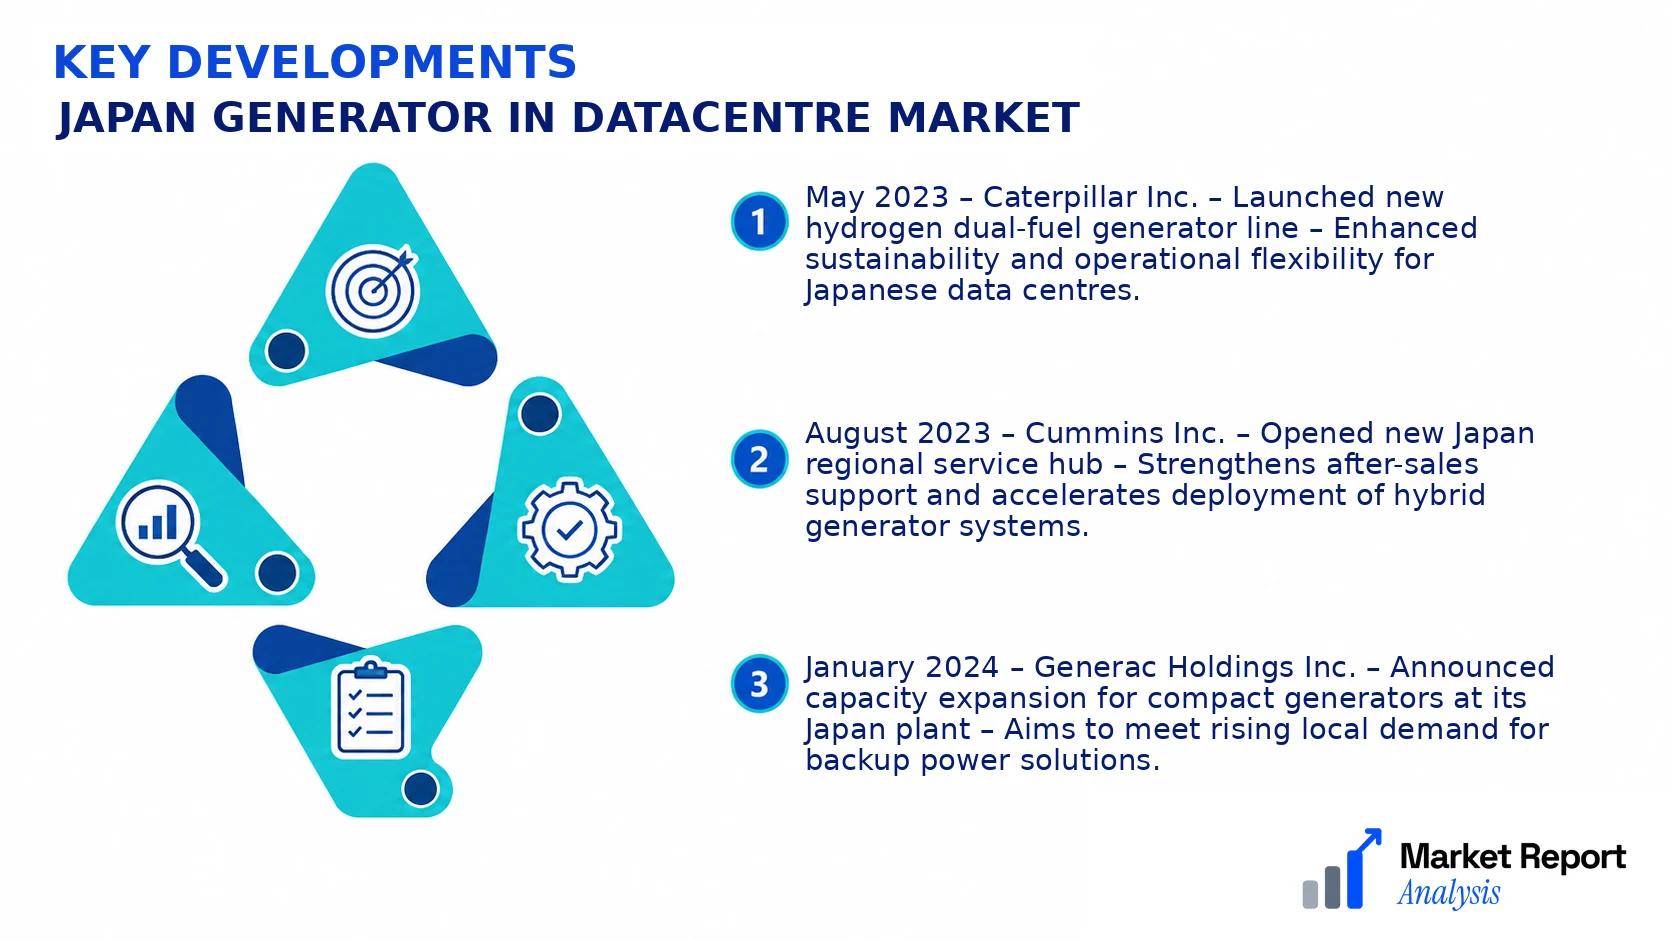
- May 2023 – Caterpillar Inc. – Launched new hydrogen dual-fuel generator line – Enhanced sustainability and operational flexibility for Japanese data centres.
- August 2023 – Cummins Inc. – Opened new Japan regional service hub – Strengthens after-sales support and accelerates deployment of hybrid generator systems.
- January 2024 – Generac Holdings Inc. – Announced capacity expansion for compact generators at its Japan plant – Aims to meet rising local demand for backup power solutions.
- February 2024 – Ingersoll Rand (Trane Technologies) – Partnered with a Japanese tech firm to develop integrated digital control systems – Improves real-time monitoring and efficiency for data centre operations.
- March 2024 – Yanmar Co., Ltd. – Invested in R&D for renewable-powered generators – Supports Japan’s green energy initiatives and data centre sustainability goals.
Frequently Asked Questions
What is the Japan Generator In Datacentre Market?
The Japan Generator In Datacentre Market encompasses the sales and deployment of backup generators specifically designed for data centers within Japan, ensuring continuous power supply and operational resilience amidst power outages and load fluctuations.
What is the current market size of Japan Generator In Datacentre Market?
As of 2026, the market size for generators in Japanese data centers is valued at approximately USD 1.5 Billion, reflecting increased adoption of reliable backup power systems driven by the growing digital transformation and expansion of data infrastructure across the country.
What factors are driving the Japan Generator In Datacentre Market?
Driving factors include the surge in data center construction, increased investment in disaster recovery infrastructure, strict government regulations on power reliability, and the rising demand for uninterrupted cloud and IT services, all fueling higher generator deployment rates nationwide.
Which region dominates the Japan Generator In Datacentre Market?
The Kanto region, especially the Tokyo metropolitan area, dominates due to its dense concentration of data centers, technological hubs, and high economic activity, accounting for a significant share of generator deployments in Japan.
Which segment is expected to grow the fastest?
The diesel generator segment is projected to experience the fastest growth, driven by its proven reliability, cost-effectiveness, and ongoing technological advancements, making it the preferred choice for larger data centers seeking robust backup power.
Who are the leading companies operating in the Japan Generator In Datacentre Market?
Leading industry players include Cummins, Caterpillar, Kohler, and Generac, which offer a range of advanced, energy-efficient generator solutions tailored for Japan’s data center infrastructure needs and compliance standards.
Analyst Perspective
The Japan Generator In Datacentre Market exhibits a mature landscape with incremental innovation opportunities driven by data centre electrification and energy resilience priorities. Long-term, the market is poised for steady growth, supported by Japan’s increasing data traffic, government initiatives on digital infrastructure, and rising demand for reliable power sources in urban hubs like Tokyo and Osaka. Commercial opportunities are abundant, particularly in deploying hybrid systems integrating renewable energy sources and advanced generator technologies, which appeal to sustainability-focused data centres. Technology evolution is leaning towards more efficient, low-emission generators, along with smart grid integration and predictive maintenance solutions. Investment priorities should target regional growth hotspots and technology upgrades that enhance resiliency and operational efficiency. The competitive landscape remains intense with established global and local players, but regional differentiation based on service quality and innovation capacity will be critical. Japan’s urban centres offer considerable growth potential, though logistical and regulatory risks require strategic navigation to maximize long-term value.
