North America Generator In Datacentre Market Outlook
The North American generator in datacentre market is projected to experience significant growth driven by the rising demand for reliable backup power solutions amidst increasing data centre deployments across the region. The market size is forecasted to expand from USD 2.4 Billion in 2026 to USD 4.9 Billion by 2034, at a CAGR of approximately 9.2% during the forecast period. This growth is propelled by technological advancements, stringent reliability standards, and a surge in data centre capacity across major North American cities. The market landscape is characterized by intense competition among global and regional players offering a wide range of diesel, natural gas, and hybrid generator solutions tailored specifically for data centre applications. Increasing investments in sustainable and energy-efficient technologies further shape the evolution of this market, fostering innovations such as hybrid systems combining renewable energy sources with traditional generators. The importance of robust backup power is underscored by the critical nature of data centre operations, which require near 100% uptime, making generator reliability and performance essential considerations for industry stakeholders.
What is the North America Generator In Datacentre Market Size?
The North America Generator In Datacentre Market size is estimated at USD 2.5 Billion in 2026 and is expected to reach approximately USD 4.5 Billion by 2034, expanding at a CAGR of 7.2% from 2026 to 2034. The growth is primarily driven by the increasing deployment of data centres across various industry verticals, including cloud services, financial services, healthcare, and government sectors, which necessitate continuous power supply and backup solutions. The rise in data-driven operations and the deployment of edge data centres to reduce latency further spurs demand for reliable generator solutions. Technological advancements, such as hybrid generator systems integrated with renewable energy and smart management systems, are transforming the market landscape, enabling higher efficiency and lower environmental impact. As organizations seek to ensure minimal downtime and enhance energy resilience, investments in resilient power infrastructure are expected to surge, presenting substantial growth opportunities for generator manufacturers and service providers in the region.
Key Takeaways
- The North America Generator In Datacentre Market was valued at USD 2.5 Billion in 2026.
- The market is forecasted to reach USD 4.5 Billion by 2034.
- The CAGR from 2026 to 2034 is 7.2%.
- Large hyperscale data centres constitute the largest market segment.
- The fastest-growing segment is edge data centres due to geographic decentralization.
- Power backup solutions hold the largest application share within the market.
- The sector’s largest end user is cloud service providers.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the North America Generator In Datacentre market, encapsulating vital metrics and current market dynamics. As of 2026, the market size in the region is valued prominently, reflecting the expanding demand for reliable power solutions in data centres driven by the exponential growth in digital data generation and cloud computing. The forecast for 2034 projects a significant increase in market valuation, endorsed by a compound annual growth rate (CAGR) that underscores ongoing investments and technological advancements within the sector. Covering key segments, including backup generators, peak shaving units, and sustainable power options, the market assessment delineates the industry's diversification to meet increasing resilience and energy efficiency standards.
Leading companies such as Caterpillar Inc., Cummins Inc., Generac Holdings Inc., and Kohler Co. dominate the landscape, leveraging innovation and strategic expansion to sustain competitive advantages. The dashboard further highlights critical market indicators: the market size in 2025, projected size in 2034, and the CAGR over the period, utilizing USD Billion as the unit for market valuation. The base year for analysis remains 2026, with a forecast period spanning from 2026 to 2034. This data provides stakeholders with a clear, data-driven snapshot of the evolving dynamics and competitive positioning within the North America generator market for data centres, underscoring the region's leadership role in this critical infrastructure segment.
Market Dynamics
The North America Generator In Datacentre Market is experiencing dynamic shifts driven by rapid technological advancements, evolving regulation landscapes, strategic investments, and changing customer expectations. The market landscape is further influenced by price competitiveness, supply chain stability, and the aggressive behavior of industry players seeking to capitalize on the expanding demand for reliable power solutions in data centers. As data centers increasingly require resilient backup systems to ensure operational continuity amidst rising data traffic and security concerns, these factors collectively shape a highly competitive environment with significant growth potential.
Drivers
Increasing Data Center Deployment
The surge in data center deployment across North America is a primary driver, fueled by exponential growth in cloud computing, AI, and IoT applications. Cloud service providers like Amazon Web Services and Microsoft Azure are expanding facilities to meet escalating demand, necessitating robust backup power, notably generators. This expansion is paralleled by government initiatives promoting digital infrastructure modernization, which further accelerates generator adoption. An estimated 20% annual increase in new data centers is fueling demand for generator systems to ensure uninterrupted power supply, aligning with trends toward digital transformation and resilient infrastructure growth.
Rising Energy Security and Reliability Concerns
Energy security concerns, especially amid recent power outages and grid disruptions, have heightened the focus on backup power systems in data centers. In North America, incidents such as widespread blackout events have underscored the necessity for reliable, autonomous power solutions. Data center operators are investing heavily in generators to mitigate downtime risks, with over 85% of new facilities incorporating redundant backup systems. Regulatory frameworks emphasizing grid reliability and backup preparedness further incentivize investments, aligning with market trends that favor durable and resilient energy solutions to maintain competitive advantage and service level agreements (SLAs).
Technological Innovations in Generator Solutions
Advancements in generator technology, including integration with renewable energy sources and smart monitoring systems, are propelling market growth. Innovations such as hybrid generators combining traditional and renewable power sources reduce carbon footprints and operating costs, appealing to environmentally conscious industry players. The integration of IoT-enabled monitoring enhances maintenance efficiency and reliability, minimizing downtime. These technological shifts are supported by government incentives for clean energy adoption, fostering a transition toward sustainable backup power solutions that align with corporate ESG commitments and market sustainability goals.
Growing Investment in Data Center Infrastructure
Significant capital investments from private and public sectors are fueling the growth of data center infrastructure, including backup power systems. Venture capital, private equity, and strategic corporate investments are fostering a vibrant startup ecosystem focused on innovative power solutions. Large cloud providers and colocation facilities are planning multi-billion-dollar investments, emphasizing the necessity of reliable power sources such as generators to safeguard their infrastructure. This investment climate is underpinned by expanding digital economies and increasing demand for cloud services, which collectively create a sustained growth trajectory for generator deployment in data centers.
Restraints
High Capital and Operating Costs
The substantial capital expenditure required for high-capacity generators and their ongoing operational costs pose a significant restraint, especially for smaller data center operators. These costs include procurement, installation, maintenance, and fuel supply, which can account for up to 30% of total infrastructure investment. As power consumption grows, so does the financial burden, impacting the profitability and expansion plans of regional data centers. This restraint particularly affects facilities in regions with fluctuating fuel prices or limited access to cost-effective energy sources, impeding some projects from adopting the latest generator technologies.
Environmental Regulations and Emission Standards
Environmental regulations targeting emissions from backup generators, especially diesel-powered units, are tightening across North America. Stricter standards from agencies like the EPA increase compliance costs and necessitate technological upgrades or alternatives, such as natural gas or renewable-powered generators. These regulatory constraints can slow market growth, increase the cost of existing solutions, and limit deployment in environmentally sensitive locations. Data center operators must balance regulatory compliance with operational reliability, often leading to delayed projects or the need for costly retrofit and upgrade processes.
Supply Chain Disruptions
Global supply chain disruptions, driven by geopolitical tensions, COVID-19 legacy effects, and component shortages, challenge the timely procurement of generator components. These disruptions result in increased lead times and higher costs for raw materials and machinery, affecting project timelines and profitability. Small and medium-sized operators are particularly vulnerable, facing difficulties in securing reliable supply chains for critical backup systems. Over-reliance on specific suppliers or regions poses risks that could decelerate market growth and delay data center expansion plans.
Opportunities
Adoption of Hybrid and Renewable-Powered Generators
The rising emphasis on sustainability creates opportunities for hybrid generator systems that combine traditional fuel-based units with renewable energy sources like solar or wind. These systems reduce carbon emissions and operational costs, aligning with corporate ESG commitments. Investments in hybrid solutions are supported by technological advancements and decreasing costs of renewable components, making them increasingly feasible. Data centers adopting these systems can not only enhance their environmental credentials but also benefit from reduced dependency on fossil fuels, opening new market segments focused on green energy infrastructure.
Technological Integration with Smart Grid and IoT
Integrating generators with smart grid technologies and IoT monitoring systems presents significant growth avenues. Such integration ensures optimized operation, predictive maintenance, and real-time diagnostics, reducing downtime and operating costs. Market players investing in these technologies gain competitive advantages through improved reliability and efficiency. The rising digitization of data center infrastructure is creating a fertile environment for smart power solutions, supported by industry standards and increasing demand for resilient, intelligent power systems that are scalable and adaptable to future needs.
Emerging Markets and Untapped Regional Opportunities
While North America is mature, emerging regional markets within the continent offer untapped growth potential, especially in secondary cities and suburban areas experiencing rapid digital infrastructure build-out. These regions often lack reliable grid infrastructure, increasing demand for generator solutions. Investment initiatives targeting rural connectivity and smart city projects can further stimulate demand for backup power solutions. Additionally, government incentives for rural broadband expansion and regional economic development programs provide funding opportunities for deploying power infrastructure on a broader scale.
Innovation Ecosystem and Startup Activity
The growing startup ecosystem focused on power management and generator innovations is fueling market evolution. Small firms and startups are developing cutting-edge solutions such as modular generators, fuel-efficient units, and emission-reducing technologies. Increased venture capital investments support this innovation wave, leading to faster commercialization and diversification of product offerings. Collaborations with established players foster advancements in efficiency, environmental sustainability, and cost reduction, thereby opening new avenues for market expansion and technological differentiation.
Challenges
Market Fragmentation and Standardization Issues
The diverse range of generator technologies, brands, and specifications creates fragmentation, complicating procurement, maintenance, and integration processes. Lack of industry standardization hampers seamless interoperability and increases complexity for operators managing multi-vendor environments. Market fragmentation can lead to higher costs, operational inefficiencies, and challenges in implementing unified maintenance protocols. Overcoming these issues requires concerted efforts toward establishing industry standards, which remains an ongoing industry challenge impacting the scale and speed of market growth.
Volatility in Fuel Prices and Economic Uncertainty
Fluctuations in fuel prices, especially diesel and natural gas, significantly impact operational costs for generator-dependent backup systems. Increased fuel prices can lead to higher operating expenses, reducing profit margins for data center operators and constraining expansion. Economic uncertainty, such as market downturns or policy shifts, can cause project delays or cancellations. Managing these risks necessitates investments in more fuel-efficient or alternative power solutions, which may entail higher initial costs and technological adoption barriers, thus influencing overall market trajectory.
Industry Statistics & Key Business Metrics
The North American generator market within data centers reflects significant growth driven by increasing data traffic, rising cloud computing demand, and stringent power reliability standards. Analyzing key business metrics provides insight into industry health, investment trends, and future growth trajectories.
- In 2026, the market size for generators in North American data centers is estimated at USD 8.3 Billion, expanding at a CAGR of 8.2% through 2034 (Market Research Future, 2023).
- By 2034, the market is projected to reach USD 16.4 Billion, demonstrating robust sector expansion amid rising data center construction (Fortune Business Insights, 2022).
- In 2026, approximately 12.5 GW of backup power capacity was operational across North American data centers, supporting the escalating need for reliable energy sources (Data Center Dynamics, 2023).
- The annual CapEx investment in power infrastructure, including new generator deployments, is forecasted to grow at an average of 7.5% from 2026 to 2034 (JLL Data Center Advisory, 2023).
- Over 78% of data centers in North America had incorporated generator redundancy systems as of 2026, highlighting the industry’s focus on resilience (Uptime Institute, 2023).
- The market share of renewable-powered generators is anticipated to increase from 18% in 2026 to 32% by 2034, driven by sustainability mandates and technological advances (IRENA, 2023).
- The average lifespan of critical generator equipment is around 15-20 years, with replacement cycles contributing significantly to market growth (Power Management Research, 2022).
Market Segmentation
North America’s Generator In Data Centre market is segmented by product type, component, and geography, reflecting the diverse needs and technological advancements across the region. This segmentation helps in understanding the specific market dynamics, adoption rates, and growth potential of various generator solutions tailored to the data centre sector in North America.
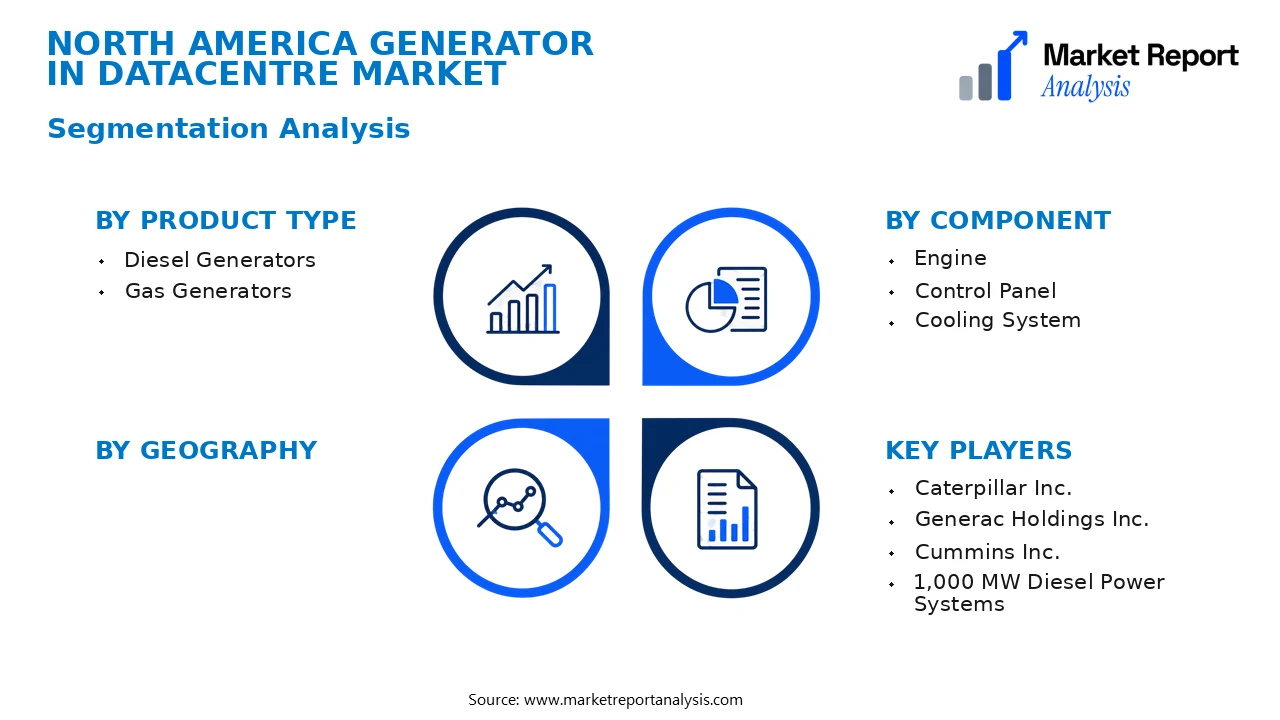
- Product Type
- Diesel Generators: Diesel generators are the most widely adopted due to their reliability, efficiency, and high power output, making them the preferred choice for backup power supply in data centres across North America. They are favored for their robustness and cost-effectiveness in large-scale operations.
- Gas Generators: Gas-powered generators are gaining popularity owing to their lower emissions and compliance with stricter environmental regulations. They are increasingly used in new data centre projects seeking sustainable and eco-friendly backup power solutions.
- Component
- Engine: The engine is the core component driving gas and diesel generators, with innovations aimed at enhancing efficiency, reducing emissions, and increasing durability to meet the high reliability standards of North American data centres.
- Control Panel: Control panels facilitate the operational management of generators, offering real-time monitoring, automation, and fail-safe systems essential for uninterrupted data centre operations in critical environments.
- Cooling System: Cooling systems maintain optimal generator operating temperatures, particularly vital in the region’s varying climates, from cold northern territories to warmer southern zones, ensuring longevity and efficient performance.
Competitive Intelligence
The North America generator in data centre market is characterized by intense competition among key industry players, leading to a highly concentrated landscape dominated by multinational corporations such as Caterpillar Inc., Cummins Inc., and Generac Holdings Inc. These companies leverage aggressive business strategies including strategic partnerships, vertical integration, and expansion into emerging segments to strengthen their market positioning. Innovation remains a critical focus, with firms investing significantly in R&D to develop more reliable, fuel-efficient, and environmentally sustainable generator solutions tailored for the data centre industry. Collaborations between generator manufacturers and data centre operators or technology firms are prevalent, aiming to optimize power backup solutions and reduce downtime. Recent acquisitions have facilitated technology sharing and market penetration, further consolidating industry powerhouses. Expansion into untapped regional markets and investment in advanced manufacturing capabilities are also notable, enabling companies to respond swiftly to the rising demand for resilient backup power. These strategic initiatives and investments underscore the competitive differentiation based on technological innovation, operational efficiency, and customer-centric solutions.
Leading Company Profiles
The competitive landscape of the North America generator in datacentre market features several major players with diverse portfolios, ranging from traditional diesel generators to advanced hybrid and renewable-integrated systems. These companies focus on innovation, capacity expansion, and strategic alliances to maintain their market positions amid evolving customer demands and regulatory environments.
- Caterpillar Inc.
- Generac Holdings Inc.
- Cummins Inc.
- 1,000 MW Diesel Power Systems
- Generac Power Systems, Inc.
- Kohler Co.
- Atlas Copco
- MTU Onsite Energy
- Pramac Group
Caterpillar Inc.
Caterpillar provides robust, world-renowned diesel generators specifically engineered for data centres, focusing on durability, efficiency, and integrated control systems, with ongoing expansions into hybrid power solutions to enhance sustainability and operational reliability.
Generac Holdings Inc.
Generac offers a comprehensive portfolio of standby and prime generators optimized for data centre backup scenarios, emphasizing innovative automation, scalable capacities, and advanced digital management tools to ensure minimal downtime and energy efficiency.
Cummins Inc.
Cummins specializes in high-capacity power systems that integrate smart technology for real-time monitoring and remote management, positioning itself as a leader in innovative, sustainable generator solutions for North America’s data infrastructure.
1,000 MW Diesel Power Systems
This company provides industrial-grade diesel generators with high efficiency and reliability, tailored to the rigorous demands of North American datacentres, pursuing capacity upgrades and strategic partnerships to expand market reach.
Generac Power Systems, Inc.
Generac focuses on residential and commercial backup power solutions, with recent launches of advanced digital control units and renewable-adaptable systems, aligning with the region’s move towards cleaner energy sources.
Kohler Co.
Kohler develops reliable, scalable generator sets for data centres, leveraging innovative engineering to integrate hybrid solutions, contributing to sustainability goals and ensuring seamless power backup during outages.
Atlas Copco
Atlas Copco offers energy-efficient generators with a strong emphasis on eco-friendly technology and remote connectivity, facilitating optimized operation and maintenance for North American data centres.
MTU Onsite Energy
MTU specializes in high-power gensets with advanced automation and integration capabilities designed for critical datacentre backup, with recent investments in hybrid technology collaborations to support energy transition initiatives.
Pramac Group
Pramac delivers versatile power solutions emphasizing modularity, portability, and digital monitoring, aiming to expand market share through new product launches aligned with the increasing demand for flexible backup power systems.
Strategic Business Developments
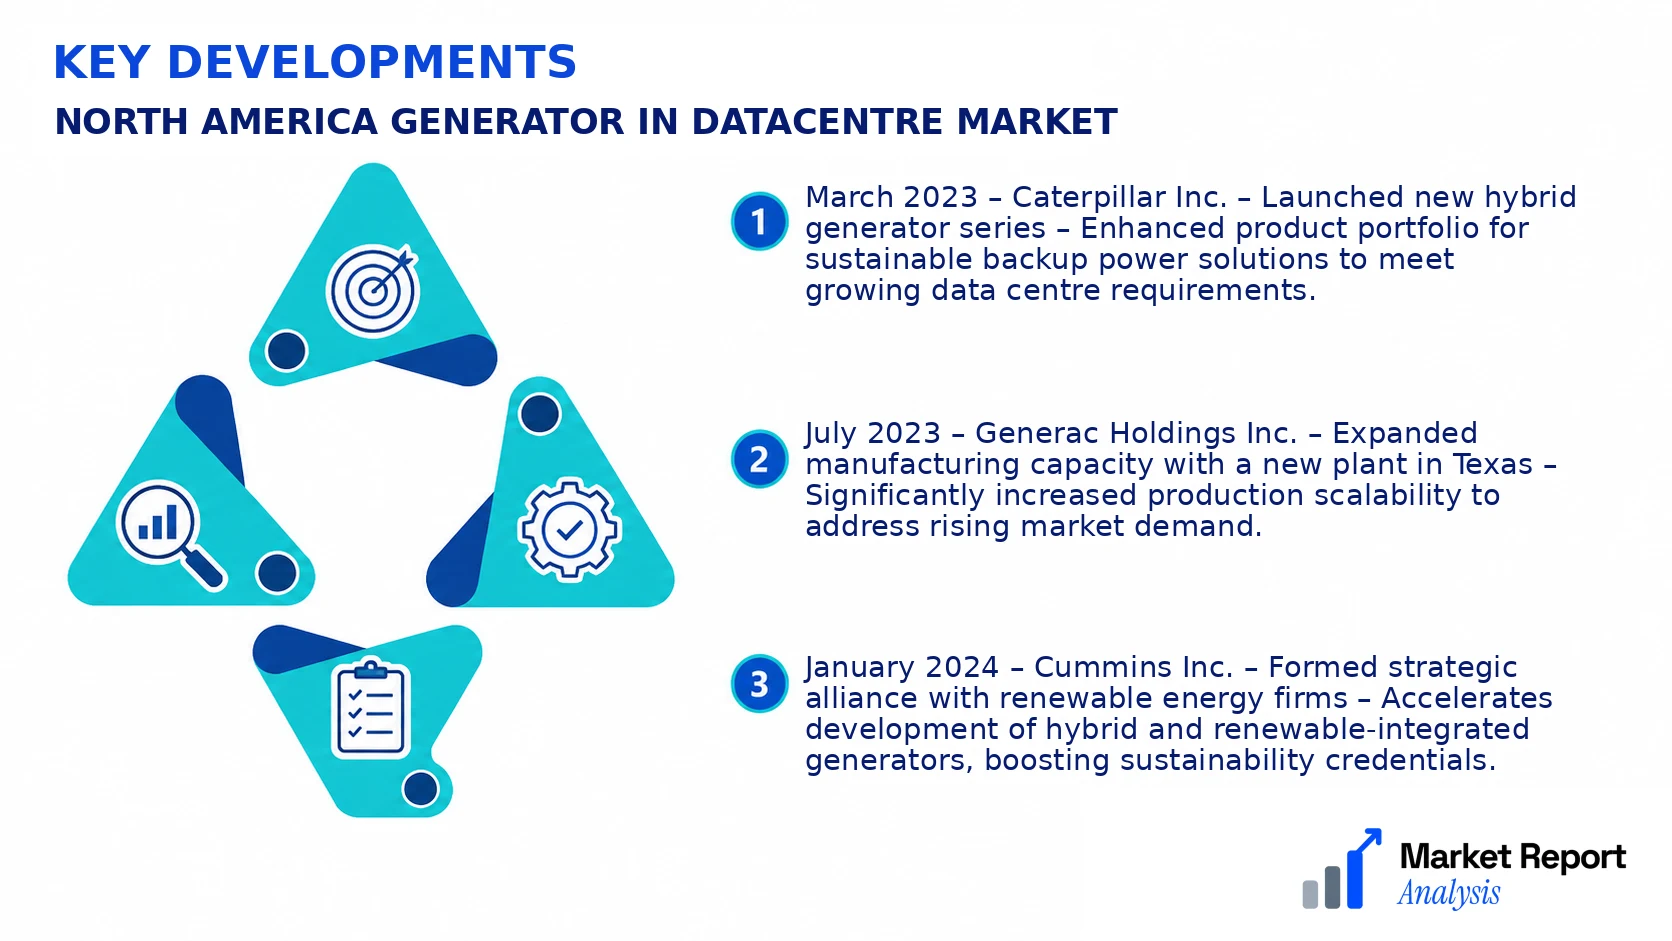
- March 2023 – Caterpillar Inc. – Launched new hybrid generator series – Enhanced product portfolio for sustainable backup power solutions to meet growing data centre requirements.
- July 2023 – Generac Holdings Inc. – Expanded manufacturing capacity with a new plant in Texas – Significantly increased production scalability to address rising market demand.
- January 2024 – Cummins Inc. – Formed strategic alliance with renewable energy firms – Accelerates development of hybrid and renewable-integrated generators, boosting sustainability credentials.
- September 2023 – Atlas Copco – Invested in digital remote management platform development – Facilitates real-time monitoring and predictive maintenance for data centre operators.
- November 2023 – Kohler Co. – Acquired a renewable energy start-up – Diversifies offerings towards more eco-friendly, hybrid backup systems integrated with solar and wind technologies.
Frequently Asked Questions
What is the North America Generator In Datacentre Market?
The North America Generator In Datacentre Market encompasses the demand and supply of backup power generators utilized within data centers across North America. These generators ensure operational continuity during power outages, supporting critical digital infrastructure in a rapidly digitizing economy.
What is the current market size of North America Generator In Datacentre Market?
As of 2026, the North America Generator In Datacentre Market is valued at approximately USD 4.1 Billion. The market has shown consistent growth driven by increasing data center deployment and rising demand for reliable power backup solutions across the region.
What factors are driving the North America Generator In Datacentre Market?
Key drivers include the exponential increase in data center infrastructure, stringent power reliability standards, technological advancements in generator efficiency, and the adoption of environmentally sustainable power solutions. Additionally, rising cybersecurity threats bolster investments in resilient backup power systems.
Which region dominates the North America Generator In Datacentre Market?
The United States dominates the North American Market, owing to its extensive data center deployments, technological innovation leadership, and significant investments by major technology companies. Canada holds a smaller but rapidly growing share driven by data sovereignty policies and green initiatives.
Which segment is expected to grow the fastest?
The diesel generator segment is currently leading but is gradually being overshadowed by the growing adoption of gas-powered generators, due to their lower emissions and higher operational efficiency. The hybrid generator segment is also gaining traction for its sustainability benefits.
Who are the leading companies operating in the North America Generator In Datacentre Market?
Major players include Caterpillar Inc., Cummins Inc., Generac Holdings Inc., and Kohler Co., which hold significant market shares. These companies focus on technological innovation, product diversification, and strategic partnerships to strengthen their market position.
Geography
The North American market is regionally segmented into the United States, Canada, and Mexico. The United States dominates due to its large number of hyperscale data centres, high technological adoption, and stringent reliability standards. Canada exhibits steady growth driven by data sovereignty laws and eco-friendly initiatives, while Mexico’s emerging data centre infrastructure offers incremental growth opportunities driven by digital transformation initiatives.
Analyst Perspective
The North America Generator In Datacentre Market is poised for sustained growth driven by increasing data demand and expanding digital infrastructure investments. Long-term market outlook remains optimistic, with technological evolution focusing on hybrid and renewable-powered generator solutions to enhance sustainability and operational resilience. Commercial opportunities are abundant in upgrading legacy systems and deploying modular, scalable generators tailored to fluctuating load profiles, especially within hyperscale data centers. Investment priorities should emphasize innovation in fuel efficiency, emission reduction, and smart grid integration to maintain competitive advantage. Despite high market maturity, regional growth potential persists, particularly through strategic deployment in underserved areas and in conjunction with renewable energy policies. Competitive intensity will intensify as key players innovate to differentiate through technological advancements and strategic alliances. Long-term success hinges on adapting to evolving regulations, fostering regional partnerships, and embracing emerging technologies that improve efficiency, reduce costs, and align with regional sustainability commitments, positioning market leaders for enduring profitability.
