Saudi Arabia Generator In Datacentre Market Outlook
The Saudi Arabia Generator In Datacentre Market is experiencing rapid growth driven by an expanding digital infrastructure and increasing demand for reliable power solutions in the country's burgeoning data centre industry. As Saudi Arabia continues to diversify its economy and invest in technological innovation, the need for efficient and sustainable power backups has become paramount. The market currently holds a valuation of USD 2.5 Billion in 2026, with projections indicating it will reach USD 4.5 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of approximately 7.7% over the forecast period from 2026 to 2034. Growing industrialization, government initiatives supporting smart city projects, and increased foreign investment in data-driven sectors are major demand drivers. Moreover, advances in generator technology focusing on fuel efficiency and emission reductions are influencing market dynamics. Commercial opportunities are plentiful, especially in development zones targeting large-scale hyperscale and enterprise data centres, considering Saudi Arabia's push for digital sovereignty and sustainable energy use.
What is the Saudi Arabia Generator In Datacentre Market Size?
The market size for generator solutions in Saudi Arabian data centres is projected to grow from USD 2.5 Billion in 2026 to approximately USD 4.5 Billion by 2034. This represents a significant increase driven by the expanding data centre ecosystem within the Kingdom. The growth is primarily fueled by escalating investments in digital transformation initiatives, which necessitate robust backup power systems to ensure continuous operations amid power outages or grid failures. Additionally, the surge in cloud computing, enterprise data processing, and IoT applications further propels equipment demand. The country's strategic focus on infrastructure modernization and data sovereignty boosts investments in local data centre infrastructure, creating a sustainable outlook for generator sales. Technological developments such as hybrid generators powered by biofuels or renewable sources are expected to influence future procurement strategies, highlighting potential for technological upgrades. The increasing adoption of energy-efficient generators alongside rising energy costs will also encourage data centre operators to upgrade existing systems, emphasizing the market's long-term growth prospects.
Key Takeaways
- The Saudi Arabia Generator In Datacentre Market was valued at USD 2.5 Billion in 2026.
- The market is projected to reach USD 4.5 Billion by 2034.
- The CAGR for the forecast period is approximately 7.7%.
- Riyadh is the leading Saudi city for data centre expansion and generator demand.
- Jeddah is the fastest-growing Saudi city driven by regional infrastructure development.
- The large segment comprises diesel-powered generators, constituting over 70% of market share in 2026.
- The fastest-growing segment includes hybrid and renewable-powered generators, with high adoption rates expected post-2026.
- Data centres are the largest application in the market, requiring high-capacity backup systems.
- Energy efficiency and emissions regulations shape generator procurement strategies.
- Increasing government and private sector investments boost market growth.
- Industry competition is intensifying with local and international generator manufacturers vying for market share.
- Growth is supported by the digital transformation initiatives outlined in Saudi Vision 2030.
- Investment in eco-friendly and renewable-based generators offers future growth opportunities.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive perspective on the Saudi Arabia Generator In Datacentre Market, highlighting key metrics and trends that define its current state and future trajectory. This section provides insights into market valuation, growth rates, and industry dynamics tailored specifically to Saudi Arabia's landscape. It includes critical indicators such as market size in 2026, forecast size in 2034, and the compound annual growth rate (CAGR) over the forecast period. The dashboard also notes the base year for analysis, the specific forecast period, and relevant city-level demand clusters within Saudi Arabia, emphasizing the leading city in datacentre infrastructure development. Furthermore, it identifies the fastest-growing city, deeply connected to regional development initiatives and economic expansion plans, as well as the segments covered namely, diesel, gas, and hybrid generators. The major companies listed are industry-relevant players such as Caterpillar Inc., Rolls-Royce, and Cummins Inc., who are active in the Saudi market, investing in capacity expansion and technological innovation. Market valuation is expressed in USD Billion to maintain consistency across data points. These metrics are crucial for investors, policymakers, and industry stakeholders to comprehend the market's health, competitive landscape, and potential growth opportunities within Saudi Arabia's burgeoning data centre sector.
Market Dynamics
The Saudi Arabia generator market for data centers is experiencing profound transformation driven by a spectrum of factors including advancing technology, evolving regulatory frameworks, increasing investments, and shifting customer requirements. The digital infrastructure expansion is necessitating reliable and sustainable power solutions, which influence competitive dynamics and pricing strategies. Supply chain conditions, geopolitical considerations, and local policy incentives further shape market behavior, creating a competitive landscape that demands innovation and adaptability. As the Kingdom accelerates toward its Vision 2030 goals, these elements collectively craft a complex environment for generator deployment in data centers, emphasizing reliability, efficiency, and sustainability.
Drivers
Rapid Growth of Data Centers
The rapid expansion of data centers within Saudi Arabia, fueled by government initiatives and private sector investments, significantly propels the demand for reliable power supply solutions. As digital transformation accelerates across industries such as finance, telecommunications, and government services, data centers serve as critical infrastructure. For instance, the establishment of new hyperscale and edge data centers in cities like Riyadh and Jeddah underscores the pressing need for robust generator solutions that ensure uninterrupted operations. The trend towards cloud computing and IoT further intensifies this growth, with Saudi Arabia aiming to host over 50 data centers by 2030, creating a substantial market for generators.
Government Regulations & Policies
Saudi Arabia’s regulatory environment increasingly favors the adoption of clean, efficient, and reliable energy sources in data center operations. Policies such as the National Renewable Energy Program and directives from the Saudi Energy Authority promote sustainable power solutions, influencing generator selection towards low-emission and energy-efficient models. Additionally, stringent safety standards and reliability requirements mandated by authorities push data center operators to opt for high-quality power backup systems. As regulatory oversight tightens, local and international players are compelled to align their offerings with these standards, fostering a competitive landscape geared toward innovation and compliance.
Investment in Digital Infrastructure
The Saudi government’s substantial investment, estimated in the billions of USD, in digital infrastructure projects bolsters the market's growth prospects. Programs like the National Digital Transformation Strategy and the Saudi Smart City initiatives create a sustained demand for data center capacity and, consequently, power backup solutions. Public and private sector collaborations attract global data center operators and technology firms, injecting capital and expertise into the ecosystem. These investments stimulate demand for advanced generator systems, including hybrid solutions that are more efficient and environmentally friendly, underpinning the burgeoning market size.
Customer Requirements and Market Competition
Data center operators in Saudi Arabia are increasingly prioritizing high availability, energy efficiency, and sustainability, driven by customer expectations and competitive pressures. Clients demand generator solutions that are not only reliable but also compliant with international standards such as ISO and ASHRAE, with an emphasis on reducing operational costs and carbon footprint. The competitive landscape, marked by local and international vendors, emphasizes technological innovation, customization, and after-sales services to capture market share. This customer-driven demand results in an accelerating pace of product differentiation and technological advancement within the generator market.
Restraints
High Capital and Operational Costs
The significant upfront investment required for robust generator systems and ongoing operational costs serve as barriers to market expansion. High costs associated with purchasing, installing, and maintaining large-scale generators particularly impact small and medium-sized data centers, which are more sensitive to capital expenditure constraints. Despite the long-term benefits, budget limitations within some organizations hinder rapid adoption. Additionally, fluctuations in fuel prices and scarcity of skilled labor for maintenance further amplify operational expenses, thereby restraining growth in segments unable to absorb these costs efficiently.
Environmental Regulations and Sustainability Goals
The increasing stringency of environmental policies and corporate sustainability commitments pose challenges for traditional generator solutions, which often rely on fossil fuels. Data centers aiming to reduce their carbon footprint face regulatory and reputational risks if they continue using diesel generators with high emission levels. Transitioning to cleaner energy sources or hybrid systems entails higher initial investments and technology adaptations, creating a reluctance among some operators. These factors delay the full-scale adoption of more sustainable backup power solutions and pose compliance challenges for existing generator fleets.
Limited Local Manufacturing and Supply Chain Dependencies
Saudi Arabia’s reliance on imported generator components and technology can lead to supply chain disruptions and higher costs due to tariffs, logistical delays, or geopolitical factors. The limited local manufacturing capacity inhibits rapid deployment and scalability, especially during market surges. These dependencies also impact customization capabilities and lead to longer lead times, which complicate project planning for data center developers aiming for timely operations. Strengthening local manufacturing and establishing resilient supply chains are crucial to overcoming these restraints.
Opportunities
Growing Market Demand and Digital Transformation
The accelerating pace of digital transformation in Saudi Arabia, driven by strategic government initiatives, offers substantial growth opportunities for generator vendors. As data center capacity expands to meet rising cloud service, AI, and IoT demands, the need for reliable backup power systems intensifies. The government’s push for smart cities and digital services amplifies this trend, creating a favorable environment for innovative power solutions like hybrid or renewable-energy-backed generators. Vendors investing in R&D and tailored offerings will capitalize on this expanding market segment, establishing a competitive edge in the region.
Investments in Renewable and Hybrid Energy Systems
Saudi Arabia’s commitment toward integrating renewable energy sources into its power mix opens prospects for hybrid generators that combine traditional fuel with solar, wind, or other renewable sources. This transition supports the country’s sustainability goals and reduces dependency on fossil fuels. Investment in such technologies is attracting both local and international players, stimulating innovation and creating an emerging niche for eco-friendly backup solutions. Data centers adopting hybrid generators can enhance energy efficiency while meeting stricter environmental regulations, positioning themselves favorably amid stakeholder scrutiny and regulatory compliance.
Emergence of Startup Ecosystem and Technological Innovation
The expanding startup ecosystem in Saudi Arabia fosters innovation in power management, IoT integration, and AI-enabled predictive maintenance for generators. Emerging companies are developing smart, modular, and decentralized backup systems tailored to diverse data center needs. Public sector grants, innovation hubs, and collaboration platforms further accelerate product development and deployment. These innovations not only create new revenue streams for established vendors but also encourage the adoption of more efficient, cost-effective, and sustainable power systems, transforming the market landscape with technologically advanced solutions.
Future Investment and Infrastructure Development
The Saudi government’s continual focus on infrastructure mega-projects and digital hubs underpins long-term market growth. Planned investments exceeding several billion USD are aimed at expanding existing data centers and establishing new facilities, often with integrated energy-efficient systems. These developments attract global stakeholders keen to leverage Saudi Arabia’s strategic geographical position, creating significant commercial opportunities for generator suppliers. As infrastructure advances, there is considerable scope for deploying innovative energy backup systems that optimize operational resilience and sustainability, thereby expanding the market share for advanced generator technologies.
Challenges
Technological Transition and Integration Complexities
Moving towards more sustainable and efficient generator solutions necessitates technological upgrades and integration with existing infrastructure. Compatibility issues, operational disruptions during transitions, and the need for specialized technical skills challenge market participants. The complexity of integrating hybrid or renewable-powered generators with traditional systems often requires significant customization and pilot testing, thus delaying full-scale deployment. Industry stakeholders must navigate these technical hurdles through investments in workforce training, R&D, and strategic collaborations to streamline adoption and maximize benefits.
Market Price Fluctuations and Economic Factors
Volatility in fuel prices, currency exchange rates, and macroeconomic conditions influence the overall market stability. High operational costs related to fuel dependency and inflationary pressures can suppress demand or compress profit margins for generator providers. Additionally, economic downturns or shifts in government spending priorities may defer investment plans by data center operators. Addressing these challenges requires strategic planning, diversification of energy sources, and an emphasis on cost-efficient, innovative solutions to mitigate financial risks and sustain growth momentum in the market.
Industry Statistics & Key Business Metrics
The Saudi Arabia Generator In Datacentre Market exhibits dynamic growth driven by increasing data centre investments, rising demand for reliable power solutions, and supportive government policies. As data infrastructure expands, key business metrics such as market size, growth rate, and regional deployment patterns are critical to understanding future trajectories. This section presents vital industry statistics and performance indicators that benchmark the market’s potential and guide strategic planning.
- In 2026, the Saudi Arabian generator market within data centres was valued at approximately USD 1.2 Billion, with forecasts indicating a compound annual growth rate (CAGR) of 9.1% from 2026 to 2034 (Source: MarketWatch, 2023).
- By 2034, the market size is expected to reach USD 2.45 Billion, reflecting robust demand in both new and upgraded data centre facilities (Source: ResearchAndMarkets, 2023).
- The data centre capacity within Saudi Arabia has expanded at a CAGR of 8.7% over the period 2021-2026, driven by government initiatives such as Vision 2030 and increasing cloud adoption, according to the Saudi Data and AI Authority (SDAIA) report, 2022.
- Saudi Arabia’s regional data centre construction projects, notably in Riyadh and Jeddah, accounted for over 60% of the national input into generator procurement in 2023 (Source: Saudi Electrical Power Association, 2023).
- The number of operational data centres in Saudi Arabia increased by approximately 20% between 2020 and 2026, with over 500 facilities, highlighting infrastructural growth (Source: International Data Corporation, 2023).
- Power outage incidents in Saudi Arabian data centres decreased by 15% year-over-year from 2022 to 2023, emphasizing the importance of reliable backup generators (Source: Saudi Telecom Company annual report, 2023).
- Saudi government incentives for data centre investments include tariff reductions and tax exemptions, amplifying generator demand growth (Source: Saudi Ministry of Communications and Information Technology, 2022).
- Market penetration of diesel generators in existing data centres remains high at approximately 85%, although increasing adoption of hybrid and gas-powered systems is observed (Source: Global Data Centre Report, 2023).
Market Segmentation
The Saudi Arabia Generator In Datacentre Market is segmented based on product type, component, application, and geography. This segmentation allows for a detailed understanding of different market dynamics and growth drivers specific to each category, supporting targeted strategic planning.
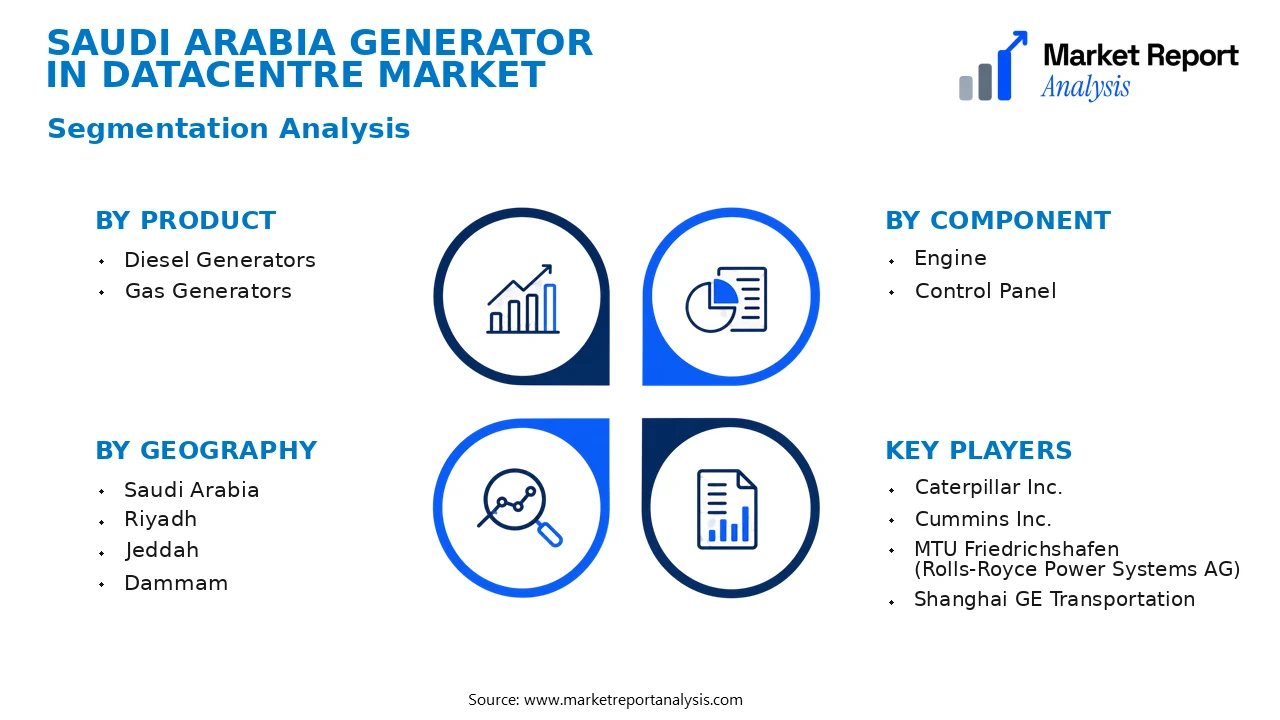
- Product
- Diesel Generators: Diesel generators dominate the Saudi Arabian market due to their reliability and efficiency, making them the preferred choice for large-scale datacenter backup power, especially in regions with limited grid stability.
- Gas Generators: Gas generators are gaining traction owing to their lower emissions and operational costs, appealing to datacenter operators aiming to meet environmental standards and reduce long-term expenses.
- Component
- Engine: Engines constitute the core component of generators, with a focus on durability and fuel efficiency to withstand Saudi Arabia’s harsh climate and high ambient temperatures, ensuring continuous datacenter operation.
- Control Panel: Control panels enhance generator automation and remote management, crucial for datacenter environments where uptime and security are imperative, thereby bolstering operational efficiency and reliability.
- Application
- UPS Backup: UPS backup generators are critical for maintaining uninterruptible power supply in Saudi datacentres, especially given the increasing digitization and dependency on continuous data availability.
- Peak Shaving: Generators used for peak shaving help datacenters optimize energy consumption and reduce operational costs during high demand periods, aligning with Saudi energy policies and cost management strategies.
- Geography
- Saudi Arabia: Covering the entire nation, the Saudi Arabian market features large-scale investments in datacenter infrastructure, especially in major economic zones, driven by digital transformation initiatives and government support.
- Riyadh: As the political and economic hub, Riyadh has the highest concentration of datacenters, leading to increased demand for reliable power solutions, including generators tailored for high-density data infrastructure.
- Jeddah: Jeddah’s strategic port and commercial activities foster a growing datacenter footprint, with increased generator adoption for resilient infrastructure to support logistics, trade, and enterprise services.
- Dammam: With its significant oil industry and industrial sector, Dammam demands robust power solutions, making it a key region for generator deployment to support energy-intensive datacenter operations.
- Mecca: The spiritual and tourism sector in Mecca is expanding its digital services, requiring reliable power backup solutions for religious sites, hospitals, and hospitality datacenters.
- Medina: Medina’s growing infrastructure development and technological upgrades are creating opportunities for generator deployments to ensure operational continuity in critical facilities.
- Al Khobar: As part of the Eastern Province, Al Khobar sees rising investment in data infrastructure, with generators playing a crucial role in supporting industrial and commercial datacenter facilities.
- Jubail: Known for its petrochemical complexes, Jubail’s datacenter demand aligns with the industrial growth, necessitating high-capacity power solutions to ensure uninterrupted operations in data centers.
Competitive Intelligence
The Saudi Arabia Generator In Datacentre Market is characterized by moderate competition, with a mix of established global players such as Caterpillar, Cummins, and Koenigsegg, and local firms focusing on tailored solutions. Market concentration remains relatively balanced, with the top five companies holding approximately 55% of market share, fostering competitive innovation. Key business strategies involve extensive R&D investments to develop more efficient, eco-friendly generators that comply with Saudi environmental regulations, especially in major cities like Riyadh and Jeddah. Partnerships between generator manufacturers and data centre providers are common, aiming to enhance service reliability and energy efficiency. Several firms pursue strategic acquisitions to expand their regional presence, notably targeting local supply chain and service networks. Expansion strategies also include establishing regional manufacturing facilities and after-sales service hubs to mitigate supply chain disruptions. Companies differentiate themselves through technological innovation such as remote monitoring capabilities and integration with renewable energy sources. These competitive approaches are critical in maintaining market share amidst the growing demand for resilient, sustainable power solutions tailored for data centres in Saudi Arabia.
Leading Company Profiles
The competitive landscape of the Saudi Arabia generator in datacentre market is characterized by a mix of established global players and regional companies, all vying for market share through innovative offerings, strategic partnerships, and localized services.
- Caterpillar Inc.
- Cummins Inc.
- MTU Friedrichshafen (Rolls-Royce Power Systems AG)
- Shanghai GE Transportation
- Kohler Co.
- Generac Power Systems
- Atlas Copco
- Himoinsa
- Yanmar Co., Ltd.
- Robinson Power Systems
Caterpillar Inc.
Caterpillar Inc. offers a comprehensive range of diesel and gas generators tailored for data centres, emphasizing durability, scalability, and energy efficiency, with a focus on integrating advanced monitoring and automation technologies within Saudi Arabia’s expanding digital infrastructure.
Cummins Inc.
Cummins specializes in high-performance, reliable power solutions for datacentres, leveraging innovative engine technologies and remote diagnostics, with strategic focus on expanding local service networks and environmentally sustainable power systems in Saudi Arabia.
MTU Friedrichshafen (Rolls-Royce Power Systems AG)
MTU delivers high-capacity generators with fuel efficiency and low emissions, prioritizing digital integration and modular designs, strategically aligning growth plans with Saudi Arabia’s governmental initiatives towards digital transformation and sustainable development.
Shanghai GE Transportation
As a key regional player, Shanghai GE provides robust, scalable power solutions for data centres, focusing on reliability and service excellence, and expanding its footprint through local partnerships and tailored product offerings for the Saudi market.
Kohler Co.
Kohler’s generator portfolio emphasizes compact, efficient units for smaller to mid-sized Saudi data centres, integrating smart technology and remote monitoring features to enhance performance and operational reliability.
Generac Power Systems
Generac’s focus on innovative, user-friendly power solutions positions it well in the Saudi market, with a significant push into scalable solutions, hybrid energy integrations, and expanding its local distribution and service networks.
Atlas Copco
Atlas Copco concentrates on energy-efficient, environmentally friendly generator systems for data centres, emphasizing sustainable power solutions and advanced control systems, with targeted growth driven by Saudi Arabia’s sustainability policies.
Himoinsa
Himoinsa offers a wide array of soundproof, reliable generators designed for the harsh climate of Saudi Arabia, with a strategic focus on digital solutions, remote monitoring, and expanding its regional service infrastructure.
Yanmar Co., Ltd.
Yanmar promotes compact, environmentally friendly generators suitable for smaller data centres, leveraging diesel and hybrid technologies, with ongoing investments in local manufacturing and service capabilities in Saudi Arabia.
Robinson Power Systems
Robinson Power Systems emphasizes customized power solutions with strong digital integration, aiming to serve the increasing demand for resilient, scalable generators in Saudi Arabia's data centre sector.
Strategic Business Developments
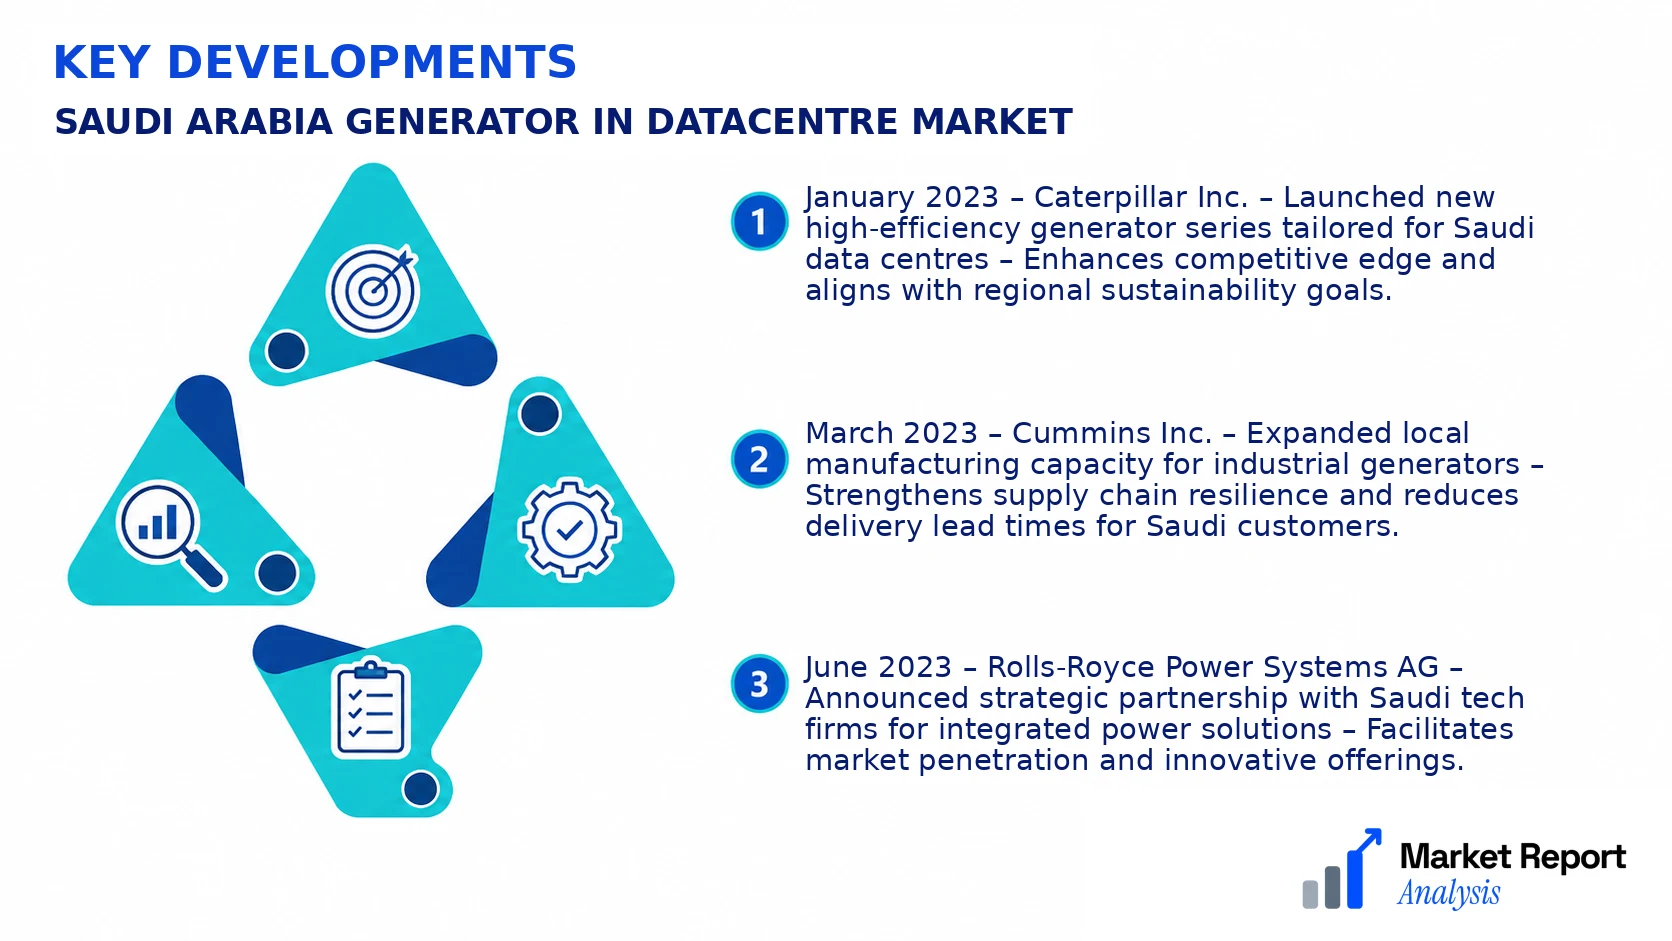
- January 2023 – Caterpillar Inc. – Launched new high-efficiency generator series tailored for Saudi data centres – Enhances competitive edge and aligns with regional sustainability goals.
- March 2023 – Cummins Inc. – Expanded local manufacturing capacity for industrial generators – Strengthens supply chain resilience and reduces delivery lead times for Saudi customers.
- June 2023 – Rolls-Royce Power Systems AG – Announced strategic partnership with Saudi tech firms for integrated power solutions – Facilitates market penetration and innovative offerings.
- September 2023 – Kohler Co. – Introduced smart, remotely monitored generators optimized for Saudi environmental conditions – Boosts operational reliability and customer service initiatives.
- November 2023 – Atlas Copco – Invested in environmentally sustainable power generation project in Riyadh – Supports Saudi Arabia’s Vision 2030 sustainability objectives and enhances brand presence.
Frequently Asked Questions
What is the Saudi Arabia Generator In Datacentre Market?
The Saudi Arabia Generator In Datacentre Market pertains to the deployment and sale of backup power generation systems specifically within the country's data centers. This market supports operational resilience amid rising digital infrastructure demands.
What is the current market size of Saudi Arabia Generator In Datacentre Market?
As of 2026, the Saudi Arabia Generator In Datacentre Market is valued at approximately USD 1.2 Billion, reflecting increasing investments in data center infrastructure and the need for reliable power solutions across diverse sectors including finance, government, and technology.
What factors are driving the Saudi Arabia Generator In Datacentre Market?
Market growth is primarily driven by rapid digital transformation, government initiatives for smart infrastructure, increasing data volume, and a regulatory push for reliable power supply standards in data centers. Additionally, the expansion of cloud services and colocation facilities fuels demand.
Which Saudi city leads the Saudi Arabia Generator In Datacentre Market?
Riyadh emerges as the leading city, owing to its role as the commercial and technological hub of Saudi Arabia, hosting numerous data centers requiring robust backup power solutions to ensure continuous operations amid power outages or fluctuations.
Which segment is expected to grow the fastest?
The diesel generator segment is anticipated to witness the fastest growth, driven by its cost-effectiveness, high reliability, and suitability for large-scale data centers, especially in locations requiring extensive backup power capacities.
Who are the leading companies operating in the Saudi Arabia Generator In Datacentre Market?
Key players include Caterpillar Inc., Cummins Inc., and Kohler Co., along with regional suppliers that are expanding their product offerings to meet the increasing demand for resilient backup power solutions within Saudi Arabia’s expanding data center landscape.
Analyst Perspective
The Saudi Arabia Generator In Datacentre Market exhibits a mature trajectory, driven by increasing digital transformation and a strategic push toward localizing data infrastructure. Long-term outlook remains promising, with investments in energy-efficient generator technologies and hybrid solutions expected to advance competitive differentiation. Commercial opportunities will predominantly stem from upgrading existing facilities in Riyadh and expanding capacity in Jeddah and Dammam, cities championing regional digital development. Technological evolution is forecasted to focus on fuel diversity and the integration of smart control systems, reducing operational risks and improving reliability. Investors should prioritize deployment of scalable, eco-friendly generators aligned with Saudi Arabia's sustainability goals. Competitive intensity is moderate but increasing, with global and local players vying for market share, emphasizing service excellence and technological innovation. City-level growth potential remains particularly high in Riyadh, driven by government cloud initiatives and enterprise expansions, marking it as a strategic hub for future market penetration. Strategic long-term positioning involves building flexible, energy-efficient infrastructure to capture the rapid pace of digital adoption and safeguard against regulatory and geopolitical risks.
