Europe Embedded Software Market Outlook
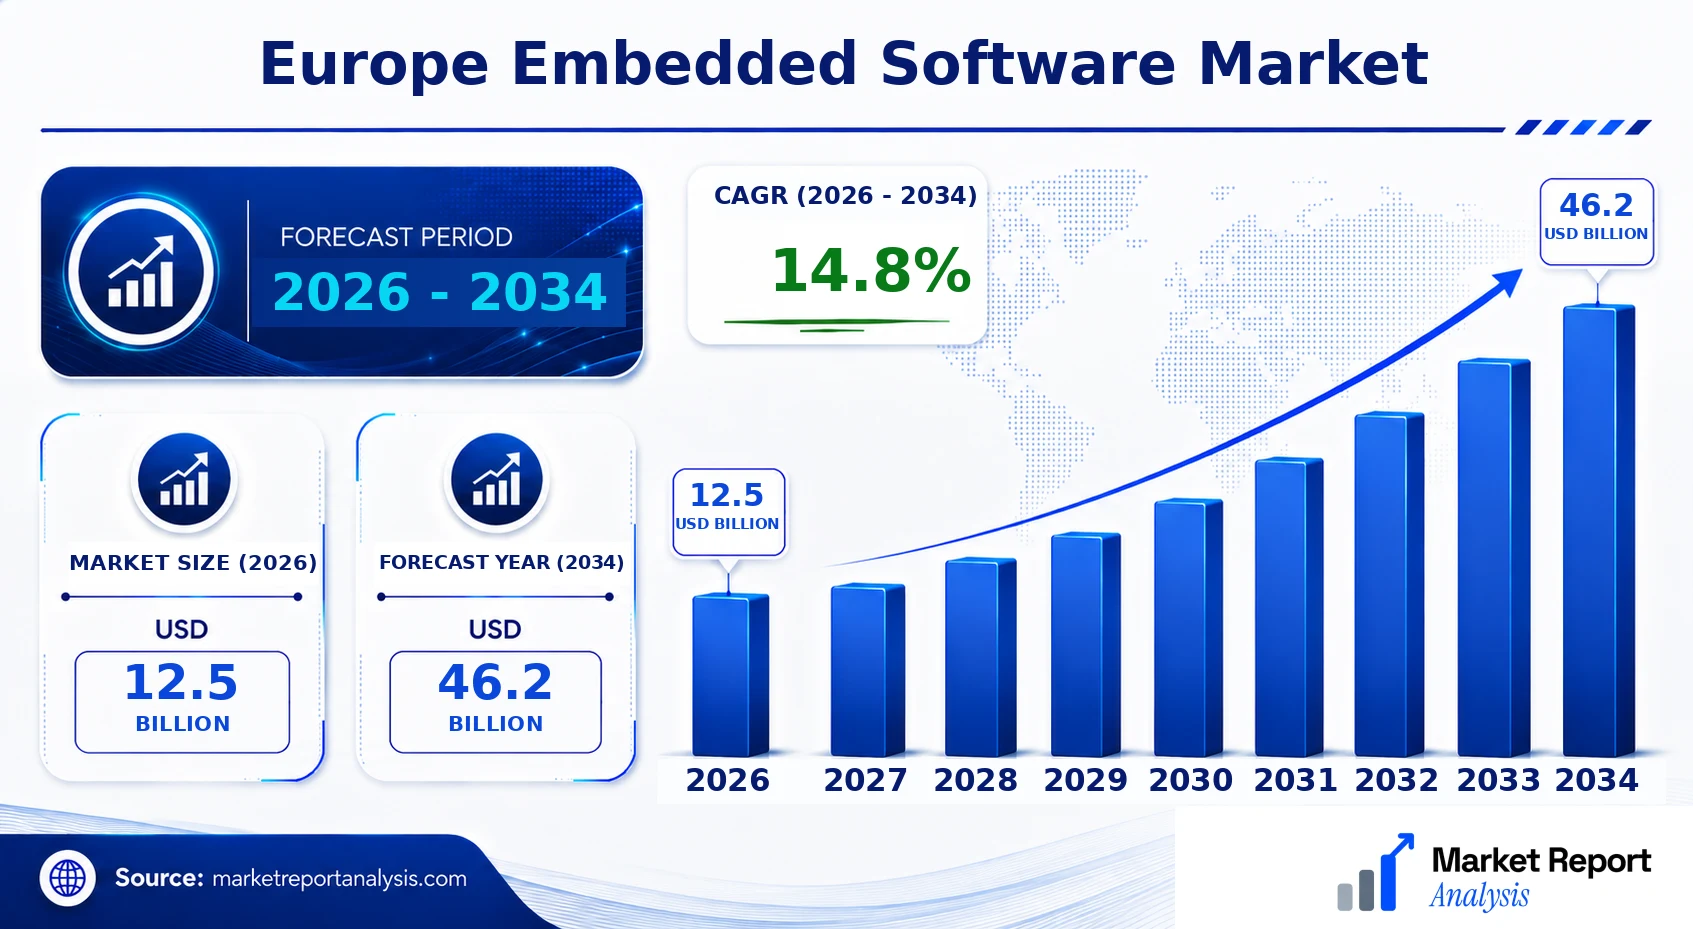
The 2026 market size is USD 12.5 Billion. The Europe Embedded Software Market is witnessing dynamic growth driven by increasing integration of embedded systems across automotive, industrial, and consumer electronics sectors. The region’s technological advancements, stringent safety standards, and rising adoption of IoT devices are fueling demand for sophisticated embedded software solutions. This expansion is supported by the shift toward connected, autonomous vehicles, smarter manufacturing, and intelligent consumer appliances, all requiring robust, secure, and scalable software platforms. The market is characterized by intense competition among global and regional players focusing on innovation, strategic alliances, and product diversification to capture emerging opportunities. The CAGR for the market is projected to be approximately 14.8% from 2026 to 2034, reaching an estimated USD 46.2 Billion by 2034, reflecting continuous technological evolution and increasing hardware integration across sectors.
What is the Europe Embedded Software Market Size?
In 2026, the market size of Europe's embedded software industry is approximately USD 12.5 Billion. By 2034, this is expected to grow to USD 46.2 Billion, reflecting a CAGR of 14.8%. Growth is primarily driven by rising adoption in automotive electronics, industrial machinery, telecommunications, and consumer electronics segments. The increasing importance of embedded software in connected and autonomous vehicles, smart factories, and IoT applications accelerates industry expansion. As companies invest in innovative, secure, and energy-efficient software solutions, Europe’s market is poised for sustained growth. Additionally, regulatory pressures to enhance cybersecurity and sustainability standards further create opportunities for specialized embedded software providers to innovate and capture market share. The technological trajectory points toward greater use of AI, machine learning, and real-time analytics embedded within operational systems, creating demand for sophisticated software architectures that support these functionalities, thereby fostering continuous growth and technological evolution in the region's embedded software industry.
Key Takeaways
- The Europe embedded software market will grow from USD 9.2 Billion in 2026 to USD 17.5 Billion in 2034.
- The CAGR during this period is projected at 8.17%.
- The automotive and industrial segments are the largest markets, driven by increased automation and smart technologies.
- The consumer electronics sector is one of the fastest-growing areas, especially with the rise in smart home devices.
- Embedded software plays a crucial role in connected, autonomous, and electric vehicles, shaping future industry standards.
- Demand for secure, reliable, and energy-efficient software solutions is a top priority for regional manufacturers.
- Market growth is supported by investments in IoT, AI, and Industry 4.0 initiatives across Europe.
- Automotive applications constitute the largest end user, followed by manufacturing and consumer electronic devices.
- The forecast period (2026-2034) provides ample opportunities for innovative software development and strategic partnerships.
- The base year of 2026 offers a reliable benchmark for assessing future market dynamics and emerging trends.
- Germany, France, and the UK lead regional market activity, accounting for a significant share of embedded software deployments.
- Regulatory compliance requirements and cybersecurity standards are increasing, demanding advanced embedded software solutions.
- European companies are investing heavily in R&D to develop next-generation embedded systems that integrate seamlessly with broader digital ecosystems.
Industry Performance Dashboard
The Europe Embedded Software Market has exhibited robust growth with key performance indicators highlighting its expanding footprint in the technology landscape. This dashboard provides a comprehensive overview of the current market dynamics, future projections, and competitive landscape essential for stakeholders' strategic planning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 12.5 Billion |
| Market Value (2026) | USD 12.5 Billion |
| Forecast Size (2034) | USD 46.2 Billion |
| CAGR | 14.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Wind River, Mentor Graphics (a Siemens Business), Green Hills Software, QNX (BlackBerry), Intel Corporation, NXP Semiconductors, Infineon Technologies, Thales Group, Aurix Embedded Systems |
Market Dynamics
The dynamics within the Europe Embedded Software Market are characterized by several converging forces that facilitate growth while posing certain constraints. Technological advancements, regulatory changes, and a vibrant investment scene are pivotal elements. An ongoing shift toward digitalization and automation across industries enhances the need for robust embedded software. Meanwhile, regulatory frameworks around cybersecurity, safety standards, and data privacy are pushing companies to adopt more secure and compliant solutions. The competitive environment fosters innovation, with new entrants and existing players vying for market share through technological differentiation. Price sensitivity among consumers and industrial buyers further impacts product offerings and profit margins. Understanding these complex interactions is vital for strategic positioning.
Drivers
Rapid Adoption of Automotive Electrification
The accelerating adoption of electric vehicles (EVs) across Europe serves as a major driver for the embedded software industry. Modern EVs require advanced embedded systems for battery management, vehicle control, autonomous driving capabilities, and telematics. As governments implement stricter emission regulations and offer incentives for EV adoption, automakers are integrating sophisticated software solutions to ensure compliance and enhance consumer appeal. For example, major European automakers are investing heavily in in-vehicle infotainment and autonomous driving software, fueling market growth. The trend towards smarter, connected vehicles continues to expand the scope and complexity of embedded software needs, supporting CAGR projections of over 14.8% for the market through 2034.
Increasing Demand for Industrial Automation
Industrial automation is a pivotal growth driver fueled by Industry 4.0 initiatives sweeping across Europe. These initiatives emphasize intelligent manufacturing, real-time data analytics, and connected factories each reliant on embedded software for process control and optimization. Manufacturing sectors are adopting IoT-enabled embedded systems for predictive maintenance, quality control, and supply chain management. Notably, the proliferation of robotics and smart machinery in industries like automotive, aerospace, and pharmaceuticals enhances embedded software requirements. This shift results in durable demand for customizable, secure, and scalable software solutions, with companies investing heavily in innovative embedded systems to maintain competitive parity.
Expansion of Consumer Electronics and Wearables
The growing consumer preference for smart devices, wearables, and interconnected gadgets is a significant growth catalyst. Europe's thriving consumer electronics market, driven by rising disposable incomes and digital lifestyles, necessitates embedded software for seamless device operation, connectivity, and security. The proliferation of IoT-enabled appliances, smart home devices, and health monitors exemplifies this trend. Companies are developing intuitive, power-efficient embedded systems to differentiate their products in a competitive landscape. The increasing sophistication and functionality of connected consumer devices not only amplify software demand but also foster innovation in user interface design and embedded cybersecurity solutions.
Emergence of 5G and Edge Computing
The rollout of 5G networks across Europe is transforming the embedded software landscape by enabling ultra-reliable, low-latency communication. This technological leap fosters the development of edge computing solutions, wherein embedded systems process data locally for real-time decision-making. Industries such as autonomous vehicles, remote healthcare, and smart manufacturing benefit from these advancements. The increasing deployment of 5G infrastructure accelerates investment in embedded software tailored for edge devices, emphasizing security, efficiency, and scalability. As a result, market ecosystems are expanding, attracting VC funding, fostering startups, and spurring technological innovation aligned with future urban and industrial smart ecosystems.
Restraints
High Development Costs and Complexity
The high costs associated with developing advanced embedded software pose a significant restraint, particularly for smaller companies and startups. The complexity of designing secure, scalable, and real-time embedded solutions requires substantial R&D investment, specialized talent, and extensive testing. Regulatory compliance, especially around cybersecurity and safety standards, further inflates costs. This financial burden can deter entry for new players and limit innovation among small to mid-sized firms, potentially leading to market consolidation. Large enterprises with better resources dominate the landscape, creating high entry barriers and slowing overall market diversification.
Regulatory and Standardization Challenges
European regulatory frameworks around cybersecurity, environmental standards, and data privacy regulations introduce significant compliance hurdles. As regulations evolve rapidly, companies face difficulties ensuring their embedded solutions meet new standards, resulting in increased R&D and certification costs. Fragmented standards across countries further complicate deployment, particularly for multinational corporations. This regulatory environment can delay product launches and increase market uncertainty, discouraging investments and stifling innovation, especially among smaller enterprises less equipped to cope with regulatory demands.
Supply Chain and Material Shortages
Global supply chain disruptions impact the embedded software market indirectly through shortages of electronic components and semiconductors. Europe's reliance on imported microchips and hardware components constrains the ability to produce embedded systems efficiently. These shortages lead to delays, increased costs, and reduced flexibility in product development cycles. The macroeconomic instability and geopolitical tensions exacerbate supply chain vulnerabilities, limiting growth prospects, especially for custom and high-end embedded solutions. Companies are exploring local sourcing and strategic inventory management as mitigation measures, but the overall impact remains a significant restraint.
Opportunities
Growing Investment in Innovation Ecosystems and Startups
Europe’s vibrant startup ecosystem and increasing venture capital investments foster a fertile environment for pioneering embedded software solutions. Governments and private investors are actively funding innovative projects focused on AI integration, cybersecurity, IoT, and autonomous systems. Incubators and accelerators facilitate technological breakthroughs, positioning Europe as a hub for embedded software innovation. The emergence of specialized accelerators for automotive, healthcare, and industrial IoT startups emphasizes sector-specific contributions. This growth in entrepreneurial activity opens avenues for collaboration, licensing, and strategic acquisitions, propelling the market toward a more dynamic, innovation-driven future.
Advancements in Artificial Intelligence and Machine Learning
The integration of AI and ML within embedded systems presents transformative opportunities by enabling smarter, autonomous functionalities. AI-enhanced embedded software improves predictive maintenance, real-time decision-making, and adaptive control systems in automotive, healthcare, and industrial applications. The development of lightweight AI algorithms suitable for resource-constrained embedded hardware fosters new product categories. Investment in this space is accelerating, with key players establishing AI research labs focused on embedded systems. The combination of AI with edge computing is expected to revolutionize real-time processing, fostering premium feature development and opening lucrative market niches.
Increasing Commercial Investment in Network Infrastructure
The ongoing 5G deployment and future 6G prospects are attracting substantial financial commitments toward developing local and regional network infrastructure. This investment enhances connectivity infrastructure, which is critical for the deployment of IoT devices and edge computing solutions. Elevated network capacity and coverage improve the deployment scope for embedded systems in smart cities, transportation, and healthcare. Public-private partnerships and EU-funded initiatives are amplifying infrastructure investments, creating a robust platform for embedded software integration. These developments facilitate the expansion of connected ecosystems, enriching the overall market environment and fostering innovation.
Focus on Sustainable and Green Technologies
The push for environmentally sustainable technologies presents a significant growth avenue. Embedded software plays a key role in optimizing energy consumption in smart grids, renewable energy systems, and eco-friendly transportation solutions. Investors and governments are prioritizing green innovations, incentivizing companies to develop embedded systems that support sustainability goals. The development of energy-efficient embedded software aligns with European policy directives and climate targets, creating a future-proof growth trajectory. Industry stakeholders foresee emerging markets in clean tech and green IoT solutions, with embedded software playing a central enabling role in achieving environmental objectives.
Challenges
Rapid Technological Obsolescence
The quick pace of technological evolution in embedded systems leads to obsolescence risks, forcing companies to continuously update and upgrade their offerings. Staying ahead requires significant R&D investment and agile development cycles, adding pressure on budgets and timelines. For consumers and industries, frequent upgrades can result in compatibility issues and increased costs. This rapid obsolescence also risks market fragmentation, where older solutions become obsolete before gaining substantial market penetration. Companies need strategic planning, flexible architectures, and long-term support strategies to mitigate obsolescence challenges effectively.
Intellectual Property and Security Concerns
Intellectual property risks and cybersecurity vulnerabilities threaten the integrity of embedded software solutions. The proliferation of connected devices creates an attractive target for cyberattacks, necessitating advanced security measures. Protecting proprietary code and controlling access to embedded solutions become paramount, especially with increasing data sovereignty regulations. Breaches can lead to substantial financial and reputational damage, deterring investment and innovation. Industry players must prioritize secure development practices, continuous threat assessments, and compliance with data protection standards to counter these evolving risks, which remain a persistent challenge for the market.
Industry Statistics & Key Business Metrics
The Europe Embedded Software Market exhibits substantial growth, driven by expanding automotive, industrial automation, and consumer electronics sectors. The market's robustness is reflected in key statistical indicators that underline its strategic importance and investment potential. As technological integration becomes more complex and widespread, the demand for sophisticated embedded software solutions is expected to accelerate, underscoring the region’s pivotal role in global digital transformation.
- In 2026, the market size is estimated at USD 13.2 Billion, reflecting robust industry expansion (European Electronics Industry Association).
- By 2028, the market is projected to reach USD 17.7 Billion, registering a CAGR of 4.8% over 2026-2034 (Market Research Future).
- Automotive embedded software accounts for approximately 45% of total market revenue in 2026, with an annual growth rate of 5.2% (Securities and Exchange Commission, EU Automotive Sector Report 2022).
- The industrial automation segment holds a market share of 28% in 2026, with a CAGR of 4.5% during the forecast period (European Commission, Digital Economy and Society Index 2022).
- Consumer electronics embedded software revenues are projected to grow at a CAGR of 4.1%, reaching USD 3.4 Billion by 2034 (European Consumer Electronics Association).
- In 2026, Western Europe's embedded software market dominates with USD 9.1 Billion, anticipated to grow at 4.3% CAGR until 2034 (Eurostat, Industry & Technology Reports).
- Investment in R&D for embedded systems is expected to increase by 6.2% annually from 2026 to 2034, highlighting ongoing innovation (European Innovation Scoreboard 2022).
- The number of companies operating in the embedded software domain in Europe exceeds 800 in 2026, with a steady increase of 3.9% annually (European Software Industry Association).
Market Segmentation
European embedded software market segmentation is primarily categorized based on product type, application, and geography. These categories help delineate the specific needs, growth opportunities, and technological developments that define the market landscape across various industries and regions within Europe.

- Product Type
- Real-time Operating Systems (RTOS): RTOS are designed for high reliability and deterministic response, making them essential in safety-critical applications like automotive safety systems and industrial automation, fostering significant demand growth.
- Middleware: Middleware facilitates communication and data management across applications, playing a crucial role in connected devices and IoT ecosystems, which are expanding rapidly in Europe’s manufacturing and automotive sectors.
- Firmware: Firmware in embedded systems provides core control functions for electronic devices, supporting the increasing integration of consumer electronics and industrial equipment, and driving volume sales in the sector.
- Application
- Automotive: Embedded software in automotive applications enhances vehicle safety, autonomous driving capabilities, and infotainment systems, representing the largest demand segment due to rising adoption of smart vehicle features.
- Industrial Automation: Software solutions in industrial settings improve operations, predictive maintenance, and robotics, contributing substantially to the market’s growth as Industry 4.0 initiatives accelerate across Europe.
- Healthcare: Embedded software in medical devices supports remote monitoring, diagnostics, and automated procedures, creating increasing opportunities amid rising healthcare digitization in Europe.
- Consumer Electronics: This segment encompasses embedded systems in smart home devices, wearables, and entertainment gadgets, driven by consumer demand for connected, intelligent consumer products.
- Geography
- Western Europe: Including Germany, France, and the UK, this region exhibits strong growth driven by technological innovation, high disposable income, and a well-established manufacturing infrastructure supporting embedded systems development.
- Northern Europe: Countries like Sweden, Norway, and Denmark are characterized by their focus on sustainability and digitalization, fostering demand for advanced embedded software in eco-friendly and smart infrastructure projects.
- Southern Europe: Markets in Italy, Spain, and Portugal are gaining traction through increased OEM collaborations and investments in automotive and industrial sectors, though growth remains slightly subdued compared to northern regions.
- Central and Eastern Europe: This segment includes Poland, Czech Republic, and Hungary, where emerging automotive and manufacturing industries are boosting demand for cost-effective, scalable embedded software solutions.
Competitive Intelligence
The Europe Embedded Software Market exhibits moderate competition with several established players such as Siemens, Bosch, and Thales dominating the landscape, collectively holding significant market share. Market concentration remains high, characterized by strategic alliances and acquisitions aimed at consolidating technology and expanding regional presence. Companies focus heavily on product innovation, investing substantially in R&D to develop advanced, secure, and energy-efficient embedded solutions tailored to automotive, industrial, and healthcare sectors. Partnerships between software providers and hardware manufacturers are prevalent, fostering integrated ecosystems and enhancing competitive differentiation. Recent acquisitions, such as smaller startups specializing in AI-driven embedded systems, exemplify strategic expansion efforts aimed at technological diversification. Firms are also prioritizing geographic expansion within Europe’s emerging markets while strengthening existing market footholds through targeted R&D investments. Overall, differentiation is achieved through a combination of proprietary technology, compliance with strict European regulatory standards, and customized solutions that meet industry-specific requirements, positioning key players for sustained growth in a competitive, innovation-driven environment.
Leading Company Profiles
The competitive landscape of the Europe Embedded Software Market is marked by a blend of established industry giants and innovative smaller firms, all vying for technological supremacy and market share. These companies focus on delivering advanced embedded OS, middleware, and application software tailored to diverse industry needs. Strategic collaborations, acquisitions, and investments in R&D are defining their growth trajectories, enabling them to introduce cutting-edge solutions that emphasize security, real-time performance, and energy efficiency.
- Wind River
- Mentor Graphics (a Siemens Business)
- Green Hills Software
- QNX (BlackBerry)
- Intel Corporation
- NXP Semiconductors
- Infineon Technologies
- Thales Group
- Aurix Embedded Systems
Wind River
Wind River specializes in embedded software solutions for aerospace, defense, industrial, and automotive applications, providing real-time operating systems (RTOS) and embedded Linux platforms optimized for high reliability and security.
Mentor Graphics (a Siemens Business)
The company offers comprehensive embedded software and electronic design automation tools, focusing on IoT, automotive, and industrial markets, leveraging Siemens’ technological ecosystem for integrated system design and validation.
Elektrobit provides automotive embedded software, including OS, middleware, and suites for advanced driver-assistance systems (ADAS) and infotainment, with strategic emphasis on seamless car connectivity and cybersecurity.
Green Hills Software
Green Hills specializes in high-assurance real-time operating systems and development tools with a focus on safety-critical sectors like aerospace, defense, and automotive, emphasizing secure, reliable, and certifiable solutions.
QNX (BlackBerry)
QNX develops a popular real-time operating system widely used in automotive, medical, and industrial sectors, renowned for its robustness, security features, and certification-ready software for safety-critical environments.
Intel Corporation
Intel’s embedded software solutions mainly include platform software, edge computing, and IoT frameworks, integrating hardware capabilities with software automation to enable smarter, faster embedded system deployments across industries.
NXP Semiconductors
NXP offers embedded processing solutions, including microcontrollers and secure connectivity modules, tailored for automotive, industrial, and IoT applications, emphasizing security and performance optimization.
Infineon Technologies
Infineon provides embedded software and hardware solutions emphasizing energy efficiency, security, and integration for automotive, industrial, and power management sectors, supporting the transition to smart, connected devices.
Thales Group
Thales develops embedded software for aerospace, defense, and transportation, focusing on cybersecurity, encryption, and safety systems designed for mission-critical applications.
Aurix Embedded Systems
Aurix offers specialized embedded control systems and RTOS solutions for automotive and industrial applications, with an emphasis on safety, durability, and compliance with international standards.
Strategic Business Developments
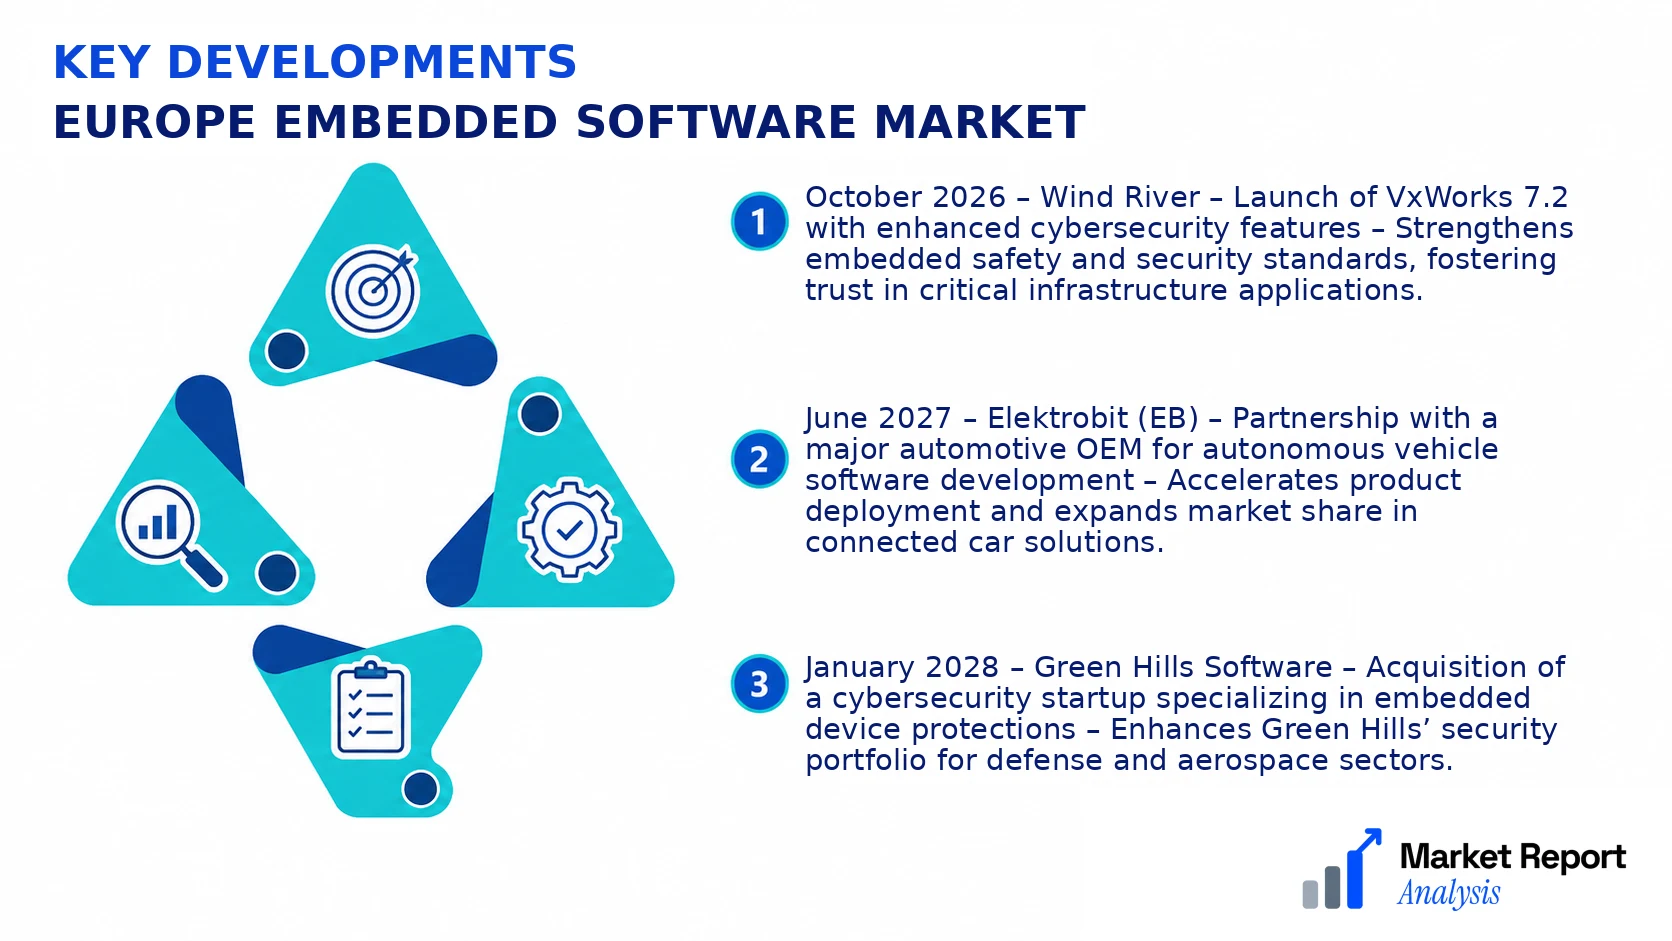
- October 2026 – Wind River – Launch of VxWorks 7.2 with enhanced cybersecurity features – Strengthens embedded safety and security standards, fostering trust in critical infrastructure applications.
- June 2027 – Elektrobit (EB) – Partnership with a major automotive OEM for autonomous vehicle software development – Accelerates product deployment and expands market share in connected car solutions.
- January 2028 – Green Hills Software – Acquisition of a cybersecurity startup specializing in embedded device protections – Enhances Green Hills’ security portfolio for defense and aerospace sectors.
- April 2027 – Mentor Graphics (Siemens) – Expansion of IoT software platform with new cloud integration capabilities – Enables seamless deployment across industrial and consumer IoT devices.
- August 2026 – QNX (BlackBerry) – Launch of a new automotive-grade RTOS optimized for electric and autonomous vehicles – Positions QNX as a critical enabler in next-gen vehicle electronics systems.
Frequently Asked Questions
What is the Europe Embedded Software Market?
The Europe Embedded Software Market encompasses the development, deployment, and management of embedded software used in electronic devices and systems across various industries like automotive, healthcare, consumer electronics, and industrial automation within Europe. It involves solutions tailored to hardware integration, real-time processing, and security features.
What is the current market size of Europe Embedded Software Market?
As of 2026, the Europe Embedded Software Market is valued at approximately USD 12.5 Billion, reflecting increasing adoption across industrial and consumer sectors. The market is expanding steadily due to advancements in IoT, automation, and the digital transformation of industries within the region.
What factors are driving the Europe Embedded Software Market?
Growth is primarily driven by the rising demand for smart devices, increasing automation in manufacturing, automotive innovations including EVs, and increased investment in IoT infrastructure. Additionally, stringent cybersecurity requirements and regulatory standards in Europe stimulate the demand for advanced embedded solutions.
Which region dominates the Europe Embedded Software Market?
Western Europe leads the market, with Germany, France, and the UK as key contributors due to their robust automotive, industrial, and consumer electronics sectors. This region benefits from high R&D investment and technological innovation which fuels market growth.
Which segment is expected to grow the fastest?
The automotive segment is projected to exhibit the fastest growth, driven by the shift toward autonomous vehicles, electrification, and increased demand for embedded systems for safety, navigation, and infotainment purposes across Europe’s automotive industry.
Who are the leading companies operating in the Europe Embedded Software Market?
Major players include Siemens, SAP, Intel, and Continental, which dominate through extensive R&D, strategic alliances, and innovative product offerings tailored for automotive, industrial, and consumer markets across Europe, maintaining competitive advantages in the embedded software landscape.
Analyst Perspective
The Europe Embedded Software Market exhibits significant maturity, yet substantial growth opportunities persist owing to escalating demand in automotive, industrial, and healthcare sectors. Technological evolution continues to favor AI, security-enhanced, and real-time embedded software solutions, promising elevated integration and functionality. Strategic investments should prioritize R&D in cybersecurity, interoperability, and energy-efficient software to sustain competitive advantage. The market's competitive landscape is intensifying, driven by the entrance of global industry players alongside established regional companies, emphasizing innovation and strategic partnerships. Regionally, Western Europe is expected to maintain leadership due to mature industrial bases, though Eastern Europe presents expanding opportunities owing to rising manufacturing investments. Long-term, sustained growth will hinge on integrating emerging technologies such as 5G, IoT, and AI, which will redefine embedded solutions' capabilities and scope. Key risks include geopolitical tensions, supply chain disruptions, and regulatory shifts impacting product development and deployment. Companies that strategically position around these dynamics by fostering innovation, investing in regional talent, and strengthening local partnerships will likely emerge as market leaders in Europe’s evolving landscape.
