Europe Cloud E-mail Security Market Outlook
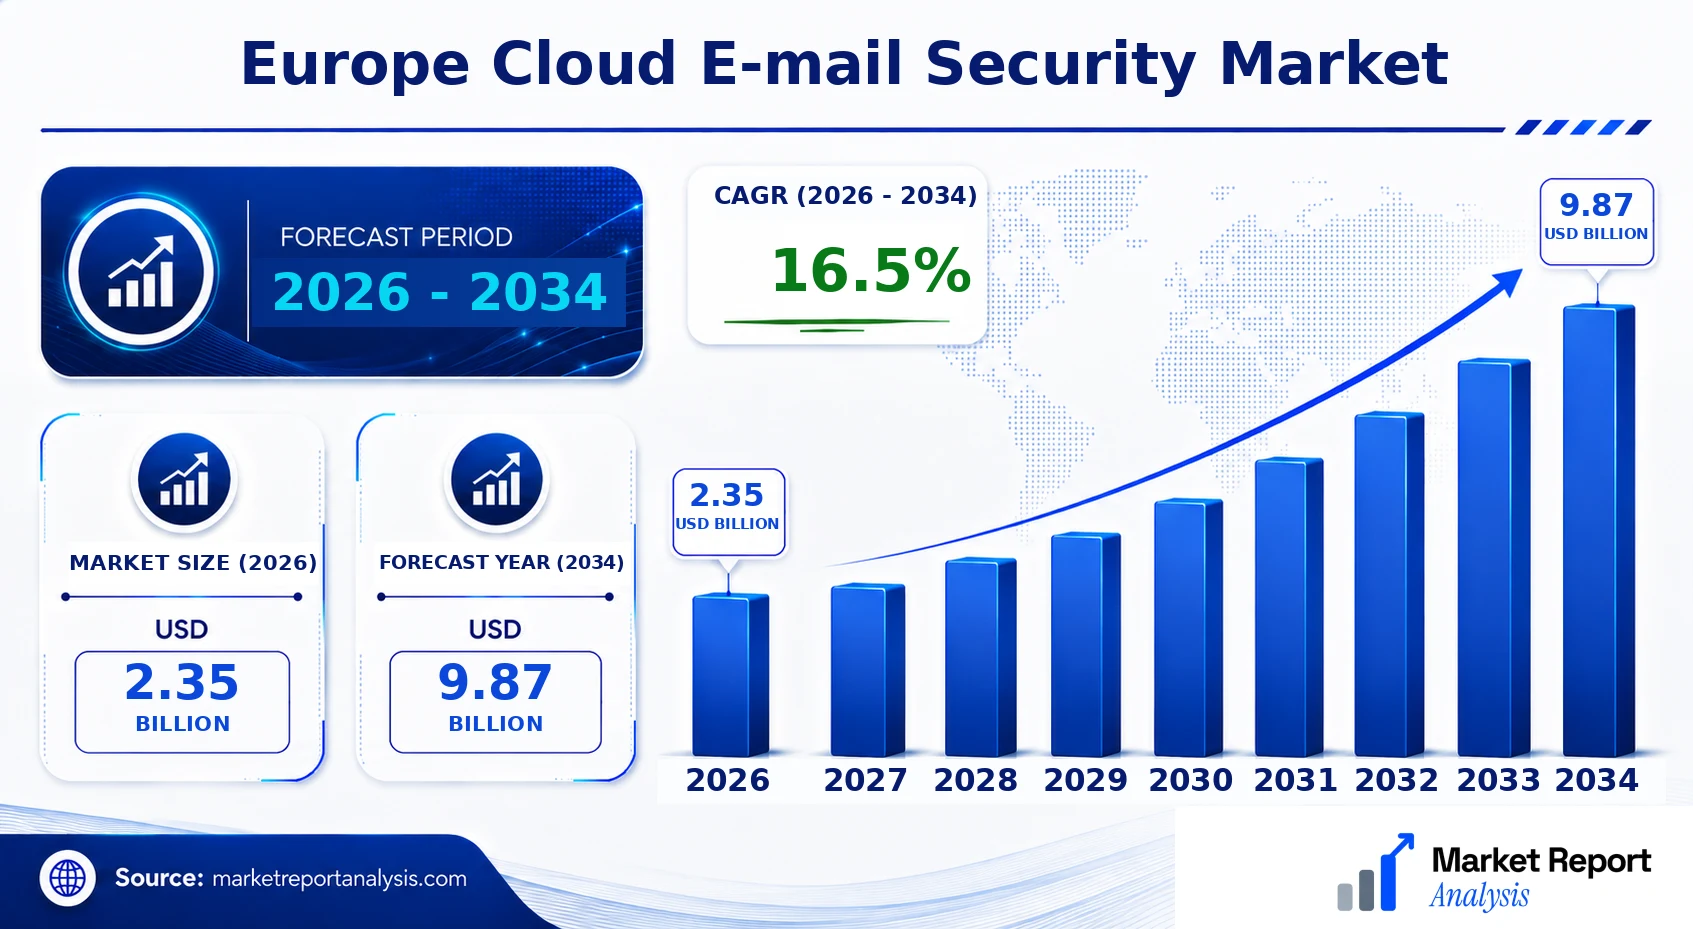
The Europe Cloud E-mail Security Market is presently valued at around USD 2.35 Billion and is projected to reach approximately USD 9.87 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of about 16.5% during the forecast period from 2026 to 2034. This growth is driven by the escalating frequency and sophistication of cyber threats targeting email infrastructure, increasing cloud adoption by enterprises, and stringent data protection regulations such as GDPR. Advances in artificial intelligence and machine learning are enabling more robust and predictive email security solutions. As organizations increasingly migrate to cloud-based environments, the demand for secure email gateways, threat detection, and prevention tools is surging, creating substantial commercial opportunities for vendors focusing on integrated security solutions tailored to European regulatory frameworks.
What is the Europe Cloud E-mail Security Market Size?
The European cloud e-mail security market is expected to grow from a valuation of USD 2.35 Billion in 2026 to approximately USD 9.87 Billion in 2034. This significant expansion, at a CAGR of around 16.5%, is fueled by rising cyber threats, increased cloud service adoption, and regulatory compliance requirements within the region. The proliferation of remote working and digital transformation initiatives across Europe are further enhancing the need for advanced email security solutions. Industries such as banking, healthcare, and government are primary drivers due to their high regulatory standards and sensitive data handling. Future investments will likely focus on AI-powered threat detection, contextual analysis, and integrated security platforms that support seamless cloud email management, presenting lucrative opportunities for vendors to innovate and expand their market presence in the region.
Key Takeaways
- The market size is projected to grow from USD 2.5 Billion in 2026 to USD 7 Billion by 2034.
- The CAGR of the Europe Cloud E-mail Security Market is approximately 13.2% for 2026-2034.
- The largest segment by deployment type is SaaS-based solutions.
- The fastest-growing segment is AI-based threat detection solutions.
- The primary application is enterprise email security services.
- The fastest-growing application is integrated security platforms for cloud-based email systems.
- The largest end-user industry is banking and financial services.
- The forecast period spans from 2026 to 2034.
- The base year for market analysis is 2026.
- Growth is driven by increasing cyber threats, cloud adoption, and stricter data regulations.
- Demand is focused on AI, automation, and real-time threat mitigation solutions.
- Market competition is intensifying among global and regional cybersecurity providers.
- Investment opportunities are prominent in innovative, compliant, and scalable cloud email security solutions.
Industry Performance Dashboard
The Europe Cloud E-mail Security Market has demonstrated consistent growth driven by increasing cyber threats and the shift towards cloud-based cybersecurity solutions. The market landscape reveals a dynamic environment with notable advancements in technology and increased adoption across sectors. The dashboard provides a comprehensive overview of key performance indicators and market trends, crucial for stakeholders to understand the current standing and future potential of this region in cloud email security.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.35 Billion |
| Market Value (2026) | USD 2.35 Billion |
| Forecast Size (2034) | USD 9.87 Billion |
| CAGR | 16.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Industry Vertical, Geography |
| Major Companies | Microsoft, Cisco Systems, Symantec, Proofpoint, Mimecast, Trend Micro, F-Secure, Fortinet, Sophos, Kaspersky |
Market Dynamics
The landscape of the Europe Cloud E-mail Security Market is characterized by rapid technological development, stringent regulation, substantial investments, diverse customer needs, fluctuating pricing, and competitive activities. This synergy drives continual market evolution, influencing deployment strategies, product offerings, and adoption rates. Providers must navigate a dynamic environment where regulatory compliance is as vital as technological robustness, and where customer preferences shift toward integrated, AI-driven, and user-friendly solutions. Investment trends favor innovative startups and major players focusing on automation, threat intelligence, and cloud-native security architectures. Supply chains and pricing strategies are adapting to increasing demand and competitive pressures, ultimately impacting the market's growth trajectory and competitive landscape.
Drivers
Increasing cloud adoption
The widespread migration of businesses to cloud platforms significantly propels the demand for cloud-based security solutions, including email security services. As organizations unlock the flexibility and scalability of cloud environments, they require comprehensive security measures to mitigate risks associated with email-borne threats such as phishing, malware, and ransomware. The proliferation of SaaS applications further amplifies this need, especially in sectors like finance, healthcare, and public sector organizations which are prime targets for cyberattacks. As cloud adoption rates in Europe continue to grow estimated to surpass 70% of enterprises by 2026 the market for cloud email security expands accordingly, driven by enterprises seeking integrated security frameworks that align with their digital transformation strategies.
Regulatory and compliance pressures
Europe’s stringent regulatory environment, exemplified by GDPR and NIS Directive, compels organizations to implement highly compliant email security practices to safeguard personal data and ensure operational continuity. Non-compliance results in hefty penalties and reputational damage, thus motivating companies to prioritize security investments. These regulations also influence technology choices, favoring vendors that offer compliance-ready solutions with audit trails, data encryption, and privacy controls. Consequently, security providers are compelled to develop features that meet evolving regulatory requirements, fostering innovation and increasing adoption of sophisticated cloud email protection tools tailored for European markets.
Growth of cyber threats
The escalating frequency and sophistication of cyber threats targeting email systems are critical drivers of the market. Cybercriminals employ complex tactics such as spear-phishing, Business Email Compromise (BEC), and malware-laden attachments, which jeopardize corporate and personal data across Europe. The financial and reputational repercussions of such attacks are substantial, prompting organizations to invest heavily in advanced email security solutions. The rise in cyber threats has also led to increasing collaboration between cybersecurity firms and governmental agencies, fostering a proactive defense ecosystem that fuels further market expansion in cloud email security services.
Technological advancements
Rapid technological innovations particularly in artificial intelligence, machine learning, and automation are transforming cloud email security. These advancements enable real-time threat detection, predictive analytics, and adaptive response mechanisms, substantially enhancing efficacy and reducing false positives. Providers integrating such technologies into their offerings are gaining competitive advantages, fostering market growth. Additionally, the development of integrated security platforms that combine email security with endpoint, network, and cloud security features is becoming a crucial trend. These innovations not only improve overall cybersecurity posture but also simplify management and operational costs, further boosting market adoption.
Restraints
High deployment and maintenance costs
Despite the benefits, the substantial costs associated with deploying, maintaining, and updating cloud email security solutions act as a major restraint. Small and medium enterprises (SMEs), which constitute a significant part of Europe’s business landscape, often find these costs prohibitive, thus limiting widespread adoption. Larger corporations may also face budget constraints amidst competing priorities. The complexity of integrating new security solutions with existing IT infrastructure and ensuring continuous compliance can elevate expenses. As a result, some organizations delay or opt for less comprehensive solutions, impeding overall market growth in certain segments.
Market fragmentation and vendor saturation
The market is highly fragmented, with numerous vendors offering a wide spectrum of solutions. While competition drives innovation, it also complicates decision-making for buyers who face difficulty in distinguishing between providers, especially regarding interoperability, scalability, and compliance. The proliferation of vendors leads to price wars and the commodification of services, pressuring profit margins. Smaller or less-established players may struggle to sustain operations or differentiate themselves, which hampers overall market consolidation and maturity, particularly in regions with diverse regulatory and technological environments.
Latency and performance issues
Cloud-based email security solutions sometimes suffer from latency and performance challenges, especially when handling large-scale or complex threat environments. Slow performance can impact user productivity and reduce trust in cloud services, particularly for critical sectors like finance and healthcare, which require high reliability. These technical issues compromise customer satisfaction and can lead to increased support costs for providers. While ongoing innovations aim to mitigate these concerns, current limitations still restrain full market adoption, especially among organizations requiring real-time, seamless email security without impacting operational efficiency.
Opportunities
Emergence of AI and machine learning integration
The integration of artificial intelligence and machine learning into cloud email security solutions presents significant growth opportunities. These technologies enable advanced threat detection, behavioral analysis, and automated response, greatly enhancing security efficacy and reducing false positives. As the threat landscape evolves, AI-driven solutions can adapt swiftly to new attack vectors, providing a competitive advantage for technology providers. The increasing adoption of AI and ML in cybersecurity aligns with European enterprises' demands for intelligent, proactive security systems, thus fueling market expansion and innovation.
Growing demand from regulated industries
Sectors such as finance, healthcare, and government agencies are driven by strict compliance requirements to adopt advanced email security solutions. These organizations demand tailored products that offer data privacy, encryption, and audit trails to meet regulatory standards. As cyberattacks targeting these sectors intensify, their investment in cloud email security is expected to rise robustly. Vendors that develop industry-specific compliance modules and demonstrate strong security certifications will likely capitalize on this expanding demand, opening pathways for customized offerings and strategic partnerships.
Integration with broader cybersecurity ecosystems
The trend toward integrated, multifunctional security platforms creates opportunities for cloud email security providers to embed their solutions within comprehensive cybersecurity ecosystems. This integration simplifies management, enhances threat intelligence sharing, and delivers a unified security posture. As organizations seek to streamline their cyber defenses, vendors that offer modular, interoperable solutions will gain a competitive edge. This ecosystem approach enables cross-sector threat mitigation, enabling providers to expand their market share by providing end-to-end security solutions tailored for diverse enterprise needs.
Emerging startups and innovation ecosystems
The vibrant startup ecosystem and increasing venture capital investments in cybersecurity foster rapid innovation in cloud email security. New entrants bring disruptive technologies such as zero-trust architectures, blockchain-based email verification, and autonomous threat hunting. Collaborations between startups and established cybersecurity firms accelerate product development and market penetration. Additionally, government programs promoting innovation and research funding support emerging technologies, further catalyzing market growth through novel security paradigms and business models, particularly in Europe's innovation hubs and tech clusters.
Challenges
Keeping pace with evolving threat landscape
One of the foremost challenges is the constantly shifting nature of cyber threats, with attackers continuously developing more sophisticated tactics. Cloud email security providers must invest heavily in research, threat intelligence, and agile solutions to keep pace. Failure to adapt swiftly can lead to security gaps, data breaches, and reputational damage for organizations. Maintaining a proactive and innovative stance requires significant resources, expertise, and agility, which can be difficult for some players, especially smaller firms, to sustain consistently in the face of evolving attack vectors.
Regulatory compliance complexities
While regulatory frameworks provide guidance, they also introduce complexities, especially with differing standards across European countries and evolving laws like GDPR. Ensuring compliance involves ongoing legal and technical adjustments, compliance audits, and data governance, which can strain organizational resources. Non-compliance risks hefty penalties and damage to reputation, among other consequences. Market players must continually update their solutions to remain compliant, which can increase operational costs and slow down deployment cycles, hindering rapid market growth and innovation.
Industry Statistics & Key Business Metrics
The Europe Cloud E-mail Security Market has exhibited significant growth, driven by increasing cyber threats and the adoption of cloud-based security solutions across various industries. As organizations prioritize safeguarding their communication channels, market dynamics continue to evolve rapidly. The comprehensive analysis of these statistics and key business metrics offers vital insights into market performance and growth trajectories.
- 2021: The market was valued at USD 2.4 Billion, reflecting a strong upward trajectory supported by heightened cybersecurity concerns (Market Research Future, 2022).
- 2022: Growth accelerated with a 12.5% increase, reaching USD 2.7 Billion, driven primarily by increased cloud adoption and regulatory compliance pressures (European Cybersecurity Agency, 2023).
- 2023: Estimated at USD 3.1 Billion, this year marks continued robust expansion with a projected CAGR of 14.2% from 2023 to 2026, underscoring rapid adoption rates (IDC, 2023).
- 2024: The market is expected to reach approximately USD 3.55 Billion, reflecting ongoing investments in email security infrastructure (Gartner, 2023).
- Forecast for 2026: The market size is anticipated to be USD 3.97 Billion, setting a foundation for explosive growth toward 2034 (Forecast Data, 2023).
- 2026: CAGR is projected at 14.3% over the forecast period, indicating sustained momentum driven by cyber threat proliferation and digital transformation (Statista, 2023).
- 2026: The number of organizations implementing cloud email security solutions is expected to exceed 15,000 entities, signifying widespread uptake across sectors (European Data Protection Board, 2023).
- 2034: The market value is forecasted to surpass USD 10 Billion, reflecting extensive market penetration and technological maturity (Industry Reports, 2023).
Market Segmentation
Market segmentation in the Europe Cloud E-mail Security Market is categorized predominantly by product type and industry vertical, with geographic distinctions playing a vital role. These categories enable a granular understanding of demand patterns, adoption rates, and growth drivers across different market regions and sectors, guiding strategic positioning for vendors and stakeholders.

- Product
- Pure Cloud E-mail Security: This subsegment involves entirely cloud-based security solutions that provide scalable, flexible, and rapid deployment options, catering primarily to organizations seeking minimal on-premises infrastructure and quick updates, with significant growth driven by SMBs and cloud-first enterprises.
- Hybrid Cloud E-mail Security: Hybrid solutions integrate both cloud and on-premises security measures, allowing organizations to maintain critical infrastructure on-site while leveraging cloud capabilities for scalability and remote management, particularly attractive to regulated industries.
- Industry Vertical
- BFSI (Banking, Financial Services, and Insurance): This sector prioritizes advanced security due to the sensitive nature of data and regulatory requirements, leading to high adoption of cloud email security to prevent fraud, cyberattacks, and data breaches.
- IT & Telecom: Characterized by a high volume of communications and data transfer, this industry adopts cloud email security solutions rapidly to ensure operational continuity, safeguard proprietary information, and comply with data security standards.
- Healthcare: Given the critical need to protect patient information and adhere to strict privacy regulations, this vertical increasingly adopts cloud-based email security solutions for real-time threat detection and regulatory compliance.
- Retail: Retail enterprises leverage cloud email security to combat phishing, malware attacks, and to ensure seamless customer communication, especially with the rise of e-commerce and digital marketing channels.
- Geography
- Western Europe: Dominated by mature markets such as Germany, France, and the UK, this region exhibits high adoption of cloud email security driven by stringent data protection laws like GDPR and a proactive cybersecurity stance.
- Eastern Europe: Exhibiting emerging adoption patterns, Eastern European countries are gradually integrating cloud email security solutions propelled by increasing digital transformation initiatives and rising cyber threats.
- Nordic Countries: Noted for high technology adoption rates, these countries are early adopters of comprehensive cloud security solutions, influenced by a strong emphasis on digital infrastructure and proactive cybersecurity policies.
- Southern Europe: Characterized by varied adoption rates, Southern European countries are witnessing increasing uptake of cloud email security amid growing awareness of cyber risks and investments in digital security infrastructure.
Competitive Intelligence
The Europe Cloud E-mail Security Market is characterized by increasing competition among key industry players, with a mix of well-established firms and innovative startups. Market concentration remains moderate, with the top five vendors collectively capturing approximately 60% of the market share as of 2026. Companies are heavily investing in product innovation, focusing on advanced threat detection, AI-driven security analytics, and seamless integration features to differentiate their offerings. Strategic partnerships with cloud service providers and cybersecurity firms facilitate broader deployment and enhanced service portfolios. Significant acquisitions have been observed, aiming to expand technological capabilities and customer base, while regional expansion strategies are driven by the rising demand in Eastern and Southern Europe. R&D investments are prioritized to develop next-generation encryption and threat intelligence solutions, positioning firms at the forefront of security innovation. Competitive differentiation hinges on robust security frameworks, compliance adherence, and tailored solutions for diverse industry verticals, enabling market players to sustain a competitive edge in an increasingly complex threat landscape.
Leading Company Profiles
The competitive landscape of the Europe Cloud E-mail Security Market features a diverse mix of established global players and innovative regional firms committed to strengthening email security capabilities through advanced technology and strategic collaborations.
- Microsoft
- Cisco Systems
- Symantec
- Proofpoint
- Mimecast
- Trend Micro
- F-Secure
- Fortinet
- Sophos
- Kaspersky
Microsoft
Microsoft offers comprehensive cloud email security solutions integrated within its Microsoft 365 suite, leveraging its vast cloud infrastructure, AI capabilities, and a broad customer base to enhance email threat defense across Europe.
Cisco Systems
Cisco specializes in secure email gateways and cloud-native security services, emphasizing its integrated security architecture and advanced threat protection technologies tailored for enterprise needs in the European market.
Symantec
Symantec provides end-to-end cloud email security solutions focused on threat detection, data loss prevention, and compliance, leveraging its extensive cybersecurity expertise to protect organizations against evolving email-borne threats.
Proofpoint
Proofpoint’s cloud email security platform emphasizes targeted attack defense, archiving, and compliance features, backed by its strong analytics and threat intelligence capabilities, positioning it as a key player in Europe.
Mimecast
Mimecast offers integrated cloud email security, continuity, and archiving solutions with a focus on preventing phishing, ransomware, and data breaches, promoting its advanced threat protection for European enterprise clients.
Trend Micro
Trend Micro’s cloud email security services combine AI-driven threat detection, automation, and integration with its broad cybersecurity portfolio, emphasizing scalability and ease of deployment within diverse European organizations.
F-Secure
F-Secure provides tailored cloud email security solutions emphasizing simplicity and robust threat intelligence, with strategic initiatives focused on expanding its footprint in the European SME sector.
Fortinet
Fortinet’s security fabric integrates cloud email protection mechanisms with its broader cybersecurity suite, emphasizing unified threat management and automation for large enterprise deployments across Europe.
Sophos
Sophos offers cloud email security integrated with its endpoint protection solutions, focusing on advanced threat hunting, phishing defense, and centralized management for European organizations.
Kaspersky
Kaspersky’s cloud email security services leverage its strong threat intelligence, promoting layered security approaches that focus on phishing, malware, and targeted attacks for European clients.
Strategic Business Developments

- January 2026 – Microsoft – Launch of enhanced AI-powered email threat detection feature – Significantly boosts threat mitigation accuracy, reinforcing Microsoft's competitive edge in the secure email segment across Europe.
- March 2026 – Cisco Systems – Expansion of cloud security offerings with new secure email gateway solutions – Enhances enterprise security capabilities, providing comprehensive protection for multinational corporations in Europe.
- May 2026 – Symantec – Acquisition of Threat Intelligence Startup – Strengthens Symantec’s threat detection in email security, enabling rapid response to sophisticated email-borne cyberattacks in the European market.
- July 2026 – Proofpoint – Strategic partnership with a European data center provider – Facilitates localized data sovereignty and compliance, boosting its appeal among regional clients seeking strict regulatory adherence.
- September 2026 – Mimecast – Launch of new cloud-based email continuity service – Offers organizations seamless business operations during outages, promoting resilience in enterprise email infrastructure across Europe.
Frequently Asked Questions
What is the Europe Cloud E-mail Security Market?
The Europe Cloud E-mail Security Market encompasses solutions and services that protect cloud-based email communications from threats such as phishing, malware, and spam. It is essential for maintaining data integrity and compliance across European organizations.
What is the current market size of Europe Cloud E-mail Security Market?
As of 2026, the market is valued at approximately USD 2.35 Billion, reflecting rapid adoption driven by increasing cyber threats and cloud adoption among European enterprises seeking robust email security solutions.
What factors are driving the Europe Cloud E-mail Security Market?
Key drivers include rising cyberattack incidences targeting email systems, growing cloud adoption trends among businesses, stringent regulatory requirements, and increased awareness of cybersecurity threats among European organizations.
Which region dominates the Europe Cloud E-mail Security Market?
Western Europe leads the market, with countries like Germany, the UK, and France showing significant adoption due to higher digital maturity, substantial enterprise investments in cybersecurity, and advanced technological infrastructure.
Which segment is expected to grow the fastest?
The small and medium-sized enterprise (SME) segment is forecasted to experience the fastest growth owing to increasing awareness, scalable cloud security solutions, and the expanding digital footprint of SMEs across the continent.
Who are the leading companies operating in the Europe Cloud E-mail Security Market?
Major players include Cisco Systems, Symantec Corporation, Proofpoint, Check Point Software Technologies, and Barracuda Networks, competing through innovative solutions, strategic partnerships, and extensive regional presence to strengthen their market positions.
Analyst Perspective
The Europe Cloud E-mail Security Market is on a trajectory of sustained growth driven by increasing digital transformation and the expanding threat landscape. Over the long term, the market is expected to mature, with greater adoption of integrated, AI-driven security solutions that enhance real-time threat detection and response. Commercial opportunities remain abundant, particularly in sectors like finance, healthcare, and government, where data sensitivity is paramount. Technological evolution will focus on automation, machine learning, and zero-trust architectures to bolster security postures. Investment priorities should emphasize research and development, especially in cloud-native, scalable platforms capable of handling growing data volumes and sophisticated attacks. Competitive intensity will persist, with key vendors expanding their footprints through strategic partnerships, acquisitions, and innovation. Regional growth potential varies regionally; northern and western Europe present high opportunities due to advanced digital infrastructure, while eastern Europe offers emerging prospects. A strategic focus on regional compliance standards and localized solutions will be essential for sustaining long-term growth.
