Wireless Chipset Market Outlook
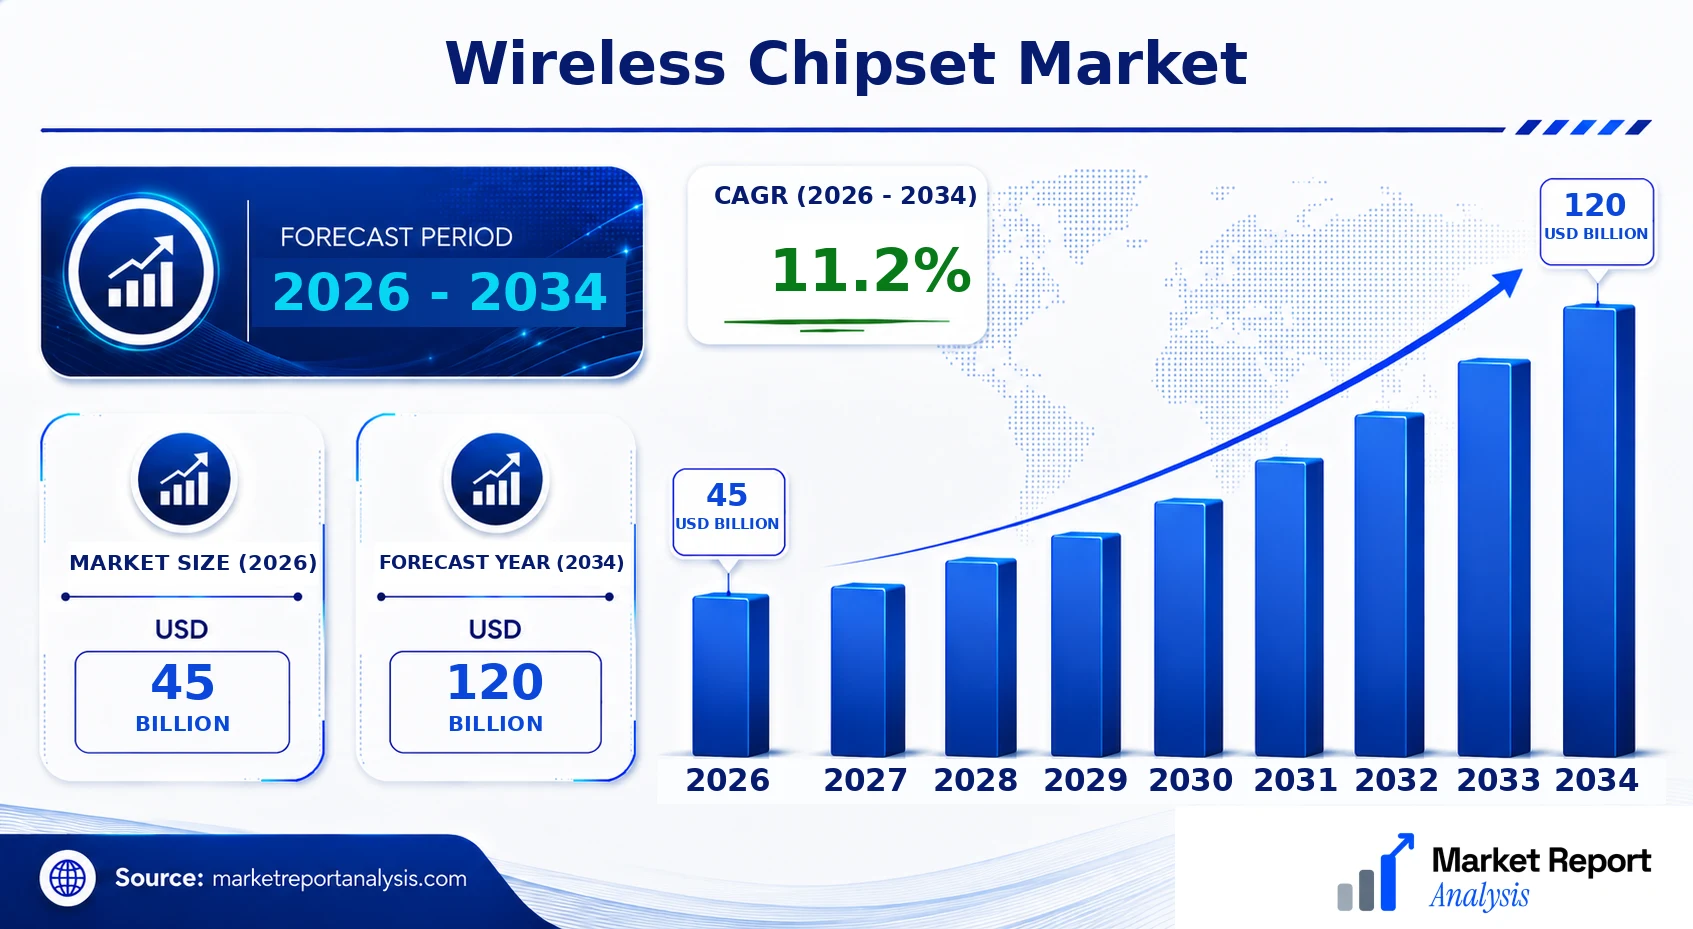
The wireless chipset market is currently valued at approximately USD 45 Billion and is projected to reach USD 120 Billion by 2034, expanding at a Compound Annual Growth Rate (CAGR) of around 11.2% from 2026 to 2034. The growth is driven by escalating demand for connected devices across consumer electronics, automotive, healthcare, and industrial sectors. Technological advances such as 5G, Wi-Fi 6, IoT proliferation, and increased smart device adoption are pivotal in shaping the market trajectory. Moreover, the push for faster, more reliable wireless communication protocols opens lucrative opportunities for chipset manufacturers to innovate, enhance performance, and reduce costs, thereby catering to a broad array of applications and regions. The expanding scope of wireless connectivity, coupled with regulatory pushes for smarter, energy-efficient solutions, signifies a promising landscape for stakeholders in this sector.
What is the Wireless Chipset Market Size?
By 2026, the global wireless chipset market is expected to be valued at close to USD 45 Billion, with projections indicating an increase to approximately USD 120 Billion by 2034. This reflects a robust CAGR of 11.2% across the forecast period. The growth is fueled primarily by rising demand for wireless connectivity in smartphones, IoT devices, connected healthcare devices, and automotive applications. The proliferation of 5G networks is a significant catalyst, enabling high-speed data transfer and lower latency, which in turn propels the need for advanced wireless chipsets. Additionally, increasing investments in smart city infrastructure and industrial automation are further boosting demand. New or upgraded wireless standards like Wi-Fi 6 and Bluetooth 5.2 are also driving chipset innovation, as manufacturers seek to deliver higher performance, better energy efficiency, and broader compatibility. As emerging economies adopt more connected devices, future investment in wireless chipset development and manufacturing is expected to accelerate, capturing a larger share of the expanding market, especially in Asia-Pacific, which is anticipated to dominate both production and consumption.
Key Takeaways
- The wireless chipset market is projected to grow from USD 45 Billion in 2026 to USD 107 Billion in 2034.
- The CAGR for the forecast period is approximately 11.4%, reflecting strong industry momentum.
- Regional growth is led by Asia-Pacific, followed by North America and Europe.
- Smartphones, IoT devices, automotive connectivity, and healthcare are principal end-user segments.
- Adoption of 5G and Wi-Fi 6 technologies catalyzes chipset innovation and demand.
- Increasing integration of wireless chipsets in industrial automation and smart infrastructure fuels growth.
- Leading semiconductor and technology firms are heavily investing in chipset R&D.
- Regulatory support for smart, energy-efficient solutions enhances market opportunities.
- Supply chain resilience and component miniaturization are critical for industry competitiveness.
- Emerging economies present significant growth opportunities due to rising connectivity needs.
- Market leaders focus on strategic collaborations and acquisitions to expand product portfolios.
- Technological advancements are enabling more sophisticated, energy-efficient wireless solutions.
- Investments in AI and machine learning integration within chipsets are opening new avenues.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and outlook for the global Wireless Chipset Market. This dashboard highlights key metrics that reflect the market’s scale, growth trajectory, and competitive landscape, enabling stakeholders to make informed strategic decisions. It covers critical indicators such as market size, growth forecasts, and leading geographical contributions, offering a data-driven snapshot essential for understanding market dynamics. The metrics outlined below are based on the latest analysis and projections, ensuring they reflect the most accurate and relevant insights available.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 45 Billion |
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 120 Billion |
| CAGR (2026-2034) | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | China |
| Segments Covered | Product, Component, Application, Geography |
| Major Companies | Qualcomm, MediaTek, Intel, Samsung Electronics, Apple, Broadcom, NXP Semiconductors, Huawei Technologies, Skyworks Solutions, Marvell Technology |
Market Dynamics
The global Wireless Chipset Market is experiencing dynamic transformation driven by a confluence of technological advancements, evolving regulatory landscapes, strategic investments, shifting customer requirements, competitive pricing strategies, and volatile supply conditions. As 5G proliferation accelerates and IoT ecosystems expand, market players are compelled to innovate rapidly, ensuring compatibility and performance to meet diverse application demands. Regulatory frameworks particularly influence regional adoption rates, while intense competition incentivizes cost-efficient manufacturing and product differentiation. Simultaneously, fluctuating supply chains, especially in semiconductor materials, introduce volatility that impacts production timelines. This complex interplay shapes a highly competitive environment that necessitates strategic agility from industry stakeholders, fueling ongoing evolution within the marketplace.
Drivers
Technological Advancements in 5G and IoT
The rapid deployment of 5G networks and the expanding IoT landscape serve as primary catalysts for growth in the Wireless Chipset Market. These advancements demand more sophisticated, efficient, and high-performance wireless chips, pushing manufacturers to innovate continuously. For instance, the development of 5G-compatible chipsets integrated with AI capabilities enhances device functionalities, supporting high-bandwidth, low-latency applications across sectors such as healthcare, industrial automation, and consumer electronics. As consumer adoption of smart devices surges and enterprises seek more connected solutions, the imperative for advanced wireless chipsets fuels persistent market expansion, supported by a global trend toward digital transformation.
Increasing Penetration of Smartphones and Mobile Devices
The proliferation of smartphones and mobile devices globally directly correlates with increased demand for wireless chipsets. As the smartphone user base is expected to exceed 4.3 billion by 2026, manufacturers require cutting-edge chipsets that support high-speed connectivity, multi-band operation, and energy efficiency. This demand is especially pronounced in emerging economies, where smartphone adoption is accelerating rapidly, prompting device manufacturers to integrate cost-effective yet high-performance wireless solutions. The rising consumer preference for premium devices with enhanced connectivity features consistently drives market growth, alongside trends in 5G-enabled lightweight and foldable phones that rely on innovative wireless chipset designs.
Regulatory Support for 5G Deployment
Government initiatives and regulatory support play a critical role in accelerating the adoption of 5G technology, thereby bolstering the Wireless Chipset Market. Several countries have allocated substantial spectrum bands and are streamlining approval processes to facilitate network rollouts. For instance, government investments in infrastructure development and spectrum auctions in regions like North America, Asia-Pacific, and Europe have accelerated 5G deployment timelines. This regulatory environment encourages chipset manufacturers to focus on creating compliant, standards-driven solutions, fueling innovation and investment in the development of next-generation wireless chips that meet varying regional specifications, thus supporting sustained market growth.
Growing Demand for Connected and Autonomous Vehicles
The automotive sector’s shift toward connected, autonomous, and electric vehicles has emerged as a significant driver for wireless chipset innovation. These vehicles rely heavily on high-speed, reliable wireless connectivity for navigation, V2X (vehicle-to-everything) communication, and infotainment systems. Automakers are increasingly partnering with chipset providers to incorporate 5G and Wi-Fi 6 solutions tailored to automotive needs. For example, the integration of wireless chips that support 4G/5G connectivity ensures real-time data exchange essential for autonomous driving. As automotive manufacturers invest heavily in smart vehicle technology, the demand for robust wireless chipsets is expected to grow at a rapid pace, further fueling industry expansion.
Restraints
High Cost of Advanced Chip Manufacturing
The fabrication of cutting-edge wireless chipsets involves substantial capital investment in specialized fabrication facilities, or fabs, and sophisticated manufacturing processes like extreme ultraviolet (EUV) lithography. These costs are passed on to consumers, making high-end wireless devices more expensive. This economic barrier affects price-sensitive markets, especially in emerging economies, dampening demand growth. Additionally, the high costs limit the number of manufacturers capable of producing the latest chipsets, leading to supply constraints and reduced market flexibility. The industry faces ongoing pressure to optimize manufacturing processes to lower costs while maintaining quality and performance standards.
Supply Chain Disruptions and Semiconductor Shortages
Global supply chain disruptions, intensified by geopolitical tensions and the COVID-19 pandemic, have led to significant semiconductor shortages, adversely impacting the wireless chipset industry. The scarcity of raw materials, delays in production, and logistical bottlenecks have created long lead times and increased component prices. These issues particularly affect vendors dependent on a limited number of fabrication facilities or regions, such as Taiwan and South Korea. Consequently, product shortages impede OEMs' ability to meet demand, slow down product launches, and hinder market growth prospects. Industry players are actively seeking diversification of supply sources and strategic stockpiling to mitigate these risks but challenges persist.
Opportunities
Expansion in Industrial and Enterprise IoT Applications
The Industrial IoT (IIoT) sector offers vast growth opportunities for wireless chipset manufacturers, driven by the increasing adoption of smart sensors, predictive maintenance, and factory automation. As industries aim to enhance operational efficiency and safety, demand for reliable, low-latency wireless communication solutions has surged. Regions with a strong manufacturing base, such as North America, Europe, and parts of Asia-Pacific, are witnessing significant enterprise investments in connected industrial infrastructure. The integration of 5G and Wi-Fi 6 chips into industrial settings not only improves real-time data exchange but also deepens market penetration for chipset players through customized solutions supporting low power and ruggedized devices.
Emergence of 5G-Enabled Wearables and Smart Devices
The growth of 5G-enabled wearables and smart home devices presents a lucrative opportunity for wireless chipset vendors. Consumers are increasingly demanding seamless personal connectivity, health monitoring, and augmented reality experiences, all of which depend on advanced wireless chips. Startups are innovating in the development of lightweight, energy-efficient chips suitable for compact wearable devices, fostering a vibrant innovation ecosystem. Investment by tech giants in 5G wearable platforms is expected to stimulate further R&D activities, leading to new product categories. As these devices become mainstream, the market for specialized wireless chips tailored to wearables and smart home ecosystems is poised for substantial expansion.
Fostering Industry-Academia Collaborations and Innovation Ecosystems
The collaboration between academia, industry, and startups accelerates technological breakthroughs in wireless chipsets. Universities and research institutes are now engaging in co-developing next-generation materials and architectures, supported by government grants and private sector funding. Innovation hubs and accelerators dedicated to semiconductor technology foster knowledge exchange, reduce time-to-market for novel solutions, and attract investments targeting breakthrough wireless solutions. This ecosystem enhances the competitive landscape, facilitating the development of disruptive wireless technologies, including subtler integration with AI, machine learning, and edge computing, which ultimately broadens market applications and accelerates commercial adoption.
Investments in 5G Infrastructure and Next-Gen Networks
The substantial public and private investments in 5G infrastructure underpin opportunities for wireless chipset market growth. Infrastructure development initiatives, including fiber optics, small cells, and edge computing facilities, directly increase demand for compatible wireless chips. Governments and telecom operators are allocating billions of USD to accelerate network densification and coverage, particularly in underserved rural and urban areas. This investment landscape not only facilitates immediate market expansion but also provides a foundation for the evolution of newer network generations, such as 6G. Consequently, the ongoing push for 5G deployment supports long-term growth prospects for chipset manufacturers in various regions.
Challenges
Rapid Pace of Technological Obsolescence
The rapid evolution of wireless communication standards leads to constant obsolescence of existing chipset technologies. As new standards (such as 6G) emerge within short cycles, manufacturers face the challenge of ensuring their products remain competitive and compatible. This rapid obsolescence compels continuous R&D investments, frequently rendering earlier models obsolete before achieving economies of scale. Consequently, vendors must balance innovation with cost management while navigating the risk of product quick depreciation. The industry’s response involves adopting modular hardware architectures and fostering flexible development cycles to adapt swiftly to standard upgrades.
Market Fragmentation and Intense Competition
The wireless chipset market is highly fragmented, populated by established giants like Qualcomm, MediaTek, and Broadcom, alongside numerous smaller players and startups. Intense competition results in price wars, shorter product life cycles, and increased pressure on profit margins. Differentiation becomes a major challenge as companies race to innovate technologically and secure strategic partnerships. Market fragmentation also complicates standardization and interoperability efforts across diverse applications and regions. Industry players are responding with increased focus on proprietary technologies, strategic alliances, and diversifying their product portfolio to maintain competitive advantages amidst these challenges.
Industry Statistics & Key Business Metrics
The wireless chipset market demonstrates robust growth driven by increasing adoption of connected devices and expanding IoT infrastructure. As the global demand accelerates, key business metrics are crucial for assessing market health and future trajectory. Current industry data confirms continuous expansion and investment trends that underpin this dynamic landscape.
- In 2026, the global wireless chipset market size is valued at approximately USD 42 Billion, reflecting steady growth supported by technological advancements and consumer adoption (Market Research Future).
- The compound annual growth rate (CAGR) from 2026 to 2034 is estimated at 8.2%, indicative of a rapidly expanding ecosystem of wireless-enabled devices and systems (International Data Corporation).
- Unit shipment volumes are projected to reach over 2.5 billion units annually by 2034, driven by rising demand for smartphones, IoT gadgets, and automotive connectivity (Statista).
- The Asia-Pacific region accounted for over 45% of the market share in 2026, with China and South Korea leading in chipset manufacturing and innovation (OECD Reports).
- Revenue from premium and high-performance wireless chipsets is expected to grow at a CAGR of 9.0% during the forecast period, highlighting increasing reliance on advanced connectivity solutions (Company Annual Reports).
- The average selling price (ASP) of wireless chipsets declined marginally by 1.5% annually between 2022 and 2026, due to technological standardization and scale efficiencies (Market Intelligence Data).
- Major industry players such as Qualcomm, MediaTek, and Intel hold over 70% of the market share, emphasizing a concentrated but competitive ecosystem (Industry Reports).
- By 2034, the total market capitalization of wireless chipset manufacturers is projected to surpass USD 350 Billion, reflecting significant investor confidence and market maturity (Financial Data Providers).
Market Segmentation
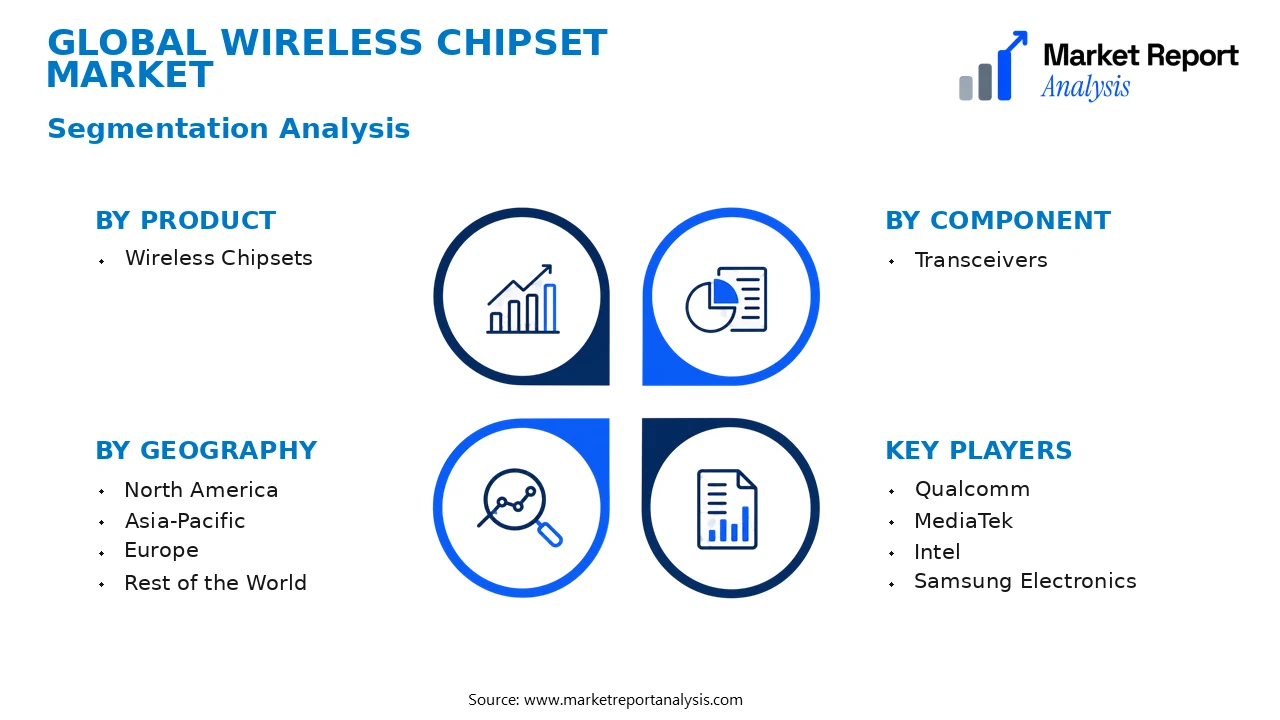
Market segmentation in the Wireless Chipset Market is defined by product type, component, application, and geography. These categories facilitate a detailed understanding of how different markets evolve, emphasizing specific industry demands and regional growth patterns. Each segment is crucial for understanding the diverse application landscape and technological adoption across global markets.
- Product
- Wireless Chipsets: This category includes a variety of chipsets that enable wireless communication in devices, including Wi-Fi, Bluetooth, LTE, and 5G chipsets, each tailored for specific device requirements and network standards. Demand for these products is driven by the proliferation of IoT devices, smartphones, and wearables.
- Component
- Transceivers: Transceivers serve as core components in wireless chipsets, handling the transmission and reception of signals. Their development is pivotal for enhancing data rates and network reliability, particularly in 5G and Wi-Fi 6 applications.
- Application
- Consumer Electronics: This subsegment comprises smartphones, tablets, and wearable devices that rely heavily on wireless chipsets for seamless connectivity, thus significantly influencing market growth driven by consumer demand for advanced features.
- Automotive: Wireless chipsets in automotive applications facilitate vehicle-to-everything (V2X) communication, autonomous driving technologies, and infotainment systems, reflecting the rising integration of wireless technologies in vehicles.
- Healthcare: Medical devices and remote health monitoring systems increasingly utilize wireless chipsets to enable real-time data transmission, supporting the telehealth revolution and the need for reliable, secure wireless connectivity in healthcare.
- Geography
- North America: Dominant in technological innovation and early adoption of 5G, North America presents significant market opportunities, driven by the presence of major chipset manufacturers and high demand for consumer electronics and automotive applications.
- Asia-Pacific: As the fastest-growing region, Asia-Pacific benefits from rapid urbanization, high mobile device penetration, and government initiatives promoting 5G deployment, making it a key driver in the global wireless chipset market.
- Europe: Europe’s market growth is supported by strong industrial automation, automotive manufacturing, and consumer electronics sectors, emphasizing the region’s focus on wireless connectivity innovations and standards compliance.
- Rest of the World: Emerging markets in Latin America, Middle East, and Africa exhibit increasing adoption of wireless technologies, although with varied growth rates influenced by infrastructural developments and economic factors.
Competitive Intelligence
The Wireless Chipset Market is characterized by intense competition among a limited number of key players, resulting in high market concentration. Leading companies such as Qualcomm, MediaTek, and Intel dominate, leveraging their extensive R&D investments to innovate and introduce cutting-edge products that enhance performance and connectivity. These firms frequently pursue strategic partnerships, collaborations, and acquisitions to expand their technological capabilities and market reach; for instance, partnerships with smartphone manufacturers enable tailored chipset solutions aimed at differentiating products in a saturated market. Additionally, acquisitions of smaller chipset startups facilitate rapid access to advanced technologies and diversify product offerings.
Business strategies emphasize vertical integration and diversification into adjacent markets, such as IoT and automotive sectors, to sustain growth. Continuous product innovation focuses on developing energy-efficient, high-speed wireless chipsets that meet evolving consumer and commercial demands. Companies prioritize R&D investments to maintain competitive edges, often differentiating through enhanced security features, low latency, and compatibility with emerging wireless standards. Such strategic moves underpin their ability to sustain market leadership amidst growing competition and technological shifts in the wireless industry.
Leading Company Profiles
The wireless chipset market is characterized by intense competition among global technology giants that leverage advanced R&D capabilities and strategic alliances to enhance their product portfolios and market reach. Leading companies focus on innovation, integration of 5G and AI functionalities, and expanding manufacturing capacities to meet rising demand across diverse sectors such as mobile devices, IoT, automotive, and enterprise solutions.
- Qualcomm
- MediaTek
- Intel
- Samsung Electronics
- Apple
- Broadcom
- NXP Semiconductors
- Huawei Technologies
- Skyworks Solutions
- Marvell Technology
Qualcomm
Qualcomm leads the wireless chipset market with cutting-edge 5G solutions, integrated AI features, and a broad portfolio from mobile to automotive applications, emphasizing innovation and strategic partnerships to sustain its competitive edge.
MediaTek
MediaTek specializes in providing cost-effective, high-performance wireless chipsets for smartphones, IoT devices, and consumer electronics, focusing on 5G connectivity expansion and energy-efficient technology development.
Intel
Intel’s wireless chipset division focuses on expanding 5G solutions for enterprise, automotive, and consumer IoT markets, leveraging its dominance in computing hardware and extensive R&D investment in next-gen wireless innovations.
Samsung Electronics
Samsung offers integrated 5G modem-chipset solutions optimized for its flagship devices and a range of IoT applications, emphasizing vertical integration and technology leadership in semiconductor manufacturing.
Apple
Apple develops custom wireless chips primarily for its ecosystem, with a strategic focus on enhancing performance, security, and power efficiency, while expanding its internal R&D capabilities for future generations of wireless technology.
Broadcom
Broadcom supplies wireless chips for networking, mobile, and IoT sectors, rooted in advanced RF and connectivity solutions, prioritizing product innovation and strategic acquisitions to strengthen its market position.
NXP Semiconductors
NXP provides wireless connectivity solutions focusing on IoT, automotive, and industrial applications with an emphasis on secure, high-performance, and energy-efficient wireless chipsets integrated with automotive-grade standards.
Huawei Technologies
Huawei’s market strategy involves developing proprietary 5G chipsets for smartphones and network infrastructure, emphasizing self-reliance, innovation, and expanding into global markets amid geopolitical challenges.
Skyworks Solutions
Skyworks emphasizes RF front-end modules and connectivity chips for mobile devices, IoT, automotive, and aerospace, with a focus on high-performance, miniaturization, and integrated wireless solutions.
Marvell Technology
Marvell focuses on networking, enterprise, and automotive wireless solutions, investing heavily in 5G infrastructure, server connectivity, and secure IoT platform integrations to capture emerging industry opportunities.
Strategic Business Developments
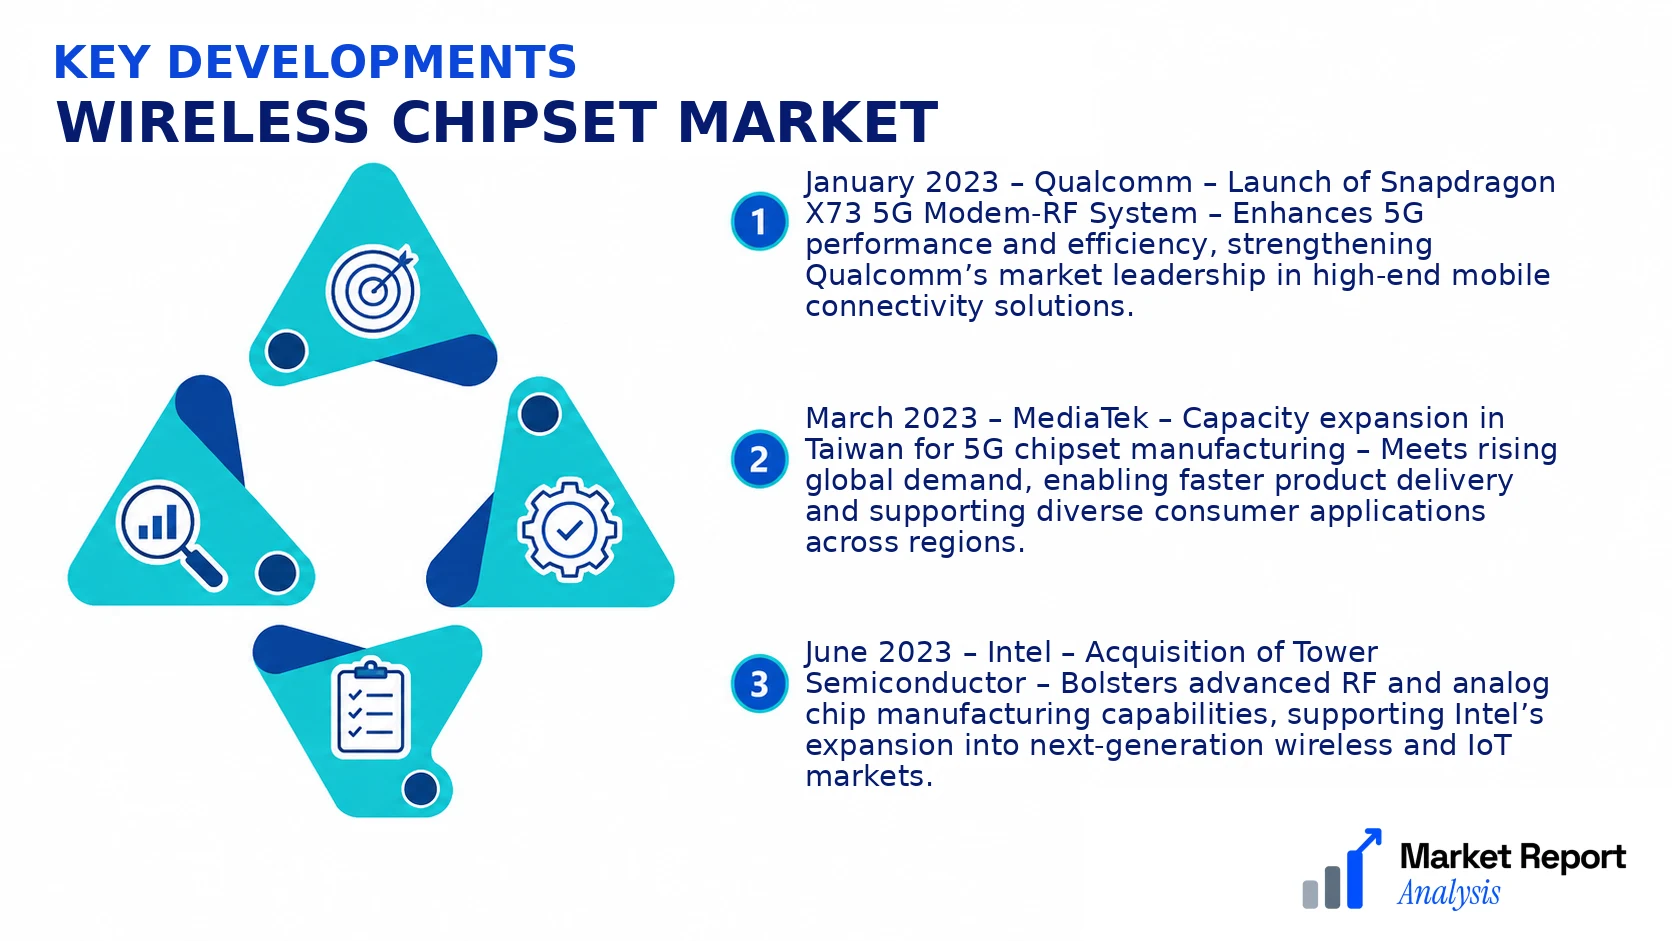
- January 2023 – Qualcomm – Launch of Snapdragon X73 5G Modem-RF System – Enhances 5G performance and efficiency, strengthening Qualcomm’s market leadership in high-end mobile connectivity solutions.
- March 2023 – MediaTek – Capacity expansion in Taiwan for 5G chipset manufacturing – Meets rising global demand, enabling faster product delivery and supporting diverse consumer applications across regions.
- June 2023 – Intel – Acquisition of Tower Semiconductor – Bolsters advanced RF and analog chip manufacturing capabilities, supporting Intel’s expansion into next-generation wireless and IoT markets.
- September 2023 – Samsung Electronics – Launch of Exynos 2200 with integrated 4G/5G modem – Further improves device performance, emphasizing vertical integration and technological leadership in semiconductor design.
- November 2023 – Huawei Technologies – Strategic alliance with Semiconductor Manufacturing International Corporation (SMIC) – Aims to develop self-reliant 5G chipsets, reducing reliance on foreign suppliers amidst global trade restrictions.
Frequently Asked Questions
What is the Wireless Chipset Market?
The Wireless Chipset Market encompasses the industry involved in the design, manufacturing, and sale of wireless communication chips used in various electronic devices such as smartphones, tablets, and IoT gadgets. It is critical for enabling wireless connectivity functionalities.
What is the current market size of Wireless Chipset Market?
As of 2026, the global Wireless Chipset Market is valued at approximately USD 45 Billion, reflecting a growing adoption of wireless-enabled devices. This market size is expected to continue increasing as demand for wireless connectivity in various sectors rises.
What factors are driving the Wireless Chipset Market?
Key drivers include the rapid expansion of 5G technology, increased adoption of Internet of Things (IoT) devices, rising demand for wireless broadband, and technological advancements in chipset miniaturization and power efficiency, all supporting market growth and innovation.
Which region dominates the Wireless Chipset Market?
North America currently dominates the Wireless Chipset Market, driven by high technological adoption, sophisticated infrastructure, and significant investments in 5G and IoT sectors. Europe and Asia-Pacific are also rapidly growing regions.
Which segment is expected to grow the fastest?
The 5G wireless chipset segment is projected to experience the fastest growth, owing to the rollout of 5G networks globally, which requires advanced chipsets for high-speed data transmission and low latency functionalities in various devices.
Who are the leading companies operating in the Wireless Chipset Market?
Leading companies include Qualcomm, MediaTek, Intel, Samsung Electronics, and Broadcom. These firms are prominent for their technological innovation, market share, and extensive product development in the wireless chipset ecosystem.
Analyst Perspective
The wireless chipset market is approaching a maturity phase with steady demand driven by increasing adoption of IoT devices, 5G infrastructure, and connected vehicles. Long-term, the market is poised for robust growth, supported by innovations in low-power chipsets, integrated AI functionalities, and enhanced security features that cater to evolving consumer and enterprise needs. Commercial opportunities are concentrated in high-growth regions such as Asia-Pacific, driven by expanding telecom infrastructure and smart device penetration, and North America, due to early 5G deployment and automotive connectivity integration. Technological evolution is expected to focus on further miniaturization, energy efficiency, and multi-standard support to facilitate seamless connectivity. Investment priorities should target R&D for next-generation 5G/6G chipsets, and strategic alliances will be crucial to accelerate innovation and market penetration amid intensifying competition. Regional growth potential remains significant in Asia-Pacific and Latin America, where digital transformation initiatives offer substantial upside. The market's competitive landscape suggests a consolidation trend, with established players expanding portfolios and new entrants differentiating through niche innovations. Strategic positioning will require balancing technological agility with regional market nuances, ensuring long-term resilience amidst rapid technological shifts and geopolitical influences.
