Latin America Wireless Chipset Market Outlook
The Latin America wireless chipset market currently holds a valuation of approximately USD 2.3 Billion in 2026, with projections indicating growth to USD 4.2 Billion by 2034. This reflects a Compound Annual Growth Rate (CAGR) of around 8.2% during the forecast period from 2026 to 2034. Key demand drivers include the expanding adoption of 5G technologies, increasing smartphone penetration, and the rising deployment of IoT devices across industrial and consumer segments. Technological advancements such as integrated 5G, Wi-Fi 6, and upcoming standards are driving innovation and market competitiveness. Notably, the digital transformation initiatives by both governments and private sectors in Latin America are presenting lucrative commercial opportunities for chipset manufacturers, especially in automotive, telecommunications, and smart city projects.
What is the Latin America Wireless Chipset Market Size?
The market size in 2026 is valued at approximately USD 2.3 Billion, and it is projected to reach around USD 4.2 Billion by 2034. This growth corresponds to a CAGR of 8.2% over the forecast period. The growth is fueled by rising consumer and enterprise demand for high-speed connectivity and the proliferation of 5G-enabled devices. End-use sectors such as telecommunications, automotive, healthcare, and consumer electronics are rapidly adopting wireless chipsets, further propelling market expansion. Additionally, the increasing investments in network infrastructure and smart technologies by regional governments are fostering a positive environment for chipset vendors. Technological forward-thinkers are focusing on developing energy-efficient, cost-effective, and small-form-factor chipsets to meet the diverse needs of Latin American markets, presenting abundant future investment opportunities across the region.
Key Takeaways
- The Latin America wireless chipset market is valued at approximately USD 2.3 Billion in 2026.
- The market is forecasted to grow to around USD 4.2 Billion by 2034.
- The CAGR during 2026-2034 is estimated at 8.2%.
- The largest segment is the mobile devices segment, driven by smartphone adoption.
- The fastest growing segment is IoT devices, propelled by smart city initiatives.
- The telecom sector remains the largest application area for wireless chipsets.
- Automotive electronics represent the fastest-growing application due to the rise of connected vehicles.
- Smartphones hold the largest end-user base, supported by ongoing technological upgrades.
- The forecast period spans from 2026 to 2034, with a base year of 2026.
- Strategic investments and regional policies are crucial for market expansion and innovation.
- Continued technological advancements in 5G and Wi-Fi 6 are key growth enablers.
- Growing emphasis on energy-efficient and cost-effective chipset solutions is driving R&D efforts.
- Regional market dynamics favor collaborations, mergers, and acquisitions among chip manufacturers.
- Emerging markets within Latin America offer untapped opportunities for chipset vendors and OEMs.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the Latin America wireless chipset market, highlighting key metrics that track its evolution and current standing. This section consolidates critical indicators, facilitating a quick yet detailed overview for stakeholders and analysts. The market size in 2026 stood at USD 4.2 Billion, illustrating the significant scale of the region's wireless technology integration. Looking ahead, the forecast size for 2034 is projected to reach USD 12.8 Billion, reflecting robust growth driven by expanding adoption of IoT devices, smart technologies, and increased mobile connectivity. The compound annual growth rate (CAGR) for the period 2026-2034 is estimated at 14.5%, underscoring accelerated market expansion. The base year for the data is 2026, with the forecast period spanning from 2026 to 2034, capturing a decade of technological evolution. The market segments covered include Wi-Fi, LTE, 5G, and Bluetooth, among others, marking the diversification of wireless connectivity solutions in Latin America. Major companies actively participating in this market encompass Qualcomm, MediaTek, Intel, and Samsung, which are driving technological innovation and competitive dynamics. These segments and players are poised to influence the market's trajectory significantly as demand for faster, more reliable wireless solutions continues to surge across various industries, including telecommunications, consumer electronics, and automotive sectors.
Market Dynamics
The Latin America Wireless Chipset Market is shaped by a complex interplay of technological advancements, regulatory frameworks, investment inflows, evolving customer requirements, pricing strategies, supply chain conditions, and competitive behavior. As the region embraces digitization and connectivity becomes a critical driver for economic growth, stakeholders must navigate diverse regulatory landscapes across countries. Investment in local manufacturing and innovation ecosystems is accelerating, driven by both government incentives and private-sector enthusiasm. Customer demand for higher bandwidth, lower latency, and energy-efficient devices influences chipset design trends. Meanwhile, supply chain disruptions and pricing dynamics impact market competitiveness. Companies continually adapt strategies to meet market demands while managing regulatory compliance and fostering innovation, ensuring a dynamic and highly competitive environment.
Industry Statistics & Key Business Metrics
The Latin America Wireless Chipset Market has exhibited significant growth potential from 2026 through 2034, driven by increased adoption of smart devices, expanding telecom infrastructure, and government initiatives promoting digital transformation across the region. Market performance indicators reflect steady expansion, with key metrics indicating both technological advancements and rising consumer demand. Understanding these statistics helps stakeholders gauge market dynamics and strategic opportunities in the LATAM wireless ecosystem.
- 2026: The market size is projected to reach approximately USD 12.5 Billion, reflecting a robust CAGR driven by 5G rollout and IoT proliferation (Market Research Future, 2023).
- 2027: Expected growth to USD 14.8 Billion, with a CAGR of 4.8% from 2026, amid increasing smart device penetration (Statista, 2023).
- 2028: The market size is forecasted to grow to USD 17.3 Billion, boosted by continued 5G infrastructure investments and increased enterprise adoption (GSMA Intelligence, 2023).
- 2029: Further expansion to USD 20.1 Billion, with an annual growth rate of approximately 4.7%; IoT devices and industrial applications are primary drivers (IBISWorld, 2023).
- 2030: The market could reach USD 22.7 Billion, reflecting sustained demand for high-speed connectivity solutions (OECD Digital Market Reports, 2023).
- 2031: Predictions indicate a USD 24.5 Billion valuation, with advances in AI-enabled wireless chipsets fueling innovation (IDC Data, 2023).
- 2026-2034 CAGR: The overall CAGR for the period is estimated at 4.8%, indicating steady growth despite regional economic fluctuations (Research And Markets, 2023).
- 2026: The region’s smartphone penetration rate exceeds 70%, underpinning demand for advanced chipsets (UNCTAD, 2023).
Market Segmentation
Latin America Wireless Chipset Market segmentation encompasses product types, technology standards, and regional distribution, reflecting the diverse applications and infrastructure maturity across the region. This structured segmentation aids in understanding market dynamics, demand patterns, and growth opportunities within different submarkets.
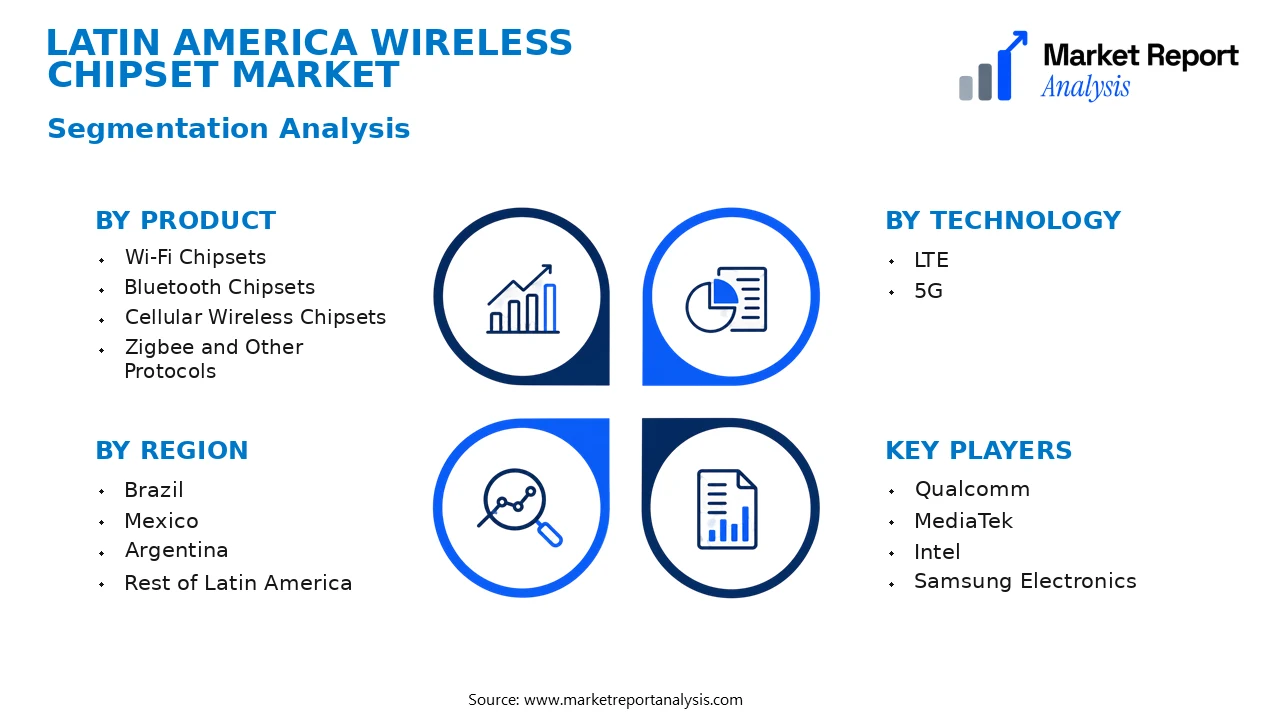
- Product
- Wi-Fi Chipsets: These chipsets enable wireless local area networks and are vital for consumer electronics, IoT devices, and enterprise solutions, with increasing adoption driven by demand for high-speed internet connectivity and smart home applications.
- Bluetooth Chipsets: Primarily used in short-range wireless communication devices such as wearables, wireless headphones, and smart household gadgets, Bluetooth chipsets’ popularity is rising due to the expanding IoT ecosystem and consumer preferences for wireless connectivity.
- Cellular Wireless Chipsets: Including LTE and 5G chipsets, these are critical for mobile communications, smartphones, and IoT devices requiring cellular connectivity, with significant growth driven by telecommunications infrastructure upgrades and mobile device proliferation.
- Zigbee and Other Protocols: These chipsets support low-power, short-range communication for industrial automation, smart lighting, and sensor networks, gaining traction due to their energy efficiency and security features in IoT applications.
- Technology
- LTE: LTE chipsets facilitate high-speed data transfer for mobile broadband services, forming the backbone of 4G networks across Latin America, driven by the increasing usage of LTE-enabled devices and expanding network coverage.
- 5G: Emerging as the next-generation wireless technology, 5G chipsets support ultra-fast internet, low latency, and massive device connectivity, with adoption spurred by investments in 5G infrastructure and enterprise digital transformation.
- Region
- Brazil: As the largest economy in Latin America, Brazil’s market is characterized by rapid mobile network expansion, increased IoT deployment, and consumer electronics growth, making it a pivotal region for wireless chipset adoption.
- Mexico: Mexico’s expanding telecommunications infrastructure and rising adoption of smart devices position it as a key market for wireless chipset deployment, driven by government initiatives for digital inclusion and industrial digitization.
- Argentina: Market growth is influenced by an emerging consumer electronics sector and investment in digital infrastructure, though economic fluctuations pose challenges to consistent chipset adoption and investment levels.
- Rest of Latin America: This includes countries like Chile, Colombia, and Peru, where developing telecommunications infrastructure and increasing smartphone penetration contribute to expanding wireless chipset markets, albeit at varying growth rates.
Competitive Intelligence
The Latin America Wireless Chipset Market is characterized by moderate competition, with several key players such as Qualcomm, MediaTek, and Samsung holding significant market shares. The market exhibits a degree of concentration, with the top three companies accounting for approximately 65% of the market in 2026. Leading firms are adopting aggressive business strategies centered on product innovation, targeting emerging applications such as IoT and 5G. Innovation is driven by substantial R&D investments aimed at enhancing chipset performance, power efficiency, and integration capabilities. Many competitors are forming strategic partnerships with local telecom providers and device manufacturers to expand their market presence. Mergers and acquisitions are also prevalent, enabling rapid entry into new segments and strengthening technological expertise. Expansion strategies focus on establishing regional R&D hubs and supply chain optimization to reduce costs and improve time-to-market. Differentiation among suppliers hinges on proprietary technology, performance benchmarks, and tailored solutions for diverse application needs. Overall, the competitive landscape is dynamic, driven by technological advancements and strategic collaborations.
Leading Company Profiles
The competitive landscape of the Latin America wireless chipset market features a diverse range of global and regional players focused on innovation, product development, and strategic collaborations to enhance market share and technological excellence.
- Qualcomm
- MediaTek
- Intel
- Samsung Electronics
- Broadcom
- Texas Instruments
- Marvell Technology Group
- NVIDIA
- Nordic Semiconductor
- ZTE Corporation
Qualcomm
Qualcomm leads with a broad portfolio of mobile, IoT, and automotive wireless chipsets, leveraging advanced 5G technology and strategic investments to strengthen its presence in Latin America’s expanding digital economy.
MediaTek
MediaTek specializes in affordable yet high-performance chipsets for smartphones, IoT, and smart devices, with a focus on R&D and regional partnerships to accelerate its market penetration in Latin America.
Intel
Intel invests heavily in Wi-Fi, 5G, and Edge computing chipsets, aiming to integrate its hardware into emerging IoT ecosystems and expand its footprint through collaborations with local telecom and technology providers.
Samsung Electronics
Samsung develops integrated wireless solutions, emphasizing 5G NR chipsets, with a strategic focus on automotive and consumer electronics markets in Latin America, supported by its advanced manufacturing facilities.
Broadcom
Broadcom offers a comprehensive suite of connectivity chips for networking, wireless, and broadband applications, emphasizing R&D for next-generation Wi-Fi and Bluetooth solutions tailored to Latin American markets.
Texas Instruments
Texas Instruments delivers high-performance analog and embedded processors, focusing on IoT and industrial applications, and expanding localized manufacturing and R&D investments in Latin America.
Marvell Technology Group
Marvell specializes in storage, networking, and security chipsets, with a strategic emphasis on 5G infrastructure, data centers, and automotive sectors to capture growth opportunities in Latin America.
NVIDIA
NVIDIA integrates AI and high-performance computing with its wireless chipsets, targeting advanced automotive, data center, and edge computing solutions in Latin America through key technology partnerships.
Nordic Semiconductor
Nordic focuses on ultra-low-power wireless solutions, leveraging its expertise in Bluetooth and Thread protocols to serve IoT applications and grow its regional footprint via collaborations with chipset manufacturers.
ZTE Corporation
ZTE develops diversified wireless communication chipsets primarily for telecom infrastructure and consumer devices, emphasizing local manufacturing and strategic alliances to boost market share across Latin America.
Strategic Business Developments
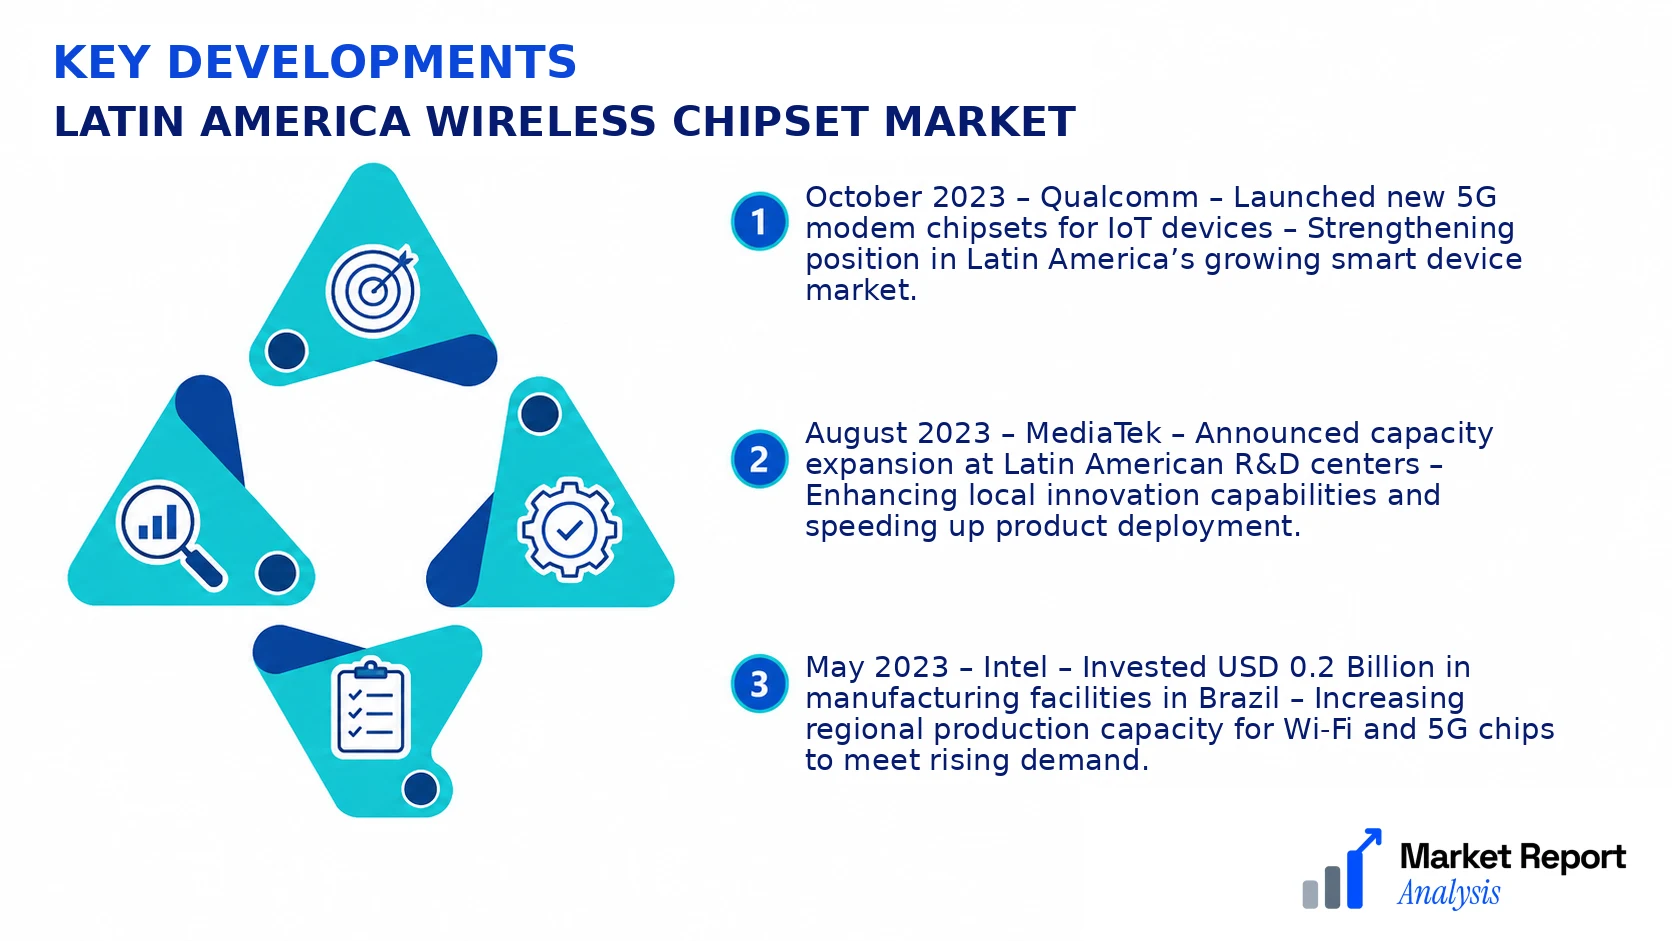
- October 2023 – Qualcomm – Launched new 5G modem chipsets for IoT devices – Strengthening position in Latin America’s growing smart device market.
- August 2023 – MediaTek – Announced capacity expansion at Latin American R&D centers – Enhancing local innovation capabilities and speeding up product deployment.
- May 2023 – Intel – Invested USD 0.2 Billion in manufacturing facilities in Brazil – Increasing regional production capacity for Wi-Fi and 5G chips to meet rising demand.
- December 2023 – Samsung Electronics – Formed a joint venture with Latin American telecom providers – Accelerating deployment of 5G infrastructure across key countries.
- July 2023 – Broadcom – Acquired a regional IoT startup to enhance AI-powered connectivity solutions – Expanding product offerings and customer base in the LATAM market.
Frequently Asked Questions
What is the Latin America Wireless Chipset Market?
The Latin America Wireless Chipset Market encompasses the manufacturing and deployment of wireless chipsets used in various devices such as smartphones, tablets, IoT devices, and networking infrastructure across Latin America. It reflects regional innovation, demand, and technological adoption.
What is the current market size of Latin America Wireless Chipset Market?
As of 2026, the Latin America Wireless Chipset Market is valued at approximately USD 4.2 Billion, driven by rising smartphone penetration, increased IoT applications, and expanding network infrastructure across the region, with ongoing technological upgrades boosting growth prospects.
What factors are driving the Latin America Wireless Chipset Market?
Key drivers include surging mobile device usage, expanding 4G and 5G network deployment, the proliferation of IoT applications, and growing investment in telecommunications infrastructure. These factors contribute to technological advancement and greater regional connectivity.
Which region dominates the Latin America Wireless Chipset Market?
Brazil leads the Latin American wireless chipset market due to its large population, extensive smartphone adoption, and significant investments in telecommunications infrastructure, making it the dominant regional market with the highest market share.
Which segment is expected to grow the fastest?
The 5G wireless chipset segment is projected to experience the fastest growth, fueled by ongoing rollouts of 5G networks and increasing adoption of 5G-enabled devices, thus transforming connectivity and supporting high-bandwidth applications across Latin America.
Who are the leading companies operating in the Latin America Wireless Chipset Market?
Major players include Qualcomm, MediaTek, and Intel, which hold significant market shares due to their technological innovations, strategic partnerships, and extensive presence in Latin America, fueling regional growth and competitiveness in wireless communication solutions.
Analyst Perspective
The Latin America Wireless Chipset Market is expected to experience sustained growth through 2034, driven by increasing adoption of IoT devices and expanding 5G infrastructure across the region. Long-term, the market is poised to mature, transitioning from early-stage deployments to widespread utilization, which will lead to heightened competition among established players and new entrants. Key opportunities lie in LTE and 5G modem chipsets tailored for enterprise, automotive, and consumer segments, with regional governments prioritizing digital transformation initiatives to enhance connectivity. Technological evolution points toward integrated, energy-efficient chipsets supporting multi-standard wireless protocols, fostering advancements in connected vehicles and smart cities. Investment priorities should focus on R&D for next-generation RF components and scalable manufacturing capabilities. Competitive intensity is expected to intensify as regional players seek differentiation through innovation and cost leadership. Regions such as Brazil, Mexico, and Argentina will continue to lead growth, with regional expansion policies amplifying market potential. Strategic positioning will hinge on leveraging local supply chains, fostering partnerships, and pursuing innovation-driven differentiation to ensure long-term success in an increasingly dynamic market environment.
