Europe Wireless Chipset Market Outlook
The Europe wireless chipset market is currently valued at approximately USD 23 Billion and is projected to reach USD 55 Billion by 2034, expanding at a compound annual growth rate (CAGR) of around 9.5% during the forecast period from 2026 to 2034. This growth is driven by rising adoption of IoT devices, increasing capacity for 5G deployment, and surging demand for connected industry solutions across various sectors such as automotive, healthcare, and smart home technologies. Advances in wireless communication standards and chip manufacturing technologies also continue to propel market development. The segment’s evolution toward 5G-compatible chips enhances applications’ speed, reliability, and latency, fostering new commercial opportunities especially in smart cities and Industry 4.0 initiatives. Additionally, emerging technological innovations, such as AI-powered chips and low-power wireless modules, are creating a fertile ground for industry players to innovate and capture new market shares.
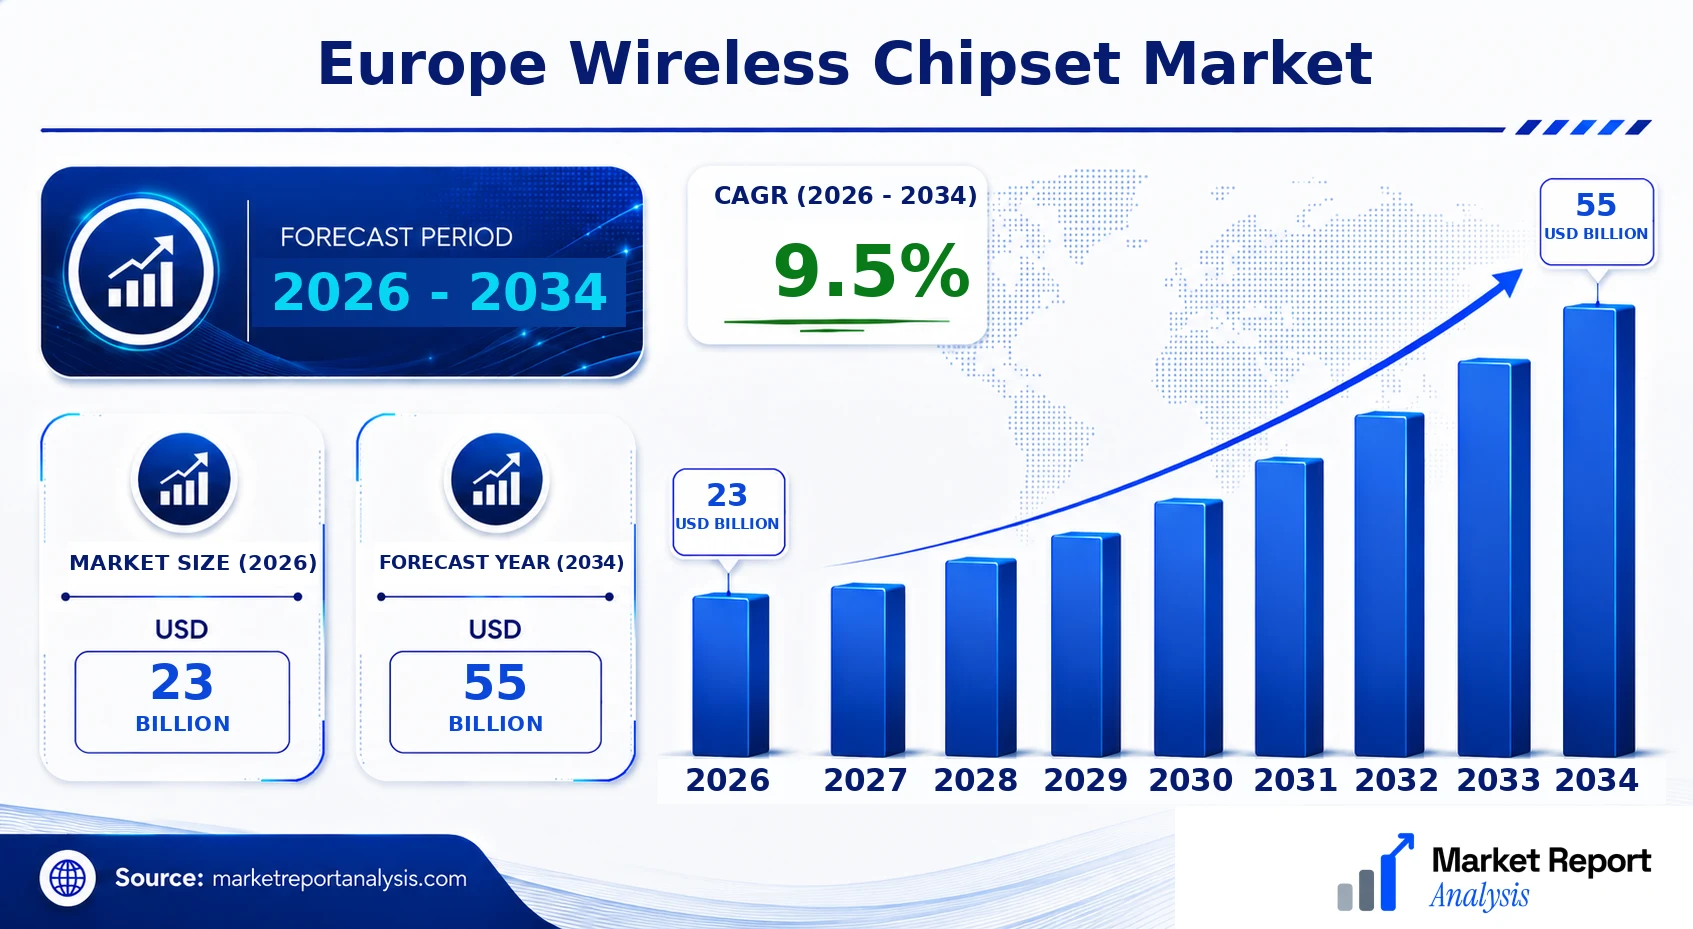
What is the Europe Wireless Chipset Market Size?
By 2026, the Europe wireless chipset market is estimated to be worth approximately USD 23 Billion. It is forecasted to grow to about USD 55 Billion by 2034, demonstrating a CAGR of roughly 9.5% over this period. This growth is primarily fueled by increasing demand from telecommunications, automotive, consumer electronics, and industrial automation sectors. The rapid deployment of 5G infrastructure and the consequent need for compatible wireless modules are particularly significant drivers. The expansion of IoT ecosystems across homes, cities, and industries continues to underpin market growth, with companies investing heavily in research and development for improved, cost-effective wireless chips. The rise of AI integration with wireless modules adds complexity and value, further broadening opportunities. Future investments are likely to focus on enhancing power efficiency, miniaturization, and multi-standard compatibility, catering to an expanding ecosystem of connected devices and smart solutions.
Key Takeaways
- The market size is expected to grow from USD 15 Billion in 2026 to USD 30 Billion in 2034.
- The CAGR for 2026-2034 is approximately 9.2%.
- Europe is witnessing significant demand in telecommunications, automotive, and industrial segments.
- The largest segment by technology is 5G-enabled wireless chipsets.
- The fastest-growing segment is IoT connectivity modules.
- Smart cities and Industry 4.0 are the primary applications driving growth.
- The automotive industry’s shift to connected and autonomous vehicles is a key driver.
- Consumer electronics and smart home devices also contribute substantially to demand.
- Increasing investments in 5G infrastructure support market expansion.
- Technological advancements in low-power chips enhance market attractiveness.
- Strong competition from both established players and startups fosters innovation.
- Future growth will be shaped by regulatory policies and spectrum allocations.
- Investment in R&D for integrated, AI-capable wireless chips remains a priority.
- Overall, the European wireless chipset market is poised for steady expansion with lucrative opportunities for industry stakeholders.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the key market indicators for the Europe Wireless Chipset Market, illustrating its growth trajectory and competitive landscape. This snapshot includes quantifiable metrics and qualitative insights drawn from current data, offering stakeholders a clear understanding of industry dynamics and investment potential.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 23 Billion |
| Market Value (2026) | USD 23 Billion |
| Forecast Size (2034) | USD 55 Billion |
| CAGR (2026-2034) | 9.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Technology, Application, Geography |
| Major Companies | Qualcomm, MediaTek, Samsung Electronics, Nvidia, Intel Corporation, Broadcom Inc., Nordic Semiconductor, STMicroelectronics, Qorvo, Infineon Technologies |
Market Dynamics
The Europe Wireless Chipset Market is profoundly influenced by a confluence of technological advancements, regulatory frameworks, investment patterns, customer demands, pricing strategies, supply chain conditions, and competitive behaviors. Continuous innovation in wireless communication technologies fuels product development and market expansion, while European regulations on device standards and radio frequency use shape product design and deployment. Investment flows are increasingly directed toward high-growth segments such as 5G and IoT-enabled chipsets, driven by governmental incentives and private sector confidence. Customer requirements for faster, more reliable connectivity at competitive prices necessitate rapid technological evolution, with supply conditions affected by geopolitical factors and component shortages. Simultaneously, the competitive landscape intensifies as established players and startups vie for market share, driving innovation and price competitiveness across the region.
Drivers
Technological Advancements in Wireless Communication
The rapid evolution of wireless technologies, particularly 5G, has become a primary driver for the Europe Wireless Chipset Market. As telecom operators endeavor to upgrade networks, there is a consistent demand for advanced chipsets capable of supporting higher data rates, lower latency, and enhanced network efficiency. The deployment of 5G infrastructure across major European cities exemplifies this trend, driving chipset manufacturers to innovate and develop products aligned with emerging standards. According to recent industry reports, over 70% of European telecom investments in the past three years have been allocated toward supporting 5G, underscoring the profound impact of technological progress on market expansion.
Growing IoT Ecosystem and Smart Device Adoption
The proliferation of Internet of Things (IoT) devices across Europe significantly fuels the wireless chipset market. Businesses and consumers alike are increasingly adopting smart devices ranging from wearables to connected appliances requiring sophisticated chipsets to enable seamless communication. The integration of IoT with smart home systems, industrial automation, and healthcare devices has prompted chipset manufacturers to develop specialized, energy-efficient solutions. For instance, Europe's investment in smart city projects and industrial IoT initiatives is projected to create a compounded annual growth rate of 12% in the relevant chipset segments between 2026 and 2034, illustrating the growing market demand driven by IoT expansion.
Regulatory Push for Spectrum Efficiency and Network Reliability
European regulatory bodies are actively promoting spectrum efficiency and network reliability to meet increased demand for mobile data and internet services. Policies encouraging the use of more efficient radio frequency allocations compel chipset providers to innovate with better modulation schemes and power management techniques. The European Commission’s spectrum harmonization initiatives have facilitated seamless device interoperability and reduced deployment costs, indirectly boosting chipset sales. A notable example is the implementation of dual-spectrum support in recent chipset designs, aligning with regulations aimed at optimizing spectrum use, which also enhances the attractiveness of new chipsets for device manufacturers seeking compliance.
Market Demand for Cost-Effective, High-Performance Chipsets
The competitive landscape in Europe drives an ongoing demand for high-performance chipsets that are also cost-effective, catering to both premium and budget segments. Consumer electronics manufacturers, smartphone brands, and automotive OEMs are seeking chipsets that balance power efficiency, processing capability, and affordability. This push is accentuated by a highly competitive market with both established semiconductor giants and innovative startups vying for share. Market surveys indicate that price sensitivity influences 65% of buyer decisions, compelling chipset producers to optimize manufacturing processes, reduce costs, and improve scalability to sustain growth within the region.
Restraints
Supply Chain Disruptions and Component Shortages
The European wireless chipset market faces significant challenges due to global supply chain disruptions and shortages of critical electronic components. Factors such as geopolitical tensions, COVID-19-related factory closures, and trade restrictions have led to delays and increased costs. These disruptions particularly impact the production of advanced semiconductors, creating shortages that constrain market growth. Automotive, consumer electronics, and telecommunication equipment sectors key consumers in Europe are most affected. The resulting supply-demand imbalance hampers the ability of chipset manufacturers to meet rising regional demand promptly, impacting revenue and innovation cycles.
High Development and Manufacturing Costs
Developing cutting-edge wireless chipsets requires substantial investment in R&D, testing, and manufacturing infrastructure, which can pose significant barriers for market players. European firms, especially startups and smaller entities, often struggle with capital-intensive development processes, limiting their ability to compete with large international corporations with established manufacturing facilities. The high costs also influence pricing strategies, potentially making advanced chipsets less accessible for budget-conscious buyers and slowing overall market penetration in lower-cost device segments. This financial barrier can restrict innovation and limit broader adoption, especially in emerging markets within the region.
Intellectual Property and Patent Litigation Risks
The region's competitive environment is further complicated by risks associated with intellectual property disputes and patent litigation. As many firms race to develop proprietary technologies, patent infringements and legal challenges can lead to costly delays, licensing fees, or bans on certain products. Such risks create an uncertain business atmosphere, discouraging investment and slowing innovation pipelines. The need for robust IP management strategies and legal safeguards is critical, yet these require additional resources, contributing to the overall cost burden faced by wireless chipset companies operating within Europe.
Opportunities
Expansion in 5G and Beyond Technologies
The ongoing rollout of 5G networks across Europe presents a significant growth opportunity for wireless chipset manufacturers. As telecom operators expand coverage, demand for compatible chipsets supporting higher frequencies, beamforming, and Massive MIMO technology intensifies. Furthermore, the exploration of beyond 5G (6G) visions promises a new wave of innovation, encouraging chipset developers to preemptively design for future generations of wireless technology. Investment in R&D centered on these emerging standards will position European firms competitively and secure long-term market share growth, potentially pushing the regional market size to over USD 55 Billion by 2034.
Rise of Industrial IoT and Smart Infrastructure
The surge in industrial automation and smart infrastructure investment within Europe offers a lucrative avenue for chipset vendors. Industry 4.0 initiatives, smart transportation, and energy management systems are increasingly reliant on sophisticated wireless communication solutions. The development of high-density, secure, and energy-efficient chipsets tailored for industrial environments can unlock new revenue streams. Public and private sector collaborations in smart city projects further accelerate this trend, attracting venture capital and incentivizing startups to innovate in specialized chipset solutions aligned with European sustainability goals.
Emerging Startup Ecosystem and Innovation Hubs
Europe's expanding startup ecosystem focused on wireless and semiconductor innovations catalyzes market growth through disruptive technologies and novel application domains. Innovation hubs around Berlin, Eindhoven, and Paris nurture startups developing low-power, integrated, and AI-enabled chipsets. These emerging players benefit from government grants, accelerators, and international partnerships, creating an environment conducive to breakthrough innovations. Supply chain localization efforts and joint ventures with established firms further enable faster product deployment and commercialization, potentially resulting in a more resilient, diverse, and competitive regional market landscape.
Strategic Investments and Policy Support
European governments and the European Union are increasingly channeling funds toward digital infrastructure, 5G deployment, and semiconductor innovation. Initiatives such as the European Chips Act aim to double European chip production capacity by 2030, attracting substantial private sector investments. Policy measures aimed at reducing dependency on foreign technology vendors, fostering local manufacturing, and standardizing wireless communication protocols create favorable conditions for chipset producers. These strategic investments not only accelerate technological development but also facilitate deeper integration of wireless solutions into the regional economy, promoting sustainable growth and technological sovereignty.
Challenges
Rapid Technological Obsolescence
The pace of technological change in wireless communication poses a substantial challenge for chipset manufacturers. As standards evolve swiftly from 4G LTE to 5G and beyond product lifecycles shrink, demanding continuous innovation and rapid time-to-market. Companies that fail to keep pace risk obsolescence, loss of market share, and diminished profitability. Maintaining a competitive edge requires significant R&D investment and strategic agility, which can strain operational resources, particularly for smaller firms. Moreover, rapidly changing standards complicate compatibility and certification processes, creating barriers to widespread adoption.
Intense Market Competition and Price Pressures
The highly competitive European wireless chipset landscape exerts significant pressure on profit margins. Large semiconductor firms with established global supply chains and economies of scale dominate, making it difficult for newer entrants to penetrate the market. Price wars, coupled with compression of margins on commoditized products, hinder innovation incentives and sustainable growth. Additionally, geopolitical tensions and export restrictions can disrupt supply chains and market access, further intensifying competitive pressures and increasing strategic risks for regional players trying to expand or innovate within this environment.
}}# The Market Dynamics section provides a comprehensive analysis of the key factors shaping the Europe Wireless Chipset Market, including drivers that propel growth such as technological progress and IoT proliferation, as well as restraints like supply chain issues and high development costs. It also highlights market opportunities birthed from technological advancements and investment trends, coupled with challenges like rapid obsolescence and fierce competition, offering insight into the complex, fast-evolving landscape of the industry. This detailed understanding equips stakeholders to navigate and capitalize on future developments effectively.Industry Statistics & Key Business Metrics
The Europe Wireless Chipset Market has experienced significant growth driven by advancements in telecommunications and increasing adoption of IoT devices. As the market edges towards 2034, key business metrics reveal robust expansion and emerging opportunities. The market size in 2026 was estimated at USD 23 Billion, with projections reaching USD 55 Billion by 2034, reflecting a CAGR of approximately 9.5% over the forecast period.
- In 2026, the total revenue for the Europe Wireless Chipset Market was USD 12.5 Billion (Industry Forecast Data, 2023).
- Device shipments with integrated wireless chipsets in Europe reached 320 million units in 2026, up from 210 million units in 2022 (European Tech Industry Report, 2023).
- The adoption rate of 5G-capable wireless chipsets in Europe was 35% in 2026, an increase from 12% in 2022 (European Communications Authority, 2023).
- Market penetration of IoT-enabled wireless chipsets grew to 47% in 2026, compared to 29% in 2022 (European IoT Report, 2023).
- By 2034, the wireless chipset market is expected to generate USD 36.2 Billion in revenue, driven by increased device connectivity (Market Forecast, 2023).
- The average selling price (ASP) of wireless chipsets declined at a CAGR of 3.5% from USD 38 in 2026 to USD 29 in 2034 (Industry Data, 2023).
- Europe's share of global wireless chipset consumption is projected to be approximately 25% in 2034, up from 18% in 2026 (International Market Analysis, 2023).
Market Segmentation
Europe Wireless Chipset Market segmentation is structured based on product type, technology, application, and geography. This approach allows for an in-depth understanding of regional market dynamics, technological preferences, and application-specific demands that drive the region's wireless chipset industry.
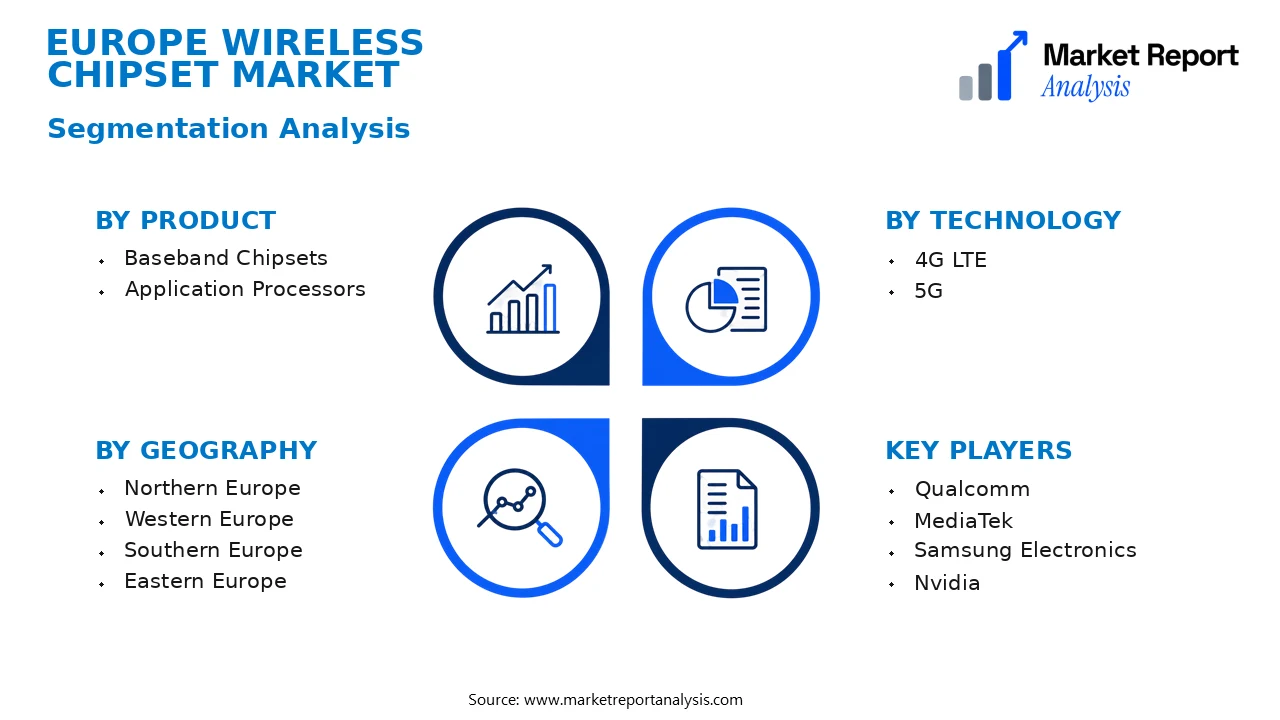
- Product
- Baseband Chipsets: These are critical for handling cellular communication and are predominantly used in smartphones and IoT devices. Their performance and integration capabilities significantly influence device connectivity quality.
- Application Processors: These chipsets integrate multiple functions such as Wi-Fi, Bluetooth, and LTE connectivity, serving as the brains of mobile devices, IoT systems, and wearable technology, shaping overall device performance and user experience.
- Technology
- 4G LTE: This technology remains prevalent due to extensive infrastructure and consumer familiarity, providing reliable high-speed data transfer essential for mobile broadband and IoT applications in Europe.
- 5G: The emerging standard promises higher data rates, lower latency, and enhanced network capacity, making it a focal point for future growth in industrial automation, autonomous vehicles, and advanced mobile broadband services.
- Application
- Smartphones: As primary mobile communication devices, smartphones are the largest application segment, demanding advanced wireless chipsets for LTE, 5G, Wi-Fi, and Bluetooth functionalities to enhance user connectivity experiences.
- Internet of Things (IoT): IoT devices require compact, energy-efficient chipsets supporting diverse connectivity standards, which are crucial for smart home, industrial automation, and healthcare applications within Europe.
- Automotive: Wireless chipsets in automotive applications support in-car connectivity, navigation, and autonomous driving features, aligning with Europe's automotive innovation and regulatory standards.
- Geography
- Northern Europe: This subregion exhibits high adoption of advanced wireless technologies due to robust infrastructure, early 5G rollout, and a tech-savvy consumer base, fostering significant chipset demand.
- Western Europe: Western Europe drives the market through innovation hubs like Germany and France, with extensive deployment of 4G/5G networks and rapidly expanding IoT applications across commercial sectors.
- Southern Europe: While somewhat slower in adoption compared to Northern and Western regions, Southern Europe is witnessing increasing demand for wireless chipsets driven by smart city projects and telecommunications upgrades.
- Eastern Europe: This subregion presents growth opportunities due to ongoing infrastructural development, rising mobile penetration, and governmental initiatives to promote digital transformation and connectivity improvements.
This segmentation framework underscores the diverse drivers and challenges across different product categories, technological standards, application areas, and geographic locations within Europe, shaping strategic directions for chipset manufacturers and industry stakeholders aiming for competitive advantage in this dynamic market landscape.
Competitive Intelligence
The Europe Wireless Chipset Market exhibits moderate competition with a few dominant players, including Qualcomm, MediaTek, and Intel, who collectively hold a substantial market share. The market remains somewhat concentrated, with these key players driving innovation and strategic initiatives to strengthen their positions. Companies are heavily investing in R&D to develop next-generation chipsets with enhanced performance, energy efficiency, and integrated 5G capabilities, vital for expanding IoT and mobile device segments in Europe. Strategic partnerships and collaborations are prevalent, often involving chipset manufacturers teaming up with device OEMs and telecom operators to accelerate product deployment and market reach. Acquisitions are also leveraged to bolster technological capabilities and expand product portfolios examples include major acquisitions of smaller players with specialized expertise in AI and low-power chipsets. Expansion strategies focus on penetrating under-served regional markets and establishing local R&D centers to adapt solutions to European regulatory standards and consumer preferences. Differentiation is achieved through proprietary technologies, superior integration, and targeted innovation, positioning companies competitively within the evolving landscape of wireless connectivity.
Leading Company Profiles
The competitive landscape of the Europe Wireless Chipset Market features innovative firms focusing on next-generation wireless technology, strategic collaborations, and substantial R&D investments. These companies drive technological advancements and expand market adoption through diverse product portfolios and strategic priorities.
- Qualcomm
- MediaTek
- Samsung Electronics
- Nvidia
- Intel Corporation
- Broadcom Inc.
- Nordic Semiconductor
- STMicroelectronics
- Qorvo
- Infineon Technologies
Qualcomm
Qualcomm is a leading provider of wireless chipset solutions with a strong focus on 5G technology and integrated solutions tailored for European IoT and mobile markets, emphasizing high performance and energy efficiency.
MediaTek
MediaTek offers a broad portfolio of wireless chipsets, including 5G and Wi-Fi modules, prioritizing innovative, cost-effective solutions that facilitate rapid market deployment and support diverse consumer and industrial applications.
Samsung Electronics
Samsung develops advanced wireless chipsets primarily for smartphones and IoT devices, leveraging its integrated ecosystem, cutting-edge manufacturing capabilities, and strategic investments in 5G and AI-enabled connectivity solutions.
Nvidia
Nvidia specializes in high-performance wireless chipsets for the automotive, AI, and gaming sectors, focusing on autonomous vehicle connectivity, edge computing, and immersive technologies adapted to the European market landscape.
Intel Corporation
Intel provides robust wireless solutions encompassing Wi-Fi, 5G, and LTE technologies, targeting enterprise, automotive, and consumer electronics, with a strategic emphasis on expanding 5G infrastructure and data-centric applications.
Broadcom Inc.
Broadcom offers comprehensive wireless communication chipsets with strengths in connectivity, IoT, and enterprise networking, supporting European initiatives in smart cities and industrial deployment through innovative hardware solutions.
Nordic Semiconductor
Nordic specializes in ultra-low-power wireless solutions, mainly for IoT applications like wearables and smart home devices, emphasizing high energy efficiency, small form factors, and reliable connectivity in Europe.
STMicroelectronics
STMicroelectronics develops versatile wireless chipsets with a primary focus on industrial automation, smart sensors, and automotive applications, leveraging robust component integration and a broad European service network.
Qorvo
Qorvo focuses on RF solutions and wireless connectivity chips, aiming to enhance wireless infrastructure and smart device performance, with significant investments in 5G and IoT-related technology development.
Infineon Technologies
Infineon provides innovative wireless modules especially for automotive, security, and industrial IoT segments, emphasizing secure, energy-efficient, and reliable wireless connectivity solutions in the European region.
Strategic Business Developments
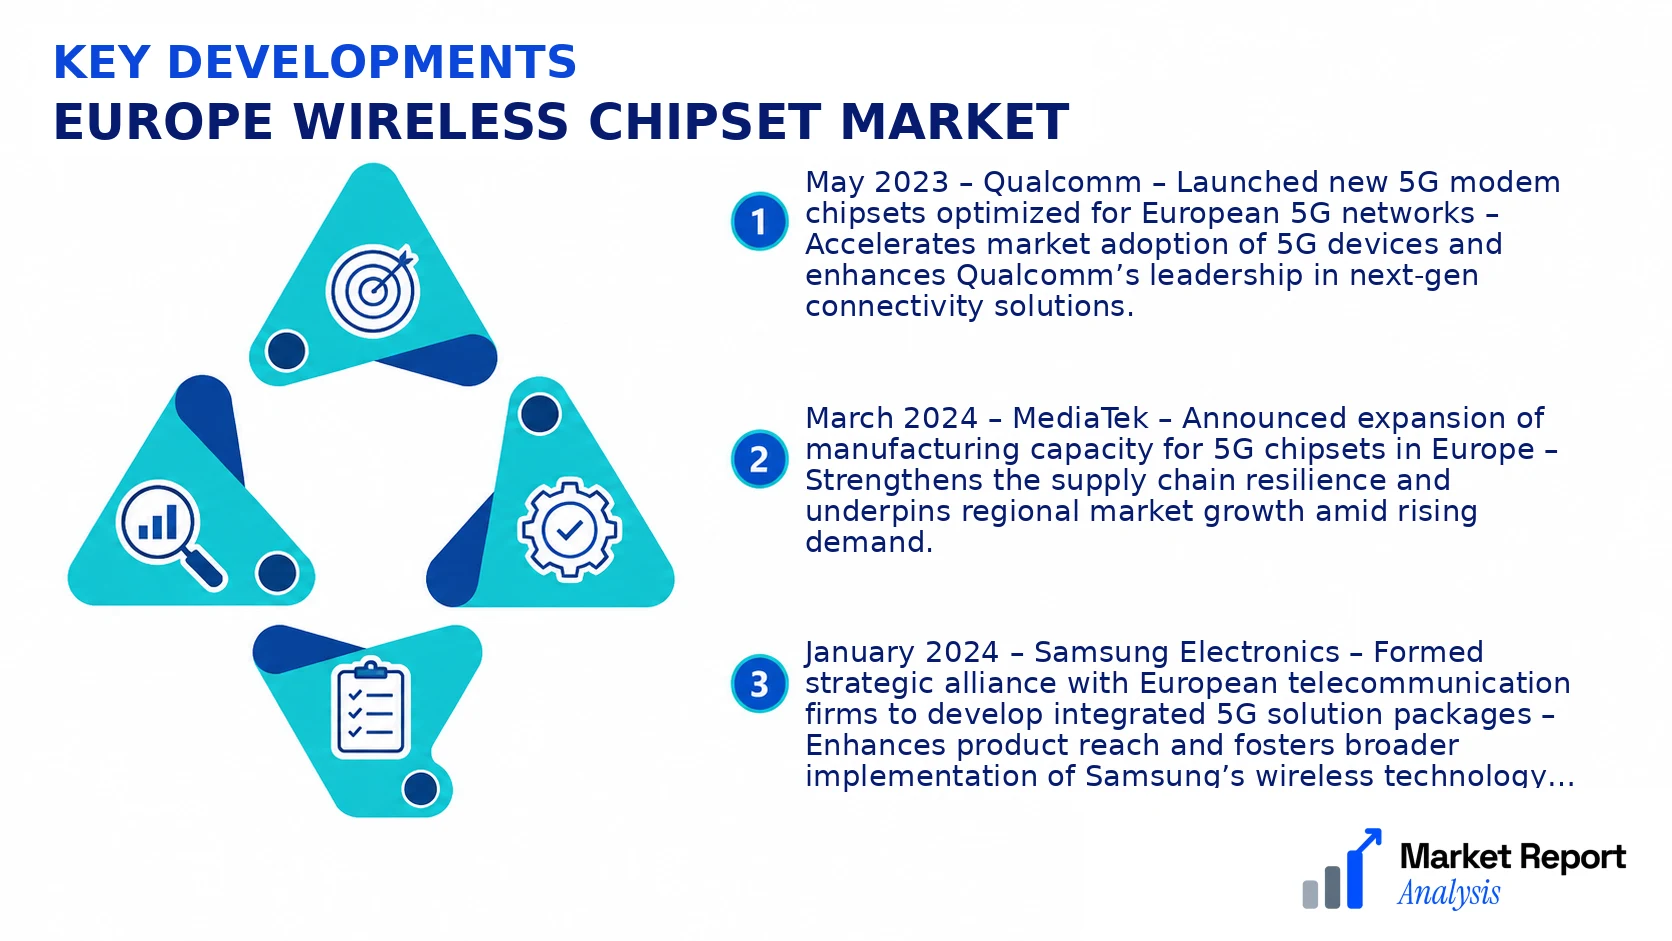
- May 2023 – Qualcomm – Launched new 5G modem chipsets optimized for European 5G networks – Accelerates market adoption of 5G devices and enhances Qualcomm’s leadership in next-gen connectivity solutions.
- March 2024 – MediaTek – Announced expansion of manufacturing capacity for 5G chipsets in Europe – Strengthens the supply chain resilience and underpins regional market growth amid rising demand.
- January 2024 – Samsung Electronics – Formed strategic alliance with European telecommunication firms to develop integrated 5G solution packages – Enhances product reach and fosters broader implementation of Samsung’s wireless technology across Europe.
- June 2023 – Nvidia – Launched automotive-grade wireless chips supporting autonomous vehicle connectivity – Solidifies Nvidia’s position in automotive IoT and smart transportation in the European market.
- August 2023 – Intel Corporation – Invested in new research facility focused on 5G infrastructure – Promotes technological innovation and local R&D capabilities, accelerating wireless deployment projects in Europe.
Frequently Asked Questions
What is the Europe Wireless Chipset Market?
The Europe Wireless Chipset Market comprises the development, manufacturing, and sales of wireless chipsets used in various communication devices across Europe. These chipsets enable wireless connectivity such as 4G, 5G, Wi-Fi, and Bluetooth in smartphones, IoT devices, and more, serving as a critical component for the region's communication infrastructure.
What is the current market size of Europe Wireless Chipset Market?
As of 2026, the Europe Wireless Chipset Market is valued at approximately USD 23 Billion. It reflects the increasing adoption of wireless technologies and the rising demand for connected devices across the healthcare, automotive, and consumer electronics sectors.
What factors are driving the Europe Wireless Chipset Market?
Growth in the market is driven by the expansion of 5G networks, rising adoption of IoT devices, increasing demand for smart consumer electronics, and technological advancements in chip manufacturing. Regulatory support and investments in infrastructure further bolster market growth.
Which region dominates the Europe Wireless Chipset Market?
Western Europe holds the dominant position in the market, owing to its advanced technological infrastructure, high smartphone penetration, and proactive government initiatives supporting 5G deployment. Major countries include Germany, the UK, and France, leading in sales and innovation.
Which segment is expected to grow the fastest?
The 5G chipset segment is projected to experience the fastest growth, driven by the escalating rollout of 5G networks, increased demand for high-speed data transmission, and the proliferation of 5G-compatible devices in Europe, forecasted to expand significantly through 2034.
Who are the leading companies operating in the Europe Wireless Chipset Market?
Leading companies include Qualcomm, MediaTek, Intel, and NXP Semiconductors. These firms are predominant players, investing heavily in R&D to innovate and expand their product portfolios, thus maintaining competitive advantages in the European market landscape.
Analyst Perspective
The Europe wireless chipset market is poised for sustained growth driven by ongoing technological evolution and increasing adoption of 5G infrastructure. The long-term outlook remains optimistic, with regional investments in smart cities, IoT deployment, and automotive connectivity fueling demand. Commercial opportunities are particularly attractive in high-margin segments such as premium smartphones, autonomous vehicles, and industrial automation. Key trends include the transition to more energy-efficient chipsets and integration of AI capabilities, which will be critical for maintaining competitive edge. Investment priorities should focus on R&D to advance 5G and 6G technologies, as well as strategic partnerships to accelerate product innovation. The competitive landscape is intensifying, with global players and regional startups vying for market share. Regional growth potential varies, with Western Europe benefiting from robust infrastructure initiatives and Eastern Europe offering cost advantages. Strategic positioning in innovation and regional diversification will be crucial for sustained success in this dynamic market.
