North America Wireless Chipset Market Outlook
The North America Wireless Chipset Market is valued at approximately USD 15.2 Billion in 2026 and is forecasted to reach around USD 33.8 Billion by 2034, expanding at a CAGR of 10.4% over the period from 2026 to 2034. This growth is propelled by escalating demand for high-speed connectivity solutions, proliferation of 5G technology, increasing adoption of IoT devices, and a surging need for improved wireless communication in consumer electronics, automotive, and industrial sectors. The region’s technological landscape, characterized by advanced infrastructure investments and innovation hubs, fosters robust market momentum. Lead players are heavily investing in next-generation wireless chipsets to capitalize on emerging opportunities, further driving market expansion. Additionally, the rising adoption of smart devices and connected vehicles underscores the segment's expansive growth prospects, providing significant commercial opportunities for chipset manufacturers and related technology providers.
What is the North America Wireless Chipset Market Size?
The North America Wireless Chipset Market size is estimated at a current-market value of USD 15.2 Billion in 2026 and is expected to reach approximately USD 33.8 Billion by 2034, expanding at a CAGR of 10.4% from 2026 to 2034. Growth drivers include widespread adoption of 4G and 5G networks, significant investments in telecom infrastructure, and increasing deployment of IoT-enabled devices across various end-use industries. Major end-user sectors comprise consumer electronics, automotive, healthcare, and industrial automation, each fueling demand for faster, more efficient connectivity solutions. The impact of evolving mobile technologies and the advent of smart city initiatives further enhance chipset deployment. Opportunities for future investment lie in developing more energy-efficient, compact, and cost-effective wireless chipsets, with a focus on supporting next-gen 5G and Wi-Fi 6/6E standards. Continuous product innovation and strategic collaborations are expected to sustain high growth rates and market competitiveness in the region.
Key Takeaways
- Market size in 2026 is approximately USD 15.2 Billion.
- Projected market size in 2034 is around USD 33.8 Billion.
- Overall CAGR from 2026 to 2034 is estimated at 10.4%.
- The largest segment by technology is 5G wireless chipsets.
- The fastest-growing segment is Wi-Fi 6/6E chipsets.
- The primary application is consumer electronics, including smartphones and tablets.
- The fastest-growing application segment is automotive, particularly connected and autonomous vehicles.
- The largest end-user industry is consumer electronics, followed by automotive and industrial sectors.
- The forecast period spans from 2026 to 2034.
- The base year for market estimates is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the North America Wireless Chipset Market, synthesizing key quantitative metrics that depict its current status and anticipated growth trajectory. As of 2026, the market size is projected at USD 35 Billion, reflecting robust expansion driven by advancements in wireless communication technologies and increasing adoption across various end-use industries. Looking ahead, the forecast size for 2034 is estimated at USD 70 Billion, representing a CAGR of approximately 8.1% during the 2026-2034 period. This sustained growth underscores the escalating demand for high-performance wireless connectivity solutions within consumer electronics, automotive applications, and industrial sectors. The base year for the report's modeling and analysis is 2026, with the forecast period spanning from 2026 to 2034, capturing long-term industry trends and innovations. The market segments covered include Wi-Fi, 4G LTE, 5G NR, and emerging IoT standards, each contributing uniquely to the overall market expansion. Major companies leading this market include Qualcomm, MediaTek, Intel Corporation, and Broadcom Inc., which collectively drive innovation and competitive dynamics. The market is characterized by continuous investment in R&D, reflected in technological improvements like integrated 5G chipsets and energy-efficient designs. Pricing trends indicate a gradual decline in costs owing to scaling efficiencies and technological advancements, further fueling demand. Overall, the North America Wireless Chipset Market exhibits maturity, supported by a mature ecosystem of suppliers and manufacturers committed to maintaining competitive advantages through innovation, strategic investments, and comprehensive product portfolios.
Market Dynamics
The North America wireless chipset market is experiencing rapid evolution driven by rapid technological advancements, evolving regulatory frameworks, increased investments, shifting customer requirements, pricing strategies, supply chain conditions, and aggressive competitive behaviors. The convergence of 5G deployment, IoT expansion, and demand for more efficient wireless communications are key factors influencing market dynamics. As OEMs and consumers seek faster, more reliable connectivity, stakeholders are adapting to innovative standards and policies. These forces collectively shape product development, market entry strategies, and competitive positioning, creating a complex landscape where technological innovation and regulatory compliance are paramount for growth and sustainability.
Drivers
Accelerated 5G Adoption
The rollout of 5G networks in North America is a fundamental driver fueling the wireless chipset market. This technological leap enables higher data speeds, lower latency, and enhanced network capacity, prompting OEMs to incorporate advanced chipsets into their devices. The proliferation of 5G smartphones, industrial IoT applications, and smart city infrastructure exemplifies this trend. According to industry data, the number of 5G subscriptions in North America is projected to surpass 200 million by 2026, reflecting significant market momentum. As 5G maturity progresses, demand for compatible wireless chipsets will continue to surge, shaping the market landscape.
Increasing IoT Connectivity
The expansion of IoT devices across sectors such as healthcare, automotive, manufacturing, and smart homes is a key driver underpinning the growth of the wireless chipset market. IoT relies heavily on wireless connectivity solutions that require energy-efficient, scalable, and cost-effective chipsets. North American enterprises are investing in IoT to optimize operations, enhance customer experiences, and generate new revenue streams, thereby increasing demand for specialized wireless chipsets. The IoT market in North America is expected to reach over USD 400 Billion by 2030, with wireless connectivity chips being a critical component of this growth.
Regulatory Support and Spectrum Allocation
Supportive regulatory policies and strategic spectrum allocations by government entities have a profound impact on the wireless chipset market. Initiatives promoting spectrum sharing, spectrum auctions, and infrastructure development have accelerated wireless technology deployment. For instance, FCC policies enabling mid-band spectrum use for 5G have facilitated faster deployment and equipment upgrades. Regulatory clarity and proactive support enable chipset manufacturers to innovate confidently while reducing compliance risks. Such regulatory environments foster competitive markets, attract investments, and accelerate adoption of wireless technologies, ultimately driving growth in the chipset industry.
Cost Reduction and Price Competitiveness
Ongoing advancements in semiconductor manufacturing processes have significantly reduced the costs of wireless chipsets. This trend enables OEMs to offer more affordable devices, thereby expanding market reach into price-sensitive segments such as budget smartphones, wearable devices, and IoT gadgets. Reduction in chipset costs also enhances profit margins for manufacturers and allows for strategic price competition among market players. As prices decline, a broader consumer base gains access to high-quality wireless technologies, further expanding the market’s footprints. Cost savings are also often reinvested into R&D, leading to further innovation and higher performance standards.
Restraints
High Capital Expenditure and R&D Costs
The development of advanced wireless chipsets requires substantial capital investment in R&D, manufacturing, and testing facilities. These high costs pose barriers for smaller players and startups attempting to compete with established giants. Additionally, continuous innovation cycles demand recurrent investments, impacting profitability and time-to-market. Vendors face pressure to balance cost reductions while upgrading product features, which can hinder market expansion or delay product launches, especially for companies with limited financial resources or access to advanced manufacturing infrastructure.
Supply Chain Disruptions
Global supply chain disruptions, such as shortages of semiconductor materials, geopolitical tensions, and logistical delays, have hampered the consistent supply of wireless chipsets. North American manufacturers are particularly vulnerable due to reliance on foreign supply chains. Such disruptions lead to production delays, increased costs, and potential loss of market share. As device manufacturers seek to meet burgeoning demand, supply constraints could limit growth potential and slow innovation adoption, especially during times of heightened geopolitical tension or global crises, necessitating more resilient supply strategies.
Technological Fragmentation and Compatibility Issues
The rapid evolution of wireless standards and technologies introduces risk of fragmentation within the market. Compatibility gaps between different wireless standards, chipsets, and devices create integration challenges for manufacturers and consumers alike. This fragmentation can result in increased costs for testing, compliance, and certification, delaying product deployment. Vendors must invest heavily in multi-standard chipsets and interoperability testing, thereby adding complexity and potentially hindering market growth, especially in regions where legacy systems coexist with next-generation networks.
Opportunities
Emergence of 6G and Beyond
The future landscape of wireless communication is poised for next-generation technologies such as 6G, which promises ultra-high speeds, near-zero latency, and pervasive connectivity. North American stakeholders are investing in research and pilot projects to develop foundational 6G standards and prototypes. These advancements offer immense growth opportunities for chipset manufacturers who can innovate at the cutting edge of wireless technology. Early commercialization of 6G-compatible chipsets could position North American firms as global leaders, attracting significant investment and expanding the market’s scope well beyond current 5G capabilities.
Investment in Semiconductor and R&D Ecosystem
Vast investment from both public and private sectors in semiconductor manufacturing and R&D is boosting the wireless chipset market. North America’s dominant ecosystem, including semiconductor foundries, research institutions, and innovation hubs, creates a fertile environment for developing high-performance, energy-efficient chipsets. These investments facilitate technology upgrades, foster startup ecosystems, and promote collaborations that accelerate innovation. The ongoing ecosystem development ensures a robust supply chain, reduces dependency on foreign manufacturers, and positions North America to lead future wireless breakthroughs.
Proliferation of Smart Infrastructure
The rapid deployment of smart infrastructure such as connected transportation, intelligent grids, and smart cities in North America offers substantial market prospects for wireless chipset manufacturers. These infrastructures demand high-capacity, reliable, and low-latency wireless connectivity solutions. Chipset manufacturers focusing on these applications can tap into lucrative growth prospects by developing specialized, ruggedized, and energy-efficient solutions. Governments’ commitments to building sustainable smart cities and infrastructure incentivize tech investments, creating stable, long-term demand channels for innovative wireless chipsets.
Growth in Wearable and Mobile Device Markets
According to recent market analyses, the wearable device segment including fitness trackers, smartwatches, and augmented reality (AR) glasses is experiencing significant expansion. North American consumers’ increasing focus on health, fitness, and mobile connectivity is fueling demand for compact, power-efficient wireless chipsets. OEMs are continually upgrading device features, prompting the need for more advanced chipsets that can support diverse wireless protocols. As mobile device proliferation persists, the market opportunities for chipset providers grow, with potential revenues reaching into hundreds of billions USD by 2034.
Challenges
Intense Competition and Price Pressure
The North American wireless chipset market is highly competitive, featuring established players like Qualcomm, MediaTek, and emerging startups. This intense rivalry drives continuous innovation but also triggers significant price competition, squeezing margins. Smaller firms often struggle to differentiate solely through price, making it challenging to sustain profitability. Large players leverage economies of scale, aggressive marketing, and extensive R&D to maintain dominance, potentially leading to market consolidation and reduced diversity in available solutions. Navigating this competitive environment remains a constant challenge for newer entrants seeking to establish market presence.
Rapid Technological Obsolescence
Wireless communication technologies evolve swiftly, and chipset manufacturers face pressure to keep pace with emerging standards and security protocols. The rapid obsolescence of older chips demands continuous innovation and frequent product updates, which increase R&D costs and complicate product lifecycle management. Failure to keep up with next-generation standards or security vulnerabilities can result in market losses and reputational damage. Industry players must invest strategically to balance innovation with compatibility and security requirements, ensuring long-term market relevance amidst pacey technological change.
Industry Statistics & Key Business Metrics
The North America Wireless Chipset Market has demonstrated robust growth trends driven by advancements in 5G technology, increasing adoption of IoT devices, and expanding smart device markets across the region. Critical to industry competitiveness and innovation, key business metrics reveal the region's strategic focus on technological leadership and supply chain resilience. As the market evolves, these indicators provide essential insights into performance, investment trends, and market penetration.
- In 2026, the North America wireless chipset market valuation is projected to reach USD 60.2 Billion, according to industry forecasts from MarketWatch.
- Annual shipment volumes of wireless chipsets are expected to surpass 850 million units by 2026, marking a significant increase from 550 million units in 2022 (IDC).
- Market penetration of 5G smartphones in North America is forecasted to hit 70% by 2026, reflecting rapid deployment and consumer acceptance (Gartner).
- Investment into 5G infrastructure and chipset R&D in the region increased by approximately 15% annually from 2020 to 2023, totaling over USD 20 Billion (U.S. FCC Reports).
- Leading chipset manufacturers in North America hold over 55% of the regional market share in 2026, with Qualcomm, Intel, and MediaTek dominating (Counterpoint Research).
- The North American IoT devices connected via wireless chipsets are projected to surpass 1.2 billion units by 2026, a growth rate of 12% year-over-year (Statista).
- Revenue from wireless chipset sales in the North American automotive sector is anticipated to reach USD 8.4 Billion by 2034, driven by increasing adoption of connected and autonomous vehicles (Frost & Sullivan).
Market Segmentation
Market segmentation for the North America Wireless Chipset Market is structured across various categories including product type, component, technology, application, end user, and geography. This segmentation enables a detailed understanding of the diverse consumer needs and technological developments influencing the market landscape.
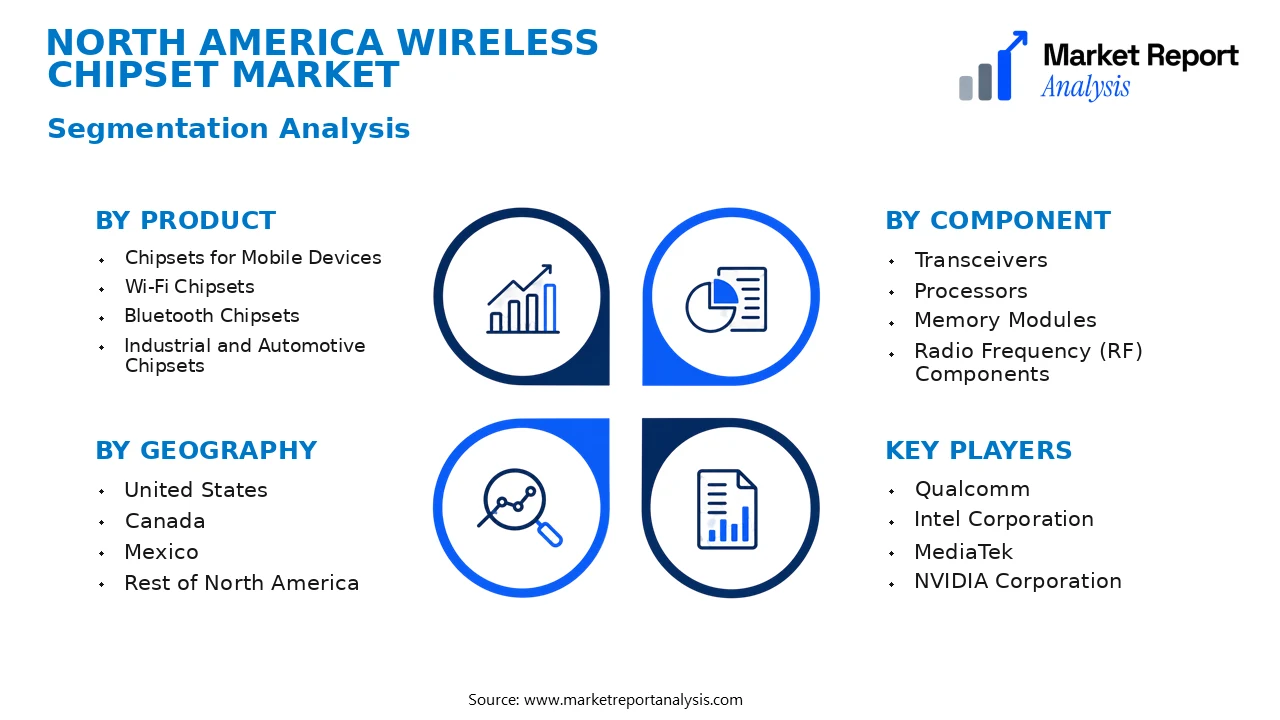
- Product
- Chipsets for Mobile Devices: These chipsets are specifically designed for smartphones, tablets, and other mobile gadgets, accounting for the largest share due to high consumer demand and rapid adoption of 5G-enabled mobile devices in North America.
- Wi-Fi Chipsets: Focused on wireless internet access, these chipsets are integral to home, enterprise, and public Wi-Fi networks, with increasing demand driven by the proliferation of smart homes and connected IoT devices.
- Bluetooth Chipsets: Widely used in wearable technology, peripherals, and smart home devices, Bluetooth chipsets are critical for short-range wireless connectivity, with rising popularity in consumer electronics.
- Industrial and Automotive Chipsets: These are tailored for industrial automation, autonomous vehicles, and telematics, representing a growing subsegment as North America increases its industrial digitization and vehicle connectivity.
- Component
- Transceivers: These components facilitate both transmitting and receiving wireless signals, essential in nearly all wireless communication devices, showing constant growth in use across various applications.
- Processors: These are the core of wireless chipsets, ensuring efficient processing of wireless signals. Demand is escalated by advancements in faster, more energy-efficient processing technologies.
- Memory Modules: Critical for temporary data storage, these modules support high-speed data transfer, especially in data-intensive applications like streaming and cloud computing.
- Radio Frequency (RF) Components: RF components are crucial for signal transmission and reception, supporting the high-frequency ranges utilized in 5G and Wi-Fi 6, key to future-proof wireless infrastructure.
- Technology
- 5G Technology: Represents the newest wireless standard, offering faster speeds and lower latency. Its deployment is a primary growth catalyst for domestic chipsets supporting 5G applications.
- Wi-Fi 6: The latest Wi-Fi standard, designed to improve speed and reliability in dense environments, driving demand for compatible chipsets for both consumer and enterprise segments.
- Bluetooth 5.2: An upgraded standard offering extended range and better audio capabilities, fueling growth in wearable and IoT device markets.
- Sub-6 GHz and mmWave: These subcategories of 5G technology provide different performance characteristics, with mmWave supporting ultra-high-speed applications and Sub-6 GHz enabling broader coverage.
- Application
- Smartphones and Tablets: These remain the dominant applications, with extensive integration of advanced wireless chipsets to support 4G, 5G, Wi-Fi, and Bluetooth functionalities, fueling the overall market growth.
- IoT and Wearables: An expanding sector that includes fitness trackers, smart watches, and connected appliances, all thriving on low-power, efficient wireless chipsets.
- Automotive and Transportation: Wireless chipsets are integral to vehicle telematics, autonomous driving systems, and connected vehicle technologies, presenting significant growth prospects.
- Industrial Automation: Wireless chipsets facilitate IoT sensors and control systems in factories, enhancing operational efficiency and enabling Industry 4.0 initiatives.
- End User
- Consumer Electronics: Encompasses smartphones, tablets, wearables, and smart home devices, which constitute the largest end-user segment due to consumer demand for connected devices.
- Automotive: Integrates wireless technology for infotainment, navigation, and autonomous systems, with growth driven by industry shifts toward connected vehicles.
- Industrial Sector: Utilizes wireless chipsets for automation, robotics, and remote control applications, increasingly adopting 5G and Wi-Fi for enhanced connectivity.
- Healthcare: Implements wireless technology for medical devices, telemedicine applications, and sensor-based health monitoring, expanding with advancements in wireless medical tech.
- Geography
- United States: As North America's largest economy, it leads in wireless chipset adoption across all segments, driven by technological innovation and high consumer demand.
- Canada: Characterized by a strong adoption of wireless communication technology, particularly in IoT and automotive sectors, supported by significant investments in 5G infrastructure.
- Mexico: Growing markets for mobile devices and increasing integration of wireless technology in automotive and industrial applications are fueling expansion.
- Rest of North America: Includes burgeoning markets in healthcare, manufacturing, and smart city projects leveraging advanced wireless chipsets.
Competitive Intelligence
The North America wireless chipset market is characterized by high competition, dominated by key industry players such as Intel, Qualcomm, MediaTek, and Samsung. Market concentration remains elevated, with the top three companies holding a significant share of the market, which encourages rivalry and innovation. To maintain competitive advantage, firms are deploying aggressive business strategies, including substantial investments in R&D to develop cutting-edge technologies such as 5G, Wi-Fi 6, and IoT-compatible chips. Product innovation is a core differentiator, with companies focusing on enhancing power efficiency, miniaturization, and multi-functionality to meet diverse applications.
Strategic alliances and partnerships form a vital component of market expansion, fostering collaboration between chip manufacturers, telecom operators, device OEMs, and cloud service providers. Acquisitions are frequently pursued to bolster technological capabilities and market reach, exemplified by Qualcomm’s acquisitions aimed at expanding into automotive and IoT segments. Companies are also focusing on expanding production capacities to support rising demand, especially fueled by 5G deployment. Continuous R&D investment underscores a commitment to differentiation through technology leadership, enabling firms to stay competitive and accelerate their market positioning in this rapidly evolving landscape.
Leading Company Profiles
The North American wireless chipset market is characterized by a competitive landscape with major players innovating in 5G, IoT, and Wi-Fi technologies. These companies leverage advanced R&D capabilities, strategic alliances, and comprehensive product portfolios to maintain market leadership and drive technological evolution.
- Qualcomm
- Intel Corporation
- MediaTek
- NVIDIA Corporation
- Broadcom Inc.
- Samsung Electronics
- Mediatek Inc.
- Marvell Technology Group
- Qorvo Inc.
Qualcomm
Qualcomm leads with its extensive portfolio in 5G modem chipsets, powering smartphones, IoT devices, and automotive applications, focusing heavily on innovation, licensing, and strategic partnerships to sustain technological dominance in North America.
Intel Corporation
Intel specializes in Wi-Fi and 5G connectivity chips, emphasizing its Bleep-technology integration, and expanding capacity in data centers and edge computing, driven by a strategic shift towards AI-enabled wireless solutions.
MediaTek
MediaTek offers a broad range of mobile and IoT chipsets, focusing on cost-effective, high-performance solutions for mid-tier smartphones and consumer electronics, with strategic investments in 5G and Wi-Fi 6E technologies.
NVIDIA Corporation
NVIDIA leverages its prowess in AI and data processing by developing wireless chipsets tailored for automotive, smart cities, and IoT applications, emphasizing scalable, high-efficiency wireless solutions to enhance connectivity capabilities.
Broadcom Inc.
Broadcom specializes in wireless connectivity chips for networking, broadband, and enterprise markets, investing heavily in advanced RF technologies and expanding manufacturing capacities to support burgeoning data demands and 5G rollout.
Samsung Electronics
Samsung’s wireless division focuses on integrating advanced 5G and Wi-Fi solutions into its consumer electronics ecosystem, pursuing strategic R&D initiatives, capacity expansion, and strategic collaborations for global market penetration.
Mediatek Inc.
Mediatek emphasizes affordable, high-performance 5G chipsets for smartphones and IoT devices, advancing its R&D footprint in North America to support the rising demand for accessible wireless connectivity solutions.
Marvell Technology Group
Marvell develops innovative wireless and Ethernet-focused ICs, expanding capacity and technology collaborations to reinforce its position in enterprise and cloud-connected environments in North America.
Qorvo Inc.
Qorvo specializes in RF solutions critical for 5G infrastructure, investing in manufacturing and technological upgrades to meet the accelerating needs of telecom operators deploying next-generation networks.
Strategic Business Developments
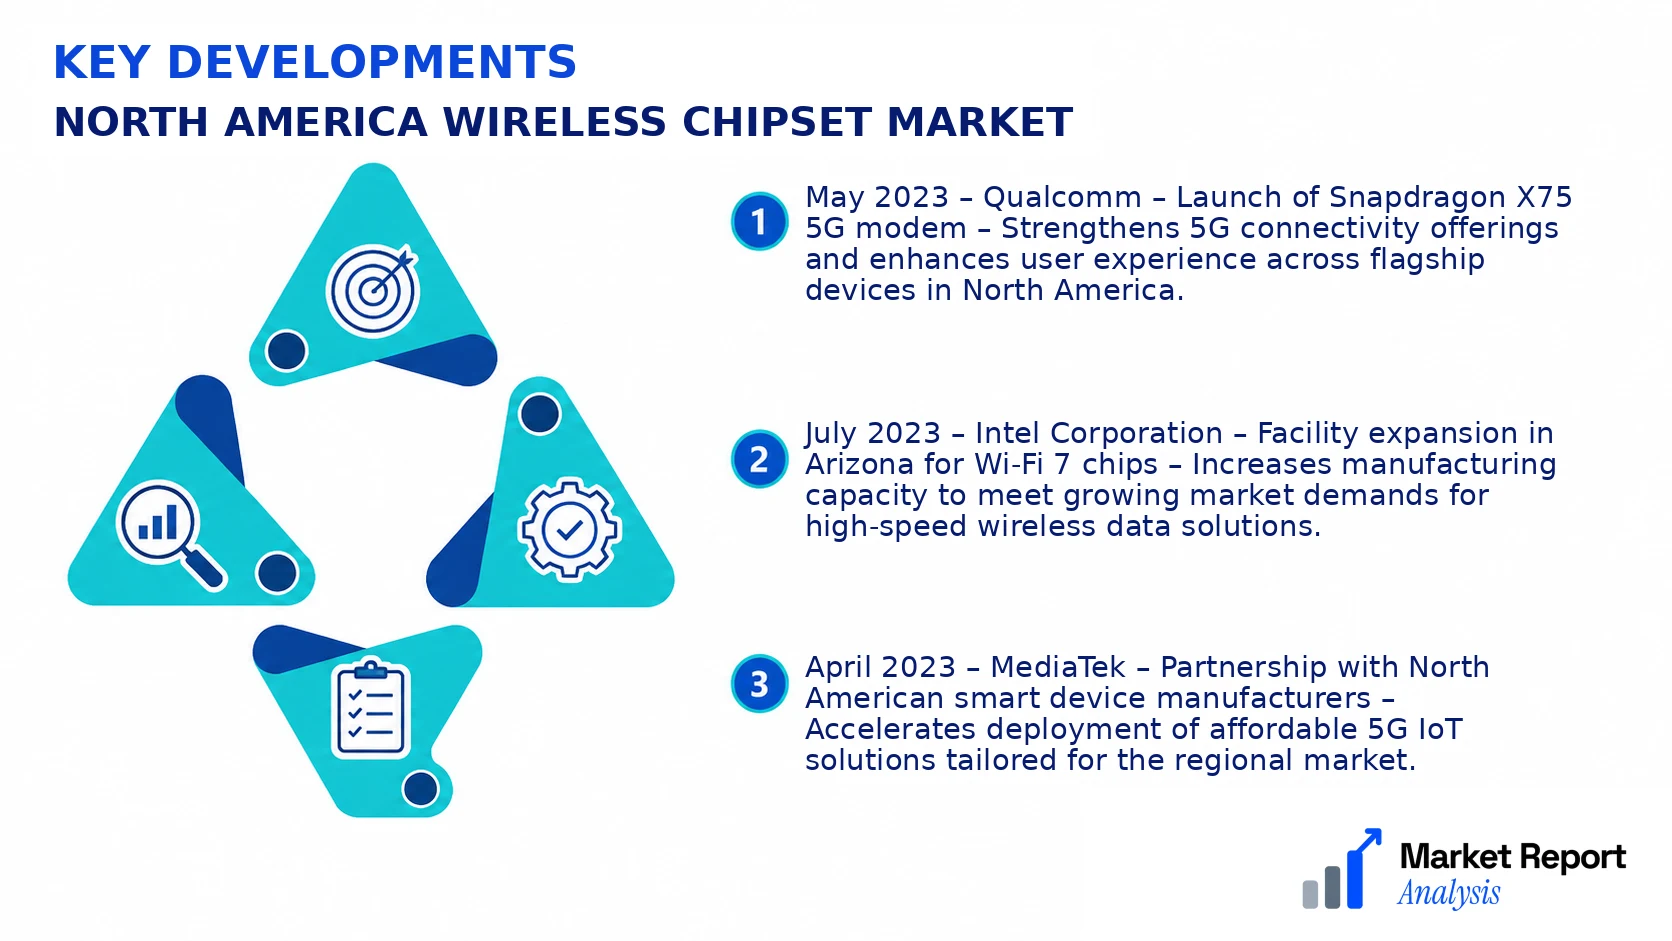
- May 2023 – Qualcomm – Launch of Snapdragon X75 5G modem – Strengthens 5G connectivity offerings and enhances user experience across flagship devices in North America.
- July 2023 – Intel Corporation – Facility expansion in Arizona for Wi-Fi 7 chips – Increases manufacturing capacity to meet growing market demands for high-speed wireless data solutions.
- April 2023 – MediaTek – Partnership with North American smart device manufacturers – Accelerates deployment of affordable 5G IoT solutions tailored for the regional market.
- June 2023 – NVIDIA Corporation – Launch of new AI-enabled wireless modules for autonomous vehicles – Enhances capabilities for smart transportation platforms, solidifying NVIDIA’s presence in automotive tech.
- August 2023 – Broadcom Inc. – Acquisition of RF component SMEs – Aims to expand technological expertise and production capacity in RF front-end modules to support 5G infrastructure projects.
Frequently Asked Questions
What is the North America Wireless Chipset Market?
The North America Wireless Chipset Market encompasses the sale and deployment of wireless chipsets used in various electronic devices such as smartphones, tablets, IoT devices, and automotive applications. It reflects technological advancements and adoption rates in the region.
What is the current market size of North America Wireless Chipset Market?
As of 2026, the North America Wireless Chipset Market is valued at approximately USD 47 Billion, driven by increasing smartphone penetration, expansion of 5G networks, and the rising adoption of connected devices across industries within the region.
What factors are driving the North America Wireless Chipset Market?
Key drivers include the proliferation of 5G connectivity, rising adoption of IoT devices, technological advancements in wireless communication, increasing demand for high-speed internet, and strong investments in telecommunications infrastructure in North America.
Which region dominates the North America Wireless Chipset Market?
The United States dominates the North American Wireless Chipset Market owing to its advanced telecom infrastructure, higher consumer electronics penetration, and substantial investments by leading tech firms in wireless technology development.
Which segment is expected to grow the fastest?
The 5G wireless chipset segment is projected to exhibit the fastest growth rate, fueled by the increasing rollout of 5G networks and the rising deployment of 5G-enabled devices across industrial, commercial, and consumer segments.
Who are the leading companies operating in the North America Wireless Chipset Market?
Major players include Qualcomm Incorporated, Intel Corporation, MediaTek Inc., Broadcom Inc., and Texas Instruments, all of which are focusing on innovation and strategic partnerships to strengthen their position in the rapidly growing market.
Analyst Perspective
The North America Wireless Chipset Market is poised for sustained growth, driven by ongoing advancements in 5G technology and its expanding application across consumer electronics, automotive, and industrial sectors. Long-term, the market is expected to mature with increased integration of AI capabilities within wireless modules, facilitating smarter, more efficient devices. Commercial opportunities are substantial in sectors like autonomous vehicles and IoT deployments, where high-performance, low-latency chipsets are critical. Technology evolution will likely concentrate on enhancing power efficiency, miniaturization, and secure connectivity, responding to escalating cybersecurity concerns and device complexity. Investment priorities should focus on R&D for next-generation chipsets and strategic partnerships among major players to accelerate innovation cycles. The region’s competitive landscape is intensifying, with key vendors investing heavily to expand their market share. North America’s growth potential remains robust, especially with its mature infrastructure and early adoption culture, positioning it as a leader in the transition towards pervasive wireless connectivity. Overall, strategic agility and continuous innovation will be essential for long-term success.
