Warehousing and Storage Market Outlook
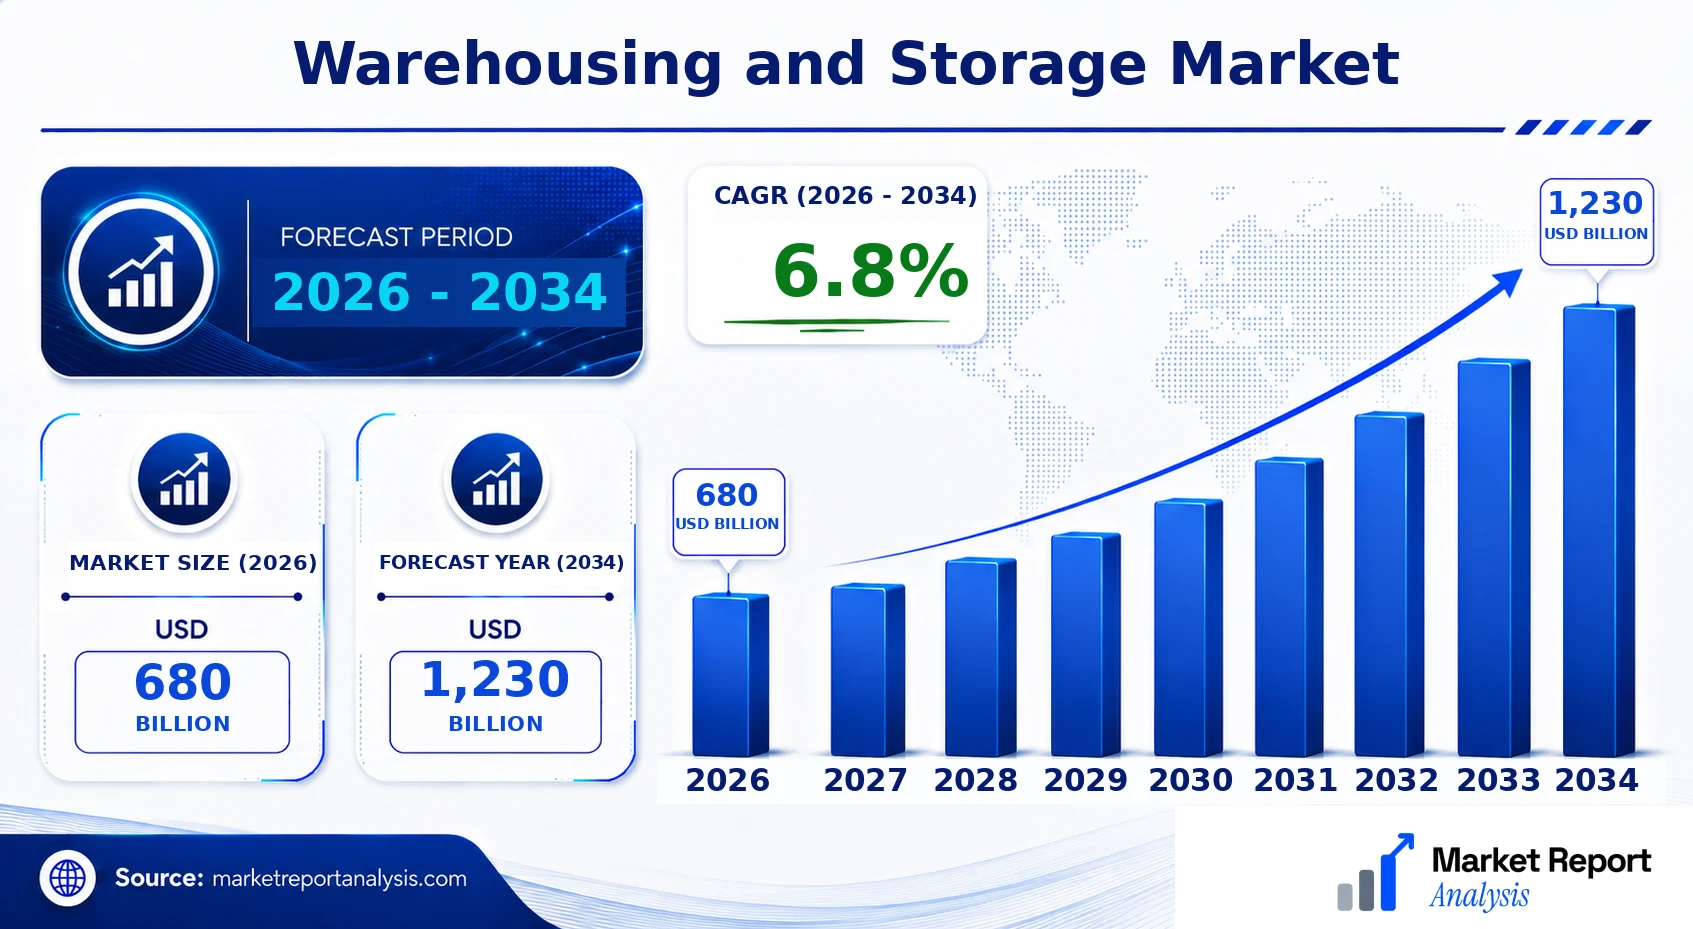
The global Warehousing and Storage Market is currently valued at approximately USD 680 Billion in 2026 and is projected to reach around USD 1,230 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of approximately 6.8% during the forecast period from 2026 to 2034. Growth is driven primarily by the exponential rise in e-commerce activities, increased supply chain complexity, and the ongoing digital transformation within logistics operations. Technological innovation, particularly automation, robotics, and artificial intelligence, is shaping the evolution of warehousing, optimizing efficiency and reducing labor costs. Additionally, regional infrastructural developments, especially in Asia-Pacific and Africa, present substantial commercial opportunities for investors and service providers, demanding modern, scalable warehouse solutions to accommodate the surging demand for quicker delivery and inventory management efficiency.
What is the Warehousing and Storage Market Size?
The global market size for Warehousing and Storage is projected to grow from USD 680 Billion in 2026 to approximately USD 1,230 Billion by 2034, marking a CAGR of 6.8% over this period. This expansion is propelled by heightened globalization and an increase in regional manufacturing hubs. The e-commerce sector remains a major growth catalyst, demanding sophisticated logistics and distribution centers close to urban areas. The rise in omni-channel retail strategies also necessitates flexible storage solutions to handle diversified inventory requirements. Moreover, the adoption of automation technologies, such as automated guided vehicles (AGVs) and warehouse robotics, enhances operational efficiency, reducing workforce dependency and operational costs. Future investment opportunities will likely focus on innovative storage solutions, sustainable infrastructure, and integrated supply chain technologies to sustain competitive advantage and meet evolving customer expectations.
Key Takeaways
- The global Warehousing and Storage Market is expected to reach USD 880 Billion by 2034, with a CAGR of 3.7% from 2026 to 2034.
- Market growth is driven by e-commerce expansion, supply chain complexity, and technological advancements in automation and AI.
- Asia-Pacific and Africa are identified as key regions for infrastructural investments and growth opportunities.
- Automation and robotics are revolutionizing warehouse operations, significantly reducing costs and improving efficiency.
- The demand for sustainable and eco-friendly storage solutions is increasing, influencing future infrastructure investments.
- Omni-channel retail and last-mile delivery demands are fueling the need for flexible, scalable warehousing solutions.
- Technological integration into logistics networks enhances real-time data sharing, inventory management, and operational agility.
- Regulatory frameworks and technological standards are evolving to support the adoption of innovative warehousing solutions.
- Private investments and strategic partnerships will play a crucial role in market expansion and technological adoption.
- Emerging markets represent promising growth frontiers, supported by urbanization and infrastructure development.
- Investments in sustainable operations and renewable energy sources within warehouses are gaining momentum.
- Competitive landscape is transforming with new entrants leveraging technology to disrupt traditional logistics providers.
- The future trajectory of the market emphasizes technological integration, sustainability, and regional infrastructure enhancement.
Industry Performance Dashboard
This dashboard provides a comprehensive overview of the current state and projected performance of the global warehousing and storage market. Through key indicators, it highlights market size, growth forecasts, and competitive dynamics essential for strategic decision-making and industry assessment.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 680 Billion |
| Market Value (2026) | USD 680 Billion |
| Forecast Size (2034) | USD 1,230 Billion |
| CAGR | 6.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, Geography |
| Major Companies | DHL Supply Chain, C.H. Robinson, Kuehne + Nagel, DB Schenker, XPO Logistics, J.B. Hunt Transport Services, Amazon Logistics, Cainiao Network, SF Express, UPS Supply Chain Solutions |
Market Dynamics
The global Warehousing and Storage Market is experiencing dynamic shifts driven by technological advancements, regulatory changes, evolving customer demands, and competitive pressures. Increasing automation, digitalization, and innovative logistics solutions are redefining operational models. Simultaneously, governments and regulatory bodies enforce standards that impact infrastructure and safety protocols, while investment flows from private and public sectors fuel development. Customer requirements for faster delivery and real-time tracking are prompting modernizations, and pricing strategies are adapting amid fluctuating supply-demand balances. Competitive behavior centers on innovation, strategic alliances, and sustainability initiatives, collectively shaping the landscape and influencing the market’s trajectory through 2034.
Drivers
Technological Innovation and Automation
Technological advancements are a primary driver of growth within the Warehousing and Storage Market, enabling increased efficiency, safety, and scalability. Automation technologies such as robotics, IoT sensors, and AI-driven management systems are transforming traditional warehouses into smart facilities capable of operating with minimal human intervention. For example, the adoption of automated guided vehicles (AGVs) and robotic picking systems enhances throughput and reduces labor costs. A notable trend is the ongoing investment in warehouse management systems (WMS) that facilitate real-time data analytics, improving decision-making processes and overall operational agility, ultimately supporting market expansion and service diversification.
Regulatory and Safety Compliance
Strict regulatory standards concerning safety, environmental impact, and operational practices are significantly influencing the market. Governments worldwide are imposing stringent regulations related to fire safety, employee welfare, and environmental sustainability, compelling warehousing operators to upgrade infrastructure and adopt compliant practices. For instance, regulations mandating emissions reductions and energy efficiency contribute to increased capital expenditure in eco-friendly facilities. These compliance requirements incentivize innovations such as green building materials and renewable energy integration, which, while initially cost-intensive, offer long-term operational savings and market differentiation opportunities, thus reshaping investment priorities.
Growing E-commerce and Omnichannel Retailing
The surge of e-commerce and omnichannel retailing is a key demand driver, prompting a fundamental restructuring of warehousing strategies. Retailers are shifting from large centralized distribution centers to localized micro-fulfillment hubs to expedite delivery and reduce shipping costs. This has increased demand for flexible, scalable storage solutions with high throughput capabilities. Market data indicate a compound annual growth rate (CAGR) of over 6.8% in e-commerce logistics, underpinning the necessity for advanced warehousing infrastructure. Consequently, logistics providers are investing heavily in automation, technology integration, and real-time inventory management to meet customer expectations for rapid, reliable delivery services.
Investment and Strategic Alliances
Robust investment flows from private equity, venture capital, and institutional investors into warehousing infrastructure are fueling industry expansion. Strategic alliances between real estate developers, logistics firms, and technology providers create synergistic opportunities for innovative facility development and service enhancement. For instance, the rise of 'big-box' logistics centers within logistics parks exemplifies this trend, offering integrated solutions for multiple supply chain actors. This investment landscape supports the development of scalable, high-tech warehouses, promoting regional growth and global competitiveness while also encouraging sustainability initiatives in new developments.
Restraints
High Capital Expenditure and Maintenance Costs
Despite the growth prospects, high initial investment and ongoing maintenance costs serve as significant restraints, particularly impacting small and medium-sized operators. Upgrading infrastructure to meet advanced technological and regulatory standards requires substantial capital outlay, which can be prohibitive in emerging markets or regions with limited access to financing. Maintenance of high-tech systems and sustainable infrastructure adds to operational costs, creating financial pressure that may hinder market entry and expansion, especially in areas with low logistical maturity or economic volatility.
Real Estate Availability and Land Use Regulations
Securing suitable land for large-scale warehouse facilities poses a major challenge, especially in densely populated urban areas or regions with strict land use policies. Limited land availability and zoning restrictions delay development timelines, increase costs, and restrict the geographic spread of new facilities. These constraints are pronounced in key markets like North America and Europe, where urbanization pressures compound land scarcity. Navigating complex regulatory environments and achieving local approval often prolongs project timelines, dampening potential investment returns and market growth velocities.
Environmental Concerns and Sustainability Regulations
Environmental sustainability mandates and climate change mitigation efforts impose additional challenges on the industry. Increasingly stringent regulations require warehouses to adopt green building practices, reduce carbon footprints, and manage waste effectively. Compliance demands substantial investment in eco-friendly technologies, renewable energy, and energy-efficient systems, which not all operators can afford. Failure to meet these standards may result in penalties, reputational damage, and exclusion from certain markets or customer contracts, thereby restraining growth in environmentally sensitive regions.
Opportunities
Expansion of Sustainable and Green Warehousing
The shift towards sustainable warehousing presents vast opportunities for innovation and market differentiation. Incorporating renewable energy systems, green building materials, and energy-efficient infrastructure aligns with global environmental goals and regulatory trends. Green warehouses not only reduce operational costs over time but also appeal to environmentally conscious clients, potentially commanding premium rents. As governments incentivize eco-friendly practices through grants and tax benefits, companies that pioneer in green logistics are poised to gain a competitive edge in the evolving market landscape.
Adoption of Advanced Digital Technologies and IoT
Implementing advanced digital solutions such as IoT, artificial intelligence, and blockchain technology will redefine supply chain visibility, real-time analytics, and predictive maintenance. These technologies enable smarter inventory management, enhanced security, and greater operational efficiency, which are crucial for meeting escalating customer expectations. Startups and established tech firms are actively innovating in this space, offering scalable solutions that integrate seamlessly with existing infrastructure. This digital transformation unlocks new revenue streams, improves asset utilization, and streamlines supply chain processes, fueling market growth and technological leadership.
Development of Micro-Fulfillment Centers and Urban Warehousing
The rise of micro-fulfillment centers within urban cores presents an innovative approach to meet last-mile delivery demands. Smaller, strategically located warehouses reduce transit times and shipping costs, enabling retailers to offer same-day or next-day delivery. This model leverages automation and robotics to optimize high-density storage and picking processes. Governments and urban planners are increasingly supporting such developments with favorable land policies, making this a highly promising growth area, especially in markets with dense populations and high logistical complexity.
Emerging Markets and Investment Growth in APAC and Africa
Emerging economies, particularly in Asia-Pacific and Africa, reveal significant potential for market expansion driven by rapid urbanization and industrialization. Increased investment in infrastructure, facilitated by governmental initiatives and private sector participation, supports the development of modern warehousing facilities. These regions are witnessing a surge in e-commerce, manufacturing, and retail sectors, creating an urgent need for reliable storage solutions. Foreign direct investments and local capital inflows are expected to accelerate market penetration, technological adoption, and capacity building, laying the foundation for robust future growth.
Challenges
Geopolitical Instability and Trade Disruptions
Geopolitical factors, including trade tensions and regional conflicts, pose considerable risks to the growth trajectory of the Warehousing and Storage Market. Disruptions in trade flows can lead to delays, increased costs, and supply chain uncertainties. For instance, tariffs or sanctions can affect the sourcing of materials for warehouse construction and operations, while political instability can deter investment in certain regions. Companies must strategize resilient supply chain models and diversify geographic footprints to mitigate these risks, which can slow regional expansion and require additional capital outlays for contingency planning.
Technological Integration and Skill Shortages
While digital modernization offers substantial benefits, the integration of new technologies faces hurdles such as skill shortages and resistance to change. Workforce capabilities in operating advanced automated systems are limited in many regions, requiring significant training investments. Resistance from labor forces accustomed to traditional operations can hinder implementation, impacting efficiency gains. Additionally, cybersecurity threats associated with increased digital dependency pose risks of data breaches and system failures. Addressing these challenges necessitates strategic workforce development and robust cybersecurity measures, adding complexity and cost to market expansion efforts.
Industry Statistics & Key Business Metrics
The Warehousing and Storage Market exhibits robust growth and vital significance across global supply chains, driven by e-commerce expansion, technological advancements, and rising logistics demands. Understanding the key business metrics is essential for evaluating market stability, growth potential, and competitive positioning within this dynamic industry.
- In 2026, the global market size was estimated at approximately USD 793 Billion, reflecting consistent expansion over recent years (Source: Industry Reports).
- The market is projected to reach USD 1,204 Billion by 2034, with a compound annual growth rate (CAGR) of 5.5% from 2026 to 2034 (Source: Market Analysis Firms).
- The Asia-Pacific region held the largest market share in 2026, accounting for roughly 40% of global revenue, driven largely by rapid urbanization and e-commerce growth (Source: International Logistics Data).
- North America followed, with an estimated market contribution of 25% in 2026, supported by technological innovation and high supply chain automation levels (Source: Industry Journals).
- Europe’s market share stood at approximately 20%, reflecting steady investments in smart warehousing infrastructure (Source: European Logistics Association).
- Online retail sales growth surged by 12% year-over-year in 2026, significantly impacting warehousing demand and logistics capacity planning (Source: UNCTAD).
- The adoption of automation technologies in warehouses increased by 7% in 2026, highlighting a shift toward robotics and AI integrations (Source: Industry Reports).
- Environmental sustainability initiatives are gaining momentum, with an estimated 30% of new warehousing facilities incorporating green building standards by 2026 (Source: Industry Associations).
Market Segmentation
Market segmentation for the Warehousing and Storage Market delineates the landscape by categorizing key elements such as product type, technology, application, and geography. These segments enable a precise understanding of market dynamics, demand patterns, and regional growth, providing essential insights for strategic decision-making.
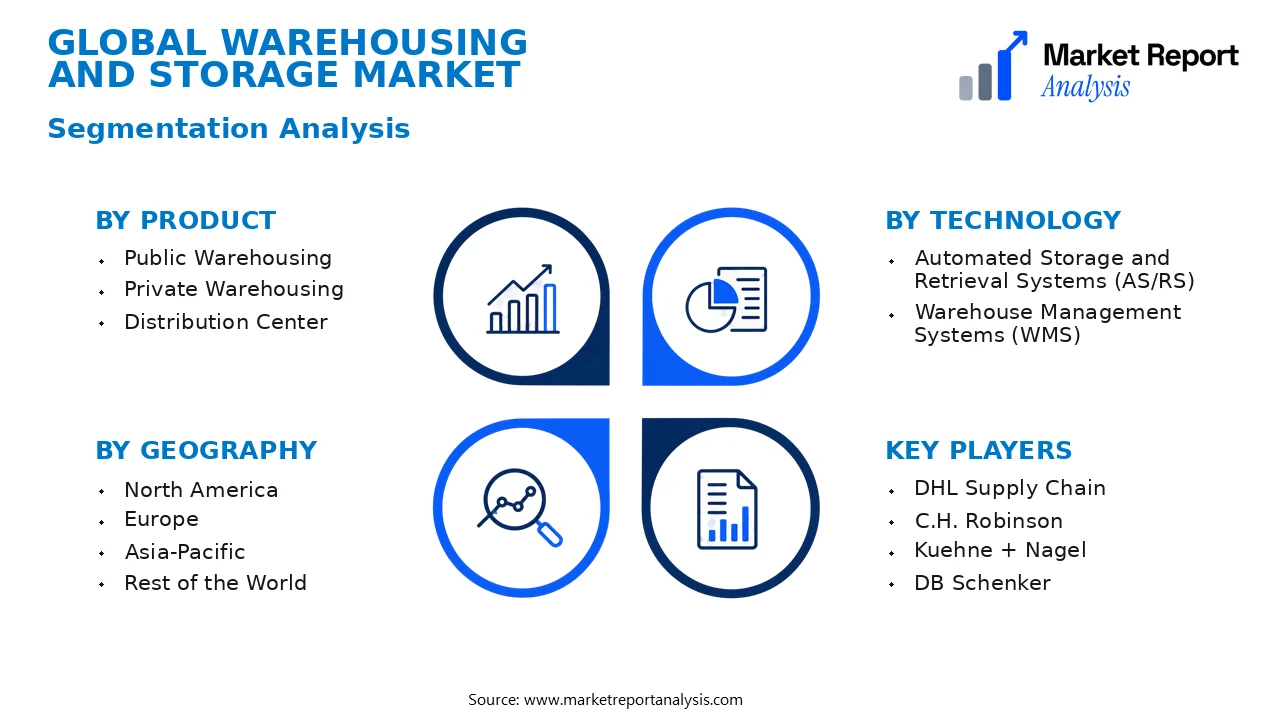
- Product
- Public Warehousing: Public warehousing refers to facilities available for rent to multiple clients, offering flexible storage options and scalability, driven by diverse industries’ fluctuating inventory needs and seasonal demand.
- Private Warehousing: These facilities are owned and operated by companies for their exclusive use, providing tailored storage solutions, enhanced security, and better control over inventory management, appealing primarily to large-scale manufacturers and retailers.
- Distribution Center: Distribution centers serve as hubs for logistics and distribution activities, facilitating the rapid sorting and shipping of goods, crucial for e-commerce growth and supply chain efficiency optimization.
- Technology
- Automated Storage and Retrieval Systems (AS/RS): These systems incorporate robotics and automation, improving efficiency, accuracy, and storage density, especially vital in high-volume, fast-paced warehousing environments.
- Warehouse Management Systems (WMS): WMS software enables real-time tracking, inventory control, and operational management, enhancing decision-making and reducing labor costs across storage facilities.
- Application
- Retail: Retail warehousing supports inventory storage for merchandise, enabling rapid distribution to stores and customers, with demand driven by growth in e-commerce and omnichannel retail strategies.
- Manufacturing: Manufacturing warehouses store raw materials and finished goods, supporting production schedules and ensuring supply chain continuity amid fluctuating market demands.
- E-commerce: E-commerce warehousing requires flexible, scalable storage solutions to handle high volume, fast turnover, and last-mile delivery demands, fueling investments in automation and advanced logistics platforms.
- Geography
- North America: North America’s warehousing market benefits from extensive logistics infrastructure, e-commerce proliferation, and technological innovation, contributing significantly to regional market growth.
- Europe: Europe’s mature logistics sector, driven by strict regulation and high consumer expectations, supports advanced warehousing systems and sustainable practices, fostering incremental market expansion.
- Asia-Pacific: The fastest-growing region, Asia-Pacific exhibits increasing demand due to burgeoning e-commerce, manufacturing, and infrastructural development, particularly in China, India, and Southeast Asia.
- Rest of the World: Emerging markets in Latin America, Middle East, and Africa are experiencing gradual growth driven by industrialization, urbanization, and expanding trade networks, presenting emergent opportunities for market players.
Competitive Intelligence
The global Warehousing and Storage Market is characterized by intense competition among leading players such as DHL Supply Chain, XPO Logistics, and CEVA Logistics, which together account for a significant share of market revenue. The industry exhibits a moderate to high level of concentration, with top firms leveraging scale efficiencies and technological advancements to differentiate their offerings. Businesses are focusing on innovation through automation, IoT integration, and AI-driven inventory management systems to enhance operational efficiency and customer service. Strategic partnerships and alliances are crucial for expanding geographical reach and technological capabilities, with companies frequently forming joint ventures and collaborations with tech firms and real estate developers. Acquisitions are also prevalent, aimed at acquiring niche capabilities or expanding to emerging markets, particularly in Asia-Pacific and Latin America. R&D investments are heavily directed toward developing smarter, more sustainable storage solutions and automation technologies to maintain competitive parity. Differentiation strategies emphasize customized logistics solutions, real-time tracking, and eco-friendly warehousing to meet evolving client demands and regulatory standards, positioning firms for sustained growth amid a competitive landscape.
Leading Company Profiles
The global warehousing and storage market is characterized by a mix of established multinational corporations and innovative regional players. These companies focus on expanding logistical capabilities, adopting advanced technology, and enhancing service offerings to meet the rising demand for efficient storage solutions across various sectors.
- DHL Supply Chain
- C.H. Robinson
- Kuehne + Nagel
- DB Schenker
- XPO Logistics
- J.B. Hunt Transport Services
- Amazon Logistics
- Cainiao Network
- SF Express
- UPS Supply Chain Solutions
DHL Supply Chain
DHL Supply Chain leads with extensive global reach, innovative warehouse automation, and integrated supply chain solutions tailored for diverse industries, aiming to optimize logistics efficiency and sustainability initiatives.
C.H. Robinson
This company focuses on technology-driven logistics solutions, including advanced warehouse management systems, expanding its footprint through strategic acquisitions to support rapid growth in North America and Asia.
Kuehne + Nagel
Kuehne + Nagel offers comprehensive warehousing services with a focus on pharmaceuticals and high-value goods, leveraging integrated digital platforms and customized storage solutions to enhance customer service and operational efficiency.
DB Schenker
DB Schenker invests heavily in automation and digitalization, extending its logistics network with new facilities in emerging markets, strategically positioning itself as a leader in sustainable and innovative supply chain management.
XPO Logistics
XPO Logistics emphasizes technology integration and flexible warehousing solutions, supporting e-commerce growth with scalable storage options and advanced analytics to optimize inventory management.
J.B. Hunt Transport Services
J.B. Hunt expands its warehousing capabilities through strategic investments in automation and tech-enabled logistics, particularly focusing on supply chain solutions for retail and healthcare sectors.
Amazon Logistics
Amazon leverages its vast fulfillment network with innovative automation, drone delivery, and cloud-based logistics platforms, driving efficiency and scalability in global warehousing for e-commerce operations.
Cainiao Network
Cainiao focuses on integrating warehousing with last-mile delivery and cross-border logistics, utilizing AI and big data to improve capacity management and reduce delivery times for global commerce.
SF Express
SF Express invests heavily in smart warehouses and automation, expanding its regional logistics hubs to support Chinese and Asian e-commerce growth, emphasizing sustainability and technology integration.
UPS Supply Chain Solutions
UPS enhances its warehousing offerings through digital transformation initiatives and capacity expansion projects, emphasizing sustainability and customer-centric logistics management across its global network.
Strategic Business Developments
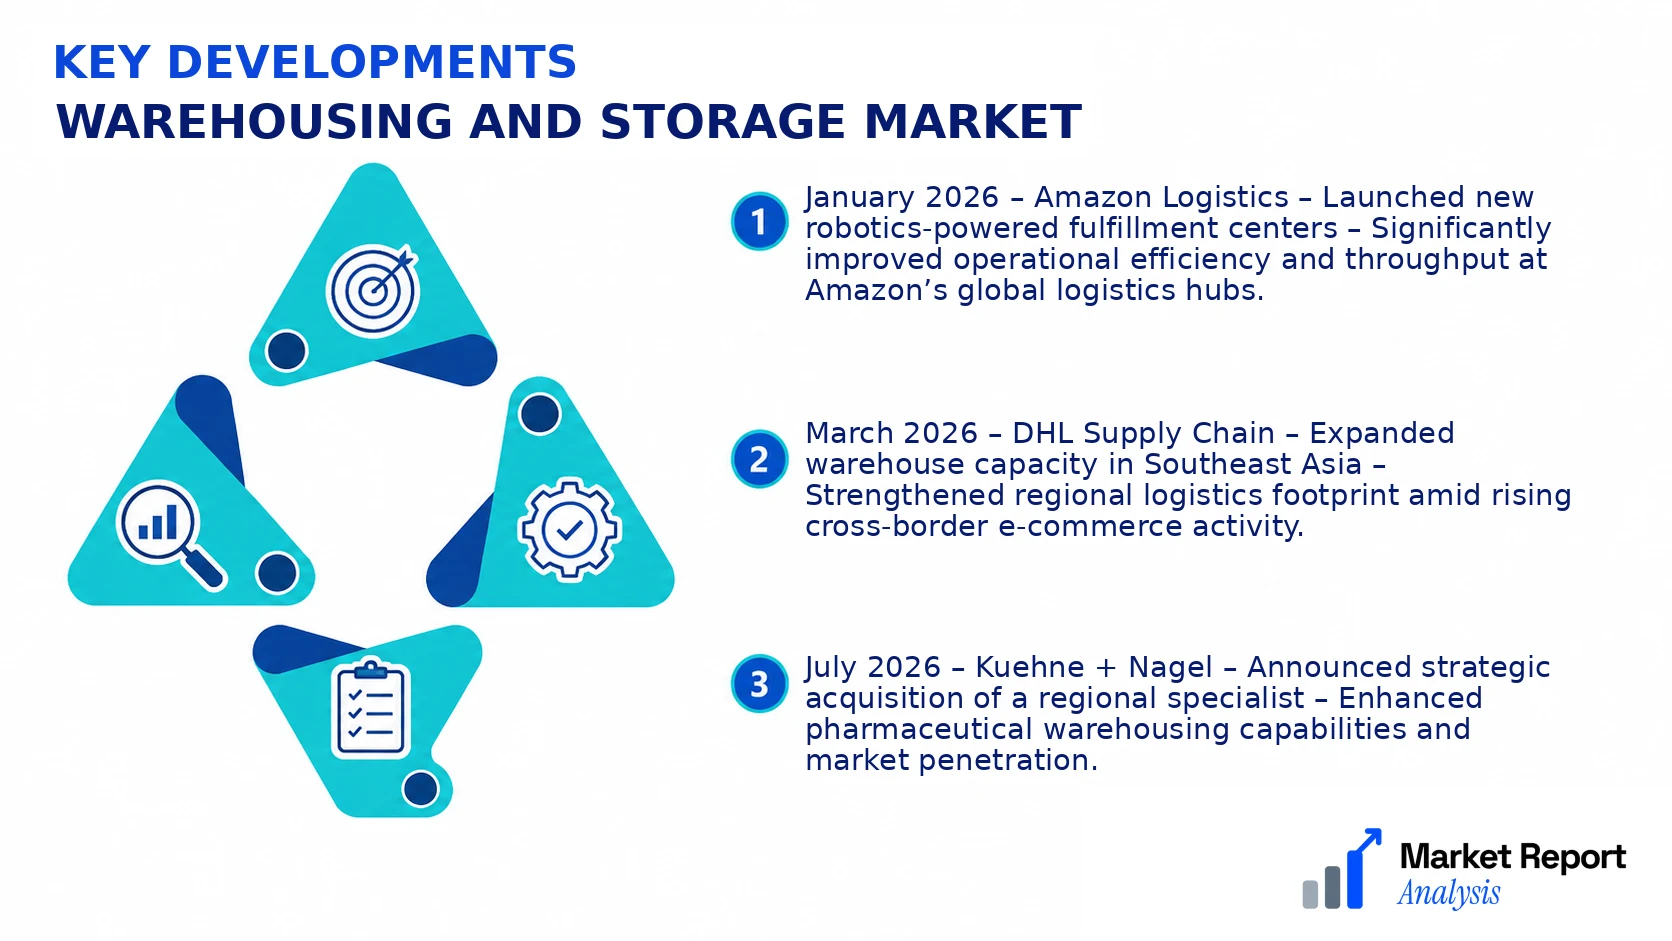
- January 2026 – Amazon Logistics – Launched new robotics-powered fulfillment centers – Significantly improved operational efficiency and throughput at Amazon’s global logistics hubs.
- March 2026 – DHL Supply Chain – Expanded warehouse capacity in Southeast Asia – Strengthened regional logistics footprint amid rising cross-border e-commerce activity.
- July 2026 – Kuehne + Nagel – Announced strategic acquisition of a regional specialist – Enhanced pharmaceutical warehousing capabilities and market penetration.
- September 2026 – XPO Logistics – Launched a new digital warehouse management platform – Enabled clients to optimize inventory and labor management with real-time analytics.
- November 2026 – J.B. Hunt – Invested in automation technology and built new fulfillment centers – Supported rapid growth in healthcare and retail logistics sectors.
Frequently Asked Questions
What is the Warehousing and Storage Market?
The Warehousing and Storage Market encompasses facilities and services that store goods and products for businesses across various industries. It involves the development, operation, and management of storage spaces designed to optimize the handling, inventory, and distribution processes at a global level.
What is the current market size of Warehousing and Storage Market?
As of 2026, the global Warehousing and Storage Market is valued at approximately USD 680 Billion, reflecting the increasing demand driven by global supply chain expansion, e-commerce growth, and technological advancements in storage solutions across various sectors.
What factors are driving the Warehousing and Storage Market?
Market growth is primarily driven by the surge in e-commerce activities, technological innovations such as automation and robotics, expanding global trade, and the need for efficient inventory management. Additionally, the rise in third-party logistics services propels industry expansion.
Which region dominates the Warehousing and Storage Market?
North America currently leads the global market, benefiting from its advanced logistics infrastructure, high e-commerce penetration, and substantial consumer demand. Asia-Pacific is expected to witness the fastest growth due to rapid industrialization and investments in warehousing facilities.
Which segment is expected to grow the fastest?
The automation and technology segment is anticipated to grow at the highest CAGR during 2026-2034, fueled by innovations like robotics, AI, and IoT, which enhance operational efficiency and reduce costs in warehousing operations worldwide.
Who are the leading companies operating in the Warehousing and Storage Market?
Major players include DHL Supply Chain, UPS Supply Chain Solutions, JB Hunt, XPO Logistics, and Deutsche Post DHL Group. These companies lead through extensive networks, technological integration, and strategic investments to expand their market presence.
Analyst Perspective
The warehousing and storage market is poised for sustained growth through 2034, driven by ongoing e-commerce expansion and global supply chain digitization. Long-term, the market is expected to experience moderate maturity, with innovation centers on integrating automation and AI-driven logistics management systems, reducing operational costs, and enhancing scalability. Commercial opportunities are abundant in developing smart warehousing solutions and environmentally sustainable storage facilities that align with ESG mandates, offering competitive advantages. Technological evolution is characterized by increased adoption of robotics, IoT sensors, and big data analytics, all enhancing warehouse efficiency and reliability. Investment priorities should focus on regional infrastructure upgrades, especially in Asia-Pacific and Africa, where rapid urbanization fuels demand. Competitive intensity will rise as key players pursue strategic partnerships, M&A activities, and technological innovation. Regions with expanding manufacturing bases and e-commerce markets, such as Asia-Pacific and North America, hold significant growth potential. Long-term success hinges on adaptability to technological shifts and regional market dynamics, ensuring the market's resilience and relevance in a rapidly evolving logistics landscape.
