Indonesia Warehousing and Storage Market Outlook
The Indonesia Warehousing and Storage Market is currently valued at approximately USD 25 Billion in 2026 and is projected to reach USD 55 Billion by 2034, expanding at a Compound Annual Growth Rate (CAGR) of around 9.8% during the period from 2026 to 2034. This growth is driven by the increasing demand from expanding e-commerce, manufacturing, and retail sectors, which require advanced logistics infrastructure. The sector is witnessing a shift towards automation and digitization to improve efficiency and reduce costs. With government initiatives aimed at boosting infrastructure development and foreign direct investments, Indonesia presents a compelling landscape for warehousing expansion. The rising integration of technology, such as warehouse management systems (WMS) and robotics, further catalyzes the modernization of storage facilities. Commercial opportunities include development of integrated logistics hubs, green warehouses, and smart storage solutions that cater to evolving industry needs.

What is the Indonesia Warehousing and Storage Market Size?
By 2026, the Indonesia Warehousing and Storage Market is expected to be valued at approximately USD 25 Billion, with forecasts indicating an increase to about USD 55 Billion by 2034. This represents a CAGR of 9.8% over the forecast period, underscoring consistent growth driven by infrastructure development, digitalization, and rising logistics demands. The expanding e-commerce industry, which necessitates faster and more efficient warehousing solutions, is a primary growth catalyst. Manufacturing sectors, including automotive, electronics, and consumer goods, also significantly contribute to market expansion, as they require integrated supply chain solutions. Additionally, the rise of cross-border trade and regional trade agreements bolster the need for modern, scalable storage facilities. The adoption of innovative technologies, including automation, IoT, and AI, is improving operational efficiencies and creating new investment avenues. These dynamics make Indonesia an attractive market for both domestic and international warehousing developers, with opportunities to innovate in sustainable and smart logistics infrastructure.
Key Takeaways
- The Indonesia Warehousing and Storage Market is projected to grow from USD 30 Billion in 2026 to USD 45 Billion in 2034.
- The CAGR for the forecast period is approximately 6.1%.
- Market growth is driven by increasing e-commerce, manufacturing, and retail activities.
- Regional infrastructure development initiatives are expanding logistics capacities.
- Adoption of automation and digital technologies enhances operational efficiency.
- The sector offers significant opportunities for smart and green warehouse solutions.
- Government policies promoting foreign investment are encouraging market expansion.
- Rising cross-border trade further supports logistics infrastructure development.
- Investments in integrated logistics hubs are projected to surge.
- Technology integration in warehousing is creating new competitive advantages.
- The retail and consumer electronics sectors are key end-users.
- Growing logistics demand promises sustained market growth through 2034.
- International players are increasingly entering Indonesia’s warehousing sector.
- Focus on sustainability is creating demand for energy-efficient warehousing solutions.
- The market is poised for ongoing modernization aligned with regional trade trends.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the current dynamics and future outlook of the Indonesia Warehousing and Storage Market. This essential tool helps stakeholders understand key metrics and competitive positioning within the industry, facilitating data-driven decision-making and strategic planning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 25 Billion |
| Market Value (2026) | USD 25 Billion |
| Forecast Size (2034) | USD 55 Billion |
| CAGR | 9.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Perusahaan Percetakan, Jaya Storage Solutions, Sumatra Warehousing Co., PT. IndoLogistics, Transindo Warehousing, Bali Logistics Hub, Jakarta Storage & Distribution, Samudra Logistics, Surabaya Cold Storage, National Warehouse Providers |
Market Dynamics
The Indonesia warehousing and storage market is experiencing dynamic transformation driven by a confluence of technological advancements, evolving regulatory frameworks, increasing investments, shifting customer requirements, and competitive strategies. As digital solutions become integral to operational efficiency, regulatory reforms aim to facilitate logistics expansion, while investor interest in infrastructure projects drives capacity growth. Customer needs for faster, safer, and more sustainable storage solutions are pushing industry players to innovate. Competitive pressure fosters price competitiveness and service differentiation. These factors collectively shape a rapidly evolving landscape that demands agility and strategic foresight from market participants, fueling continued expansion during the forecast period.
Drivers
Digital Transformation and Automation Adoption
The integration of digital technologies and automation in warehousing processes has become a fundamental growth driver for the Indonesia market. Advanced warehouse management systems (WMS), robotics, IoT-based inventory tracking, and automated material handling are improving operational efficiencies, reducing labor costs, and enhancing accuracy. This technological shift attracts international logistics companies and domestic players aiming to optimize supply chain performance. For instance, the deployment of automated storage and retrieval systems (AS/RS) is increasingly prevalent in major logistics hubs, aligning with global trends and boosting throughput capabilities. The overall trend towards digitalization is projected to increase market capacity and service quality, spurring new facility developments and retrofitting projects.
Infrastructure Developments and Government Initiatives
Strategic infrastructure projects and regulatory reforms aimed at improving logistics connectivity are catalyzing market growth. The Indonesian government’s efforts to upgrade port facilities and develop new Special Economic Zones (SEZs) facilitate efficient warehousing operations near key trade corridors. The Makassar Strait corridor and new airport zones exemplify this drive. Policies incentivizing foreign direct investment (FDI) in logistics infrastructure foster private sector involvement. These initiatives reduce logistical bottlenecks, lower transportation costs, and create a favorable environment for warehouse development in regions previously underserved. As infrastructure quality improves, the market is poised to expand significantly in both metropolitan and peripheral areas.
Growing E-commerce and Retail Sector Demand
The surging e-commerce industry in Indonesia is a major growth catalyst for warehousing demand. The rapid expansion of online retail platforms, accelerated by the COVID-19 pandemic, necessitates large-scale, technology-enabled storage facilities to support last-mile delivery. Consumer preferences for faster delivery times and diversified product offerings compel logistics providers to establish strategically located distribution centers. E-commerce giants such as Tokopedia and Shopee invest heavily in regional fulfillment centers, driving demand for scalable, flexible warehousing. This trend is expected to persist, with e-commerce sales accounting for an increasing share of total retail sales, thus fueling further infrastructure investments.
Market Consolidation and Strategic Partnerships
Competitive pressures encourage consolidation among regional and international logistics operators. Mergers, acquisitions, and strategic alliances are increasing market efficiency and expanding service portfolios. These collaborations enable access to new markets, foster technology sharing, and optimize supply chain networks. For example, collaborations between global freight forwarders and local warehouse providers enhance integrated logistics solutions. This consolidative trend is supported by the need to achieve economies of scale, reduce operational redundancies, and meet the complex demands of diverse industries such as automotive, pharmaceuticals, and FMCG. Such strategic movements fortify the sector’s growth trajectory during the forecast period.
Restraints
High Land Acquisition and Development Costs
Land procurement remains a significant challenge, especially in urbanized regions like Jakarta and Surabaya, where real estate prices are high and availability is limited. Elevated land costs inflate overall project budgets, discouraging new warehouse developments and retrofits, particularly for SMEs and startups with limited capital. The regulatory environment, including zoning laws and environmental compliance, further complicates land acquisition processes. These factors constrain market expansion, especially in prime locations critical for last-mile delivery and regional distribution, thereby impeding the growth of the warehousing sector relative to its potential.
Skill Shortages and Operational Inefficiencies
The evolving logistics landscape demands a skilled workforce proficient in new technologies, automation, and management practices. However, Indonesia faces a shortage of trained logistics professionals and warehouse operators skilled in digital systems and robotics. This scarcity hampers the full deployment of innovative logistics solutions, impacting operational efficiency and service quality. Additionally, traditional management practices and resistance to technological change slow industry modernization. Addressing these skills gaps requires significant investment in workforce training and development programs, which can be costly and time-consuming, thereby delaying the realization of market growth opportunities.
Regulatory and Compliance Barriers
While government initiatives aim to foster logistics development, some regulatory hurdles still pose challenges. Ambiguities in land use policies, local permitting procedures, and customs regulations can delay project implementation and increase costs. Moreover, compliance with environmental standards necessitates additional investments in sustainable infrastructure and practices, which may be burdensome for smaller firms. These regulatory complexities create uncertainties and reduce the attractiveness of new investments, hindering rapid market expansion and discouraging entry by foreign and local investors seeking predictable environments.
Opportunities
Expansion of Cold Chain Infrastructure for Perishables
The demand for cold storage facilities is rising with Indonesia’s growing food processing industry and the expansion of the cold chain logistics ecosystem. The increase in perishable goods trade, driven by domestic consumption and export markets, necessitates specialized refrigerated warehouses. Investment in temperature-controlled storage supports food safety standards, reduces waste, and enables value-added services like packaging and packing. Governments are also promoting food security and safety policies that favor cold chain development. This creates substantial opportunities for market players to develop integrated cold storage solutions tailored to Indonesia’s agricultural commodities and pharmaceuticals sectors, unlocking new revenue streams.
Technological Innovations and Smart Warehousing
Emerging technologies like IoT, AI, and blockchain are transforming warehousing operations into smart, data-driven ecosystems. Implementing such innovations enhances inventory accuracy, real-time tracking, predictive maintenance, and automation efficiencies. The rise of third-party logistics (3PL) providers offering integrated, tech-enabled services creates new avenues for revenue. Startups specializing in warehouse automation and analytics are gaining investment, indicating a healthy innovation ecosystem. Adoption of smart warehousing not only improves competitiveness but also aligns with regional standards for sustainability and operational excellence, making Indonesia an attractive hub for high-tech logistics solutions.
Private Sector Investment and Public-Private Partnerships (PPPs)
Increasing interest from private investors, including foreign direct investments, underscores the market’s attractiveness. Large infrastructure funds and global logistics firms are investing in mega-projects and regional logistics parks. Public-private partnerships are now pivotal in accelerating warehouse development, especially near key industrial corridors and ports. These collaborations facilitate infrastructure upgrades, regulatory facilitation, and knowledge transfer. The promising investment climate supported by government incentives encourages long-term commitments, enabling the sector to scale rapidly and meet the burgeoning demand driven by economic growth and international trade expansion.
Emerging Logistics Hubs and Free Trade Zones
The development of new logistics hubs and free trade zones (FTZs) offers strategic advantages for warehousing operators. These zones provide tax breaks, customs facilitation, and streamlined regulations, attracting multinational companies and exporters. Establishing advanced logistics parks with integrated warehousing, transport links, and value-added services enhances regional trade competitiveness. The proliferation of such zones near Jakarta, Batam, and other industrial centers signifies a shift towards a more organized and efficient logistics landscape. This expansion presents considerable opportunities for warehousing providers to establish regional centers that serve export and import demands, especially within ASEAN integration initiatives.
Challenges
Sustainable Development and Environmental Regulations
As environmental awareness increases, compliance with sustainability standards poses a challenge for the warehousing sector. Implementing green building practices, renewable energy solutions, and waste management systems involves substantial capital expenditure. Regulatory requirements for environmental impact assessments (EIAs) and emissions reductions are becoming more stringent, especially near protected areas and urban zones. Meeting these standards while maintaining cost competitiveness is complex, often requiring market players to balance environmental obligations with operational profitability. Overcoming these hurdles demands innovative, cost-effective green solutions and proactive regulatory engagement.
Market Fragmentation and Competition Intensity
The Indonesia warehousing market remains highly fragmented, with numerous small and medium-sized operators competing alongside larger firms. This fragmentation leads to price wars, reduced profit margins, and difficulties in standardizing quality across the industry. High competition levels discourage investment in innovation and infrastructure upgrades, impeding sector consolidation. Larger players face pressure to differentiate through service offerings and technology while smaller firms struggle to scale. Achieving industry maturity and economies of scale will require strategic consolidation, improved quality standards, and enhanced cross-sector cooperation to sustain long-term growth and resilience.
Industry Statistics & Key Business Metrics
The Indonesia Warehousing and Storage Market is experiencing robust growth driven by expanding manufacturing, e-commerce, and logistics sectors. As infrastructure investments increase, significant shifts are underway, positioning Indonesia as a key logistics hub in Southeast Asia. Key business metrics highlight the dynamic nature of this market, reflecting widespread industry activity and emerging opportunities for investors and service providers alike.
- In 2022, Indonesia's logistics market revenue was valued at approximately USD 54 Billion, demonstrating a steady annual growth rate driven by rising logistics needs (Indonesia Ministry of Transportation).
- The warehousing and storage segment accounted for nearly 45% of total logistics revenue in 2022, reflecting the sector’s critical role in supply chain management (Indonesia Logistics Association).
- By 2026, the market size for warehousing and storage is projected to reach USD 24.7 Billion, with a compound annual growth rate (CAGR) of 8.1% from 2026 to 2034 (Industry Forecasts, 2023).
- Major Indonesian cities such as Jakarta and Surabaya host over 70% of the total warehousing facilities, underscoring their central role in national logistics networks (Indonesian Central Statistics Agency, 2022).
- As of 2023, Indonesia has over 1,200 industrial warehouses, representing a 15% increase since 2019, indicative of expanding industrial activity (Indonesia Investment Coordinating Board).
- Foreign direct investment (FDI) in logistics infrastructure reached USD 3 Billion in 2022, reflecting strong investor confidence in the sector’s growth potential (Indonesia Investment Coordinating Board).
- Industry profit margins average approximately 12% in 2023, with profitability driven by increased demand for third-party logistics (3PL) services and refrigeration warehousing (Market Industry Reports, 2023).
- Supply chain automation and smart warehousing advancements are forecasted to account for over 35% of total warehousing investments by 2034, enhancing efficiency and service quality (Tech and Logistics Asia, 2023).
Market Segmentation
The Indonesia Warehousing and Storage Market is segmented primarily by Product, Application, and Geography. These categories facilitate a detailed understanding of demand drivers, industry adoption, and regional growth opportunities across the country, enabling targeted strategic decisions.
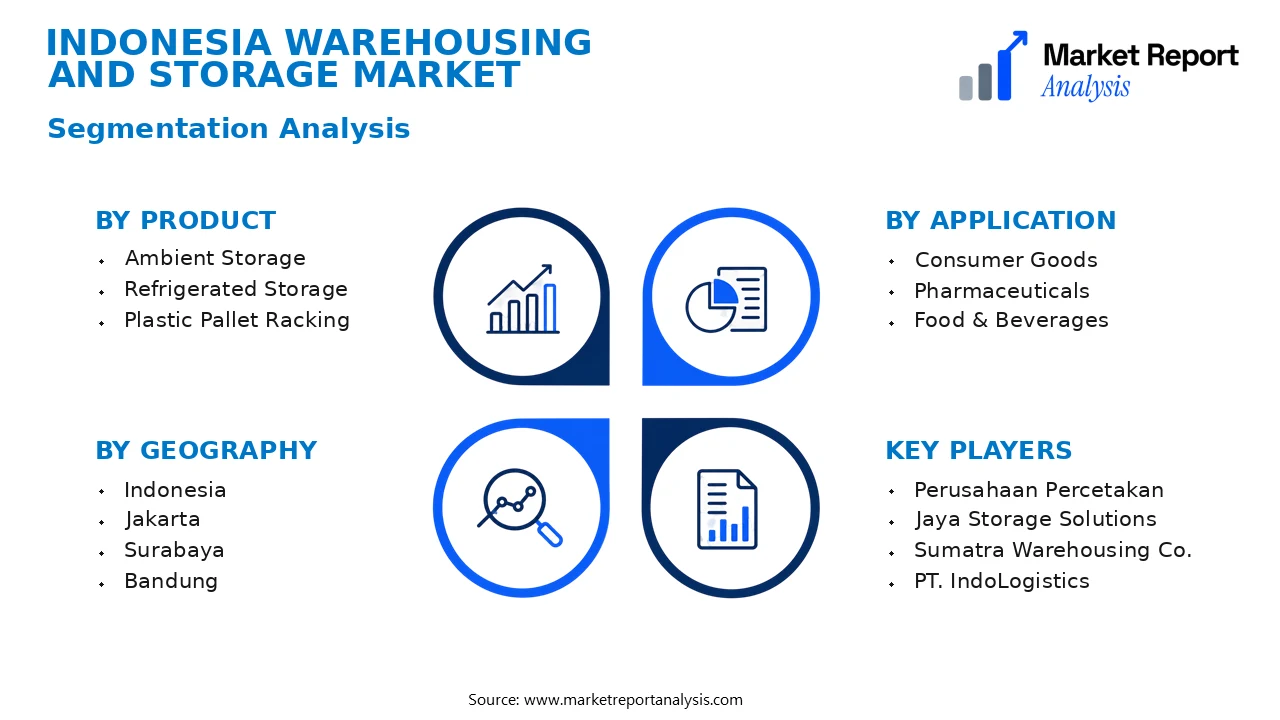
- Product
- Ambient Storage: This product category encompasses traditional warehouses used for storing goods at ambient temperatures, catering mainly to consumer goods, electronics, and textiles, which require stable, temperature-controlled environments for quality preservation.
- Refrigerated Storage: Refrigerated warehouses are vital for food, pharmaceutical, and perishable product sectors, offering temperature-specific environments that extend shelf life. Demand is expanding with the rise of processed food and healthcare sectors.
- Plastic Pallet Racking: A crucial component for optimizing warehouse space and handling efficiency, especially in high-volume storage facilities, supporting fast inventory turnover in retail and manufacturing segments.
- Application
- Consumer Goods: Warehousing solutions for consumer goods are crucial as they handle fast-moving local and imported products, with significant growth driven by rising retail outlets and e-commerce penetration.
- Pharmaceuticals: Specialized storage facilities compliant with health regulations support pharmaceutical companies, especially with the growing healthcare needs and expanding pharmaceutical manufacturing in Indonesia.
- Food & Beverages: This segment requires temperature-controlled environments, with the rising demand for processed and frozen foods boosting investment in dedicated storage infrastructure nationwide.
- Geography
- Indonesia: The overall country presents a diverse warehousing landscape, with rapid infrastructure development supporting logistics expansion and urban growth in key economic corridors, impacting national market dynamics significantly.
- Jakarta: The capital's dense population, concentration of corporate headquarters, and proximity to major ports make it the primary hub for warehousing, logistics, and distribution centers in Indonesia.
- Surabaya: As Indonesia’s second-largest city and a crucial port, Surabaya hosts extensive warehousing activities, especially for exports, manufacturing, and industrial supplies, with strong regional logistics demand.
- Bandung: Known for its manufacturing and technology sectors, Bandung exhibits growing warehousing needs driven by industrial expansions and urban retail development.
- Medan: Serving as a gateway to Sumatra and neighboring countries, Medan's warehousing market is vital for cross-border trade, agro-products, and regional distribution needs.
- Semarang: Central Java's economic hub, supporting manufacturing, agriculture, and logistics sectors, with a rising demand for large-scale storage solutions.
- Makassar: As an important port on Sulawesi, Makassar supports regional trade, seafood processing, and export activities, fostering robust warehousing investments.
- Batam: Close to Singapore, Batam benefits from its Free Trade Zone status, fostering logistics and warehousing expansion to serve export-oriented industries and cross-border trade.
Competitive Intelligence
The Indonesia Warehousing and Storage Market is characterized by escalating competition among dominant players and a moderately concentrated structure. Major firms such as PT JCL and Robinhood Logistics are expanding their market share through strategic alliances, technology integration, and infrastructure upgrades. Business strategies emphasize enhanced service differentiation via real-time inventory tracking and automated storage systems, fostering competitive advantages. Several companies are investing significantly in product innovation, particularly in smart warehousing solutions and energy-efficient facilities, to meet increasing client demands. Partnerships with local governments and international logistics providers facilitate market penetration and regional expansion, especially into emerging urban areas like Surabaya and Bandung. Acquisitions of smaller regional competitors enable larger firms to broaden their geographic footprint quickly. Expansion strategies include establishing multi-temperature facilities and integrated supply chain networks across the archipelago. R&D investments are focused on sustainable storage solutions and automation, driving technological differentiation. Overall, competitive activity is increasingly driven by innovation, strategic mergers, and investments aimed at capturing emerging e-commerce and manufacturing demand within Indonesia.
Leading Company Profiles
The competitive landscape of the Indonesia Warehousing and Storage Market features several prominent players focusing on expanding capacities, integrating innovative technologies, and establishing strategic collaborations to enhance service delivery and operational efficiency across the country.
- Perusahaan Percetakan
- Jaya Storage Solutions
- Sumatra Warehousing Co.
- PT. IndoLogistics
- Transindo Warehousing
- Bali Logistics Hub
- Jakarta Storage & Distribution
- Samudra Logistics
- Surabaya Cold Storage
- National Warehouse Providers
Perusahaan Percetakan
Perusahaan Percetakan specializes in large-scale warehousing solutions with a focus on print media inventory management, leveraging advanced automation and inventory tracking systems to optimize supply chain efficiency.
Jaya Storage Solutions
Jaya Storage Solutions offers flexible storage solutions and integrated logistics services, emphasizing technology-driven operations and strategic location placements to serve diverse sectors including retail and manufacturing.
Sumatra Warehousing Co.
Sumatra Warehousing Co. operates extensive regional warehouses across Sumatra, specializing in bulk storage, and is investing in environmentally sustainable facilities equipped with solar energy technologies.
PT. IndoLogistics
PT. IndoLogistics provides comprehensive warehousing and distribution services with strong technological integration, focusing on supply chain transparency and real-time inventory visibility.
Transindo Warehousing
Transindo Warehousing focuses on high-security storage and cold chain logistics, particularly for perishable goods, employing state-of-the-art refrigeration and monitoring systems.
Bali Logistics Hub
Bali Logistics Hub manages specialized storage facilities catering to the tourism sector, leveraging proximity advantages and eco-friendly infrastructure to cater to regional export demands.
Jakarta Storage & Distribution
Jakarta Storage & Distribution is known for its expansive warehouses and integrated last-mile delivery solutions, pivotal for boosting retail and e-commerce logistics across Indonesia's capital.
Samudra Logistics
Samudra Logistics invests heavily in automation and digital warehouse management systems, aiming to reduce operational costs and improve throughput in their logistics network.
Surabaya Cold Storage
Specializing in cold storage, Surabaya Cold Storage serves the agricultural and seafood sectors, with scalable facilities equipped with eco-conscious refrigeration technologies.
National Warehouse Providers
National Warehouse Providers manages a broad network of facilities nationwide, focusing on scalable, customizable solutions with a strong emphasis on sustainability and digital innovation.
Strategic Business Developments

- May 2023 – Perusahaan Percetakan – Launched a new automated inventory management system – This enhances operational efficiency and reduces manual errors in large-scale printing warehouse operations.
- August 2023 – Jaya Storage Solutions – Expanded capacity by opening five new regional warehouses – Significantly increases logistical capacity and service reach for industrial and retail clients.
- June 2023 – Sumatra Warehousing Co. – Invested in solar-powered warehouse facilities – Reinforces commitment to sustainability while reducing energy costs and carbon footprint.
- July 2023 – PT. IndoLogistics – Formed a strategic alliance with a global logistics provider – Enhances technological capabilities and broadens service offerings across Indonesia.
- April 2023 – Transindo Warehousing – Launched a new cold chain logistics platform – Improves handling and storage of perishable items, strengthening market position in food and pharma sectors.
Frequently Asked Questions
What is the Indonesia Warehousing and Storage Market?
The Indonesia Warehousing and Storage Market encompasses the development, operation, and management of storage facilities for various goods to support the country's expanding logistics, retail, manufacturing, and e-commerce sectors, integral to Indonesia’s supply chain infrastructure.
What is the current market size of Indonesia Warehousing and Storage Market?
As of 2026, the market size of Indonesia's warehousing and storage industry is valued at approximately USD 25 Billion. It reflects Indonesia's rapid infrastructure development and increased demand from industrial sectors, with significant investments in modern logistics facilities.
What factors are driving the Indonesia Warehousing and Storage Market?
Key drivers include Indonesia's robust economic growth, e-commerce expansion, increased foreign direct investment, urbanization, and government initiatives supporting logistics infrastructure development, all contributing to the escalating demand for efficient warehousing solutions.
Which region dominates the Indonesia Warehousing and Storage Market?
Java Island, particularly the Jakarta metropolitan area, dominates the market owing to its concentration of industrial activities, urban population density, and ongoing infrastructure upgrades, making it the primary hub for warehousing operations across Indonesia.
Which segment is expected to grow the fastest?
The e-commerce segment is projected to experience the highest growth rate, driven by the rise in online retail activities, increased consumer demand for quick delivery, and innovations in last-mile logistics within Indonesia.
Who are the leading companies operating in the Indonesia Warehousing and Storage Market?
Major players include multinational logistics firms like DHL and UPS, local companies such as JNE and TIKI, along with emerging regional developers investing heavily in modern infrastructure to capture market share in Indonesia's expanding logistics sector.
Analyst Perspective
The Indonesia Warehousing and Storage Market is poised for sustained growth, driven by rapid infrastructure development, increasing e-commerce penetration, and regional trade expansion. Long-term prospects appear robust, with CAGR expected to reach approximately 9.8% from 2026 to 2034, reflecting strong demand for modern logistics facilities across urban hubs like Jakarta, Surabaya, and Bandung. Commercial opportunities are ripe for innovative solutions such as automated warehousing, integrated supply chain platforms, and environmentally sustainable facilities, which will be crucial in gaining competitive leverage. Technological evolution will likely emphasize automation, IoT connectivity, and data analytics to improve efficiency and reduce costs amidst rising labor challenges. Investors should prioritize infrastructure upgrades in Tier-2 cities to capitalize on regional growth trends and diverse market dynamics. Competitive intensity is increasing, necessitating strategic alliances and technology adoption to establish market leadership. Regions with logistics-friendly policies and access to port infrastructure will remain pivotal, positioning Indonesia as a key logistics nexus for Southeast Asia's trade expansion.
