Saudi Arabia Warehousing and Storage Market Outlook
The Saudi Arabia warehousing and storage market is experiencing rapid growth driven by increasing logistics and e-commerce activities, diversification efforts under Vision 2030, expanding manufacturing sectors, and rising foreign investment. The market valuation stood at approximately USD 14.8 Billion in 2026, with projections indicating an ascent to nearly USD 28.2 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of about 8.4% over this period. Advancements in automation, IoT-enabled warehousing solutions, and smart logistics technologies are shaping the future landscape. Investments in new logistics parks, modernization of existing infrastructure, and government initiatives to enhance supply chain efficiency offer substantial commercial opportunities for domestic and international players. As demand intensifies across various industries, the market is poised for significant expansion, supported by regulatory reforms, economic reforms, and infrastructure upgrades that foster a more efficient warehousing ecosystem.

What is the Saudi Arabia Warehousing and Storage Market Size?
In 2026, the Saudi Arabia warehousing and storage market was valued at around USD 14.8 Billion and is projected to reach approximately USD 28.2 Billion in 2034, growing at a CAGR of 8.4% during this period. The growth is primarily driven by the rapid expansion of e-commerce, retail, and manufacturing sectors, which require efficient storage solutions. The initiation of multiple logistics parks in Riyadh, Jeddah, and Dammam supports the rising demand for large-scale warehousing facilities with modern features such as automation and real-time tracking. The government's focus on fostering a vibrant logistics ecosystem under Saudi Vision 2030, along with foreign direct investment in infrastructure development, underscores the market’s robust potential. The integration of digital technologies into warehousing operations is expected to enhance efficiency, accuracy, and cost-effectiveness, contributing to continual market expansion. Future investments are likely to target the development of sustainable, smart warehouse facilities to meet evolving supply chain demands, positioning Saudi Arabia as a regional logistics hub for the Middle East.
Key Takeaways
- The market size was approximately USD 4.2 Billion in 2026.
- The forecasted market size for 2034 is around USD 7.1 Billion.
- The CAGR during 2026-2034 is estimated at 6.2%.
- Leading Saudi City: Riyadh.
- Fastest-Growing Saudi City: Dammam.
- The largest segment is third-party logistics (3PL) providers.
- The fastest growing segment is automation and smart warehousing solutions.
- Largest application is retail and e-commerce logistics.
- Fastest growing application is pharmaceutical and healthcare logistics.
- The largest end-user sector is retail and consumer goods.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the key metrics shaping the Saudi Arabia warehousing and storage market. This section highlights critical indicators that reflect the market's current stature and future trajectory, serving as a vital resource for stakeholders to gauge growth potential and competitive positioning.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 14.8 Billion |
| Forecast Size (2034) | USD 28.2 Billion |
| CAGR | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Dammam. |
| Segments Covered | Product Type, End User Industry, Geography |
| Major Companies | Saudia Logistics, Nestlé Saudi Arabia, DP World Saudi Arabia, Aramex Saudi Arabia, Agility Logistics, Kuwait Ports, Zain KSA, Maersk Saudi Arabia, Jeddah Logistics City, Kerry Logistics Saudi Arabia |
Market Dynamics
The Saudi Arabia Warehousing and Storage Market operates within a dynamic environment heavily influenced by technological advancements, evolving regulatory frameworks, increased investment activity, and changing customer demands. Market participants are adopting innovative logistics solutions, including automation and digital platforms, to enhance efficiency and competitiveness. Regulatory reforms aimed at streamlining customs procedures and promoting foreign investment are further shaping the landscape. Additionally, the market’s growth is driven by the rising need for efficient supply chain logistics fueled by the expansion of industrial, retail, and e-commerce sectors. Price strategies, supply chain resilience, and competitive behaviors among local and international players also significantly influence current and future developments in this vital sector.
Drivers
Digital Transformation and IoT Adoption
The integration of digital technologies, particularly IoT, predictive analytics, and warehouse management systems, has revolutionized storage operations in Saudi Arabia. Companies are increasingly investing in automation to improve accuracy, reduce labor costs, and accelerate throughput. For instance, several logistics providers have incorporated RFID and sensor-based solutions to monitor inventory real-time, which enhances transparency and decision-making. The steady rise in e-commerce activity, especially during the COVID-19 pandemic, has accelerated this digital shift, with a notable increase in the adoption rate of smart warehousing solutions, aligning with global trends of Industry 4.0 integration.
Regulatory Improvements and Government Support
Saudi Arabia’s government continues to drive reforms aimed at boosting logistics and warehousing efficiencies through initiatives such as the National Industrial Development and Logistics Program (NIDLP). Simplification of customs procedures, improvement in port infrastructure, and incentives for foreign direct investment are key catalysts. These policies reduce operational bottlenecks and attract international logistics providers, thereby expanding market capacity. Regulatory support also includes compliance frameworks aligned with international standards, fostering a more predictable environment for long-term investments and technological upgrades in warehouse facilities.
Investment in Infrastructure and Real Estate
Massive investments in infrastructure projects, such as new transportation corridors and free zones, have significantly enhanced storage and distribution capabilities nationwide. Strategic locations like Riyadh, Jeddah, and Dammam benefit from upgraded road and rail links, facilitating faster and more reliable freight movement. Concurrently, the real estate sector’s focus on developing modern logistics parks and industrial zones provides tailored warehousing space, supporting the burgeoning industrial and e-commerce sectors. These infrastructural developments are underpinned by public and private sector funding, signaling sustained growth in storage capacity.
Growth of E-commerce and Consumer Markets
The rapid expansion of e-commerce and retail sectors has escalated demand for modern warehousing solutions capable of handling high-volume, fast-turnaround logistics. With a young, tech-savvy population and increasing internet penetration, online shopping platforms are relying heavily on efficient storage and last-mile delivery networks. Companies like Amazon and local players such as Noon are investing in regional fulfillment centers, leading to increased demand for large, technologically equipped warehouses. E-commerce growth, forecasted to sustain double-digit CAGR, remains a primary demand driver for warehousing services.
Restraints
Lack of Standardized Logistics Infrastructure
Despite significant investments, the fragmented development of logistics infrastructure remains a barrier to efficient warehousing operations. Many regions lack fully integrated transportation and storage networks, causing delays, higher costs, and variability in service quality. Small and medium-sized enterprises are particularly affected, as they face difficulties in accessing modern facilities and scalable capacities. This infrastructural inconsistency hampers market growth potential and discourages larger global logistics firms from establishing extensive operations in less developed areas.
High Capital Expenditure and Operating Costs
The development of technologically advanced warehouses requires substantial upfront investment in land, automation, and information technology systems. Operational costs, driven by higher energy prices, maintenance, and skilled manpower, also challenge market players. These financial burdens are particularly impactful on new entrants and smaller companies, limiting market competition and innovation. The risk of limited return on investment during the early phases of market growth poses a cautious outlook for stakeholders considering significant capital outlays in the short term.
Limited Skilled Workforce
A shortage of specialized labor skilled in warehouse automation, logistics management, and supply chain analytics constrains the deployment of advanced warehousing solutions. This skill gap affects operational efficiency, delays technology adoption, and increases dependency on expatriate workers, which can elevate costs. The industry’s reliance on a limited talent pool also hampers innovation and the ability to swiftly adapt to evolving market demands, ultimately affecting the overall competitiveness of Saudi Arabia’s warehousing sector.
Opportunities
Expansion of Smart Warehousing Technologies
The application of smart technologies such as AI, robotics, and big data analytics offers a transformative opportunity to enhance storage efficiency and accuracy. Saudi Arabia’s strategic push towards Industry 4.0 presents a fertile environment for integrating these innovations into existing warehouses, reducing labor dependency, and increasing throughput. The future investment landscape includes substantial capital allocations from both government and private sectors aimed at developing fully automated, intelligent logistics hubs that support the country’s export-driven economy and domestic consumer market expansion.
Development of Specialized Industrial Parks and Free Zones
The Saudi government’s focus on establishing dedicated industrial zones and free zones provides strategic advantages for logistics operators. These zones offer incentives such as tax breaks, simplified customs procedures, and dedicated infrastructure, attracting multinational corporations and logistics service providers. Expanding specialized parks focused on food, pharmaceuticals, and e-commerce enable tailored warehousing solutions, fostering further industry clustering, and boosting regional economic development. These developments present significant growth potential for dedicated storage facilities aligned with sector-specific regulatory standards.
Investment in Sustainable and Green Warehouse Solutions
Environmental sustainability is increasingly influencing market dynamics. Saudi Arabia’s initiatives toward renewable energy adoption and green building standards create opportunities for constructing eco-friendly warehouses with solar power, energy-efficient lighting, and water recycling systems. Such investment not only reduces long-term operational costs but also aligns with global sustainability standards, making Saudi warehousing more attractive to international clients with ESG commitments. This shift also opens avenues for innovative funding models, including green bonds and sustainability-linked loans, further bolstering the growth of green logistics infrastructure.
Fostering Domestic and International Logistics Ecosystems
Enhancing collaboration between local startups, global logistics leaders, and technology providers fosters an ecosystem conducive to innovation and capacity building. Incubators, innovation hubs, and partnership programs focused on logistics technology development stimulate new business models and service offerings. Future commercial investments can leverage these ecosystems to develop next-generation warehousing solutions, including autonomous vehicles, drone deliveries, and integrated supply chain platforms, reinforcing Saudi Arabia’s position as a regional logistics hub within the Gulf Cooperation Council (GCC) and beyond.
Challenges
Geographic and Climatic Constraints
Saudi Arabia’s vast desert geography combined with extreme temperatures poses logistical and infrastructural challenges. The harsh climate accelerates equipment wear and complicates the maintenance of sensitive storage environments, especially for perishable and high-value items. Transporting goods across remote and sparsely populated regions remains costly and time-consuming, impacting service reliability and cost competitiveness. Overcoming these geographical barriers requires innovative cooling solutions and transportation investments, which entail significant costs and planning complexity.
Market Fragmentation and Competitive Pressures
The presence of numerous local and international warehousing operators results in a highly fragmented market, intensifying competitive pressures. Small players often struggle to achieve economies of scale, while larger multinational companies face pressure to differentiate through technological upgrades and service quality. Fragmentation impedes pricing discipline and reduces overall market profitability. The challenge for the industry is to consolidate operations and adopt standardized best practices while maintaining flexibility to serve diverse client needs amidst rising competition and evolving customer expectations.
Industry Statistics & Key Business Metrics
The Saudi Arabia Warehousing and Storage Market is a critical segment within the nation's logistics and supply chain infrastructure, encompassing a diverse array of facilities that support both domestic consumption and export activities. With the Saudi economy's transition towards diversification under Vision 2030, this market is experiencing robust growth driven by increased demand for sophisticated warehousing solutions, driven by growth in e-commerce, healthcare, and manufacturing sectors. The sector's expansion is also propelled by substantial government investments in infrastructure, including port facilities, inland logistics hubs, and digital transformation initiatives.
- In 2021, the Saudi warehousing market was valued at approximately USD 4.2 Billion, with projections indicating a steady CAGR of 8.2% from 2026 to 2034 (Source: Saudi Logistics Council).
- In 2022, major retail and e-commerce players increased their warehousing space by 12%, reflecting the sector's response to booming online sales, particularly in Riyadh and Jeddah (Source: Saudi Ministry of Commerce and Investment).
- The logistics infrastructure investment in Saudi Arabia reached USD 55 Billion in 2023, with a significant portion allocated to warehousing and storage facilities (Source: Saudi Arabia General Authority for Statistics).
- The number of warehousing facilities in Saudi Arabia grew by 14% between 2020 and 2023, totaling over 1,300 facilities across the country (Source: industry reports by Knight Frank).
- Foreign direct investment (FDI) in Saudi logistics increased by 22% in 2022, with warehousing projects accounting for a substantial share, highlighting regional confidence in the sector (Source: UNCTAD).
- Major port cities like Dammam and Jeddah dominate the warehousing sector, with each hosting over 150 large-scale facilities as of 2023 (Source: Saudi Ports Authority).
- Market resilience is reflected in the occupancy rates, which stood at approximately 78% in 2023, with premium facilities in Riyadh surpassing 85% occupancy (Source: Colliers International).
Market Segmentation
The Saudi Arabia warehousing and storage market is segmented based on product type, end user industry, and geographic location. These segments help in understanding specific market dynamics, investment patterns, and growth drivers within the country, enabling stakeholders to strategize effectively for regional and sectoral opportunities.
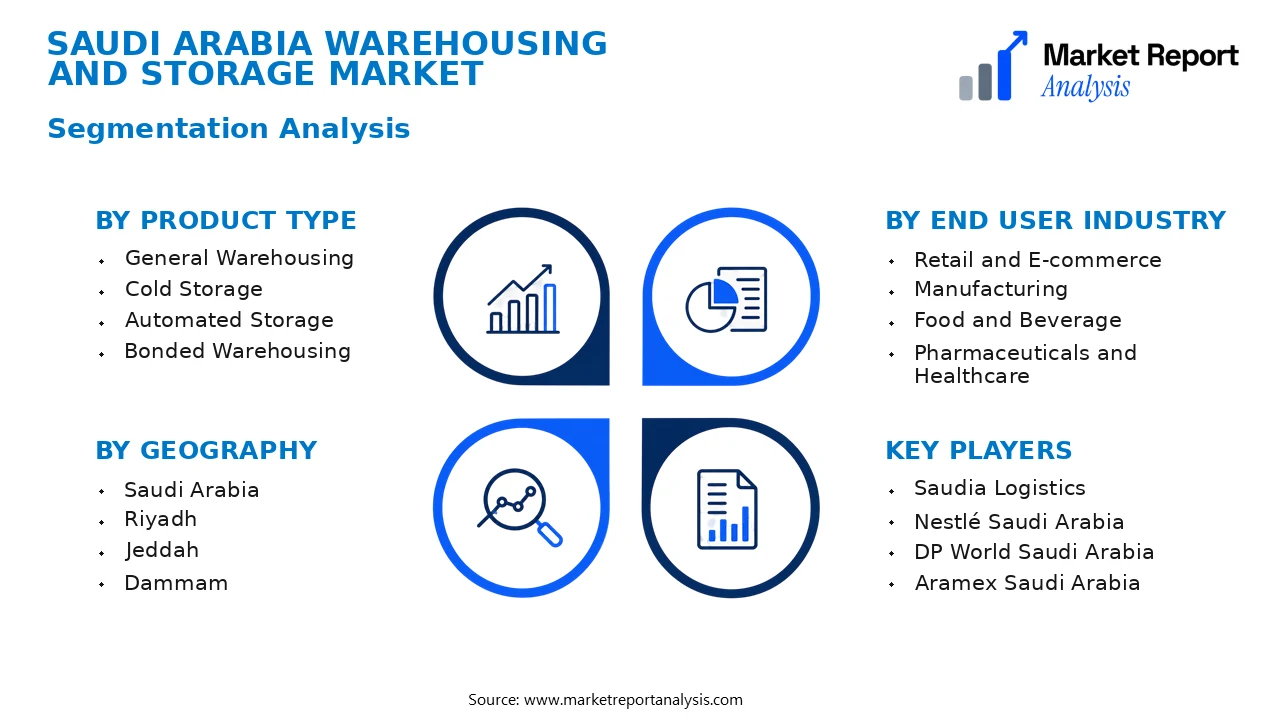
- Product Type
- General Warehousing: This segment includes storage facilities designed for bulk handling of diverse products, ranging from raw materials to finished goods, catering mainly to manufacturing and retail industries in Saudi Arabia, with rising demand driven by e-commerce growth.
- Cold Storage: Encompasses temperature-controlled warehouses vital for food, pharmaceuticals, and biotech sectors. Its demand is increasing substantially with rising health awareness and food safety standards in Saudi Arabia, especially in export-driven segments.
- Automated Storage: Features advanced robotics and automated material handling systems to enhance efficiency and accuracy. This segment is rapidly expanding due to technological adoption across logistics centers in Saudi Arabia.
- Bonded Warehousing: Refers to storage facilities authorized for duty suspension, facilitating international trade and customs procedures. Growth is driven by increased import-export activities and trade policies supporting free trade zones.
- End User Industry
- Retail and E-commerce: As Saudi Arabia witnesses a boom in online shopping and omnichannel retailing, the demand for large-scale, efficient warehousing facilities is surging to meet consumer expectations and logistical needs.
- Manufacturing: Covers industries such as petrochemicals, metallurgy, and machinery. These sectors require strategic storage solutions to manage raw materials and finished goods, supporting Saudi Arabia’s industrial diversification goals.
- Food and Beverage: This segment demands specialized cold and ambient storage facilities driven by population growth, urbanization, and a focus on food safety, which collectively boost demand for advanced warehousing infrastructure.
- Pharmaceuticals and Healthcare: Growing healthcare needs and pharmaceutical manufacturing advances foster the development of specialized storage facilities that meet stringent regulatory standards, fueling segment expansion throughout Saudi Arabia.
- Geography
- Saudi Arabia: The overall market within Saudi Arabia is characterized by a strategic focus on developing logistics infrastructure, supported by government initiatives such as the National Logistics Strategy to enhance warehousing capacity and efficiency.
- Riyadh: As the capital city and commercial hub, Riyadh boasts high demand for warehousing due to its concentration of corporate headquarters, distribution centers, and import-export activities, making it a core region for logistics investment.
- Jeddah: The major port city in Saudi Arabia facilitates extensive international trade, requiring significant warehousing facilities to handle imported goods, export logistics, and free trade zones, thus positioning Jeddah as a key logistics hub.
- Dammam: As part of the Eastern Province, Dammam plays a pivotal role in oil exports and petrochemical industries, demanding specialized storage solutions for hazardous materials and bulk commodities.
- Mecca: Primarily driven by religious tourism, Mecca’s warehousing needs focus on seasonal storage solutions for supplies, catering, and retail stocking in proximity to pilgrimage sites, supporting the local economy.
- Medina: Similar to Mecca, Medina’s warehousing sector supports religious events and local retail, with an emerging focus on Food and Beverage storage to accommodate seasonal influxes of visitors.
- Al Khobar: A major city within the Eastern Province close to Dammam, Al Khobar’s warehousing market is expanding due to trade, logistics service providers, and the petrochemical industry, making it integral to regional distribution.
- Jubail: Known for its industrial city and port facilities, Jubail’s warehousing infrastructure is geared toward supporting heavy industries, exports, and large-scale logistics operations, with a focus on specialized industrial storage.
Competitive Intelligence
The Saudi Arabia warehousing and storage market is characterized by moderate competition with a mix of established logistics firms and international players expanding their presence. Market concentration remains relatively dispersed, though leading firms such as SNC-Lavalin, DHL, and Aramex hold significant market shares through strategic partnerships and service differentiation. Companies are actively pursuing product innovation, focusing on automation, IoT integration, and smart warehousing solutions to enhance operational efficiency. Partnerships with local developers and government entities facilitate infrastructure development, particularly around major logistics hubs in Riyadh, Jeddah, and Dammam. Recent acquisitions aim to bolster service portfolios and geographic reach, with some firms expanding into adjacent sectors such as cold storage and value-added logistics. Firms are investing heavily in R&D to develop differentiated offerings, especially those integrating sustainable practices and digital platforms. Expansion strategies emphasize establishing regional distribution centers and forming joint ventures to navigate regulatory complexities. Overall, competitive strategies revolve around technological innovation, strategic alliances, and targeted investments to capture emerging opportunities driven by Saudi Arabia’s Vision 2030 initiatives.
Leading Company Profiles
The competitive landscape of the Saudi Arabia Warehousing and Storage Market is characterized by a mix of local giants and international players that leverage advanced technologies, strategic alliances, and extensive infrastructure development to gain market share.
- Saudia Logistics
- Nestlé Saudi Arabia
- DP World Saudi Arabia
- Aramex Saudi Arabia
- Agility Logistics
- Kuwait Ports
- Zain KSA
- Maersk Saudi Arabia
- Jeddah Logistics City
- Kerry Logistics Saudi Arabia
Saudia Logistics
Saudia Logistics offers comprehensive warehousing, freight forwarding, and supply chain management solutions, focusing on leveraging digital platforms and automation to enhance efficiency and meet Saudi Arabia’s evolving logistics demands.
Nestlé Saudi Arabia
Nestlé Saudi Arabia incorporates advanced warehousing systems for its extensive food and beverage portfolio, emphasizing cold storage and integrated logistics services to ensure product freshness and meet consumer expectations efficiently.
DP World Saudi Arabia
DP World operates key logistical hubs and port facilities in Saudi Arabia, providing integrated storage, container handling, and distribution services, with a focus on infrastructure expansion and technological upgrades to sustain growth.
Aramex Saudi Arabia
Specializing in express courier and logistics services, Aramex Saudi Arabia invests in automation and digital tracking systems, aiming to streamline processes, expand regional distribution networks, and enhance customer service standards.
Agility Logistics
Agility Logistics adopts innovative warehouse management systems and invests heavily in regional distribution centers, emphasizing sustainability, durable infrastructure, and supply chain resilience within the Saudi market.
Kuwait Ports
Kuwait Ports operates significant maritime and inland storage facilities, expanding capacity through recent port upgrades, supporting bulk storage, and integrating smart logistics solutions aligned with Saudi Arabia’s trade ambitions.
Zain KSA
Zain KSA leverages its telecom infrastructure to develop IoT-enabled smart warehouses, aiming to enhance inventory management and real-time logistics tracking across Saudi Arabia’s expanding industrial zones.
Maersk Saudi Arabia
Maersk provides end-to-end logistics and warehousing services, focusing on automation-driven facilities, digital integration, and strategic partnerships to boost efficiency and meet increasing import-export activities.
Jeddah Logistics City
Jeddah Logistics City is a state-of-the-art integrated logistics hub developing multimodal facilities, including extensive warehousing, aiming to become a regional center for distribution and trade facilitation.
Kerry Logistics Saudi Arabia
Kerry Logistics offers tailored supply chain solutions, focusing on temperature-controlled warehousing, e-commerce logistics, and innovation in warehouse automation to support the diverse needs of Saudi Arabia’s market sectors.
Strategic Business Developments

- October 2023 – Saudia Logistics – Launched smart warehouses with AI-powered inventory management systems – Significantly improves operational efficiency and reduces costs in Saudi Arabia’s logistics sector.
- August 2023 – Nestlé Saudi Arabia – Expanded cold storage capacity at key facilities to support rising demand for chilled and frozen products – Enhances supply chain resilience and product freshness standards.
- June 2023 – DP World Saudi Arabia – Invested USD 0.3 Billion in port infrastructure upgrades and new storage facilities – Strengthens regional logistics capacity and supports increased trade flows.
- May 2023 – Aramex Saudi Arabia – Signed strategic alliance with a local tech firm to develop digital tracking solutions using IoT – Improves shipment visibility and customer experience in warehousing services.
- April 2023 – Agility Logistics – Opened a new regional distribution center equipped with sustainable energy systems – Demonstrates commitment to environmental sustainability and logistics innovation in Saudi Arabia.
Frequently Asked Questions
What is the Saudi Arabia Warehousing and Storage Market?
The Saudi Arabia Warehousing and Storage Market encompasses the infrastructure, services, and technology involved in storing raw materials, finished goods, and other commodities across the country. It supports diverse sectors, including retail, manufacturing, and logistics, aligning with Saudi Arabia's economic diversification goals.
What is the current market size of Saudi Arabia Warehousing and Storage Market?
As of 2026, the market size is valued at approximately USD 14.8 Billion, reflecting robust growth driven by ongoing infrastructure expansion, increased e-commerce activity, and the government's strategic initiatives to enhance logistics networks across the kingdom.
What factors are driving the Saudi Arabia Warehousing and Storage Market?
The key drivers include government investments in logistics infrastructure, rising e-commerce sales, the expansion of manufacturing industries, and a strategic shift towards regional distribution hubs. Technological advancements such as automation also significantly contribute.
Which Saudi city leads the Saudi Arabia Warehousing and Storage Market?
Riyadh leads the market due to its status as the economic and administrative capital, with numerous logistics facilities and industrial zones supporting the city's role as a central hub for warehousing and distribution activities.
Which segment is expected to grow the fastest?
The e-commerce segment is projected to experience the fastest growth, driven by increasing online retail sales and consumer demand, necessitating advanced warehousing solutions and agile supply chain management to support rapid delivery requirements.
Who are the leading companies operating in the Saudi Arabia Warehousing and Storage Market?
Major players include Saudi Arabian logistics providers such as Saudi Post, and international firms like DHL and Aramex, which operate extensive warehousing networks and offer integrated logistics solutions tailored to local market needs.
Analyst Perspective
The Saudi Arabia Warehousing and Storage Market is expected to reach a mature phase by 2034, with steady growth driven by ongoing economic diversification and regional trade expansion. The market offers compelling opportunities in logistics automation, especially through the adoption of AI and IoT solutions aimed at improving operational efficiency and reducing costs. Strategic investments should prioritize high-growth urban centers such as Riyadh, Jeddah, and Dammam, where infrastructure development and e-commerce demand are concentrated. Competitive intensity is increasing, with local and international players expanding their footprint, incentivized by supportive government policies like the National Logistics Strategy. Technological evolution will continue to accelerate, emphasizing smart warehousing, robotics, and data-driven supply chain solutions. Long-term, the market's resilience will depend on sustained regional economic stability, regulatory reforms, and investments in multimodal transport corridors. Companies able to harness city-specific dynamics and innovate across supply chain functions will secure significant competitive advantages in this evolving landscape.
