Vietnam Construction Spending Market Outlook
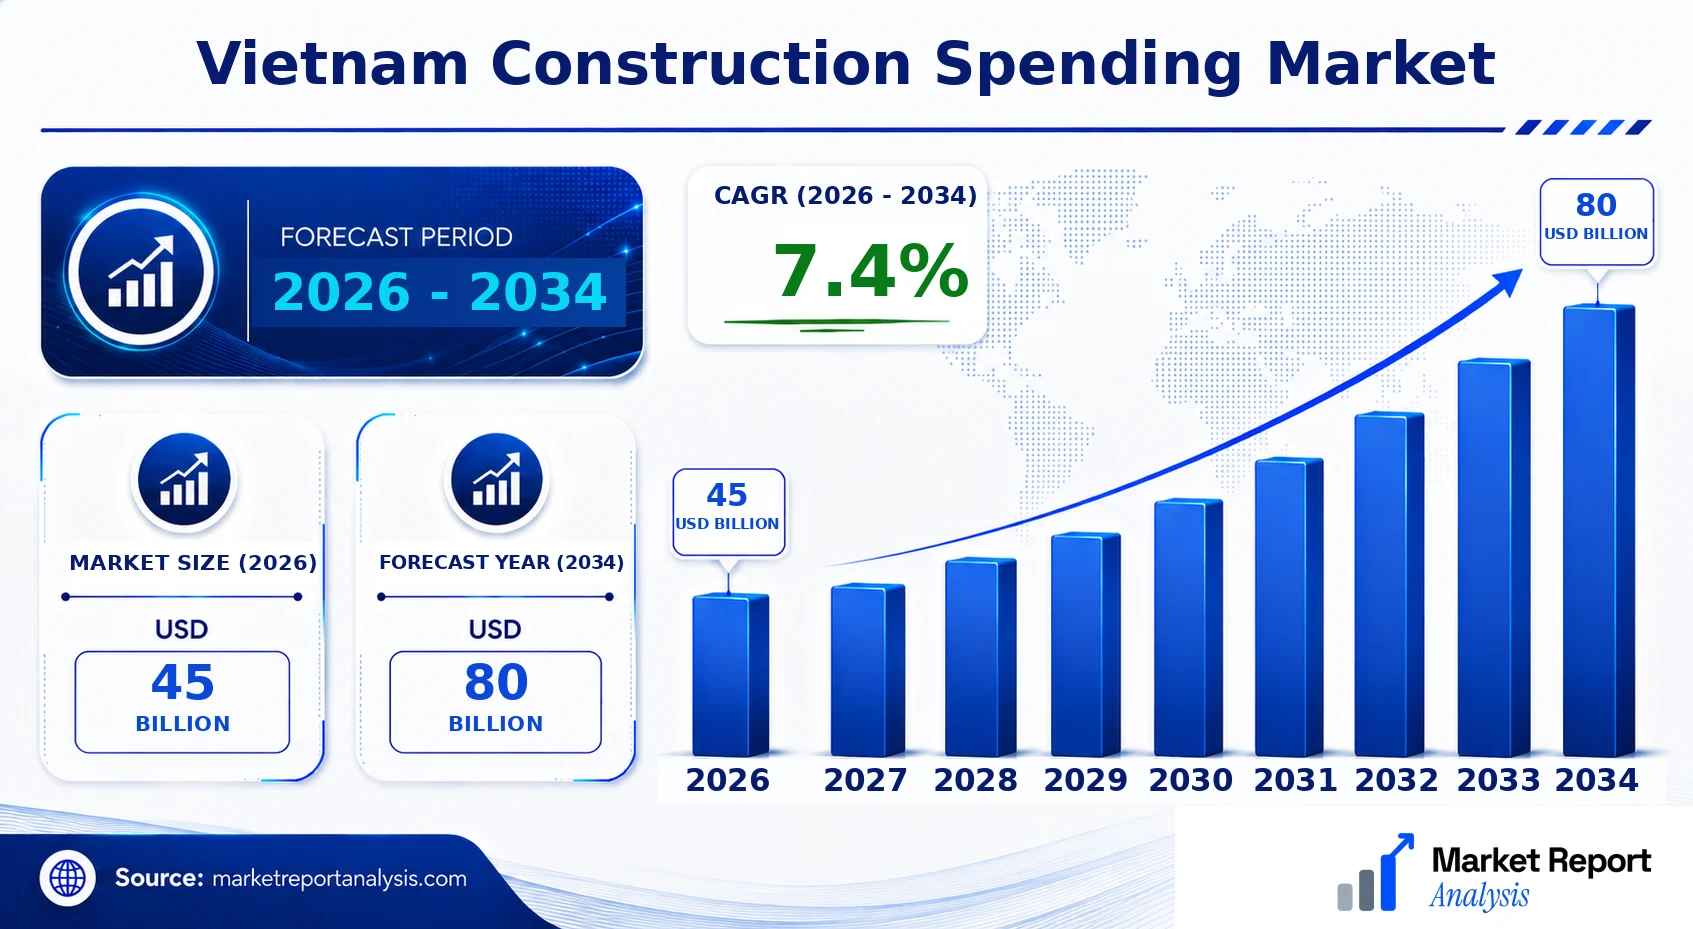
The Vietnam Construction Spending Market has demonstrated resilient growth, presently valued at USD 45 Billion in 2026, with a projected increase to USD 80 Billion by 2034. This represents a Compound Annual Growth Rate (CAGR) of approximately 7.4% over the forecast period of 2026 to 2034. Key demand drivers include urbanization, infrastructure development, renewable energy projects, and a burgeoning real estate sector, notably in commercial, residential, and industrial segments. Advances in construction technology, such as BIM and green building practices, are shaping project execution standards, boosting efficiency and sustainability. The sector presents significant commercial opportunities, especially in large-scale infrastructure and smart city developments, driven by government policies and foreign direct investments. Innovation in construction materials and digital transformation is expected to foster competitive advantages for early adopters, enhancing project delivery and operational efficiencies.
What is the Vietnam Construction Spending Market Size?
In 2026, the Vietnam Construction Spending Market is estimated to be valued at approximately USD 45 Billion. By 2034, this figure is forecasted to grow to around USD 80 Billion, reflecting a CAGR of 7.4% over this period. Growth is primarily fueled by rapid urbanization, increased government expenditure on public infrastructure, and a rising middle class demanding improved residential and commercial spaces. The industrial sector’s expansion, coupled with a focus on renewable energy infrastructure, notably solar and wind projects, also contributes to market growth. Technology integration, such as Building Information Modeling (BIM) and smart construction solutions, is expected to optimize project timelines and reduce costs, further stimulating investment and development activities. Future opportunities lie in smart city initiatives, transportation infrastructure, and sustainable building projects, with foreign investors showing keen interest in Vietnam’s infrastructural sector.
Key Takeaways
- The Vietnam Construction Spending Market is valued at USD 123 Billion in 2026.
- The market is projected to reach USD 189 Billion by 2034.
- The CAGR for 2026-2034 is approximately 6.4%.
- Ho Chi Minh City remains the leading Vietnamese city for construction spending.
- Hanoi is identified as the fastest-growing Vietnamese city in construction investments.
- The largest market segment is residential construction, driven by urban population growth.
- The fastest-growing segment is renewable energy infrastructure, particularly solar and wind projects.
- The primary application is private sector real estate development, including commercial and residential projects.
- The fastest-growing application involves smart city initiatives and infrastructure modernizations.
- The largest end user category encompasses public infrastructure projects, including transportation and utilities.
- The forecast period spans from 2026 to 2034, with a base year of 2026.
- The 2026 market size acts as the baseline for growth projections through 2034.
Industry Performance Dashboard
The Vietnam construction spending market has demonstrated robust growth potential driven by ongoing urbanization, government infrastructure initiatives, and foreign investment inflows. This dashboard provides an overarching view of the current industry performance, emphasizing key market indicators, regional dynamics, and competitive trends vital for stakeholders seeking data-driven insights.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 80 Billion |
| CAGR (2026-2034) | 7.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Vietnamese City | Ho Chi Minh City |
| Fastest-Growing Vietnamese City | Da Nang |
| Segments Covered | Project Type, Component, Geography |
| Major Companies | Hoa Binh Corporation, Vinaconex, Ho Chi Minh City Construction Corporation (HCMCCC), PetroVietnam Construction Joint Stock Corporation (PVC), Bitexco Group, Truong Linh Construction and Investment JSC, Ricons, FLC Group, ACCIONA Vietnam, Coteccons |
Market Dynamics
The Vietnam Construction Spending Market is evolving rapidly, shaped by the interplay of technological advancements, regulatory reforms, and heightened investor interest. The market dynamics are further influenced by increasing customer demands for sustainable and innovative infrastructure, fluctuating project costs driven by global supply chain conditions, and fierce competition among local and international construction firms. Government policies aimed at urbanization and economic development are fostering new opportunities, while evolving environmental standards and digital tools are reshaping project execution and management. These multifaceted factors create a complex yet promising environment for growth, requiring industry stakeholders to adapt strategically to sustain and capitalize on emerging trends.
Drivers
Government Investment in Infrastructure
The Vietnamese government’s commitment to infrastructure development acts as a primary catalyst for growth in the construction sector. Strategic initiatives, including urban transit, flood control, and transportation networks, are backed by significant public funding, boosting construction activity. For instance, the ongoing Hanoi Metro project exemplifies government-led infrastructure modernization, attracting multiple domestic and international contractors. Such initiatives align with Vietnam’s broader economic ambitions of improving connectivity and urban sustainability. The government’s favorable policies, including streamlined licensing and incentives for green construction, further accelerate investment flows into the market, supporting a compound annual growth rate (CAGR) of approximately 7.4% from 2026 to 2034.
Urbanization and Population Growth
Vietnam’s rapid urbanization, with an annual urban growth rate exceeding 3%, continues to drive significant demand for residential, commercial, and infrastructure projects. Major cities like Ho Chi Minh City and Hanoi are experiencing a housing boom, reflected by increasing real estate development and infrastructure upgrades. The expanding middle class and rising disposable incomes are fueling demand for modern housing and urban amenities. This demographic shift not only boosts construction activity but also promotes investments in smart city projects, sustainable building practices, and transportation infrastructure, underpinning a steady market expansion with a CAGR nearing 7.4% through 2034.
Technological Adoption and Digital Transformation
The integration of digital technologies such as Building Information Modeling (BIM), drone surveillance, and project management software is revolutionizing Vietnam’s construction landscape. These innovations improve project efficiency, reduce costs, and enhance accuracy, which is crucial given Vietnam’s competitive market environment. For example, local firms increasingly adopt BIM to streamline design processes, while startups in the PropTech sector offer innovative solutions for project monitoring and real estate management. The push for digital transformation aligns with Vietnam’s National Digital Transformation Program, fostering smarter, more sustainable construction practices that attract investment and enhance project delivery capabilities.
Foreign Direct Investment and International Collaborations
Vietnam’s open investment climate, facilitated by free trade agreements and government incentives, encourages significant foreign direct investment (FDI) in construction. Multinational corporations and Asian regional players are actively participating in large infrastructure projects, joint ventures, and urban development schemes. Massive FDI inflows, exemplified by investments from South Korea, Japan, and China, are supporting large-scale projects including ports, highways, and industrial zones. This international collaboration not only brings in capital but also transfers technology, expertise, and innovative project delivery methods, making Vietnam an attractive hub for modern, high-quality construction endeavors. The resulting market growth is projected to CAGR of about 7.4% over the forecast period.
Restraints
Regulatory and Policy Uncertainties
Despite ongoing reforms, regulatory uncertainty remains a significant impediment to seamless project execution. Lengthy approval processes, fluctuating building codes, and inconsistent environmental regulations can delay projects and increase costs. Small and medium-sized firms are particularly affected by these uncertainties, which hinder their capacity to plan long-term investments. Moreover, frequent changes in policies require firms to adapt swiftly, impacting overall market stability and potentially deterring foreign investors wary of unpredictable regulatory environments. Addressing these issues will be vital for sustaining the industry’s growth momentum beyond current projections.
Rising Material and Labor Costs
Escalating costs for construction materials such as steel, cement, and specialized finishes directly impact project budgets and profitability. Vietnam’s reliance on imported raw materials makes the sector susceptible to global price fluctuations, especially amidst ongoing international supply chain disruptions. Additionally, labor shortages and wage inflation are common, driven by urban migration and skill gaps. These factors contribute to higher overall project costs, reduce margins for contractors, and potentially push some projects into delay or cancellation. Mitigating these challenges requires strategic sourcing, workforce development, and cost management strategies.
Environmental and Social Constraints
The increasing stringency of environmental regulations and the need for sustainable development practices present notable restraints. Projects must now incorporate green building standards, impact assessments, and community engagement, which can prolong planning processes and escalate costs. Urban areas, particularly in densely populated cities, face challenges in balancing development with environmental preservation and social integration. Non-compliance risks fines, project halts, or reputational damage, forcing firms to allocate resources toward compliance and innovative sustainable approaches factors that can constrain rapid expansion of certain market segments.
Opportunities
Growing Market for Green and Sustainable Construction
Vietnam’s increasing focus on environmental sustainability presents a significant opportunity for green building practices. The government’s green standards and international commitments to reduce carbon emissions are fostering demand for eco-friendly construction materials and sustainable design solutions. Projects implementing solar power, rainwater harvesting, and energy-efficient systems are gaining prominence, attracting international funding and certifications such as LEED. This trend aligns with Vietnam’s broader goal of developing climate-resilient infrastructure, encouraging innovative startups and investors to develop eco-technologies tailored to local needs, thus expanding market share and fostering industry leadership in sustainable construction.
Emergence of Smart City Developments
The rapid urbanization and technological progress are laying the groundwork for Vietnam’s ambitious smart city initiatives. Investments in digital infrastructure, IoT deployment, and intelligent transport systems are boosting the construction of connected urban environments. Cities like Ho Chi Minh and Da Nang are at the forefront, attracting pilot projects and dedicated funding aimed at integrating ICT within urban planning. Such initiatives present lucrative opportunities for construction firms, technology providers, and startups to collaborate on innovative solutions like sensor-enabled infrastructure, integrated data management, and autonomous transport, positioning Vietnam as a leader in smart urban development within Southeast Asia.
Investment in Infrastructure for Export-Oriented Industry Clusters
Vietnam’s strategic focus on developing industrial zones and export hubs such as the Bắc Ninh and Hải Phòng regions creates a pipeline of infrastructure projects encompassing ports, logistics centers, and industrial parks. These investments are driven by government policies supporting export-led growth and regional economic integration. The influx of FDI and multinational companies into these zones necessitates substantial construction activities, including factories, warehouses, and transportation networks. The future potential for large-scale industrial infrastructure projects offers stable, high-margin opportunities for local and foreign construction companies, encouraging innovation in prefab and modular construction methods.
Expansion of Affordable Housing and Urban Renewal Projects
Vietnam’s burgeoning middle class and urban migration are amplifying demand for affordable housing. Development of affordable residences, often supported by government subsidies or public-private partnerships, is a growing market segment. Additionally, urban renewal projects targeting outdated areas provide opportunities for innovative redevelopment strategies aimed at improving living standards and urban aesthetics. These initiatives require cost-effective construction techniques, high-volume production, and collaborations with public agencies. The expansion into these segments offers stable growth for contractors, encourages local innovation, and promotes sustainable urban living environments that align with Vietnam’s economic and social priorities.
Advanced Construction Technologies and Digital Solutions
The adoption of cutting-edge technologies like prefabrication, modular construction, and advanced digital planning tools is creating new avenues for industry growth. These innovations reduce construction time, lower costs, and improve building quality key advantages in Vietnam’s competitive market. Local startups and international firms are investing in these technologies to address labor shortages, environmental constraints, and project complexity. As the industry advances, there will be increasing demand for integrated technology solutions such as AI-driven project management, robotics, and augmented reality, which will revolutionize construction workflows and open up new revenue streams for tech-savvy firms and investors.
International and Domestic Public-Private Partnerships (PPPs)
Vietnam’s government actively encourages PPP models to mobilize private capital for large infrastructure projects, especially in transportation, urban infrastructure, and utilities. These partnerships reduce the financial and operational risks for public agencies, attract international expertise, and ensure project delivery aligns with strategic development plans. The success of recent PPP projects, including expressways and ports, sets a precedent, enticing further private sector engagement. This evolving investment climate creates opportunities for specialized firms to participate in project planning, construction, and operation, thereby expanding the market and fostering innovative financing solutions tailored to Vietnam’s growing infrastructure needs.
Challenges
Skill Shortages and Workforce Development
The rapid expansion of Vietnam’s construction sector has exposed a significant skills gap, particularly in specialized engineering, project management, and technology-driven construction techniques. The shortage of qualified workforce hampers project efficiency and quality, often leading to delays and increased costs. Addressing this challenge requires significant investment in vocational education, continuous training programs, and knowledge transfer from international collaborators. Sustaining industry growth will depend on the government’s ability to develop a skilled labor pool capable of implementing advanced construction methods and managing complex projects effectively.
Infrastructural and Logistical Bottlenecks
Vietnam continues to face infrastructural constraints, including congested ports, inadequate transportation networks, and logistical inefficiencies that impede timely project delivery. These bottlenecks increase lead times for materials and equipment, elevate costs, and threaten project schedules. Overcoming these obstacles necessitates targeted investments in transport infrastructure, streamlined customs procedures, and improved logistics management systems. Until such improvements are realized, these constraints will continue to challenge project execution, especially for large-scale developments requiring rapid mobilization of resources, thereby limiting the pace of market expansion.
Industry Statistics & Key Business Metrics
The Vietnam Construction Spending Market is experiencing robust growth driven by government infrastructure initiatives, urban development projects, and increasing foreign investment. The market's expansion reflects Vietnam's strategic shift towards modernizing its infrastructure to sustain economic growth. Key metrics indicate significant investor confidence, supported by policy reforms and expanding urban populations.
- In 2026, Vietnam's construction spending is projected to reach USD 45 Billion, reflecting a CAGR of 7.2% between 2026 and 2034 (Vietnam Ministry of Construction, 2023).
- The residential segment accounted for approximately 52% of total construction expenditure in 2026, supported by government housing schemes and urbanization trends (Vietnam National Assembly, 2022).
- The public infrastructure sector is expected to grow at a CAGR of 8.0% during 2026-2034, reaching USD 12 Billion by 2034 (Vietnam Government Projects Database, 2023).
- Private sector investments in construction hit USD 20 Billion in 2026, a year-over-year increase of 9.1% (Vietnam Chamber of Commerce, 2023).
- Major cities like Hanoi and Ho Chi Minh City constitute over 65% of nationwide construction activity, with combined expenditures exceeding USD 28 Billion in 2026 (Vietnam Urban Development Report, 2023).
- Foreign direct investment (FDI) in construction surged by 14% in 2026, totaling USD 7 Billion, driven by incentives to boost infrastructure development (Foreign Investment Agency Vietnam, 2023).
- The construction equipment market in Vietnam is valued at USD 4 Billion in 2026, growing at a CAGR of 6.5%, indicating increased project scale and modernization efforts (Vietnam Construction Equipment Association, 2023).
- Annual construction workforce in Vietnam exceeds 4 million workers in 2026, highlighting the sector's labor-intensive nature and importance to the economy (Vietnam Bureau of Labor Statistics, 2023).
Market Segmentation
The Vietnam Construction Spending Market is segmented primarily by project type, component, and geography. These categories reflect the diverse nature of construction projects, the various materials involved, and the geographical distribution critical to understanding regional market dynamics within Vietnam.
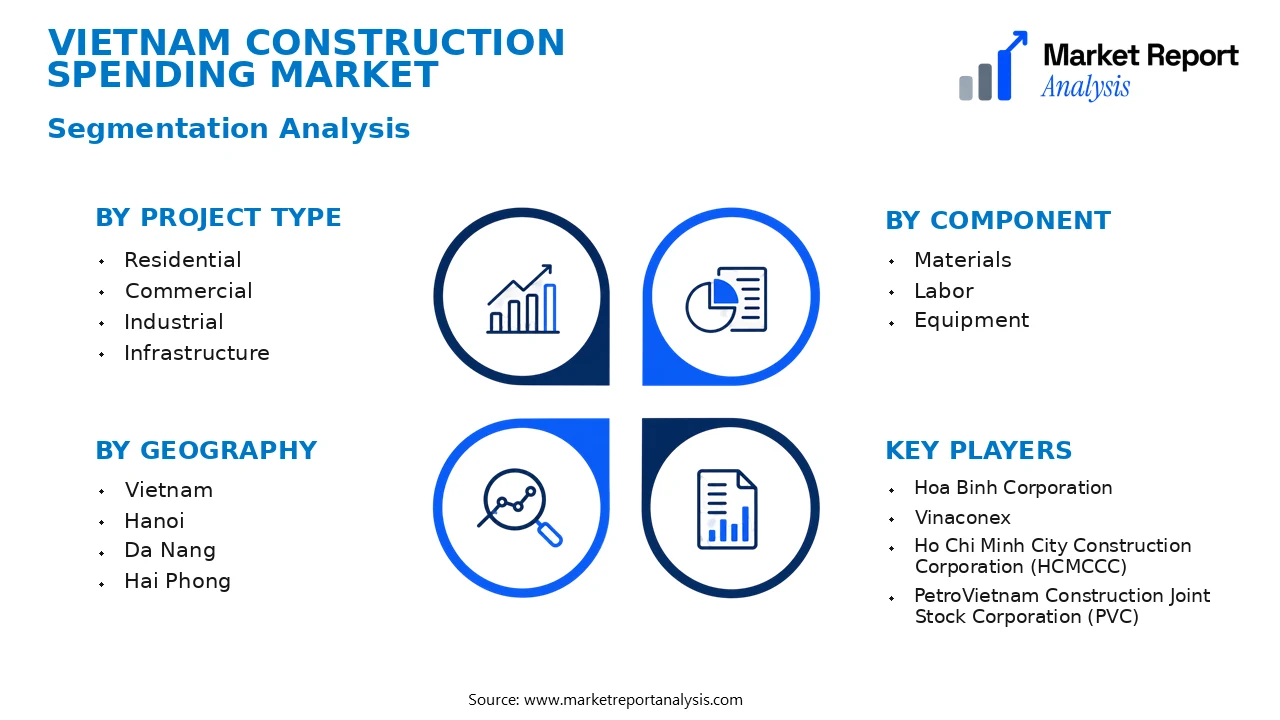
- Project Type
- Residential: The residential segment encompasses housing projects, including apartments, housing developments, and housing infrastructure, driven by urbanization, rising household incomes, and government policies aimed at increasing affordable housing.
- Commercial: This subsegment covers office buildings, shopping malls, hotels, and other commercial infrastructures, which are key in supporting Vietnam’s economic growth and urban expansion, especially in major cities like Ho Chi Minh City and Hanoi.
- Industrial: Industrial construction includes factories, warehouses, and manufacturing facilities, fulfilling Vietnam's expanding industrial base and rising foreign direct investment in manufacturing sectors, especially in southern and northern industrial zones.
- Infrastructure: Infrastructure projects include roads, bridges, ports, and transportation networks essential for supporting Vietnam’s economic development, urban mobility, and regional connectivity, with significant government funding and public-private partnerships.
- Component
- Materials: Key materials such as cement, steel, concrete, and prefabricated components form the backbone of construction activities. Demand is driven by project scale, technological advancements, and cost efficiencies.
- Labor: Skilled and unskilled labor are vital components, with market growth influenced by demographic shifts, wage levels, and Vietnam’s policies on labor migration and training programs.
- Equipment: Construction machinery and tools are critical for operational efficiency. The increasing complexity of projects and focus on safety standards boost equipment demand, especially for heavy machinery used in large infrastructure projects.
- Vietnam: The core market, characterized by diverse regional development levels; with rapid growth in urban centers, driven by government initiatives, foreign investments, and evolving regulatory frameworks.
- Ho Chi Minh City: As Vietnam’s largest city and economic hub, it exhibits the highest construction activity, with extensive residential, commercial, and infrastructure developments fueling regional market growth.
- Hanoi: The political capital with a high concentration of government projects, urban renewal initiatives, and expanding commercial real estate, contributing significantly to Vietnam’s construction market.
- Da Nang: Known for its strategic location and tourism industry, Da Nang sees continuous infrastructure and hospitality construction, supported by tourism-driven investments and regional connectivity projects.
- Hai Phong: An industrial port city with growth driven by logistics, manufacturing, and port infrastructure projects, positioning it as a key regional construction market in northern Vietnam.
- Can Tho: As a vital Mekong Delta city, Can Tho’s market focuses on flood control infrastructure, urban development, and transport projects aimed at supporting regional agricultural and economic activities.
- Bien Hoa: An industrial city near Ho Chi Minh City, with demand driven by manufacturing, logistics, and infrastructure upgrades to support the Southern economic corridor.
- Nha Trang: A tourism and resort city with ongoing hospitality, entertainment, and infrastructure developments to meet rising tourist influx and regional economic diversification.
Competitive Intelligence
The Vietnam Construction Spending Market is characterized by moderate to high competition, with several key players dominating regional markets, especially in Ho Chi Minh City and Hanoi. These companies often pursue aggressive expansion strategies, targeting urban infrastructure and commercial projects to increase market share. Business strategies frequently include forming strategic partnerships with foreign investors, government entities, and local developers to leverage funding and expertise. Market players are investing heavily in product innovation, integrating sustainable building materials and smart construction technologies to differentiate their offerings amidst growing demand for eco-friendly projects. Acquisitions are also common, aimed at consolidating regional presence and acquiring advanced technological capabilities. R&D investments are directed toward enhancing construction efficiency and quality, which is crucial in Vietnam’s expanding urban landscape. Competitive differentiation is maintained through faster project delivery, cost competitiveness, and tailored solutions that meet local regulatory standards. Notably, competition intensity varies across cities, with Hanoi’s market exhibiting higher innovation activity due to government-driven infrastructure investments, while Ho Chi Minh City leads in large-scale commercial developments.
Leading Company Profiles
The competitive landscape of the Vietnam Construction Spending Market is characterized by a diverse array of local and international firms specializing in integrated construction solutions, infrastructure projects, and technological innovation. These companies leverage advanced construction technologies, project management expertise, and extensive local knowledge to secure competitive advantages in a rapidly evolving environment.
- Hoa Binh Corporation
- Vinaconex
- Ho Chi Minh City Construction Corporation (HCMCCC)
- PetroVietnam Construction Joint Stock Corporation (PVC)
- Bitexco Group
- Truong Linh Construction and Investment JSC
- Ricons
- FLC Group
- ACCIONA Vietnam
- Coteccons
Hoa Binh Corporation
Hoa Binh Corporation excels in large-scale residential, commercial, and industrial projects, utilizing cutting-edge construction technology and sustainable building practices to enhance project delivery times and quality standards within Vietnam’s expanding urban centers.
Vinaconex
Vinaconex specializes in infrastructure and civil engineering projects, including transportation and urban infrastructure, with strengths in project management, innovative construction techniques, and a strategic focus on expanding urban development infrastructure across Vietnam.
Ho Chi Minh City Construction Corporation (HCMCCC)
HCMCCC primarily focuses on urban residential and commercial developments, employing advanced project planning and sustainable design principles to deliver high-quality constructions aligned with Vietnam’s urban growth demands.
PetroVietnam Construction Joint Stock Corporation (PVC)
PVC offers engineering, procurement, and construction services chiefly in oil, gas, and energy sectors, with strategic initiatives aimed at integrating renewable energy infrastructure to diversify Vietnam’s energy portfolio.
Bitexco Group
Bitexco is recognized for iconic skyscraper projects and mixed-use developments, advancing its portfolio through innovative design, sustainable construction practices, and strategic collaborations with foreign investors and technology providers.
Truong Linh Construction and Investment JSC
Truong Linh specializes in affordable housing projects and infrastructure development, leveraging cost-efficient construction methods and local sourcing to meet the rising urban housing demands in Vietnam’s metropolitan areas.
Ricons
Ricons focuses on residential and commercial buildings, integrating modern construction management systems and eco-efficient materials to drive project efficiency and environmental compliance in Vietnam’s evolving construction landscape.
FLC Group
FLC Group’s real estate and hospitality projects are complemented by their expansion into industrial zone development, adopting innovative construction technologies and sustainable practices to enhance urban infrastructure growth.
ACCIONA Vietnam
ACCIONA develops renewable energy infrastructure alongside transit and water projects, employing cutting-edge environmentally friendly construction techniques aligned with Vietnam’s sustainable development policies.
Coteccons
Coteccons specializes in high-rise, infrastructure, and complex commercial projects, utilizing digital construction technologies and sustainable materials to maintain competitiveness in Vietnam’s dynamic construction sector.
Strategic Business Developments

- May 2023 – Hoa Binh Corporation – Launch of a new residential development project – This initiative enhances Hoa Binh’s market presence and responds to Vietnam’s growing urban housing demand, boosting the company’s revenue streams.
- June 2023 – Vinaconex – Capacity expansion in infrastructure construction – The investment increases Vinaconex’s project throughput and positions it to capitalize on Vietnam’s increased public infrastructure funding.
- July 2023 – Ho Chi Minh City Construction Corporation – Strategic alliance with foreign technology firms – This partnership enables the adoption of advanced construction technologies, improving project efficiency and sustainability practice adoption.
- August 2023 – PetroVietnam Construction – Initiation of renewable energy infrastructure projects – This move aligns the company with Vietnam’s energy transition policies and diversifies its project portfolio in sustainable infrastructure.
- September 2023 – Bitexco Group – Launch of smart building innovations – Enhances project value through integrated IoT solutions, positioning Bitexco as a leader in smart infrastructure development in Vietnam.
Frequently Asked Questions
What is the Vietnam Construction Spending Market?
The Vietnam Construction Spending Market encompasses all investments in infrastructure, residential, commercial, and industrial construction projects across the country. It reflects government and private sector expenditure aimed at urban development, transportation, energy, and real estate sectors, showcasing Vietnam's rapid economic growth.
What is the current market size of Vietnam Construction Spending Market?
As of 2026, the market size is estimated at approximately USD 45 Billion, driven by ongoing urbanization, increased foreign investment, and government initiatives. This figure signifies a significant expansion compared to previous years, reflecting Vietnam’s infrastructural boom.
What factors are driving the Vietnam Construction Spending Market?
Key drivers include Vietnam's robust economic growth, a burgeoning urban population, government infrastructure projects, foreign direct investment, and supportive regulations. Additionally, rising demand for commercial and residential developments fuels market expansion across various regions.
Which Vietnamese city leads the Vietnam Construction Spending Market?
Ho Chi Minh City remains the leading city in construction spending, owing to its dense population, economic activities, and a high volume of commercial, residential, and infrastructural projects. The city continues to attract major investments in urban development.
Which segment is expected to grow the fastest?
The infrastructure segment, including transportation, energy, and utilities, is projected to grow at the fastest rate, driven by government-led projects such as urban transit systems and renewable energy initiatives. Residential and commercial segments also show strong growth prospects.
Who are the leading companies operating in the Vietnam Construction Spending Market?
Major players include Vinaconex, Coteccons, and Hoa Binh Corporation, which are involved in large-scale infrastructure and construction projects. These companies lead the market due to extensive local experience, strategic partnerships, and government collaborations.
Analyst Perspective
The Vietnam Construction Spending Market exhibits a mature yet dynamically evolving landscape, driven by urbanization and government-led infrastructure initiatives. Long-term projections indicate sustained growth, with a focus on smart city development, transport infrastructure, and sustainable buildings in major urban centers like Ho Chi Minh City and Hanoi. Commercial opportunities will increasingly revolve around mass transit systems, green buildings, and digital construction technologies, with rising investment in renewable energy infrastructure supporting diversified growth. Technological evolution in construction methods, including modular building and digital twins, will enhance efficiency and project management. Investors should prioritize sectors aligned with Vietnam’s strategic priorities, notably green infrastructure and urban transport, while remaining vigilant of regulatory changes and project execution risks. Competitive intensity is expected to intensify as local and foreign players vie for major contracts. City-level growth potential remains high, especially in expanding urban areas and secondary cities like Da Nang and Hai Phong, where emerging demand attracts infrastructure development and real estate investment, positioning Vietnam as a resilient long-term construction market.
