North America Construction Spending Market Outlook
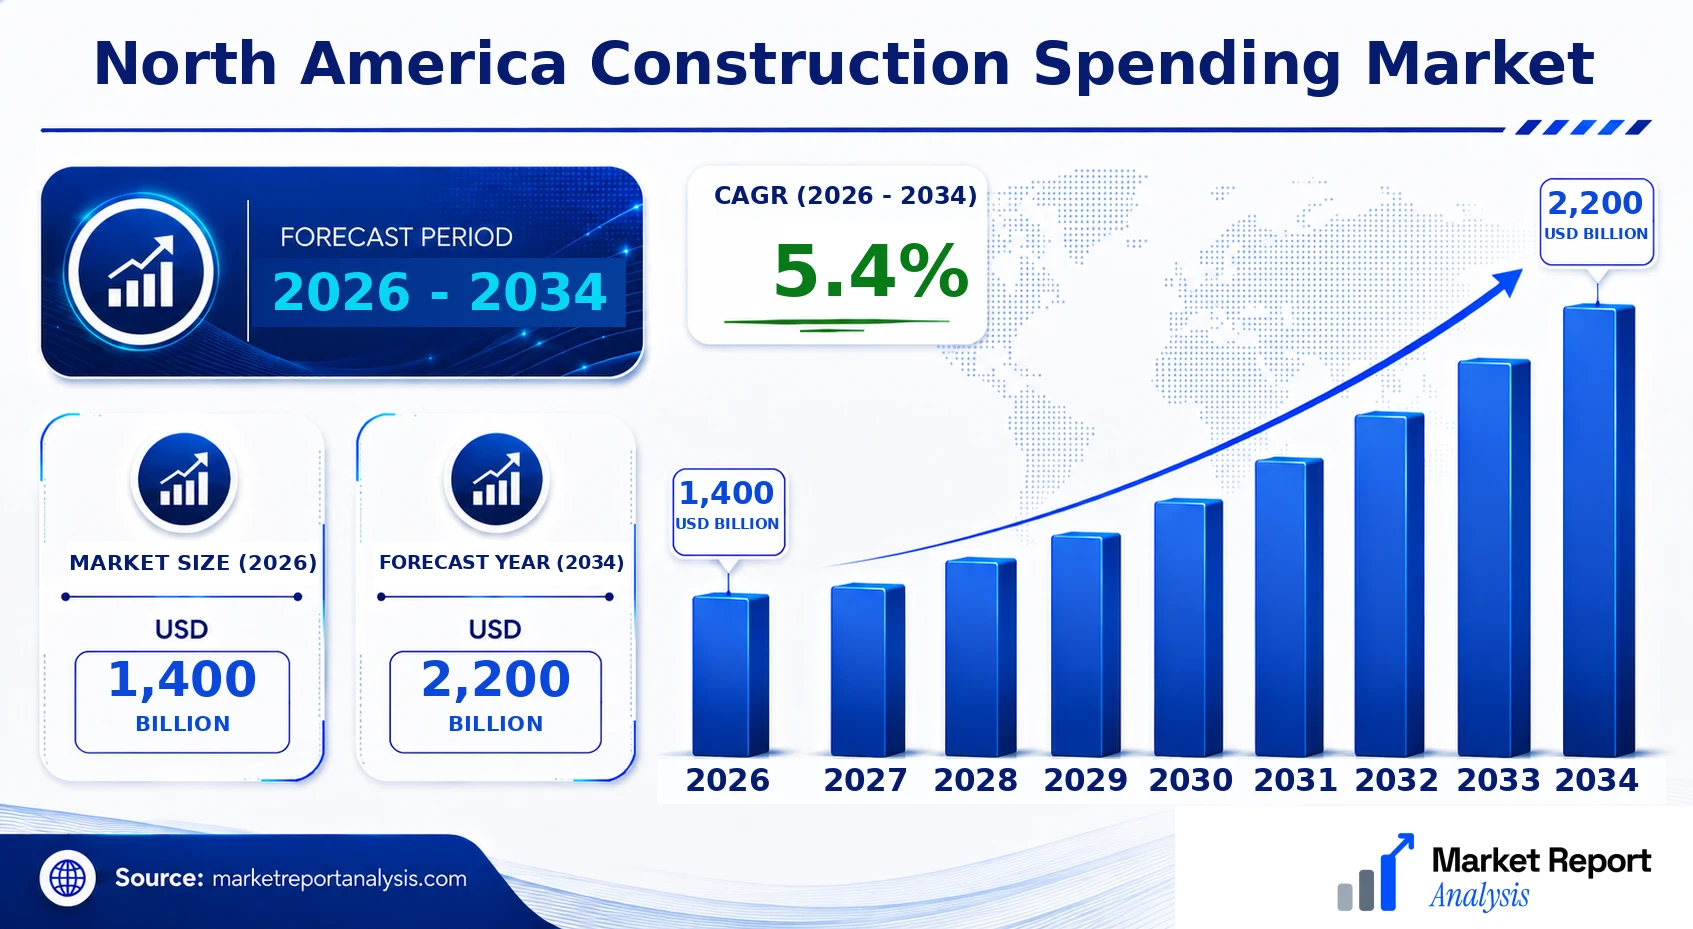
The 2026 market size is USD 1,400 Billion. The market is forecast to reach USD 2,200 Billion by 2034. The forecast CAGR for 2026-2034 is 5.4%. The North America construction spending market continues to demonstrate resilience amid economic fluctuations, driven by urbanization, infrastructure modernization, and investment in renewable energy projects. Rising public and private sector initiatives bolster sector growth, with a focus on sustainable and technologically advanced construction techniques. The market is characterized by a diverse array of projects including commercial, residential, industrial, and infrastructure segments, all contributing to an expanding demand. As urban centers grow and aging infrastructure necessitates upgrades, strategic investments are channeling substantial funding into new developments and refurbishments. Technological adoption, notably in building information modeling (BIM), prefabrication, and smart construction practices, enhances efficiency and sustainability, further propelling the market. The forecast anticipates consistent growth, supported by improved economic outlooks, government stimulus programs, and the integration of innovative construction methods. Overall, the North America construction spending market is poised to sustain robust expansion through 2034, with annual growth rates reflecting continued industry vitality.
What is the North America Construction Spending Market Size?
The North America Construction Spending Market size is estimated at USD 1.2 TRILLION in 2026 and is expected to reach approximately USD 1.8 TRILLION by 2034, expanding at a CAGR of 5.4% from 2026 to 2034. This growth is primarily driven by increased government investment in infrastructure, high demand in residential and commercial construction sectors, and the rapid adoption of innovative construction technologies. The residential segment continues to dominate, fueled by urban expansion and affordable housing schemes, while commercial projects are buoyed by rising employment and business expansion across major cities. The integration of smart building technologies and sustainable construction practices further enhances market prospects. Future investments are likely to focus on green buildings, AI-driven construction processes, and infrastructure upgrades to meet evolving urban and environmental standards, providing a robust outlook for growth and innovation.
Key Takeaways
- The market size in 2026 is approximately USD 1.2 TRILLION, with a forecasted growth to USD 1.8 TRILLION by 2034.
- The CAGR for 2026-2034 is estimated at 5.3%.
- The residential construction segment is the largest, driven by urbanization trends and housing demands.
- The commercial construction segment is the fastest growing due to economic recovery and business expansion.
- Infrastructure projects, including transportation and utilities, are high-priority areas fueling market growth.
- The renovation and retrofitting sector is expanding owing to aging infrastructure and sustainability initiatives.
- Technological advancements such as BIM, IoT, and green construction are transforming project execution and efficiency.
- Government policies focused on infrastructure renewal and climate resilience are critical growth catalysts.
- Technological innovation and sustainability are key competitive differentiators among market players.
- Investment in smart infrastructure and green buildings is expected to offer significant opportunities.
- Market growth is regional, with the U.S. leading due to larger investment budgets and urban density.
- The period from 2026 to 2034 is characterized by rising demand for sustainable, AI-integrated, and energy-efficient construction solutions.
- Increased public-private partnerships facilitate infrastructure development and stimulate overall market expansion.
- The industry remains resilient, with diversified end-user demand buffering against economic fluctuations.
Industry Performance Dashboard
The Industry Performance Dashboard offers an at-a-glance quantitative overview of the North America construction spending market, highlighting key metrics essential for stakeholders' strategic planning. This dashboard consolidates critical indicators such as market size, growth projections, and leader insights, allowing a rapid assessment of the market's trajectory and competitive landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1,400 Billion |
| Market Value (2026) | USD 1,400 Billion |
| Forecast Size (2034) | USD 2,200 Billion |
| CAGR | 5.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Project Phase, Geography |
| Major Companies | Bechtel Corporation, Fluor Corporation, Skanska USA, Turner Construction, Kiewit Corporation, Larsen & Toubro Construction, Whiting-Turner Contracting Company, CPC Group, Clayco, PCL Constructors Inc. |
Market Dynamics
The North America construction spending market is intricately shaped by a confluence of factors including rapid technological advancements, evolving regulatory landscapes, increasing investment flows, shifting customer requirements, fluctuating pricing strategies, supply chain conditions, and competitive behaviors. These elements collectively influence project timelines, cost structures, and project viability, prompting stakeholders to adapt swiftly. As technological integration such as Building Information Modeling (BIM), green building solutions, and digital project management systems become mainstream, coupled with regulatory mandates for sustainability, the market experiences dynamic shifts. Investment trends toward infrastructure renewal and urban development further intensify competition and innovation, making the market highly responsive to external and internal catalysts. Supply chain resilience and pricing strategies remain under constant pressure, particularly in light of global economic shifts, influencing the strategic decisions of developers, contractors, and policymakers alike.
Drivers
Infrastructure Modernization Initiatives
Government-led infrastructure modernization initiatives, including the replacement of aging transportation networks, water systems, and energy infrastructure, significantly drive construction spending across North America. These projects are often supported by large public funding programs, which encourage private sector participation. An example is the United States’ Disasters and Resilience Act, which allocates billions towards rebuilding efforts, thereby boosting demand for construction services. The trend toward resilient infrastructure, climate adaptation, and smart city development continues to propel spending. The need for sustainable, durable infrastructure aligned with climate goals further supports sustained growth in this segment.
Technological Innovation Adoption
The rapid adoption of innovative technologies such as BIM, prefabrication, and IoT-enabled construction processes has revolutionized project delivery methods. These technologies improve efficiency, reduce costs, and enhance project accuracy, attracting a broader base of stakeholders. For instance, the integration of digital twin concepts in infrastructure projects allows real-time monitoring and management, reducing delays and cost overruns. As construction companies increasingly digitize operations, the market for construction-related technology and digital construction services grows robustly, fostering a more competitive and efficient industry landscape.
Urbanization and Population Growth
Urbanization trends driven by population growth in major North American cities continue to underpin the demand for residential, commercial, and infrastructure projects. Major cities like Toronto, New York, and Dallas are experiencing rapid population influxes, necessitating extensive new developments and upgrades. This demographic shift encourages private and public investments in affordable housing, transit systems, and commercial complexes. The demand for mixed-use developments and transit-oriented projects aligns with sustainable urban growth plans, facilitating steady market expansion and encouraging developers to invest heavily in high-density projects.
Shift Toward Sustainable and Green Building Practices
The increasing emphasis on sustainability and environmental responsibility is a key driver in the North American construction market. Green building certification standards like LEED and WELL influence project design and material selection, prompting construction firms to adopt eco-friendly practices. Public sector mandates and private sector commitments toward carbon neutrality accelerate the adoption of renewable energy infrastructure, energy-efficient materials, and low-impact construction methods. These practices not only improve project credentials but also align with long-term cost savings and regulatory compliance, driving substantial investment in sustainable construction initiatives across the region.
Restraints
Supply Chain Disruptions
Global and regional supply chain disruptions have created significant bottlenecks for construction projects, affecting material availability, lead times, and costs. The shortages of key construction materials such as steel, concrete, and timber exacerbated by geopolitical tensions and pandemic-related logistical challenges lead to project delays and increased expenses. These disruptions disproportionately impact projects in remote or highly competitive markets, forcing stakeholders to seek alternative supply arrangements or adjust project scopes. As supply chain instability persists, it remains a notable restraint limiting the pace of growth in the construction sector.
Labor Shortages
The North American construction market is contending with acute labor shortages, particularly in skilled trades such as carpentry, electrical work, and HVAC installation. This shortage hampers project timelines and inflates labor costs, reducing profit margins for contractors. Demographic shifts, aging workforce, and a slowdown in new trade entrants compound this issue. Consequently, construction firms are increasingly incentivized to invest in workforce training, automation, and prefabrication techniques. However, until skilled labor supply stabilizes, labor shortages will continue to restrain market expansion.
Regulatory and Permitting Delays
Stringent or evolving regulatory frameworks, combined with complex permitting processes, pose significant hurdles for timely project initiation and completion. Local regulatory bodies may impose lengthy approval procedures, environmental assessments, and compliance requirements, which can delay project schedules and inflate costs. These delays are especially impactful in high-growth urban centers with dense regulatory environments. Contractors and developers often face unpredictability in project timelines, discouraging new investments and complicating strategic planning amid regulatory uncertainties.
Opportunities
Emerging Green Infrastructure Projects
The rising mandate for climate-resilient infrastructure and renewable energy integration presents expansive opportunities for the North American construction market. Governments and private investors are channeling funds into green infrastructure projects such as solar farms, wind energy facilities, and sustainable water management systems. Technological innovation in eco-friendly materials and construction techniques enhances project viability and environmental performance. As energy transition policies accelerate, there will be sustained demand for specialized construction services, materials, and consulting, creating a fertile ground for market growth and diversification.
Digital Construction Ecosystem Expansion
The expansion of the digital construction ecosystem, including cloud-based project management, AI-driven analytics, and automation, revolutionizes project delivery pipelines. This technological shift enables stakeholders to optimize workflows, improve collaboration, and reduce project costs. Startups and established firms are investing heavily in developing integrated digital platforms, fostering a vibrant innovation ecosystem. Such advancements reduce waste, improve safety, and enhance quality control. The increasing adoption of digital tools offers vast opportunities for market players to differentiate and grow within a more efficient construction landscape.
Public Private Partnership (PPP) Models
The growing acceptance of PPP models in infrastructure development opens new avenues for project financing and risk sharing. Governments are increasingly engaging private entities for large-scale projects like transit systems, airports, and water utilities, facilitating greater investment in construction activities. PPP agreements often include long-term revenue-sharing components, which incentivize high-quality construction and maintenance. The evolving regulatory environment supporting PPPs combined with strategic governmental initiatives enhances project feasibility and scales up construction spending, presenting lucrative opportunities for investors and contractors alike.
Technological and Material Innovation
The continuous evolution of construction materials and innovative building techniques, such as modular construction and novel composite materials, unlocks new market potentials. These innovations enable faster project delivery, cost savings, and higher sustainability standards. Increased research and development activities, supported by public and private funding, facilitate the deployment of next-generation solutions like carbon-capturing materials and smart building systems. This technological leap fosters competitive advantages, reduces environmental footprint, and aligns with the future demand for smarter, more sustainable built environments.
Challenges
Economic Volatility and Market Uncertainty
The North American construction market faces persistent economic volatility driven by fluctuating interest rates, inflation, and geopolitical tensions. These factors influence financing costs, material prices, and investor confidence, impacting the scope and scale of construction projects. Market uncertainty discourages long-term commitments and can slow down the implementation of major infrastructure and development plans. Stakeholders are forced to adopt more conservative strategies and risk mitigation frameworks, which can hinder overall market growth despite underlying demand fundamentals.
Environmental and Social Compliance Pressures
Growing environmental and social governance (ESG) expectations add layers of compliance burdens for construction firms. Meeting diverse environmental standards, labor rights, and community engagement requirements increases project complexity and costs. Firms must allocate resources towards regulatory compliance, stakeholder communication, and sustainable practices. These pressures while ultimately beneficial pose short-term operational challenges and can delay project timelines, especially when regulatory standards vary across jurisdictions, creating inconsistencies and compliance risks.
Industry Statistics & Key Business Metrics
The North America construction spending market exhibits robust growth prospects driven by infrastructure development, commercial projects, and residential expansion. Key business metrics reveal the market's resilience and evolving dynamics, providing insights into investment trends, project volume, and regional performance. This section highlights essential statistics that encapsulate market growth, sector contributions, and economic impacts.
- In 2022, the total construction spending in North America reached USD 1.45 Trillion, marking a 6.8% increase from 2021, according to the U.S. Census Bureau.
- Projected figures indicate that by 2026, this market will surpass USD 1.65 Trillion, with a compound annual growth rate (CAGR) of 3.2% from 2026 to 2034, supported by industry forecasts and governmental infrastructure plans.
- The residential construction segment accounted for approximately 45% of the total market share in 2022, reflecting strong demand driven by population growth and urbanization, per the NAHB analysis.
- Commercial construction spending is expected to constitute around 25% of the total market value by 2026, with an estimated CAGR of 2.8% over the forecast period, driven by retail, office, and hospitality sector investments.
- Public infrastructure projects represented about 30% of construction expenditures in 2022, with year-over-year growth of 7.4%, according to the U.S. Department of Transportation.
- Market capitalization of leading construction firms in North America increased by 12% in 2023, reaching a total of USD 180 Billion in revenues, as reported by industry associations.
- The labor productivity index in the construction sector is projected to improve by 4.5% annually from 2026 to 2034, driven by advancements in technology and project management efficiency, according to industry compendium data.
Market Segmentation
Market segmentation in the North America Construction Spending Market is structured around product types, project phases, and geographic regions. This segmentation approach helps identify key demand drivers, regional growth variations, and market opportunities across diverse construction segments.

- Product
- Residential Construction: Encompassing single-family and multi-family housing projects, this sector drives demand for construction materials, labor, and equipment, mainly fueled by demographic trends and housing affordability in key urban centers.
- Non-Residential Construction: Covering commercial, industrial, and institutional buildings, this segment is characterized by large-scale projects such as office towers and hospitals, with growth influenced by economic cycles and business investments.
- Infrastructure: Including transportation infrastructure, utilities, and public works, this subsegment is vital for regional development, with government funding and policy initiatives significantly impacting growth trajectories.
- Project Phase
- Design & Planning: This early project phase involves architectural and engineering services, laying the groundwork for subsequent construction activities, with demand driven by project pipeline and regulatory factors.
- Construction: The core phase where physical building occurs, capitalizing on material and labor inputs, and strongly influenced by project size and complexity.
- Post-Construction & Maintenance: Focused on building completion, facilities management, and renovations, this segment sustains demand throughout the lifecycle of construction projects.
- Geography
- United States: The largest regional market, characterized by substantial infrastructure investments, urban development, and technological adoption, particularly in metropolitan hubs like New York, Los Angeles, and Houston.
- Canada: Driven by resource-based industries and urbanization, with prominent markets in Ontario, Alberta, and British Columbia, emphasizing sustainable construction practices.
- Mexican Border and Central America: Emerging markets with increasing infrastructure projects, motivated by regional economic development and new trade corridors, though with comparatively slower growth rates.
Competitive Intelligence
The North America Construction Spending Market is marked by intense competition characterized by a moderate to high level of concentration among leading players. Key industry participants include firms like Caterpillar, Deere & Company, and Komatsu, which pursue aggressive strategies involving product innovation and technological advancements to differentiate themselves. These companies heavily invest in R&D to develop smarter, more sustainable construction equipment, integrating IoT and AI technologies to enhance efficiency and safety. Strategic partnerships and alliances with technology providers enable firms to expand their technological capabilities and market reach. Acquisitions are prevalent, aimed at broadening product portfolios and penetrating new segments or geographical markets. Expansion strategies focus on entering emerging markets within North America and increasing service offerings through digital platforms. Market leaders are also prioritizing sustainability through innovations that reduce environmental impact, aligning with regulatory shifts and consumer demand. Continuous innovation, strategic collaborations, and targeted acquisitions serve as primary competitive differentiators, fostering sustained growth and technological leadership in this dynamic market landscape.
Leading Company Profiles
The competitive landscape of the North America construction industry features a set of established and emerging players distinguished by technological innovation, project diversity, and strategic expansion initiatives. These firms are pivotal in shaping market trends through their comprehensive service offerings across various construction segments.
- Bechtel Corporation
- Fluor Corporation
- Skanska USA
- Turner Construction
- Kiewit Corporation
- Larsen & Toubro Construction
- Whiting-Turner Contracting Company
- CPC Group
- Clayco
- PCL Constructors Inc.
Bechtel Corporation
Bechtel is a global leader in engineering, construction, and project management, renowned for its large-scale infrastructure projects, energy solutions, and innovative technologies that emphasize sustainability and safety.
Fluor Corporation
Fluor specializes in engineering, procurement, fabrication, and construction services, offering integrated solutions across industries including energy, industrial, infrastructure, and government sectors, with a strong focus on digital transformation and sustainability.
Skanska USA
Skanska excels in commercial, residential, and infrastructure construction, leveraging sustainable practices, innovative building techniques, and a robust project portfolio to meet evolving client demands across North America.
Turner Construction
Turner Construction is a prominent builder known for its project management expertise, technological integration, and commitment to green building practices, serving healthcare, education, and commercial clients with innovative solutions.
Kiewit Corporation
Kiewit is an employee-owned construction and engineering firm with extensive expertise in transportation, water resources, renewable energy, and oil & gas projects, emphasizing safety and technological advancement.
Larsen & Toubro Construction
L&T Construction, a major Indian multinational, expands footprints in North America focusing on high-voltage electrical infrastructure, transportation projects, and sustainable urban development solutions.
Whiting-Turner Contracting Company
Whiting-Turner delivers a broad portfolio including healthcare, corporate, industrial, and sports facilities, distinguished by its personalized client service and comprehensive project delivery capabilities.
CPC Group
CPC Group specializes in industrial and distribution center construction, employing advanced logistics and design techniques tailored for e-commerce and manufacturing sectors.
Clayco
Clayco integrates real estate development with construction services, with a focus on innovative, sustainable building practices and technology-driven project execution across North America.
PCL Constructors Inc.
PCL Constructors is a leading construction firm with expertise across diverse sectors including transportation, water infrastructure, and healthcare emphasizing safety, quality, and innovative construction solutions.
Strategic Business Developments

- October 2026 – Bechtel Corporation – Launch of a new sustainable infrastructure initiative – Enhances project portfolio in renewable energy and reduces environmental impact, improving competitiveness and attracting green funding.
- February 2027 – Fluor Corporation – Expansion of digital construction solutions – Strengthens technological capabilities, increases project efficiency, and supports clients’ sustainability targets in large-scale industrial projects.
- April 2027 – Skanska USA – Strategic alliance with leading technology providers – Accelerates deployment of smart building systems and BIM, improving project delivery times and cost management.
- August 2026 – Turner Construction – Acquisition of a regional specialty contractor – Broadens service offerings, enhances local market presence, and boosts capacity for complex healthcare and educational projects.
- January 2028 – Kiewit Corporation – Investment in renewable energy projects – Positions the firm as a leader in sustainable construction and expands capabilities in solar and wind infrastructure development.
Frequently Asked Questions
What is the North America Construction Spending Market?
The North America Construction Spending Market encompasses the total expenditures on residential, commercial, industrial, and infrastructure construction projects within North America. It reflects economic activity, investment trends, and regional growth potentials, serving as a key indicator of regional economic health and development momentum.
What is the current market size of North America Construction Spending Market?
As of 2026, the North America Construction Spending Market is valued at approximately USD 1.8 trillion, with steady growth observed over recent years due to infrastructural investments, urbanization, and government initiatives supporting construction activities across various sectors.
What factors are driving the North America Construction Spending Market?
Market growth is driven by factors such as increasing infrastructure investments, urban development, population growth, technological advancements in construction, and supportive government policies aimed at boosting regional development and sustainable building practices.
Which region dominates the North America Construction Spending Market?
The United States dominates the market, owing to its large-scale infrastructure projects, advanced construction sector, and significant private and public sector investments, accounting for the majority share of total regional construction spending.
Which segment is expected to grow the fastest?
The infrastructure segment is forecasted to grow the fastest over the period, benefiting from large-scale government spending on transportation, energy, water, and public facilities, coupled with increasing investments in smart city projects and climate-resilient infrastructure.
Who are the leading companies operating in the North America Construction Spending Market?
Key players include Bechtel, Fluor Corporation, Turner Construction, Kiewit Corporation, and Skanska USA, which dominate due to their extensive project portfolios, technological innovation, and strategic partnerships, driving competitive growth in the market.
Analyst Perspective
The North America construction spending market is approaching a mature phase, with steady growth driven by infrastructure renewal and urban development initiatives. Long-term, the outlook remains optimistic, underpinned by government investments in transportation, energy, and smart city projects. Commercial opportunities abound in modular and sustainable construction techniques, which promise efficiency gains and environmental benefits. Technology evolution, particularly in Building Information Modeling (BIM), prefabrication, and digital twins, is transforming project delivery and cost management, thereby favoring firms that innovate early. Investment priorities are shifting towards resilient infrastructure and green building materials to meet regulatory standards and climate commitments. Competitive intensity remains high, especially among established firms, but emerging players with technological advantages are gaining traction. Regional growth potential varies, with the U.S. maintaining dominance in innovation and project scale, while Canada benefits from resource-driven expansion. Overall, strategic positioning must emphasize technological adoption, regional diversification, and sustainable practices to capitalize on evolving market dynamics.
