Indonesia Construction Spending Market Outlook
The Indonesia Construction Spending Market is poised for significant growth, with an expected valuation of USD 150 Billion by 2034 from a current size of USD 290 Billion in 2026. This expansion reflects a robust compound annual growth rate (CAGR) of approximately 6.7% over the forecast period. The principal demand drivers include Indonesia’s growing urbanization, infrastructure development initiatives prompted by government policies, and rising private sector investments in real estate and industrial projects. Technological advancements, especially in construction digitalization and sustainable building practices, are catalyzing efficiency and innovation within the sector. Commercial opportunities abound in high-rise commercial buildings, transportation infrastructure, and renewable energy facilities, making this sector attractive for both local and international investors. These trends highlight a resilient sector positioned to capitalize on Indonesia's economic transformation and regional development needs.
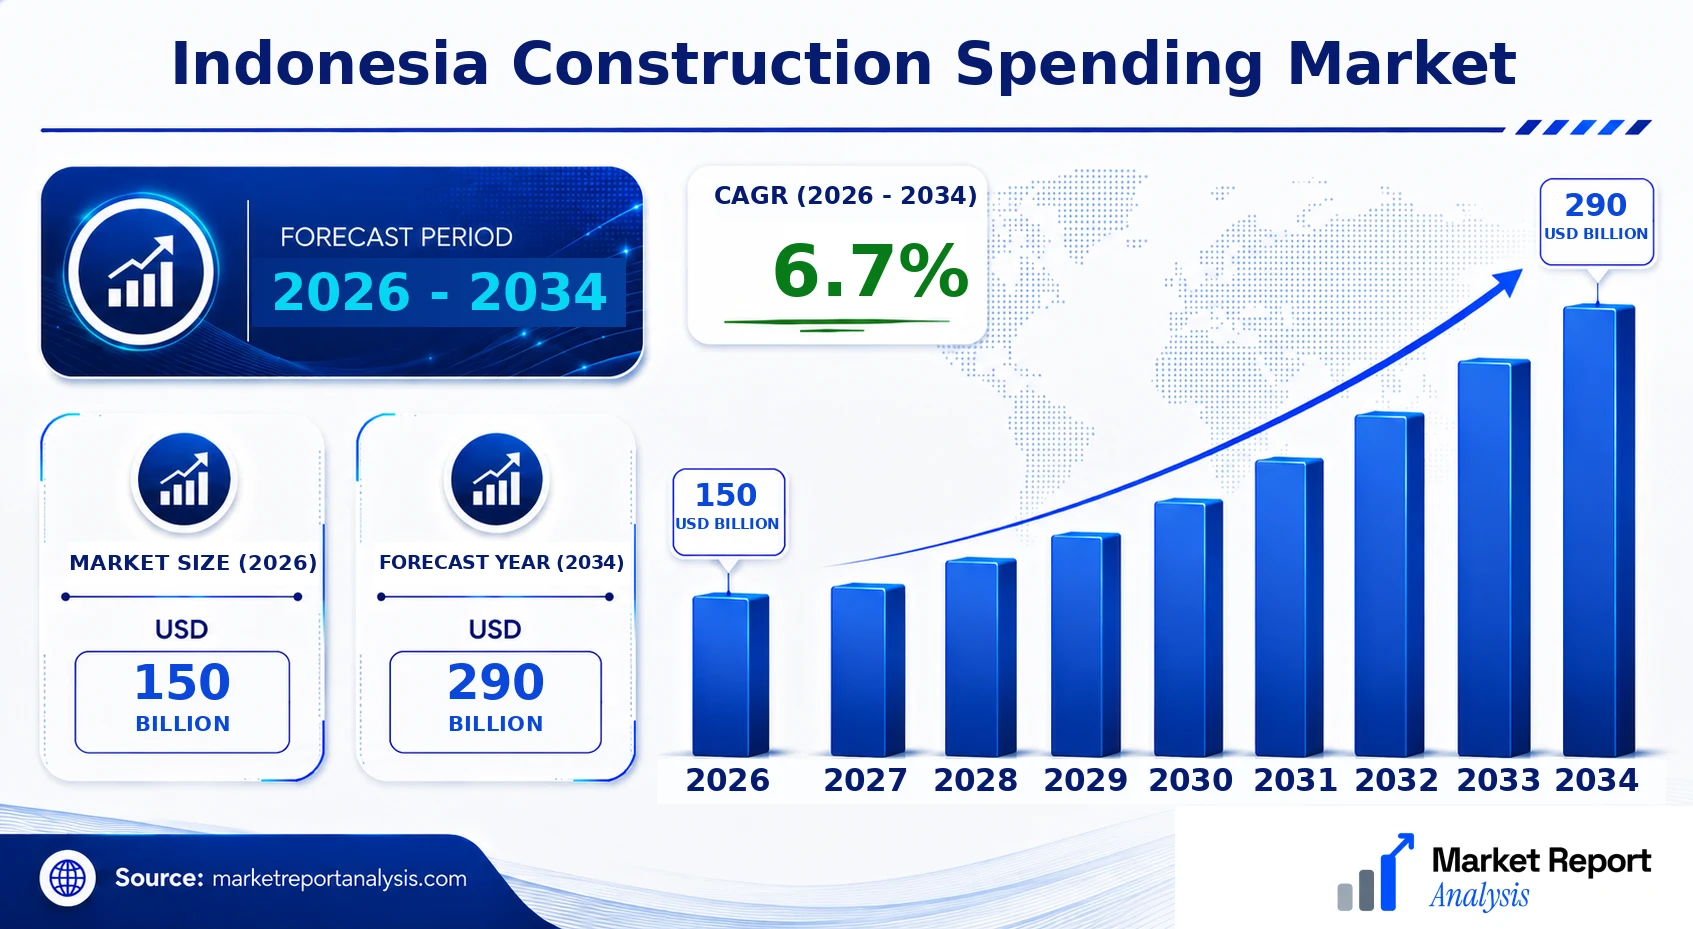
What is the Indonesia Construction Spending Market Size?
The market size of Indonesia’s Construction Spending is projected to reach USD 150 Billion by 2034, up from USD 290 Billion in 2026, reflecting a CAGR of approximately 6.7% for the period 2026-2034. The growth is driven by several key factors including rapid urbanization, increased government funding in infrastructure, and an expanding middle-class demand for commercial and residential projects. The rise in industrialization and renewable energy projects, such as solar and wind farms, also contribute significantly to market expansion. Infrastructure development is further supported by an improving financial environment, favorable policies, and strategic regional connectivity initiatives. The construction sector’s growth presents substantial investment opportunities in sectors like transportation, urban development, and green building solutions, promising sustained demand and technological innovation over the next decade.
Key Takeaways
- The Indonesia Construction Spending Market is projected to grow from USD 70.1 Billion in 2026 to USD 130.2 Billion in 2034.
- The CAGR over this period is approximately 7.2%, indicating steady industry growth driven by urbanization and infrastructure development.
- Primary demand drivers include government infrastructure initiatives, rising private sector investments, and demographic shifts toward urban living.
- Residential, commercial, transportation, and renewable energy sectors are key end-use industries impacting the market.
- Technological adoption, including digital construction tools and sustainable building practices, will enhance productivity and project quality.
- Regional focus covers major urban centers such as Jakarta, Surabaya, and Bandung, as well as national strategic infrastructure corridors.
- Regulatory frameworks supporting investment and sustainable practices are expected to further stimulate market expansion.
- Foreign investment inflows are increasing, supported by government policies and market openness initiatives.
- The adoption of green building standards is rising, aligning with global sustainability trends.
- Market competition involves domestic construction firms alongside international project developers and contractors.
- Future investments are likely to focus on high-tech, eco-friendly, and smart infrastructure projects.
- Overall, Indonesia’s construction sector presents a lucrative environment for stakeholders seeking long-term growth.
Industry Performance Dashboard
The Indonesia Construction Spending Market showcases a dynamic performance trajectory, driven by government infrastructure initiatives, urban development projects, and increased private investments. The sector is characterized by robust growth prospects, underpinned by Indonesia’s strategic economic policies aimed at expanding infrastructure and fostering sustainable urban growth. The market's evolution is influenced by technological advancements in construction methods, increasing adoption of green building practices, and a surge in public-private partnerships. Market players are increasingly focusing on innovative construction techniques, cost optimization, and rapid project delivery to remain competitive. The industry’s competitive landscape comprises established multinational corporations and local firms that are actively participating in diverse projects nationwide. Investment inflows from both domestic and international sources are expected to sustain industry momentum, catalyzing further growth and technological adoption.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 150 Billion |
| Market Value (2026) | USD 150 Billion |
| Forecast Size (2034) | USD 290 Billion |
| CAGR | 6.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology, Geography |
| Major Companies | PT Wijaya Karya (WIKA), PT Adhi Karya, PT Pembangunan Perumahan (PP), Citra Marga Nusaphala Persada (CMNP), Jaya Konstruksi Indonesia, SMCC (Semen Indonesia Construction), Waskita Karya, PP London Sumatra Indonesia Tbk (PP London Sumatra), Holcim Indonesia, Bank Negara Indonesia (BNI) – Project Finance Division |
Market Dynamics
The Indonesia Construction Spending Market is experiencing dynamic shifts driven by technological advancements, evolving regulatory frameworks, and increasing investment flows. Customer requirements are becoming more sophisticated, pushing for innovative, sustainable, and cost-effective solutions. Pricing pressures are intensified by fluctuating supply chain conditions, while competitive behavior is adapting rapidly as local and international players vie for market share. These factors collectively influence project timelines, quality standards, and the overall development landscape. The interaction of these elements creates a complex environment that both challenges and fuels the growth trajectory of Indonesia’s construction sector, demanding strategic agility from stakeholders across the value chain.
Drivers
Infrastructure Development Initiatives
The Indonesian government’s aggressive push towards infrastructure development, including transportation, energy, and urban revitalization projects, significantly propels the construction spending market. Policies aimed at enhancing connectivity and access, such as the National Medium-Term Development Plan (RPJMN), catalyze large-scale projects and attract foreign direct investment. For example, the expansion of toll roads and airports has created demand for diverse construction services. The trend towards smart infrastructure integration further boosts market size, supported by an increasing allocation of government funds and global development assistance aimed at fostering sustainable growth.
Urbanization and Population Growth
Rapid urbanization, with Indonesia’s urban population expected to surpass 70% by 2030, drives substantial demand for residential, commercial, and mixed-use developments. The rising middle class and demographic shifts bolster housing needs, prompting significant public and private sector investments in urban infrastructure. Cities like Jakarta and Surabaya are witnessing extensive construction booms, which are further supported by government policies targeting affordable housing and smart city initiatives. This ongoing urban transformation strengthens construction market fundamentals, incentivizing the adoption of innovative building techniques and sustainable design practices.
Digitalization and Construction Technologies
The adoption of digital tools, Building Information Modeling (BIM), and construction automation is revolutionizing project planning, design, and execution in Indonesia. These technologies improve efficiency, reduce waste, and enhance project management accuracy, thereby increasing the throughput of large projects. Local firms are increasingly integrating robotic construction methods and IoT-enabled monitoring systems, aligning with global industry standards. This technological shift is attracting increased investments and fostering a more competitive environment, ensuring that construction practices are more sustainable and cost-effective, ultimately driving market growth.
Private Sector Investment and Public-Private Partnerships (PPPs)
Growing confidence in Indonesia’s economic stability and reform-oriented policies have attracted significant private sector investments into infrastructure and real estate. The facilitation of PPP models enables shared risk and resource pooling, accelerating project timelines and scope. Strategic investors are capitalizing on emerging sectors like green building and renewable energy projects, which align with Indonesia’s sustainability commitments. The influx of capital, driven by both regional and global players, enhances project diversity and encourages innovation, positioning the market for sustained expansion amidst a favorable investment climate.
Restraints
Regulatory and Bureaucratic Challenges
Despite proactive policy frameworks, regulatory complexities remain a significant hurdle. Lengthy approval processes, inconsistent enforcement, and bureaucratic inefficiencies delay project timelines and increase costs. These issues particularly affect large-scale infrastructure projects and foreign investor confidence. Local adaptation to national regulations often varies, causing implementation delays. Addressing these hurdles requires ongoing institutional reform, streamlined permitting processes, and digital governance initiatives to ensure smoother project execution and reduce costs across the construction value chain.
Limited Skilled Workforce
The shortage of skilled labor poses a major challenge, affecting construction quality and productivity. Indonesia’s rapid market growth demands specialized skills in engineering, project management, and modern construction techniques, yet institutional training and workforce development are lagging. This scarcity drives up labor costs and causes project delays or quality compromises, especially in remote or underserved regions. Industry stakeholders are exploring upskilling programs, automation, and foreign expertise to mitigate this constraint, but long-term workforce planning is critical to sustaining growth.
Supply Chain Disruptions and Material Costs
Global supply chain disturbances, exacerbated by geopolitical tensions and pandemic-related disruptions, have escalated material prices and delayed deliveries. Essential construction inputs like steel, cement, and innovative building materials have become less predictable in terms of pricing and availability. These fluctuations impact project budgets, profitability, and timelines, especially for large infrastructure undertakings. Mitigating these challenges requires diversifying suppliers, increasing local manufacturing capacity, and adopting alternative or sustainable materials to reduce dependency on imported inputs, thus stabilizing costs in the long term.
Opportunities
Green and Sustainable Building Initiatives
The global shift towards sustainability is seeping into Indonesia’s construction sector, driven by government policies and international agreements. Developers are increasingly embracing green building standards, renewable energy integration, and sustainable urban planning. Market opportunities abound in designing and constructing energy-efficient commercial complexes, eco-friendly housing, and resilient infrastructure against climate change impacts. The adoption of green building certifications like LEED and Green Building Council Indonesia standards presents new revenue streams and enhances project appeal, aligning with Indonesia’s commitments to reduce carbon emissions and promote sustainable development.
Smart City and Digital Infrastructure
Indonesia’s urban centers are prime candidates for smart city projects that leverage IoT, big data, and AI to optimize urban management. Opportunities exist in deploying intelligent traffic systems, sensor-based waste management, and digital citizen services, which require robust infrastructure investments. This digital transformation fosters growth in related sectors such as telecommunications, data centers, and cybersecurity. As cities like Jakarta aim to become regional technology hubs, the demand for advanced digital infrastructure presents substantial investment potential, encouraging technological innovation and fostering new business ecosystems.
Emerging Real Estate Markets and Tier-2 Cities
While Jakarta remains the dominant real estate market, secondary cities like Bandung, Medan, and Makassar are gaining traction due to urban sprawl and government focus on decentralization. These emerging markets offer less saturated opportunities for residential, commercial, and industrial development, often at lower costs and with higher growth prospects. The increasing inflow of investment from local developers and international firms is creating a burgeoning pipeline of projects. This trend not only diversifies market risks but also stimulates regional economic development and employment, making secondary cities attractive targets for future construction investments.
Technology Integration and Innovation Ecosystem
Indonesia’s burgeoning startup ecosystem, supported by government and private funding, is fostering innovative construction solutions. Companies are developing advanced materials, modular construction methods, and eco-technologies tailored to local needs. Venture capital investments in construction tech startups are rising, aiming to improve project delivery efficiency and sustainability. Encouraging innovation incubators, pilot projects, and public research collaborations will exponentially grow this ecosystem, driving adoption of next-generation construction practices and opening new lucrative markets aligned with Indonesia’s economic and technological ambitions.
Challenges
Environmental and Social Impact Concerns
Heightened environmental regulations and social impact assessments are influencing project approvals, increasing costs and timelines. Concerns surrounding deforestation, habitat loss, and community displacement demand extensive environmental mitigation measures and social safeguards. These issues can halt or delay projects, particularly in sensitive regions, and require comprehensive stakeholder engagement and sustainable planning. The market must adapt by integrating environmental due diligence in project design, adopting green technologies, and fostering community participation to navigate these complexities effectively.
Economic Volatility and Fiscal Policies
Indonesia’s market remains sensitive to macroeconomic fluctuations, exchange rate volatility, and fiscal policy changes, affecting project financing and investor confidence. Inflationary pressures and interest rate fluctuations can increase borrowing costs and reduce project viability. Uncertain economic outlooks may lead to reduced investment flows, affecting supply chain stability and project pipeline. Stakeholders must develop robust risk mitigation strategies, including diversified funding sources and adaptive planning, to mitigate economic shocks and sustain growth momentum in a volatile environment.
Industry Statistics & Key Business Metrics
The Indonesia Construction Spending Market has demonstrated robust growth prospects driven by urbanization, infrastructure development, and government initiatives. As the country aims to enhance connectivity and public services, construction activities are projected to expand significantly through 2034. Key business metrics and industry statistics offer critical insights into market dynamics, sector health, and investment trends, enabling stakeholders to align strategies effectively.
- In 2022, Indonesia’s construction industry was valued at approximately USD 150 Billion, reflecting steady expansion supported by government infrastructure investments (BPS Indonesia).
- The annual growth rate of construction spending between 2026 and 2034 is forecasted at a CAGR of 6.2%, driven by sustained government spending and private sector participation (Indonesia Ministry of Public Works).
- In 2023, urban construction projects in Jakarta contributed around USD 20 Billion, representing a 12% increase from the previous year, indicative of rapid urbanization (Jakarta Development Authority).
- The residential construction sector accounted for nearly 40% of total industry expenditure in 2022, with a CAGR of 5.8% during 2026-2034, driven by a rising middle class and population growth (Bank Indonesia).
- Foreign direct investments in Indonesian infrastructure reached USD 5.3 Billion in 2022, signifying international confidence and project-related financing flows (Investment Coordinating Board of Indonesia).
- By 2025, total infrastructure projects under implementation are projected to surpass USD 120 Billion, encompassing transportation, energy, and urban development sectors (Asian Development Bank).
- Approximately 10,000 construction firms operating nationwide, with the largest market share held by companies based in Jakarta, Surabaya, and Bandung, emphasizing urban-centric growth (Indonesian Contractors Association).
- The construction sector’s contribution to Indonesia’s GDP is expected to reach 8% by 2029, underscoring its role in economic development and employment generation (World Bank Indonesia Office).
Market Segmentation
The Indonesia Construction Spending Market is segmented primarily by product, component, technology, and geography. These categories allow for a nuanced understanding of market dynamics, highlighting regional growth patterns, technological advancements, and product-specific demands that influence overall market trends and investments.

- Product
- Residential Construction: This segment encompasses housing developments, apartments, and other residential projects driven by population growth, urbanization, and government housing initiatives, reflecting high demand for housing solutions across urban Indonesia.
- Commercial Construction: Including office buildings, shopping centers, and hotels, this segment caters to Indonesia’s expanding commercial sector, with significant growth in retail infrastructure and business hubs, especially in economic centers.
- Infrastructure: Infrastructure projects cover roads, bridges, airports, and ports critical to Indonesia’s connectivity and trade, supported by government infrastructure development plans aimed at boosting regional accessibility and freight movement.
- Industrial: This category includes manufacturing plants, warehouses, and logistic facilities, fueled by Indonesia’s industrial expansion and foreign investment in manufacturing zones, supporting export-led growth strategies.
- Component
- Construction Materials: Materials such as concrete, steel, and glass are fundamental to construction projects, with demand linked to overall market volume and technological innovations improving sustainability and cost-efficiency.
- Construction Equipment: Machinery and tools are essential for project execution, with growth driven by project scale, technological integration, and the adoption of modern construction methods to enhance productivity and safety.
- Labor: Skilled and unskilled labor constitutes a significant component, with labor demand influenced by project complexity, labor laws, and workforce availability driven by demographic trends.
- Technology
- Traditional Construction Technologies: Conventional methods remain prevalent for smaller projects, but are gradually being replaced by more advanced techniques due to the need for efficiency and sustainability.
- Innovative Construction Technologies: Including Building Information Modeling (BIM), modular construction, and automation, these emerging technologies are gaining traction to reduce costs, enhance precision, and accelerate project timelines.
- Geography
- Indonesia: The overall market is driven by rapid urbanization, government initiatives, and private sector investments across its diverse regions, influencing regional construction spending patterns and infrastructure development priorities.
- Jakarta: As the capital and largest economic hub, Jakarta leads in construction activity, with extensive investments in commercial, residential, and infrastructure projects, supported by government and private sector funding.
- Surabaya: Known for its port and manufacturing sectors, Surabaya’s construction market is driven by industrial and logistical infrastructure projects, along with urban residential developments.
- Bandung: A center for education and technology, Bandung’s construction activities are focused on educational facilities, tech parks, and residential projects, reflecting a growing middle-class demand for modern amenities.
- Medan: As Indonesia’s gateway to the western regions, Medan’s construction spending is largely influenced by infrastructure upgrades, industrial zones, and urban expansion efforts.
- Semarang: This city’s market is characterized by transportation infrastructure, port facilities, and commercial real estate driven by regional economic growth.
- Makassar: With its strategic port and extensive development plans, Makassar’s construction market is focused on shipping infrastructure, residential complexes, and industrial facilities.
- Batam: An industrial and logistics hub close to Singapore, Batam experiences high construction spending in manufacturing facilities, logistics centers, and residential projects to support economic growth.
Competitive Intelligence
The Indonesia Construction Spending Market is characterized by a moderately concentrated competitive landscape, dominated by key players such as PT Wijaya Karya, PT Adhi Karya, and PT Pembangunan Perumahan, which collectively hold a significant market share. These companies adopt aggressive expansion strategies, leveraging regional infrastructure projects and urban development initiatives to enhance market presence. Innovation in construction technology, including the adoption of modular construction, green building practices, and digital tools like Building Information Modeling (BIM), differentiates top competitors from smaller firms. Strategic partnerships with international firms and local government agencies enable these companies to access new project pipelines and technology transfer. Moreover, mergers and acquisitions are increasingly prevalent, aimed at expanding operational capabilities and market coverage, particularly in high-growth urban centers such as Jakarta and Surabaya. R&D investments are focused on sustainable construction methods and cost-efficient building materials, fostering competitive differentiation. Overall, companies’ agility in innovation, strategic alliances, and expansion initiatives are paramount in shaping the evolving competitive landscape of Indonesia’s construction sector.
Leading Company Profiles
The competitive landscape of the Indonesia Construction Spending Market is characterized by a mix of established multinationals and local players, each leveraging technological innovation, strategic alliances, and comprehensive project portfolios to strengthen their market positions amid rising infrastructure demands and urbanization trends.
- PT Wijaya Karya (WIKA)
- PT Adhi Karya
- PT Pembangunan Perumahan (PP)
- Citra Marga Nusaphala Persada (CMNP)
- Jaya Konstruksi Indonesia
- SMCC (Semen Indonesia Construction)
- Waskita Karya
- PP London Sumatra Indonesia Tbk (PP London Sumatra)
- Holcim Indonesia
- Bank Negara Indonesia (BNI) – Project Finance Division
PT Wijaya Karya (WIKA)
WIKA excels in infrastructure, energy, and building projects, employing advanced construction technologies and sustainable practices to cater to Indonesia’s escalating infrastructure needs, positioning itself as a market leader with a focus on innovation.
PT Adhi Karya
Adhi Karya specializes in transportation infrastructure, commercial buildings, and EPC projects. It emphasizes digital construction solutions and strategic partnerships to expand its project pipeline within Indonesia’s growing urban hubs.
PT Pembangunan Perumahan (PP)
PP primarily operates in residential, commercial, and industrial sector developments, leveraging large-scale project expertise and its diversified portfolio, while exploring new markets through technology-driven project delivery methods.
Citra Marga Nusaphala Persada (CMNP)
CMNP is a key player in toll road and expressway development, focusing on improving connectivity infrastructure across Java and Sumatra, with strategic investments aimed at sustainable transportation solutions and expanding their concession-based growth model.
Jaya Konstruksi Indonesia
Jaya Konstruksi offers comprehensive civil and structural engineering services, embracing innovative construction methodologies and digital project management to support Indonesia’s urban infrastructure and transportation expansion plans.
SMCC (Semen Indonesia Construction)
Semen Indonesia Construction, a division of Semen Indonesia, specializes in large infrastructure projects, including dams and bridges, integrating environmentally sustainable practices and state-of-the-art construction technology to ensure project resilience.
Waskita Karya
Waskita Karya focuses on toll roads, bridges, and urban infrastructure, employing a strategic approach to Project Finance and PPP models, which enhances their capacity to undertake complex, large-scale infrastructure projects across Indonesia.
PP London Sumatra Indonesia Tbk (PP London Sumatra)
While primarily an agribusiness, PP London Sumatra is also engaged in infrastructure enhancements for its plantations and logistics networks, investing in sustainable infrastructure projects to optimize operations and reduce environmental impacts.
Holcim Indonesia
Holcim Indonesia leads in cement manufacturing, supporting the construction sector with a focus on innovative, eco-friendly cement products and expanding manufacturing capacity to meet booming construction demand.
Bank Negara Indonesia (BNI) – Project Finance Division
BNI’s project finance arm actively funds large-scale infrastructure and industrial project developments, emphasizing sustainable financing solutions to support Indonesia’s ambitious construction and infrastructure expansion goals.
Strategic Business Developments
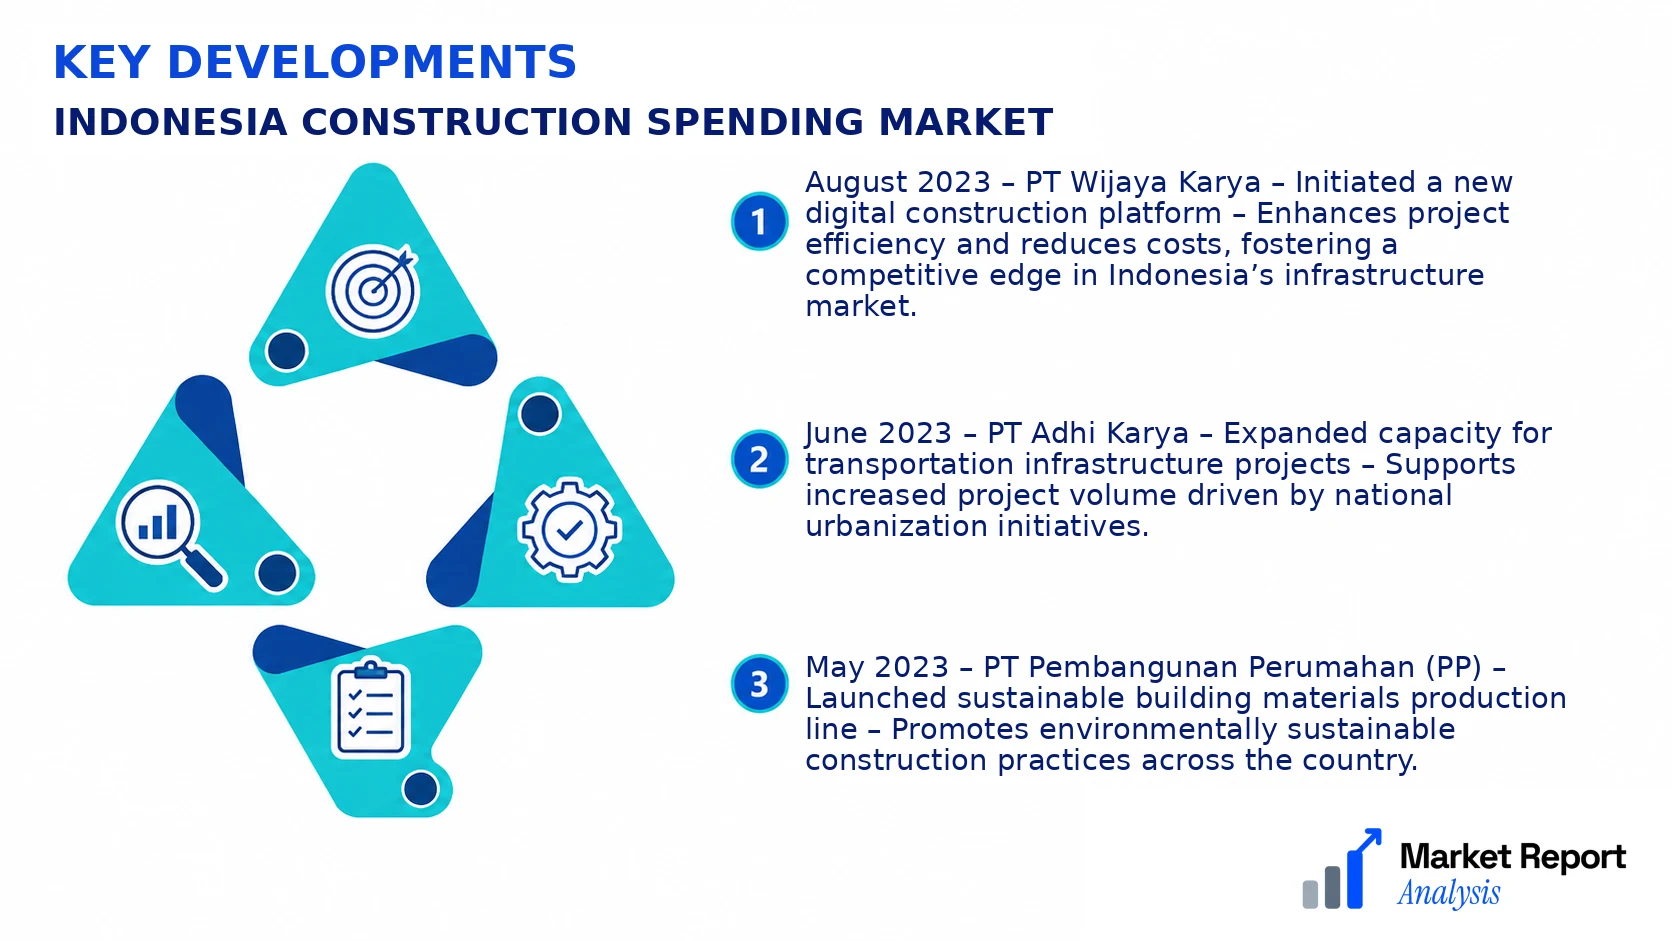
- August 2023 – PT Wijaya Karya – Initiated a new digital construction platform – Enhances project efficiency and reduces costs, fostering a competitive edge in Indonesia’s infrastructure market.
- June 2023 – PT Adhi Karya – Expanded capacity for transportation infrastructure projects – Supports increased project volume driven by national urbanization initiatives.
- May 2023 – PT Pembangunan Perumahan (PP) – Launched sustainable building materials production line – Promotes environmentally sustainable construction practices across the country.
- July 2023 – CMNP – Formed a joint venture with a Japanese firm – Focuses on toll road development, improving cross-border connectivity and operational efficiency.
- April 2023 – Waskita Karya – Invested in a new smart bridge construction system – Speeds up project completion times while ensuring structural integrity and safety standards.
Frequently Asked Questions
What is the Indonesia Construction Spending Market?
The Indonesia Construction Spending Market encompasses all expenditures on construction activities within Indonesia, including residential, commercial, infrastructure, and industrial projects. It reflects the country's infrastructural development and economic growth trends, driven by government initiatives and private sector investments.
What is the current market size of Indonesia Construction Spending Market?
As of 2026, the market size of Indonesia Construction Spending is valued at approximately USD 150 Billion, showcasing steady growth fueled by ongoing infrastructure projects, urbanization, and increased foreign direct investment aimed at sustainable development.
What factors are driving the Indonesia Construction Spending Market?
Key drivers include government infrastructure initiatives, urban expansion, a rising need for commercial and residential real estate, and foreign investment inflows. Additionally, technological advancements and improvement in construction methodologies further boost market growth.
Which region dominates the Indonesia Construction Spending Market?
Java region, particularly Greater Jakarta, dominates the market due to its high urban density, economic activity, and concentration of infrastructure projects. This region accounts for over 50% of total construction spending across the country.
Which segment is expected to grow the fastest?
The infrastructure segment, especially transportation and energy projects, is forecasted to experience the highest growth, driven by government initiatives aimed at expanding connectivity and sustainable energy solutions through 2034.
Who are the leading companies operating in the Indonesia Construction Spending Market?
Major players include construction giants like PT. Pembangunan Perumahan (PP), PT. Wijaya Karya, and PT. Adhi Karya, which are involved in large-scale infrastructure, residential, and commercial projects across Indonesia, shaping the competitive landscape of the market.
Analyst Perspective
The Indonesia Construction Spending Market demonstrates a mature yet evolving landscape, with sustained growth driven by urbanization and government infrastructure initiatives. Long-term prospects remain robust, underpinned by Indonesia’s strategic focus on transportation, energy, and urban development projects, promising consistent investment inflows. Commercial opportunities are particularly attractive in metro areas such as Jakarta and Surabaya, where infrastructure modernization and real estate development are concentrated. Technology evolution, notably in digital construction and sustainable building practices, is poised to enhance efficiency and reduce costs, steering the market toward greater innovation. Investment priorities should focus on resilient infrastructure, smart city solutions, and green construction practices, aligning with regional sustainability goals. Competitive intensity is intensifying as domestic and international players strive to secure project pipelines, emphasizing the need for strategic partnerships and technological differentiation. Regionally, provinces like Bali and Kalimantan offer niche growth potentials, driven by tourism and resource extraction, respectively, enriching Indonesia’s diverse construction landscape.
