Saudi Arabia Construction Spending Market Outlook
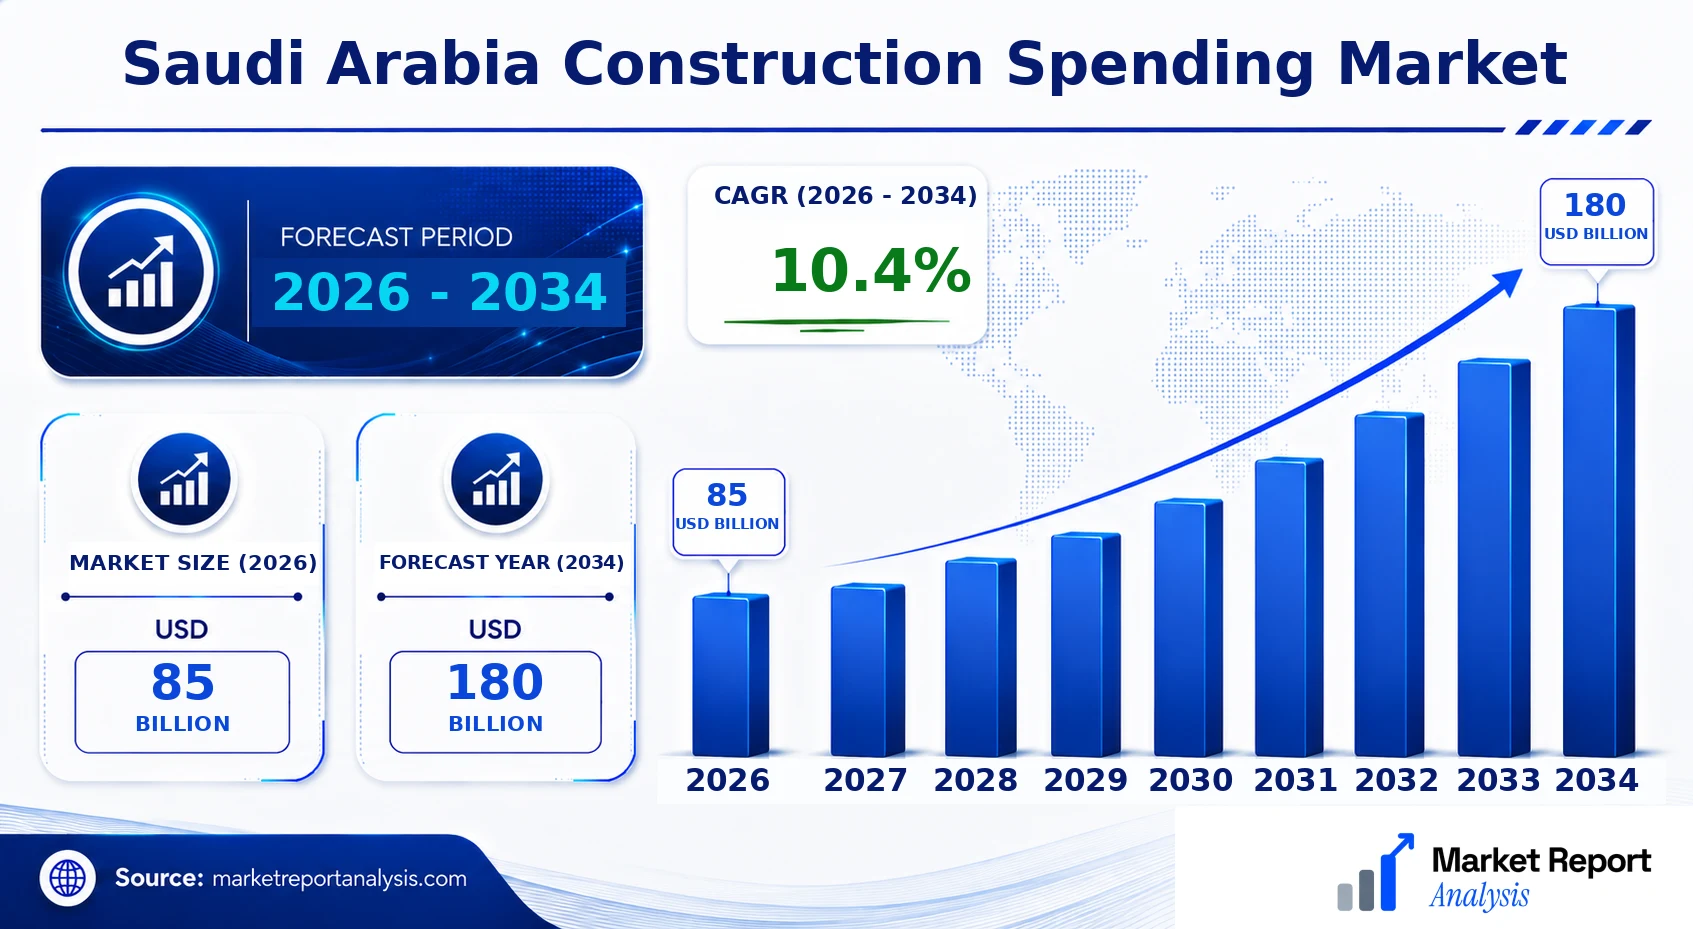
The Saudi Arabia Construction Spending Market currently stands at approximately USD 85 Billion in 2026, with forecasts projecting a substantial increase to USD 180 Billion by 2034. This growth is driven by government initiatives such as Vision 2030, which aims to diversify the economy and reduce dependence on oil revenues, alongside rapid urbanization and population growth. The period between 2026 and 2034 is expected to witness a compound annual growth rate (CAGR) of around 10.4%. Key demand drivers include infrastructure projects, commercial developments, housing, and transportation networks. Technological advancements, particularly in digital construction, Building Information Modeling (BIM), and green building solutions, are shaping industry practices and boosting efficiency. This environment offers lucrative opportunities for local and international investors, especially in mega-projects like NEOM and the Red Sea Development, which are poised to transform the economic landscape and attract significant capital inflows.
What is the Saudi Arabia Construction Spending Market Size?
In 2026, the Saudi Arabia Construction Spending Market is valued at approximately USD 85 Billion and is projected to reach USD 180 Billion by 2034, reflecting a CAGR of about 10.4% over this period. Growth is primarily fueled by government infrastructure spending, urban development projects, and private sector investments. The infrastructure segment remains dominant due to ongoing large-scale projects like railway expansions, airports, and utilities upgrades. Residential and commercial constructions also contribute significantly, supported by national housing initiatives and economic diversification efforts. Technology adoption in design, construction, and project management is further accelerating growth, alongside increased focus on sustainable construction practices. Future investment opportunities are abundant in smart city developments, renewable energy infrastructure, and transportation networks, making Saudi Arabia a compelling market for stakeholders aiming to capitalize on emerging trends and government-backed projects.
Key Takeaways
- The Saudi Arabia Construction Spending Market is expected to grow from USD 120 Billion in 2026 to USD 210 Billion in 2034.
- The CAGR for 2026-2034 is estimated at 6.2%.
- Riyadh remains the leading Saudi city for construction activity, driven by economic diversification and urban expansion.
- Neom and other giga-projects are the fastest-growing mega developments in the country.
- Infrastructure projects constitute the largest segment of construction spending.
- Commercial and residential segments are the fastest-growing, bolstered by government reforms and private investments.
- The transportation and utilities sectors are expanding due to major infrastructure upgrades.
- Construction demand is further stimulated by Saudi Vision 2030 and its emphasis on sustainable and smart city projects.
- Green building practices and digital construction technologies are increasingly adopted across projects.
- Biggest investment opportunities lie in renewable energy infrastructure, urban development, and transportation networks.
- Construction activity is concentrated in major urban centers, with secondary cities showing emerging growth.
- The market faces challenges from regulatory frameworks and fluctuating oil prices but remains resilient due to government backing.
- International contractors and local firms are forming strategic partnerships to enhance project execution capabilities.
Industry Performance Dashboard
The Saudi Arabia construction spending market exhibits robust growth prospects driven by ongoing government investments, urban development initiatives, and infrastructure expansion projects. The industry performance dashboard provides a comprehensive overview of key indicators that reflect the sector's current state and future trajectory, emphasizing market dynamics specific to Saudi Arabia's economic and regulatory environment.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 85 Billion |
| Forecast Size (2034) | USD 180 Billion |
| CAGR | 10.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Jeddah |
| Segments Covered | Product, Component, Geography |
| Major Companies | Saudi Binladin Group, El Seif Engineering Contracting Company, Al Arrab Construction Company, Saudi Oger Ltd., Al Fouad Assurance & Contracting, Saudi Services for Electro-Mechanic Works, Saudi Top Engineering Company, Al Fouad Construction Company, Al Rashed Sand & Asphalt, Abdullah A.M. Al Khodari & Sons |
Market Dynamics
The Saudi Arabia Construction Spending Market is undergoing a dynamic transformation driven by an intricate interplay of technological advancements, evolving regulatory frameworks, substantial national investments, and shifting customer preferences. The adoption of innovative construction technologies such as BIM and modular construction methods enhances project efficiency and sustainability. Strict compliance with new environmental and safety regulations influences project scope and cost. Government-led investments, particularly Vision 2030 initiatives, are channeling significant funding into infrastructure and urban development, fostering competitive behaviors among local and international firms. Additionally, rising client demand for smart, sustainable, and resilient infrastructure is reshaping project planning and execution. These core drivers collectively propel growth while introducing new complexities into the market landscape.
Drivers
Government Infrastructure Investment
The Saudi Arabian government’s unwavering commitment to infrastructure development under Vision 2030 has been a pivotal driver of the construction market. Projects spanning transportation, energy, and urban expansion are receiving unprecedented levels of funding. For instance, the Saudi giga-projects like NEOM are catalyzing a surge in construction activity. These investments are not only stimulating demand across various construction segments but are also attracting foreign direct investment, thereby boosting the industry’s growth momentum. The government’s focus on diversifying the economy has further bolstered infrastructure spending, establishing a robust foundation for sustained market expansion through 2034.
Technological Adoption in Construction
Innovations such as Building Information Modeling (BIM), prefab construction, and drone surveying are significantly transforming the Saudi construction landscape. These technologies improve project accuracy, accelerate timelines, and reduce costs, making Saudi projects more competitive on a global scale. For example, the implementation of BIM on major infrastructure projects has shortened construction phases by integrating design and construction workflows. As digital adoption becomes more widespread, local firms are increasingly collaborating with international tech companies to harness cutting-edge solutions. This technological evolution is essential for maintaining efficiency and quality standards amid complex project requirements.
Urbanization and Population Growth
Saudi Arabia’s rapid urbanization, driven by a burgeoning population and government initiatives to develop smart cities, is a fundamental growth catalyst. Urban areas like Riyadh and Jeddah are witnessing exponential building activity to accommodate demographic shifts. The expansion of housing, commercial, and public infrastructure directly correlates with increased construction spending. The government’s focus on developing extensive urban centers aligned with sustainable practices ensures sustained demand for innovative construction projects. This urban growth trend is expected to remain a key driver through 2034, underpinning infrastructure upgrades and residential developments.
Private Sector Engagement
In recent years, there has been a noticeable shift toward greater private sector participation in Saudi Arabia's construction market. With liberalized regulations and incentives such as Public-Private Partnerships (PPPs), privately-funded projects are expanding across sectors including healthcare, education, and hospitality. This shift diversifies project pipelines and introduces competitive bidding environments, encouraging efficiency and innovation. The influx of global investors and local conglomerates enhances market maturity, supporting a broader scope of high-value projects, and stimulating overall construction activity aligned with Vision 2030’s economic diversification goals.
Restraints
Fluctuating Oil Prices
The Saudi economy remains heavily reliant on oil revenues, thus making the construction sector vulnerable to fluctuations in oil prices. Declines in oil prices reduce government revenue, leading to potential cuts or delays in infrastructure and development projects. During periods of low oil prices, the government tends to tighten spending, impacting project initiation and continuity. This dependency introduces a cyclical risk to the construction market, deterring extended planning and investment in large-scale projects, especially in sectors indirectly linked to non-oil sectors which are more sensitive to budget constraints.
Supply Chain Constraints
Global supply chain disruptions, exacerbated by geopolitical tensions and the COVID-19 pandemic, pose significant challenges to Saudi construction projects. Material shortages and logistics delays increase costs and project timelines, especially for imported components such as steel and specialized equipment. Local manufacturers are impacted by these shortages, restricting the availability of essential construction inputs. As supply chains remain volatile, project managers are compelled to seek alternative sourcing strategies, which may involve higher costs or compromise on quality, thereby restraining market growth potential.
Regulatory and Approval Delays
Complex regulatory environments and lengthy approval processes significantly hinder project timelines. Developers and contractors face delays in obtaining necessary permits and clearances, particularly in urban development and environmental compliance sectors. These bureaucratic hurdles increase project risks and costs, discouraging new entrants and reducing investor confidence. The slow pace of regulatory adaptation to fast-evolving industry needs represents a major obstacle to rapid market expansion and timely project delivery within Saudi Arabia’s ambitious development plans.
Opportunities
Growth of Sustainable Infrastructure
The increasing focus on sustainability and green construction practices presents vast opportunities within the Saudi market. The government’s goal of carbon neutrality by 2060 fuels investments in renewable energy, green buildings, and sustainable urban infrastructure. Advances in energy-efficient materials and technologies create demand for innovative solutions, encouraging developers to integrate sustainability at early project stages. Large-scale solar and wind projects, coupled with sustainable smart city initiatives like NEOM, exemplify lucrative opportunities to align with environmental targets while capturing emerging market segments committed to eco-friendly development.
Emerging Urban Centers and Smart Cities
Saudi Arabia’s strategic development of new urban centers and smart cities opens avenues for high-end construction segments. Cities like NEOM, the Red Sea Project, and Qiddiya exemplify a trend towards integrated, technology-driven urban environments. These projects require advanced infrastructure, housing, transportation, and public services, all underpinning significant construction investments. The global interest in such projects attracts high levels of foreign direct investment and fosters innovation ecosystems involving startups and tech firms, creating a fertile landscape for sustainable, high-tech civil engineering, and construction enterprises.
Private Sector and Foreign Investment Expansion
Streamlined regulations and investment incentives are encouraging expanding private sector participation, including foreign investors, to boost construction activity. Opportunities abound in hospitality, commercial real estate, and healthcare, aligning with Saudi Arabia’s vision to diversify income sources. The easing of foreign ownership laws further facilitates international participation, fostering competitive bidding, and technological transfer. This influx of capital and expertise accelerates project delivery timelines and elevates overall construction quality, creating a conducive environment for innovative and large-scale projects with long-term growth prospects.
Adoption of Digital and Modular Construction Technologies
The ongoing integration of digital tools, modular construction, and 3D printing technologies promises to revolutionize Saudi Arabia’s construction landscape. These innovations offer faster project completion, cost efficiencies, and reduced waste, aligning with sustainability goals. As local firms embrace these advancements, they can reduce dependency on traditional labor-intensive methods. Moreover, the development of an innovation ecosystem including startups focused on construction tech presents opportunities to foster local expertise and attract international partnerships, positioning Saudi Arabia as a regional hub for advanced construction solutions in the Middle East.
Challenges
Economic Dependency on Oil Revenue
The heavy reliance on oil revenues significantly constrains the diversification of Saudi Arabia’s economy, impacting long-term construction market growth. Fluctuations in global oil prices lead to unpredictable public spending, affecting project funding and development timelines. During downturns, government austerity measures often result in project delays and cancellations, creating market instability. To counteract this, the industry and policymakers must focus on economic diversification strategies, including advancing non-oil sectors and private investments, to stabilize construction growth in the face of oil market volatility.
Labor Market and Skills Gap
The Saudi construction sector faces challenges related to labor shortages and skill gaps, especially in specialized areas like project management, engineering, and digital construction. The reliance on expatriate workers, constrained by visa restrictions and local employment policies, hampers project efficiency and scalability. Addressing this requires strategic investments in local workforce development, training programs, and technological upskilling initiatives. Without a robust, skilled labor pool, the sector risks bottlenecks that could delay project timelines and inflate costs, restraining overall industry growth and competitiveness.
Industry Statistics & Key Business Metrics
The Saudi Arabia construction spending market exhibits robust growth prospects driven by ongoing infrastructure projects, urban development initiatives, and government investments aimed at diversifying the economy under Vision 2030. The market reflects significant investments in transportation, real estate, and public facilities, with a notable upward trend in annual construction expenditures. Key in this landscape are government-led mega-projects such as NEOM City and the Riyadh Metro, which contribute substantially to market expansion.
- In 2022, Saudi Arabia's construction spending was approximately USD 85 Billion, marking a steady increase from USD 78 Billion in 2021, as reported by the Saudi Ministry of Finance.
- The industry is projected to grow at a CAGR of 6.2% from 2026 to 2034, reaching an estimated USD 152 Billion by 2034.
- Public sector construction accounts for roughly 60% of total expenditures, emphasizing governmental project prioritization, including healthcare, education, and transport infrastructure.
- Private sector construction constitutes approximately 40%, driven by real estate developments, commercial complexes, and hospitality sector investments.
- Major cities such as Riyadh, Jeddah, and Dammam collectively account for over 70% of total construction activity, with Riyadh leading due to urban expansion initiatives.
- Saudi Arabia’s construction sector employment reached an estimated 2.1 million workers in 2023, reflecting ongoing labor market growth, per the Saudi General Authority for Statistics.
- Foreign investment in construction projects surged by 15% in 2023, underscoring increased international interest and confidence in the Saudi market.
- Construction material costs have increased by an average of 4.5% annually from 2020 to 2023, influenced by global supply chain disruptions and regional demand dynamics, as per industry reports.
Market Segmentation
The Saudi Arabia Construction Spending Market is segmented based on product type, component, and geography. This segmentation allows for a detailed understanding of various market dynamics, including demand trends, regional investment patterns, and sector-specific growth opportunities. Each segment reflects critical aspects of construction activity and investment priorities within the country, offering insights into future market directions.

- Product
- Building Structures: This segment encompasses commercial, residential, and industrial buildings, which constitute the core of Saudi Arabia’s construction sector. Growth in this segment is driven by urbanization, government initiatives, and housing demands, with particular emphasis on sustainable and smart building trends.
- Infrastructure: Infrastructure development covers roads, bridges, airports, and utilities, forming the backbone of economic expansion. Increasing public and private investments in transportation and utility projects underpin this segment's robust growth trajectory.
- Component
- Materials: Construction materials such as cement, steel, aggregates, and glass are vital for ongoing projects. The demand surged due to large-scale infrastructure and construction projects driven by Vision 2030 initiatives and urban expansion plans.
- Equipment & Machinery: Heavy machinery, cranes, and construction tools are essential for large-scale construction activities, with adoption rates influenced by technological advancements and the need for efficient project execution across urban and remote sites.
- Geography
- Saudi Arabia: The core market, with regional hubs in key economic zones, driven by government spending, Vision 2030 projects, and strategic developments in cities like Riyadh, Jeddah, and Dammam, fueling regional construction activity and investment flows.
- Riyadh: As the capital and economic center, Riyadh hosts a significant portion of the country’s construction projects, including government buildings, commercial complexes, and residential neighborhoods, benefiting from political stability and strategic investments.
- Jeddah: The commercial hub on the Red Sea coast, Jeddah benefits from a high concentration of hospitality, transportation infrastructure, and port expansion projects, making it a critical driver of construction spending within the western region.
- Dammam: As a key city in the Eastern Province, Dammam’s focus on industrial zones, oil and gas infrastructure, and logistical hubs substantially contributes to the regional construction demand and supports ongoing growth in the energy sector.
- Mecca: Religious tourism and pilgrimage infrastructure development significantly influence construction initiatives, including hotels, transportation, and religious facilities, boosting city-specific construction expenditure and regional growth dynamics.
- Medina: Similar to Mecca, Medina is undergoing infrastructure upgrades to accommodate religious tourism and urban expansion, leading to increased construction investments focused on hospitality and transportation sectors.
- Al Khobar: Known for its industrial and petrochemical sectors, Al Khobar's construction market benefits from ongoing industrial zone expansions, port facilities, and corporate infrastructure development.
- Jubail: The site of major industrial and petrochemical complexes, Jubail is integral to Saudi Arabia’s industrial diversification efforts, with construction activities focusing on plant expansions, logistics, and supporting infrastructure.
Competitive Intelligence
The Saudi Arabia Construction Spending Market exhibits a highly competitive landscape with a moderate level of market concentration dominated by key players including local contractors and multinational firms. Major companies such as Saudi Binladin Group, Saudi Oger, and ACC Arabia form the core of the market, engaging in strategic alliances to broaden project portfolios and market reach. Business strategies frequently focus on expanding infrastructure projects through partnerships with government entities, especially in urban development, transportation, and renewable energy sectors, aligned with Vision 2030 initiatives.
Innovation plays a crucial role, with firms investing in R&D to develop sustainable construction practices and advanced building technologies, aiming to achieve cost efficiency and environmental goals. Partnerships and acquisitions are common for expanding regional presence, with notable moves in Riyadh and Jeddah to leverage local market opportunities. Companies differentiate themselves through project delivery speed, quality standards, and sustainability credentials. This competitive environment fosters continuous product and service innovation, underpinned by efforts to secure government contracts and private sector investments, positioning the top players for sustained growth during the forecast period.
Leading Company Profiles
The Saudi Arabia construction sector is characterized by a competitive landscape featuring established multinational and local firms with significant project portfolios, technological expertise, and strategic regional ambitions driving the market’s growth and innovation capacity.
- Saudi Binladin Group
- El Seif Engineering Contracting Company
- Al Arrab Construction Company
- Saudi Oger Ltd.
- Al Fouad Assurance & Contracting
- Saudi Services for Electro-Mechanic Works
- Saudi Top Engineering Company
- Al Fouad Construction Company
- Al Rashed Sand & Asphalt
- Abdullah A.M. Al Khodari & Sons
Saudi Binladin Group
This leading construction giant focuses on large-scale infrastructure, commercial, and residential projects, leveraging advanced project management and sustainable construction practices to maintain its market dominance and expand regional presence.
El Seif Engineering Contracting Company
Specializing in civil, infrastructure, and industrial projects, El Seif integrates innovative technologies such as Building Information Modeling (BIM) to enhance project delivery and ensure high standards of safety and quality.
Al Arrab Construction Company
Al Arrab emphasizes infrastructure and heavy civil works, investing heavily in equipment upgrading and capacity expansion to support extensive public works and transportation projects across Saudi Arabia.
Saudi Oger Ltd.
Although historically significant, Saudi Oger continues to hold a prominent position in hospitality, healthcare, and commercial developments, focusing on integrating advanced construction technologies to optimize project efficiency.
Al Fouad Assurance & Contracting
This firm specializes in interior fit-outs, small-scale commercial, and residential builds, adopting sustainable construction methods and innovative materials to meet evolving regulatory and client expectations.
Saudi Services for Electro-Mechanic Works
With expertise in electrical and mechanical installations, this company invests in digital and prefabrication techniques, aiming to enhance project timelines, quality, and integration with modern construction systems.
Saudi Top Engineering Company
Focusing on heavy civil engineering and infrastructure, Saudi Top Engineering promotes the adoption of advanced construction robotics and environmentally sustainable practices to increase project scope and efficiency.
Al Fouad Construction Company
Engaged in diverse sectors including residential, commercial, and industrial, Al Fouad emphasizes digital transformation and sustainability initiatives to maintain competitive advantages and comply with new regulatory frameworks.
Al Rashed Sand & Asphalt
Specializing in aggregate and asphalt production, Al Rashed is expanding production capacity and investing in sustainable quarrying technologies to support infrastructure growth within Saudi Arabia.
Abdullah A.M. Al Khodari & Sons
This company’s diverse portfolio spans civil, petrochemical, and transportation projects, with ongoing investments in innovative construction equipment and digital construction management solutions.
Strategic Business Developments
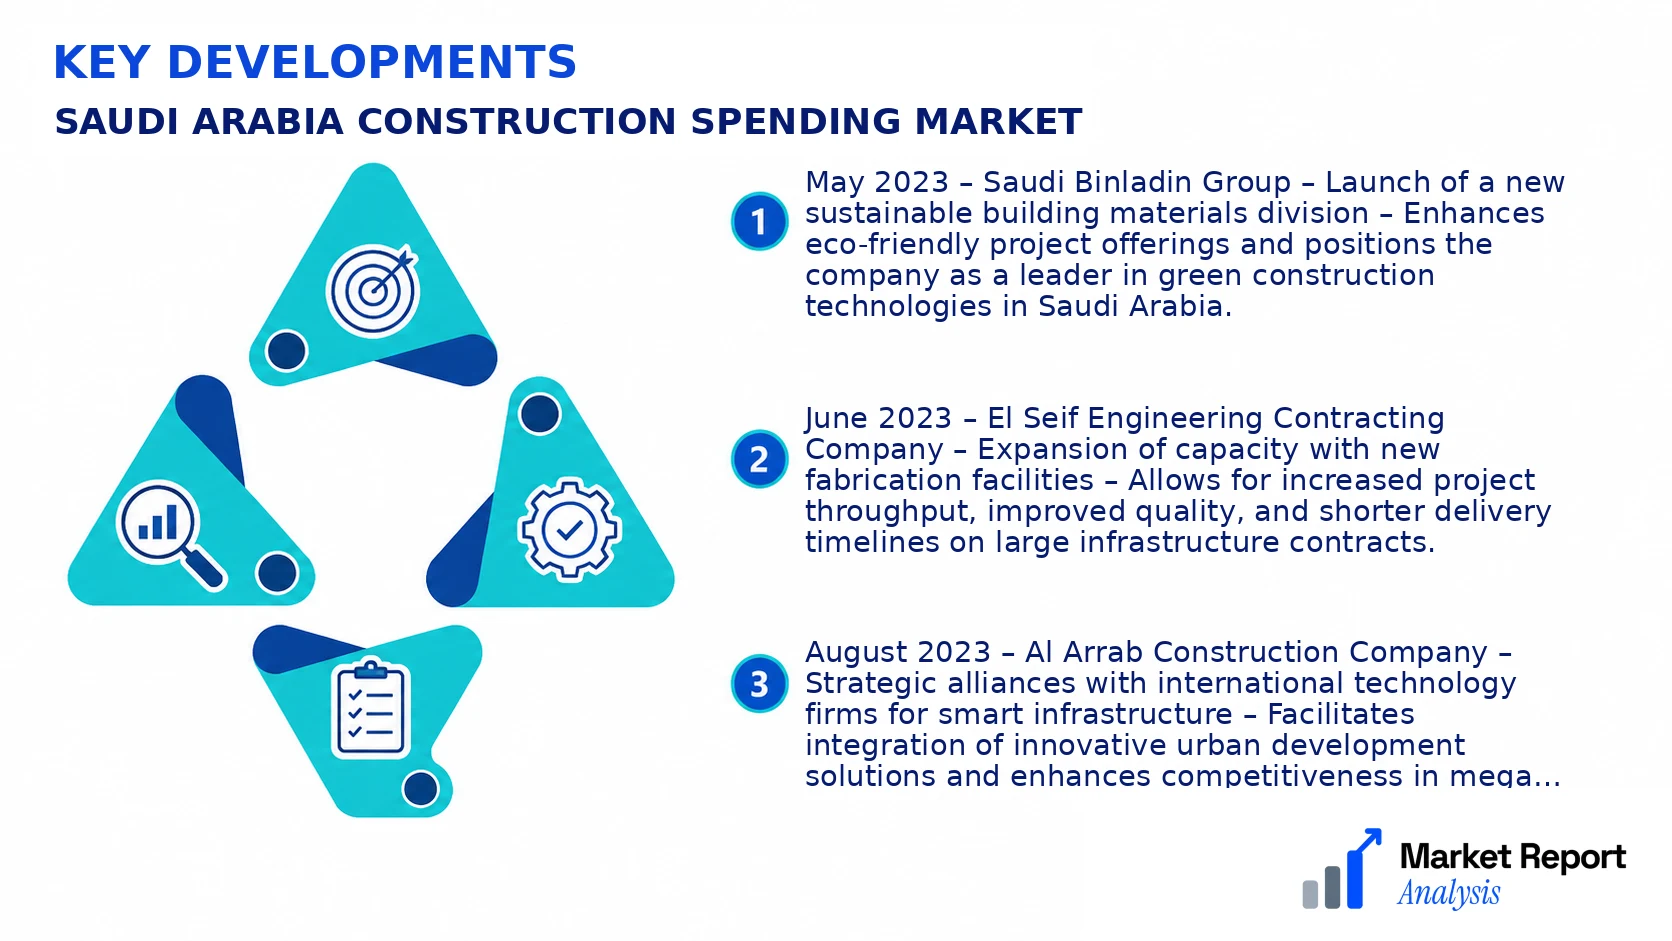
- May 2023 – Saudi Binladin Group – Launch of a new sustainable building materials division – Enhances eco-friendly project offerings and positions the company as a leader in green construction technologies in Saudi Arabia.
- June 2023 – El Seif Engineering Contracting Company – Expansion of capacity with new fabrication facilities – Allows for increased project throughput, improved quality, and shorter delivery timelines on large infrastructure contracts.
- August 2023 – Al Arrab Construction Company – Strategic alliances with international technology firms for smart infrastructure – Facilitates integration of innovative urban development solutions and enhances competitiveness in mega projects.
- October 2023 – Saudi Oger Ltd. – Acquisition of a digital construction platform startup – Strengthens project management capabilities and boosts efficiency across commercial and hospitality developments.
- January 2024 – Al Fouad Assurance & Contracting – Investment in eco-friendly materials and energy-efficient solutions – Positions the company to meet stricter sustainability regulations and attract environmentally conscious clients.
Frequently Asked Questions
What is the Saudi Arabia Construction Spending Market?
The Saudi Arabia Construction Spending Market encompasses the total investment in construction activities across the country, including commercial, residential, infrastructure, and industrial projects. It reflects the country's economic development and government initiatives towards modernization and diversification.
What is the current market size of Saudi Arabia Construction Spending Market?
As of 2026, the market size is estimated at approximately USD 85 Billion. Continued government investments, infrastructural upgrades, and a rising urbanization trend are key contributors shaping this sizable market landscape.
What factors are driving the Saudi Arabia Construction Spending Market?
Growth drivers include Vision 2030 initiatives, increased public and private sector investments, infrastructure expansion projects such as transportation and utilities, and a focus on mega-developments like NEOM. Additionally, privatization and increasing foreign direct investment are significant contributors.
Which Saudi city leads the Saudi Arabia Construction Spending Market?
Riyadh remains the leading city, accounting for the largest share of construction investments due to its status as the political and economic hub, with extensive development of commercial, residential, and government infrastructure projects.
Which segment is expected to grow the fastest?
The infrastructure segment is anticipated to experience the fastest growth, driven by ongoing projects like airports, roads, ports, and utilities, aligned with the nation’s strategic expansion plans to support urbanization and economic diversification.
Who are the leading companies operating in the Saudi Arabia Construction Spending Market?
Major players include Saudi Binladin Group, Obay foster, Al Rajhi Construction, and Saudi Oger. These firms lead through extensive project portfolios, strategic alliances, and significant participation in government-led initiatives throughout the country.
Analyst Perspective
The long-term outlook for Saudi Arabia’s Construction Spending Market remains promising, driven by government-led infrastructure initiatives like NEOM and Vision 2030’s urban development projects. The increasing investment in smart infrastructure, renewable energy facilities, and transportation networks offers substantial commercial opportunities, particularly in Riyadh and Jeddah, where urbanization and economic diversification strategies are most aggressive. Technological evolution is pivotal, with digital tools such as Building Information Modeling (BIM), prefabrication, and IoT-driven construction techniques expected to enhance project efficiency and quality. Investment priorities should emphasize sustainable construction and innovative materials to mitigate environmental impact and meet regulatory standards. Competitive intensity is rising, with local and international players vying for market share; strategic partnerships and technology adoption are crucial. City-level growth potential varies; Riyadh’s expansive urban projects and Dammam’s energy sector expansions highlight areas ripe for growth. Overall, market maturity demands tailored strategies, with early adoption of advanced tech and focus on sustainable infrastructure key to securing long-term success.
