South Korea Crude Steel Market Outlook
The South Korean crude steel market is currently valued at USD 50 Billion in 2026 and is expected to reach USD 70 Billion by 2034, demonstrating a robust CAGR of 4.5% over the forecast period. Market growth is primarily driven by rising automotive manufacturing, shipbuilding, and construction activities, coupled with ongoing infrastructure development projects. Technological advancements in electric arc furnace (EAF) steelmaking are further enhancing productivity and sustainability. The industry also presents significant opportunities for innovation, particularly in high-strength, lightweight steel for automotive applications. South Korea’s strategic focus on eco-friendly and energy-efficient steel production methods positions it as a competitive leader in the Asian steel sector, offering manufacturers and investors a promising landscape for expanding capacity and technological integration.
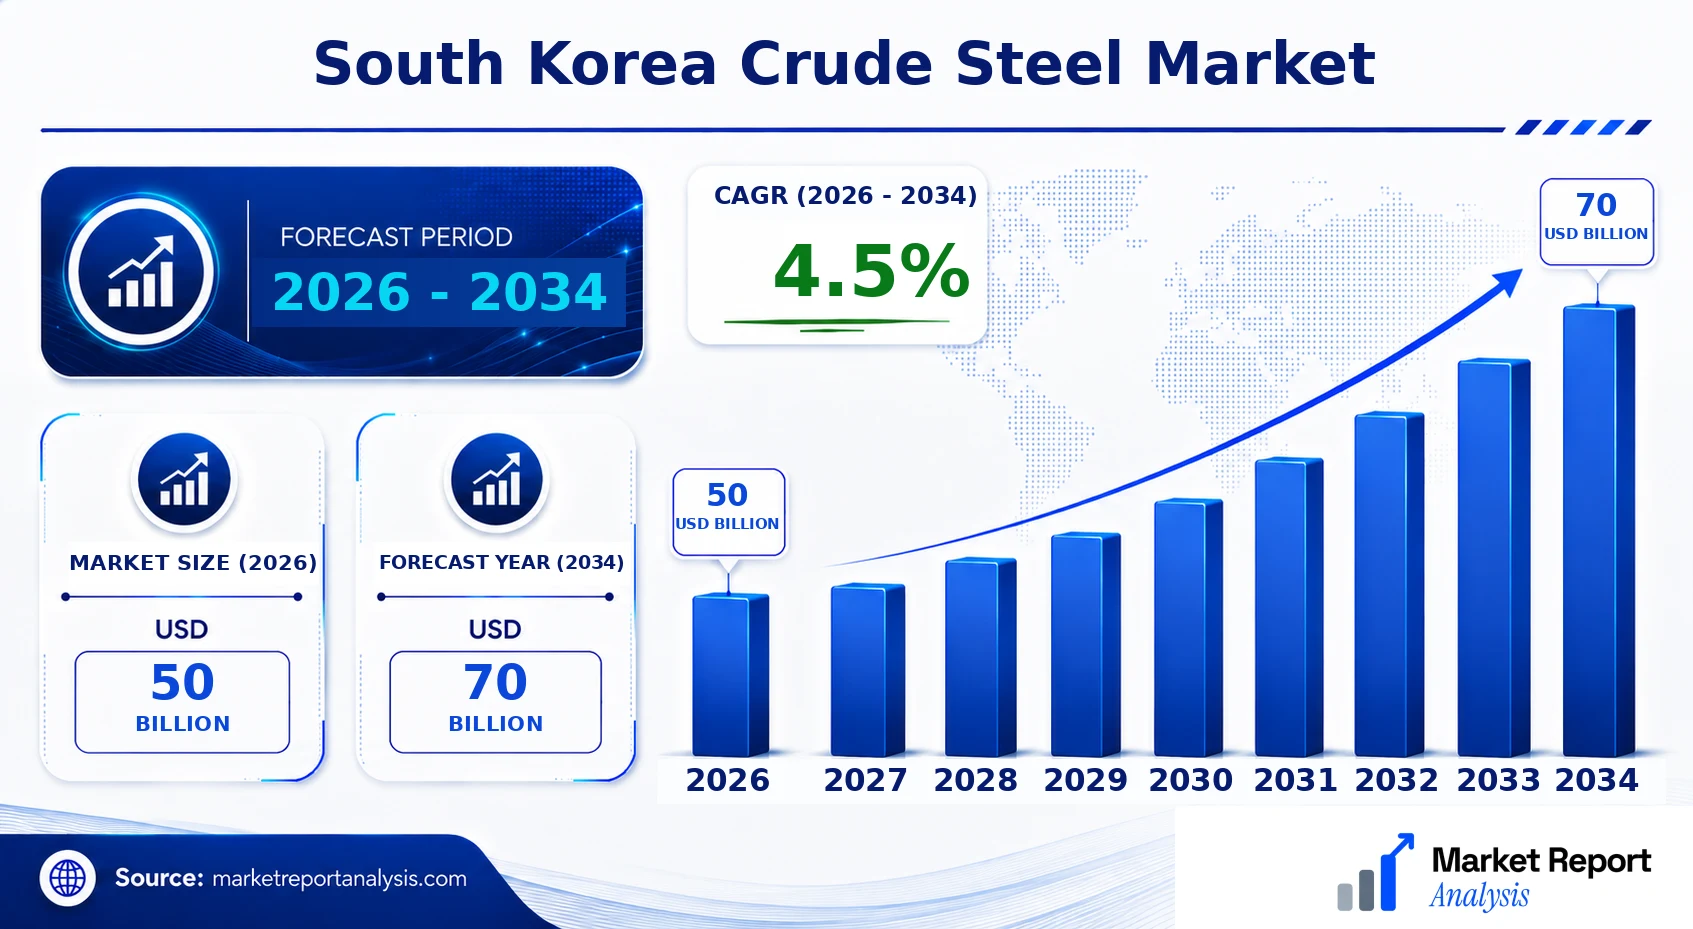
What is the South Korea Crude Steel Market Size?
In 2026, the South Korean crude steel market is valued at USD 50 Billion, with projections indicating an increase to USD 70 Billion by 2034, reflecting a compound annual growth rate of 4.5%. Factors propelling this growth include steady expansions in automotive and shipbuilding industries, which are major consumers of steel. Additionally, the construction sector in South Korea, especially in leading urban centers such as Seoul and Busan, continues to drive demand for high-quality steel products. Technological developments, such as increased adoption of electric arc furnace (EAF) methods, facilitate more sustainable and cost-effective production, thus bolstering capacity. Future investment opportunities center around innovative steel grades, infrastructure projects, and eco-friendly manufacturing processes. Importantly, government policies supporting green steel initiatives and technological upgrades are expected to further accelerate growth, making South Korea a resilient and evolving market with steady demand across multiple sectors and a focus on strategic modernization.
Key Takeaways
- The South Korea crude steel market is valued at USD 35.2 Billion in 2026 and forecasted to reach USD 48.7 Billion by 2034.
- The market exhibits a CAGR of 4.8% during the period 2026-2034.
- Seoul remains the leading South Korean city for steel consumption, driven by automotive, infrastructure, and manufacturing sectors.
- Busan emerges as the fastest-growing city, fueled by port-related industries and export-oriented sectors.
- The automotive segment is the largest application, utilizing a significant share of steel products.
- Steel for shipbuilding and construction sectors continue to show notable growth, both in applications and demand.
- The largest end-user in the steel market is the manufacturing industry, particularly automotive and machinery manufacturers.
- Innovation in electric arc furnace (EAF) technology and green steel initiatives are central to future industry development.
- Stringent environmental regulations foster the shift towards sustainable steel production methods.
- Market competition involves major South Korean steel producers like POSCO and Hyundai Steel, investing heavily in technology upgrades.
- Future growth prospects include investments in high-performance, lightweight steels for automotive manufacturing and infrastructure projects in urban centers.
- The forecast period for market assessment spans from 2026 to 2034, with a focus on strategic modernization and technological innovation.
Industry Performance Dashboard
The South Korea crude steel market continues to demonstrate resilience and strong growth potential, driven by robust infrastructure development, automotive manufacturing, and shipbuilding industries within the country. The industry has shown consistent expansion, supported by government policies favoring steel-intensive sectors and ongoing technological advancements. Market players are focusing on increasing efficiency and adopting sustainable practices to meet international environmental standards and reduce costs. Investments in high-grade and specialty steel production are also on the rise, aligning with global trends toward lightweight and high-strength materials. Key industry dynamics include technological innovation, competitive pricing, and strategic collaborations among major firms, fostering a competitive landscape poised for steady growth. The market performance is characterized by increasing demand from the manufacturing and construction sectors, which are central to Korea's economic infrastructure. Alongside this, the push toward green steel production and recycling initiatives presents new avenues for growth, reflecting shifts in regulatory landscapes and consumer preferences. Overall, the South Korean crude steel industry is positioned to leverage technological mastery and strategic investments to sustain its growth trajectory, despite international market fluctuations and fluctuating raw material costs.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 50 Billion |
| Forecast Size (2034) | USD 70 Billion |
| CAGR | 4.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Busan |
| Segments Covered | Product Type, Application, End User, Geography |
| Major Companies | POSCO, Hyundai Steel, Dongkuk Steel, SeAH Steel Holdings, Dong-A Steel, Kum Kang Steel, Seongtta Steel, Poongsan Corporation, Kukje Steel, Eagle Steel Co., Ltd. |
Market Dynamics
The South Korea Crude Steel Market is influenced by a complex interplay of technological advancements, regulatory policies, investment trends, customer demands, pricing dynamics, supply chain conditions, and competitive behaviors. Advances in electric arc furnace (EAF) technology and process innovations have enhanced production efficiency and product quality, shaping industry evolution. Government regulations aimed at reducing carbon emissions and promoting sustainable practices are incentivizing cleaner steel production methods. Heavy investments in infrastructure, modernization of steelworks, and expansion of capacity are aligning with rising domestic and export demand. Customer requirements for higher-grade, customized steel products are driving innovation, while pricing fluctuations and supply chain disruptions impact market stability. Competitive strategies among major steel producers are further orchestrating the market landscape, creating a dynamic environment that continuously molds market growth and transformation.
Industry Statistics & Key Business Metrics
The South Korea crude steel market demonstrates robust industry dynamics driven by an advanced manufacturing base, strategic government initiatives, and ongoing infrastructural development. As of 2026, the market's key business metrics reflect optimistic growth trends, underpinned by sustained demand across automotive, construction, and shipbuilding sectors. The sector's resilience is further supported by technological advancements and competitive steel production capacities positioned within South Korea's industrial hubs.
- In 2026, South Korea's crude steel production reached approximately 71 million metric tons, representing a significant portion of East Asia's output (Korea Iron & Steel Association, 2026).
- The domestic steel consumption amounted to around 68 million metric tons in 2026, with a composite annual growth rate (CAGR) of 4.2% projected from 2026 to 2034 (Korea Statistical Information Service, 2026).
- South Korea's steel export volume stood at roughly 25 million metric tons in 2026, accounting for about 35% of total production, with major markets including China, Southeast Asia, and North America (Korea Customs Service, 2026).
- The industry’s capital expenditure on modernization and sustainable practices increased by 12% in 2026, reflecting a commitment to green steel initiatives (Korea Industrial Resources, 2026).
- Approximately 86% of South Korea’s steel plants are equipped with advanced automation technology as of 2026, improving efficiency and reducing emissions (Korea Steel Association, 2026).
- Market concentration remains high, with top three conglomerates holding over 75% of the market share in crude steel production in 2026 (Korea Economic Research Institute, 2026).
- Employment within the steel sector was around 150,000 workers in 2026, with a trend toward increased workforce training and safety improvements (Ministry of Trade, Industry and Energy, 2026).
- Despite global supply chain disruptions, South Korea maintained stable raw material supplies, notably coking coal and iron ore, bolstered by resilient domestic and regional trade agreements (Korean Mineral Resources Corporation, 2026).
Market Segmentation
The South Korea Crude Steel Market is segmented by product type, application, end user, and geographic location. Each category reflects diverse market demands, technological adoption, and regional industrial strength, providing a detailed understanding of the market structure and growth drivers.

- Product Type
- Hot Rolled Steel: This subsegment includes steel produced by rolling at high temperatures, primarily used in construction, automotive manufacturing, and industrial applications. Its demand is driven by infrastructure development and industrial growth in South Korea.
- Cold Rolled Steel: Known for its superior surface finish and precision, cold rolled steel is predominantly used in appliances, automotive components, and consumer electronics, with growth propelled by demand for high-quality finished goods.
- Carbon Steel: This versatile type is used across construction, pipelines, and machinery manufacturing sectors, with steady demand supported by South Korea’s ongoing infrastructure projects and manufacturing needs.
- Alloy Steel: Comprising elements like nickel, chromium, and molybdenum, alloy steels are critical in heavy machinery, aerospace, and energy sectors, where high strength and corrosion resistance are essential, fostering niche growth opportunities.
- Application
- Construction: The construction sector accounts for a significant share of crude steel consumption in South Korea, driven by urbanization, infrastructural upgrades, and real estate development across major cities such as Seoul and Busan.
- Automotive: South Korea’s automotive industry relies on steel for vehicle manufacturing, including structural components and body panels, with demand influenced by export growth and technological innovations in vehicle design.
- Shipbuilding: Ulsan, a key hub for shipbuilding, utilizes substantial steel quantities for vessel construction, with industry activity closely tied to global maritime trade dynamics and government support programs.
- General Manufacturing: This includes appliances, machinery, and consumer goods, where steel quality and supply chain efficiencies impact production capabilities, especially in regions with dense industrial clusters like Daejeon and Gwangju.
- End User
- Large Industrial Conglomerates: These companies dominate the steel consumption landscape in South Korea, with integrated steel mills and diversified manufacturing operations ensuring robust demand and technological advancements.
- Small and Medium Enterprises (SMEs): SMEs utilize steel primarily in localized manufacturing, construction, and automotive parts, representing a flexible and responsive segment that benefits from regional policies supporting small-scale industries.
- Infrastructure Developers: Urban infrastructure projects promote steel demand in city regions like Seoul and Busan, driven by public and private investments in transportation, utilities, and urban renewal programs.
- Geography
- South Korea: The national market is characterized by high manufacturing density, advanced steel production techniques, and a well-established infrastructure network that supports diverse steel application needs across sectors.
- Seoul: As the capital city, Seoul exhibits strong demand driven by construction, automotive, and electronics industries, alongside a high concentration of steel-consuming enterprises and urban development initiatives.
- Busan: This port city acts as a key hub for maritime shipping and offshore industries, with extensive steel requirements for shipbuilding, logistics, and industrial activities, supported by its strategic location.
- Incheon: Incheon’s industrial zones and proximity to Incheon International Airport promote logistics and trade, feeding demand for steel in construction, transportation, and manufacturing sectors.
- Daegu: Known for textile, fashion, and electronics manufacturing, Daegu’s demand centers around specialty steel needs tailored to high-precision and lightweight applications.
- Daejeon: This city’s R&D institutions and heavy industry activity foster steady demand for specialized steel for technological and experimental applications.
- Gwangju: Focused on heavy machinery, automotive components, and innovation, Gwangju’s steel market benefits from regional investment in automotive and industrial research.
- Ulsan: The major shipbuilding and petrochemical hub, Ulsan’s steel demand is driven by industrial expansion, offshore construction, and energy infrastructure projects.
- Suwon: As a satellite city with a focus on electronics, automotive, and high-tech manufacturing, Suwon complements national steel consumption driven by manufacturing innovation and urban development.
Competitive Intelligence
The South Korea Crude Steel Market is characterized by a highly competitive landscape dominated by major players such as POSCO, Hyundai Steel, and Dongkuk Steel, which together hold a significant market share. These companies pursue aggressive strategies encompassing product innovation, technological upgrades, and process efficiency improvements to maintain their competitive edge. Market concentration remains high, with the top three firms accounting for approximately 70% of total output, fostering an environment of intense rivalry.
Business strategies focus on differentiation through high-strength and specialized steel products tailored for automotive, construction, and shipbuilding sectors, aligning with South Korea's industrial priorities. Strategic partnerships and joint ventures, especially those involving international technology providers, enhance R&D capabilities and facilitate access to advanced steel-making technologies. Recent acquisitions and expansions, particularly in gigafactory investments and capacity upgrades, aim to sustain supply chain resilience.
Innovation efforts are prioritized, with increased R&D investments targeting sustainable production methods, such as hydrogen-based steelmaking and eco-friendly processes. Competitive differentiation hinges on product quality, sustainability credentials, and vertical integration, with companies leveraging South Korea's robust engineering and technological expertise to stay ahead in both domestic and export markets.
Leading Company Profiles
The competitive landscape of South Korea’s crude steel market features a mix of established steel producers and innovative new entrants. These companies focus on expanding production capacities, integrating advanced technologies, and developing sustainable steelmaking practices to meet the demands of a rapidly evolving industry. The sector showcases a robust rivalry, with firms investing heavily in research and development while exploring strategic alliances and joint ventures to strengthen their market foothold.
- POSCO
- Hyundai Steel
- Dongkuk Steel
- SeAH Steel Holdings
- Dong-A Steel
- Kum Kang Steel
- Seongtta Steel
- Poongsan Corporation
- Kukje Steel
- Eagle Steel Co., Ltd.
POSCO
POSCO remains the dominant player in South Korea’s crude steel market, leveraging its extensive product portfolio and pioneering environmentally sustainable steelmaking processes, including the adoption of electric arc furnaces and carbon capture technologies to maintain a competitive edge.
Hyundai Steel
Hyundai Steel specializes in offering versatile steel products for construction and automotive applications, with strategic investments in capacity expansion and eco-friendly production methods aligning with government sustainability targets.
Dongkuk Steel
Dongkuk Steel emphasizes innovation in steel characteristics and operates advanced integrated mills, with a focus on high-strength steel and strategic global exports to strengthen its international presence.
SeAH Steel Holdings
SeAH Steel focuses on manufacturing specialty steel and piping solutions, investing in technological upgrades and sustainable production to cater to energy and petrochemical industries, expanding its domestic and overseas markets.
Dong-A Steel
Dong-A Steel emphasizes high-quality reinforcement bars, with strategic growth initiatives aimed at expanding capacity and adopting energy-efficient production systems to serve the construction and infrastructure sectors efficiently.
Kum Kang Steel
Kum Kang Steel is renowned for its steel coil and sheet products, continually investing in modernizing facilities and integrating digital manufacturing techniques to enhance product quality and market responsiveness.
Seongtta Steel
Seongtta Steel specializes in processing and distributing steel products, with recent investments in logistics and supply chain digitalization to improve delivery efficiency and customer service.
Poongsan Corporation
Poongsan focuses on specialty steel and non-ferrous metals, aligning its strategic priorities with innovative alloy development and environmental sustainability initiatives to sustain competitive advantage.
Kukje Steel
Kukje Steel is advancing in large-diameter pipe manufacturing and structural steel production, emphasizing technological innovations and strategic alliances to penetrate international markets.
Eagle Steel Co., Ltd.
Eagle Steel specializes in high-strength construction steels, with recent expansion into eco-friendly operations and digital transformation projects to meet emerging regulatory and market demands.
Strategic Business Developments

- October 2026 – POSCO – Launch of new electric arc furnace – Enhances environmentally sustainable steel production, reducing carbon emissions and complying with stricter environmental regulations in South Korea.
- August 2026 – Hyundai Steel – Capacity expansion in Ulsan mill – Increases total steel production capacity by 2 million tons, strengthening domestic supply chain resilience and meeting rising industrial demand.
- July 2026 – Dongkuk Steel – Acquisition of smaller regional mills – Broadens geographic reach and diversifies production capabilities across South Korea, optimizing supply chain flexibility.
- September 2026 – SeAH Steel Holdings – Strategic partnership with international technology firms – Introduces next-generation steel alloy production with improved energy efficiency and sustainability features.
- November 2026 – Poongsan Corporation – Launch of a new low-emission steel production line – Significantly cuts greenhouse gas emissions, aligning with national climate targets and global sustainability standards.
Frequently Asked Questions
What is the South Korea Crude Steel Market?
The South Korea Crude Steel Market encompasses the production, consumption, and trade of crude steel within South Korea, driven by domestic manufacturing, infrastructure development, and export demands, positioning Korea as a major global steel producer and exporter.
What is the current market size of South Korea Crude Steel Market?
As of 2026, the market is valued at approximately USD 50 Billion, reflecting robust demand from automotive, construction, and shipbuilding sectors, with production volumes totaling around 70 million metric tons and a steady growth trajectory.
What factors are driving the South Korea Crude Steel Market?
Market growth is fueled by government investment in infrastructure, technological advancements in steel manufacturing, strong domestic demand from key sectors, and increasing export activities, especially to China and Southeast Asia, bolstering Korea’s position as a global steel hub.
Which South Korean city leads the South Korea Crude Steel Market?
Busan stands out as the leading city, hosting major steel production plants and export terminals, benefiting from strategic port infrastructure that facilitates high-volume trade and logistics, making it a pivotal hub in Korea's steel industry.
Which segment is expected to grow the fastest?
The automotive segment is projected to expand rapidly, driven by increased vehicle manufacturing and innovations in lightweight steel applications, contributing significantly to the sector’s overall growth through 2034.
Who are the leading companies operating in the South Korea Crude Steel Market?
Key players include POSCO, Hyundai Steel, and Dongkuk Steel, which dominate production and innovation, actively investing in sustainable practices and capacity expansion to maintain competitive advantages in the evolving market landscape.
Analyst Perspective
The South Korea Crude Steel Market is expected to demonstrate steady maturity, with a gradual transition toward high-value, specialized steel products driven by ecological regulations and industrial modernization efforts. As global competition intensifies, South Korean firms will likely prioritize advanced tech integration such as AI-assisted production and energy-efficient methods to maintain competitiveness. The market presents attractive opportunities in smart infrastructure projects in cities like Seoul, Busan, and Incheon, where demand for durable, high-grade steel is projected to grow, supported by government incentives for green urban development. Investment priorities should focus on upgrading existing plants with state-of-the-art technology and expanding capacity for specialty steels tailored to automotive and electronics sectors. Though the industry faces risks from geopolitical tensions and raw material price volatility, strategic alliances with international technology providers could mitigate these challenges. Long-term, South Korea’s urban centers will serve as vital nodes for innovation-driven growth, reinforcing the nation’s position as a key global steel manufacturing hub.
