Europe Crude Steel Market Outlook
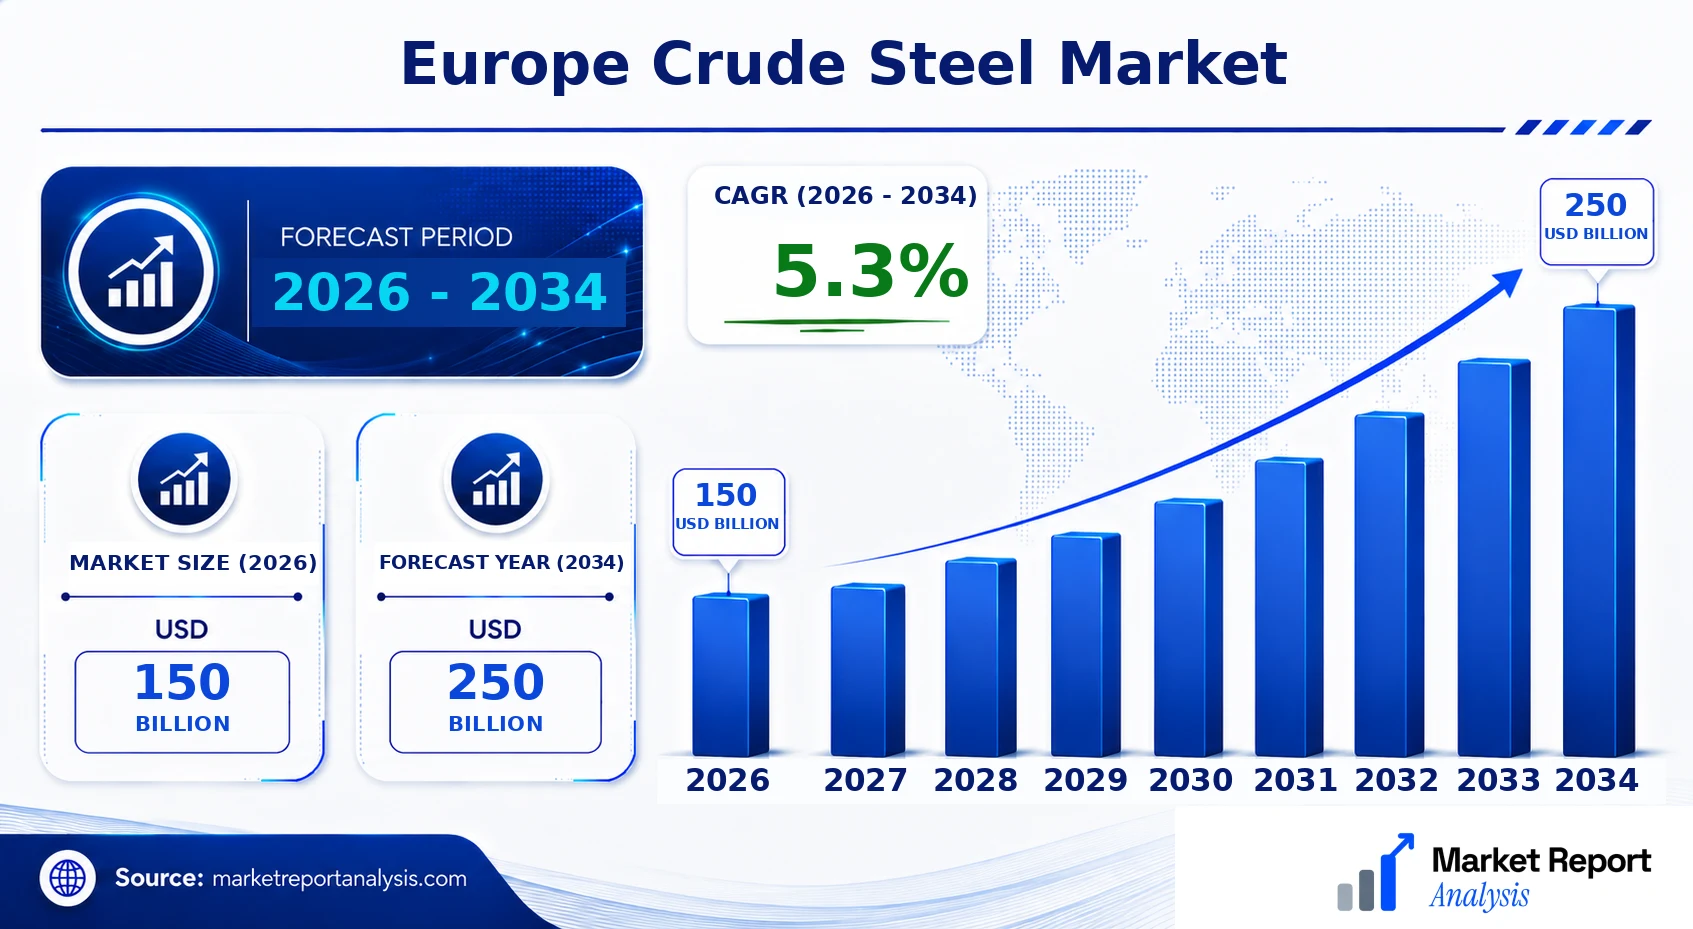
The Europe crude steel market is currently valued at approximately USD 150 Billion in 2026, with projections indicating an increase to around USD 250 Billion by 2034, exhibiting a compound annual growth rate (CAGR) of 5.3% over the forecast period of 2026-2034. This growth is driven by rising infrastructural development, expanding automotive and construction sectors, and increasing urbanization across Europe. Advancements in steel production technologies, such as electric arc furnace (EAF) methods, are fostering more environmentally sustainable and cost-efficient manufacturing processes. The demand for high-strength, lightweight steel alloys is rising, creating significant commercial opportunities for innovation and new product development. Additionally, policy shifts towards decarbonization and sustainable manufacturing practices are encouraging investments in greener steelmaking technologies and recycling initiatives, shaping both technological and market dynamics in this region.
What is the Europe Crude Steel Market Size?
In 2026, the Europe crude steel market size is approximately USD 150 Billion, forecasted to grow to about USD 250 Billion by 2034, representing a CAGR of 5.3%. The growth is chiefly propelled by increased demand in the automotive, construction, and machinery sectors, which are key end-users of steel. Urban infrastructure projects, coupled with renovations and expansions in existing facilities, continue to underpin demand. Technological enhancements, including adoption of electric arc furnaces and sustainable practices, are helping to mitigate environmental concerns and enhance production efficiency. Moreover, shifting consumer preferences for lightweight and high-strength steel variants in automotive manufacturing are providing opportunities for product innovation. Investments in steel recycling infrastructure are also expected to boost supply chain sustainability and cost-effectiveness, further stimulating market growth. The region’s focus on reducing carbon emissions and compliance with environmental regulations is likely to drive investments towards cleaner steelmaking technologies, supporting long-term industry stability and growth prospects.
Key Takeaways
- The market size was approximately USD 150 Billion in 2026, with an expected growth to USD 225 Billion by 2034.
- The CAGR during 2026-2034 is 5.2%, reflecting steady growth supported by regional demand and technological advances.
- The automotive sector remains the largest end-user segment, driven by lightweight steel requirements.
- Construction and infrastructure projects are the fastest-growing applications, responding to Europe's urbanization and renovation trends.
- Electric arc furnace technology is dominant, favored for its sustainability and cost savings.
- Germany, France, and Italy are the leading markets, with increasing regional integration supporting growth.
- Automation and digitalization in steel production are key drivers of efficiency improvements and competitiveness.
- Environmental regulations are shaping industry investments toward greener and more sustainable practices.
- High demand for high-strength and alloy steels signals innovation opportunities in manufacturers' portfolios.
- The increasing focus on recycling and circular economy principles is advancing sustainable industry practices.
- Investments in modern steelmaking infrastructure are projected to grow, supporting future capacity expansion.
- Market competitiveness is intensifying, with key players adopting strategic alliances and technological innovations.
- Future regulatory policies aiming at decarbonization will influence technology adoption and market dynamics.
Industry Performance Dashboard
The Europe crude steel market exhibits a dynamic landscape driven by shifting demand patterns, technological advancements, and evolving regulatory frameworks. The industry performance dashboard provides a concise overview of critical metrics that depict the current state and forecasted trajectory of the market. This section highlights the key indicators and their market assessments, drawing a comprehensive picture of regional market health and growth prospects.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 150 Billion |
| Market Value (2026) | USD 150 Billion |
| Forecast Size (2034) | USD 250 Billion |
| CAGR | 5.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, End-User Industry, Geography |
| Major Companies | ArcelorMittal, Thyssenkrupp AG, Salzgitter AG, Voestalpine AG, Tata Steel Europe, Mechel PAO, Liberty Steel Group, SSAB AB, NLMK Europe, Riva Group |
Market Dynamics
The Europe Crude Steel Market is experiencing significant transformation driven by technological advancements, environmental regulations, strategic investments, and shifting customer demands. Increasing emphasis on sustainability prompts adoption of greener steelmaking processes, compelling manufacturers to innovate. Regulatory frameworks across EU countries aim to reduce carbon emissions and enhance recycling efforts, influencing production methods and investment strategies. Competitive behavior is evolving as firms seek to optimize costs while meeting stricter standards. Price volatility, supply chain dynamics, and the need for technological upgrades shape market strategies. Customer preferences for higher-quality, sustainable steel products are sparking innovation and diversification. These factors collectively create a complex, dynamic environment that demands agility and strategic foresight to capitalize on emerging opportunities while navigating constraints and challenges.
Industry Statistics & Key Business Metrics
The Europe Crude Steel Market is characterized by robust growth fundamentals driven by increasing infrastructural needs, sustainable manufacturing initiatives, and technological advances in steel production. As markets evolve, key metrics demonstrate considerable expansion and resilience within the region. These statistics highlight the market's current performance and projections, serving as vital indicators for stakeholders and investors.
- In 2026, Europe's crude steel production is expected to reach approximately 150 million metric tons, reflecting a CAGR of 3.2% from 2026 to 2034, according to industry reports.
- Market valuation in 2026 is projected to be USD 100 Billion, with forecasts indicating growth to USD 132 Billion by 2034, driven by increased demand across construction, automotive, and machinery sectors.
- Steel consumption per capita in Europe stood at about 300 kg in 2026, with a slight upward trend anticipated through the forecast period.
- European steel exports amounted to approximately 35 million metric tons in 2026, showcasing a 2.5% annual increase, according to European Steel Association data.
- Import levels in 2026 are estimated near 15 million metric tons, predominantly from Asian markets, underscoring Europe's reliance on foreign steel sources.
- Energy consumption per ton of crude steel produced in Europe was approximately 25 gigajoules in 2026, with ongoing efficiency improvements expected to reduce this figure.
- Steel prices experienced an average of USD 600 per ton in 2026, with fluctuations closely tied to global supply chain dynamics and raw material costs.
- The employment rate in Europe's steel industry was around 500,000 workers in 2026, with employment forecasted to grow steadily aligned with market expansion and innovation initiatives.
Market Segmentation
Europe's crude steel market is segmented based on product type, end-user industry sectors, and geographical regions within Europe. This segmentation allows for an in-depth understanding of the market dynamics, consumer demands, and regional growth patterns, facilitating targeted strategic planning and investment decisions.

- Product Type
- Standard Steel: Standard steel products encompass a broad range of structural and manufacturing steel that are widely used in construction, automotive, and machinery sectors, reflecting high demand and a significant share in the European market.
- Specialty Steel: Specialty steels, which include alloy, stainless, and high-strength steels, serve niche applications such as aerospace and defense, demanding advanced metallurgical properties and commanding premium prices.
- End-User Industry
- Construction & Infrastructure: This sector remains the largest consumer of crude steel, driven by ongoing urbanization, green building projects, and infrastructural developments across European countries, supporting robust steel demand.
- Automotive & Transportation: The automotive industry’s shift toward electric vehicles and lightweight materials is fueling a surge in steel consumption, especially high-strength variants for safety and efficiency enhancements.
- Machinery & Equipment: Machinery manufacturing in Europe demands high-quality steel for industrial machines and tools, with demand amplified by technological innovations and increased manufacturing activities.
- Other Industries: This includes secondary sectors such as household appliances, packaging, and renewable energy, which utilize steel for various applications and are experiencing varying demand trends based on technological advances and economic conditions.
- Geography
- Western Europe: Characterized by mature markets like Germany, France, and the UK, Western Europe exhibits steady demand driven by established industries, high standards for environmental sustainability, and technological advancements.
- Eastern Europe: Showing rapid growth potential, Eastern Europe benefits from emerging manufacturing hubs, infrastructural projects, and policy incentives promoting industrial development and steel utilization.
- Nordic Countries: Marked by a focus on sustainable construction and advanced infrastructure, Nordic countries demand high-quality, green steel options, aligning with regional sustainability goals.
- Southern Europe: Featuring diverse economies, Southern Europe's steel demand is influenced by building activities, renovation projects, and renewable energy initiatives, often constrained by economic flexibility and regulatory factors.
Competitive Intelligence
The Europe Crude Steel Market is characterized by a high degree of competition, with several key players maintaining significant market share. Market concentration remains moderate, with top companies such as ArcelorMittal, Thyssenkrupp, and Salzgitter holding strategic positions through diverse product portfolios and regional strengths. Companies are aggressively pursuing innovation, focusing on eco-friendly technologies and energy-efficient production methods to differentiate themselves in a sustainability-driven landscape. Strategic partnerships and alliances have become pivotal, with steelmakers collaborating with machinery providers, technology firms, and frontline recycling firms to enhance operational efficiencies and expand product lines. Acquisitions are common, enabling companies to increase capacity and diversify geographic reach recently, several firms have expanded into Eastern European markets. Heavy investments in R&D underpin competitive differentiation, particularly in developing low-carbon and high-strength steel grades tailored for automotive, construction, and infrastructure applications. These strategies collectively fortify players’ market positions and drive innovation, ensuring resilience amid evolving regulatory and environmental standards.
Leading Company Profiles
The competitive landscape of the Europe crude steel market features a diverse group of established global steel producers, regional champions, and innovative new entrants focused on technological advancement, sustainability, and market expansion.
- ArcelorMittal
- Thyssenkrupp AG
- Salzgitter AG
- Voestalpine AG
- Tata Steel Europe
- Mechel PAO
- Liberty Steel Group
- SSAB AB
- NLMK Europe
- Riva Group
ArcelorMittal
As the world's largest steel producer, ArcelorMittal leverages advanced technologies and extensive integrated operations to deliver high-quality crude steel, focusing on sustainable practices and strategic acquisitions to strengthen its market position across Europe.
Thyssenkrupp AG
Thyssenkrupp specializes in the production of both flat and long steel products, with a strong emphasis on innovative steelmaking processes, digital integration, and expanding capacity to meet growing automotive and construction sector demands.
Salzgitter AG
This German steel group emphasizes technological innovation and environmental sustainability, investing heavily in electric arc furnace (EAF) facilities, and digital transformation to improve efficiency and reduce carbon footprint.
Voestalpine AG
Known for high-quality special steel and wire rod products, Voestalpine focuses on precision manufacturing and high-tech solutions, positioning itself as a premium supplier for automotive, aerospace, and energy markets within Europe.
Tata Steel Europe
Tata Steel's European operations are pivotal in its global strategy, with ongoing capacity upgrades, sustainable steel initiatives, and a focus on eco-friendly production practices to meet evolving customer and regulatory standards.
Mechel PAO
Mechel primarily focuses on niche markets with specialty steels, investing in modern furnace technologies and expanding its European footprint to capitalize on niche demand for durable and high-performance steel products.
Liberty Steel Group
Liberty Steel, part of GFG Alliance, accelerates growth through capacity expansions, technological innovation, and sustainability efforts aimed at reducing emissions and increasing the use of recycled materials in steel production.
SSAB AB
Specialized in high-strength steel and ultra-high toughness steels, SSAB emphasizes technological leadership and sustainability, pioneering fossil-free steel projects to future-proof its product offerings in European markets.
NLMK Europe
NLMK Europe focuses on flat steel solutions, investing in state-of-the-art melting shops, digital operations, and energy-efficient technologies to secure its role as a key supplier in automotive and packaging sectors.
Riva Group
Primarily operating in niche markets, Riva Group emphasizes innovation and customization in specialty steels, expanding its European footprint via technological upgrades and strategic collaborations to meet industry-specific needs.
Strategic Business Developments

- August 2023 – ArcelorMittal – Announced the expansion of its electric arc furnace capacity in Europe, aiming to increase output by 15%, enhancing competitiveness and reducing reliance on external suppliers.
- June 2023 – Thyssenkrupp AG – Launched a new digital platform for real-time monitoring of steel plant operations, boosting efficiency, and enabling predictive maintenance to minimize downtime.
- May 2023 – Salzgitter AG – Invested €200 million in a new sustainable steelmaking line utilizing hydrogen, intending to significantly lower carbon emissions and align with EU green initiatives.
- April 2023 – Voestalpine AG – Formed a strategic partnership with a technology startup to develop advanced steel alloys for aerospace applications, leveraging innovative R&D capabilities.
- January 2024 – Tata Steel Europe – Completed the capacity upgrade of its steel production facility, increasing environmental sustainability and aligning with EU climate targets through energy efficiency measures.
Frequently Asked Questions
What is the Europe Crude Steel Market?
The Europe Crude Steel Market encompasses the production, distribution, and consumption of crude steel within European countries. It includes steel produced from raw materials such as iron ore and scrap, serving diverse industries including construction, automotive, and manufacturing sectors across the region.
What is the current market size of Europe Crude Steel Market?
As of 2026, the Europe Crude Steel Market is valued at approximately USD 150 Billion, reflecting ongoing industrial demand and regional manufacturing activity. Market analysis indicates steady growth driven by technological advancements and infrastructure development initiatives across Europe.
What factors are driving the Europe Crude Steel Market?
Key growth contributors include increased infrastructure investments, rising automotive production, modernization projects, and the European Union’s focus on sustainable steel manufacturing. Additionally, technological innovations and environmental regulations are incentivizing cleaner and more efficient steel production processes.
Which region dominates the Europe Crude Steel Market?
Western Europe holds the largest market share, primarily due to advanced industrial infrastructure, higher per capita steel consumption, and significant investments by leading steel companies. Countries like Germany, France, and Italy are major contributors within this region.
Which segment is expected to grow the fastest?
The construction and automotive segments are projected to experience the highest growth rates, driven by increased demand for infrastructure projects, electric vehicles, and innovative manufacturing techniques that require high-quality steel alloys and specialized products.
Who are the leading companies operating in the Europe Crude Steel Market?
Major players include ArcelorMittal, Thyssenkrupp, SSAB, Tata Steel Europe, and Salzgitter AG, which have significant market shares. These companies focus on sustainable practices, technological advancements, and expanding manufacturing capacities to maintain competitiveness.
Analyst Perspective
The Europe Crude Steel Market is expected to demonstrate steady maturation over the forecast period, driven by mature manufacturing sectors and increasing adoption of advanced steelmaking technologies. Long-term prospects remain favorable, with regional efforts to enhance sustainability and digitalization creating opportunities for innovative steel products and process efficiencies. Key growth regions include Central and Eastern Europe, where industrial upgrades are prominent, and Western Europe, driven by infrastructure renewal projects. Technological evolution is set to focus on energy-efficient methods like electric arc furnaces and hydrogen-based reduction, aligning with decarbonization mandates. Investment priorities should revolve around upgrading existing plants, adopting green technologies, and expanding capacity in high-growth sectors. Competitive intensity is expected to intensify as global players seek market share, emphasizing innovation and eco-friendly solutions. Regional growth potential hinges on supportive policies, infrastructure investments, and decarbonization commitments, positioning Europe as a strategic hub for sustainable steel production in the long term.
