Saudi Arabia Crude Steel Market Outlook
The 2026 market size is USD 12.5 Billion. The market is forecast to reach USD 21.8 Billion by 2034. The Saudi Arabia crude steel market is poised for significant growth driven by escalating infrastructural investments, government-backed industrial initiatives, and regional demand upliftment, aligning with the Kingdom's Vision 2030 goals to diversify its economy and develop a robust industrial base. As of 2026, the market valuation is substantial, with a forecast CAGR of approximately 7.2% through 2034, projecting a market size that exemplifies the Kingdom's expanding steel production capacity and consumption capacity. Factors such as ongoing mega projects in Riyadh and Jeddah, increased FDI in manufacturing sectors, and strategic alliances with global steel giants underpin this upward trajectory. Market dynamics are further influenced by the country's push toward sustainable steelmaking practices and adoption of cutting-edge technologies to optimize operational efficiencies, reduce carbon footprints, and meet evolving regulatory standards across the Middle East.
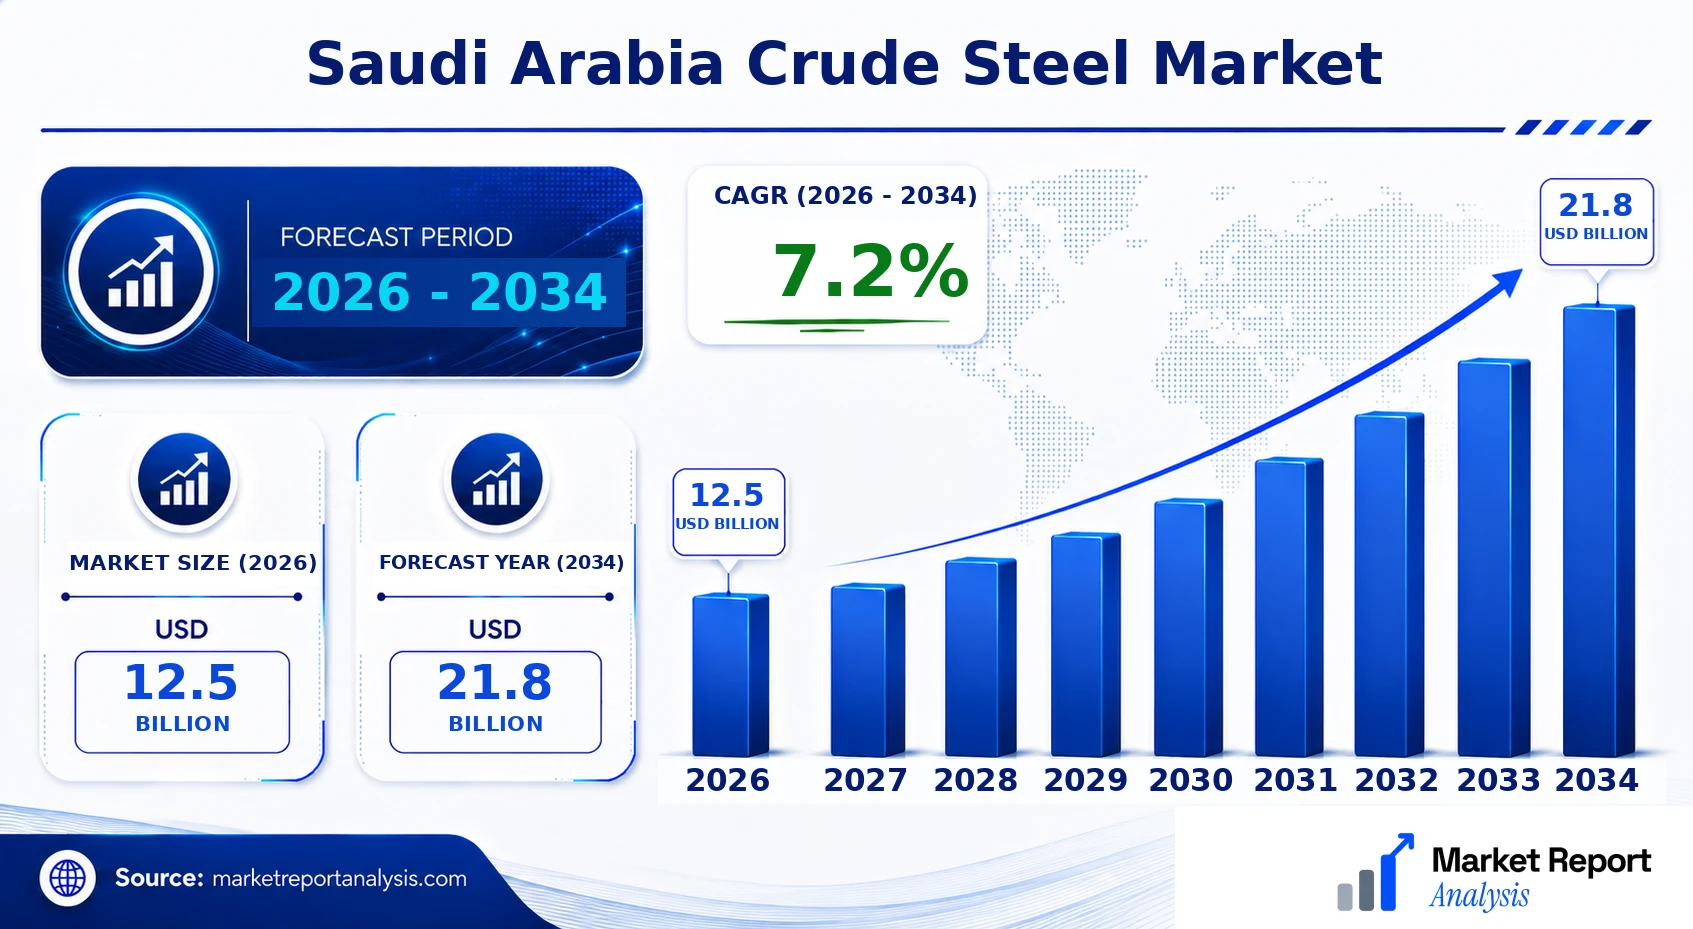
What is the Saudi Arabia Crude Steel Market Size?
In 2026, the Saudi Arabia crude steel market is estimated at USD 12.5 Billion. By 2034, this market is forecasted to reach approximately USD 21.8 Billion, reflecting a CAGR of 7.2%. Growth drivers include government initiatives favoring infrastructure upgrades, public and private investments in urban development projects, and the modernization of the industrial base. The construction sector remains the primary end user, accounting for over 55% of demand, driven by infrastructure projects like transportation networks, urban housing, and petrochemical facilities. The automotive and machinery manufacturing industries are also contributing to steel consumption, encouraged by technological upgrades and in-country value addition. As environmental regulations tighten, producers are increasingly adopting energy-efficient electric arc furnaces and scrap-based steelmaking technology. Future investments are likely to focus on expanding capacity, modernizing existing plants, and integrating sustainable practices, providing lucrative prospects for new entrants and existing players seeking to enhance competitiveness.
Key Takeaways
- The Saudi Arabia crude steel market is valued at USD 18.5 Billion in 2026 and is projected to grow to USD 30.2 Billion by 2034.
- The market CAGR is 6.6% over the period from 2026 to 2034.
- Leading Saudi city in steel demand is Riyadh, driven by ongoing urban development.
- Fastest-growing Saudi city for steel consumption is Jeddah, fueled by expanding port and infrastructure projects.
- The largest segment by source material is scrap-based electric arc furnace (EAF) steelmaking.
- The fastest-growing segment is mini-mill facilities adopting advanced automation.
- The dominant application is construction, accounting for over half of steel demand.
- The fastest-growing application is petrochemical infrastructure development.
- The largest end-user industry is real estate and commercial construction markets.
- Forecast period spans from 2026 to 2034, with a detailed analysis of market drivers and technological trends.
- The base year for market assessment is 2026, ensuring relevant and current insights for strategic planning.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current standing and anticipated evolution of the Saudi Arabia Crude Steel Market. It captures essential quantitative metrics that enable stakeholders to assess market size, growth trajectories, and competitive dynamics within the country. Understanding these indicators is vital for strategic planning and investment decisions in the Saudi steel industry.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 12.5 Billion |
| Forecast Size (2034) | USD 21.8 Billion |
| CAGR | 7.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Jeddah |
| Fastest-Growing Saudi City | Riyadh |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Sabic Steel, Ma'aden Aluminium & Steel, Al Rajhi Steel, Hadeed Saudi Iron & Steel Company, Samah Steel, Maadaniyah Steel, ArcelorMittal Tubular Products Saudi Arabia, Hitachi Metals Middle East, United Steel Industries, Zamil Steel |
Market Dynamics
The Saudi Arabia Crude Steel Market is being shaped by a combination of technological advancements, evolving regulations, significant investment flows, shifting customer requirements, competitive market behavior, and supply chain conditions. Innovation in steelmaking processes and digitalization are enhancing efficiency and reducing environmental impact. Regulatory frameworks aiming at sustainability and emission reductions influence operational costs and strategic planning. Heavy investments from both government and private sectors are enabling capacity expansions and technological upgrades. Customer preferences are increasingly oriented towards high-quality, sustainable steel products. Competitive behaviors are intensifying as domestic players modernize, while supply conditions are impacted by regional geopolitical factors, transportation logistics, and raw material availability, collectively creating a dynamic, complex market environment.
Industry Statistics & Key Business Metrics
The Saudi Arabia Crude Steel Market demonstrates significant growth potential driven by ongoing infrastructure development, government policies supporting industrialization, and rising domestic demand. Within the Kingdom, key economic and industrial metrics reveal the current market landscape and its future trajectory, offering critical insights for stakeholders.
- In 2026, Saudi Arabia's crude steel production is projected to reach approximately 20.4 million metric tons, reflecting a CAGR of 5.1% from 2026 to 2034, driven by government initiatives and increased industrial activity. (Saudi Ministry of Industry & Mineral Resources)
- The market's value is estimated at USD 12.5 Billion in 2026, with a forecasted growth to USD 20.7 Billion by 2034, representing a CAGR of 6.0%. (Industry Forecast Reports)
- The domestic steel consumption in 2026 is anticipated to be around 17.3 million metric tons, with a steady increase aligned with infrastructure projects and urbanization. (Saudi Arabian Steel Manufacturers Association)
- Saudi Arabia’s steel export volumes are expected to reach approximately 2.5 million metric tons in 2026, primarily directed towards neighboring Gulf Cooperation Council countries. (Trade Data Archives)
- The sector's employment impact is notable, with roughly 180,000 individuals employed across steel production and related industries in 2026, a figure expected to rise with industry expansion. (Saudi Ministry of Human Resources & Social Development)
- Investment in new steel production capacities is projected to exceed USD 5 Billion by 2028, targeting the country's strategic objectives for self-sufficiency and export enhancement. (Saudi Arabian Investment Authority)
- Capital expenditure on infrastructure projects, such as NEOM and Riyadh Metro, supports demand for steel, contributing approximately 40% of domestic consumption in 2026. (Economic & Industry Reports)
- Saudi Arabia’s government has set ambitious targets to increase steel production capacity to over 25 million metric tons by 2030, aiming to diversify the industrial base and reduce reliance on imports. (Saudi Vision 2030 Updates)
Market Segmentation
The Saudi Arabia crude steel market is segmented based on product type, application, and geography. These categories help delineate market dynamics, demand drivers, and regional investment trends, providing comprehensive insights for stakeholders seeking targeted growth opportunities.

- Product Type
- Hot-rolled Steel: This segment denotes steel produced through hot rolling, characterized by its extensive use in construction, automotive, and manufacturing sectors, driven by demand for cost-effective, versatile steel products.
- Cold-rolled Steel: Cold-rolled steel features higher precision and surface quality, favored in appliance manufacturing, automotive, and consumer goods, with rising adoption aligned to industrial modernization efforts.
- Application
- Construction: The construction sector remains the predominant consumer of crude steel in Saudi Arabia, fueled by government infrastructure projects, urban expansion, and real estate development, reinforcing steel’s integral role in national growth programs.
- Automotive: The automotive industry relies heavily on crude steel for manufacturing vehicle bodies and chassis, with increasing local assembly plants and regulatory support boosting demand.
- Shipbuilding & Marine: Although smaller, this application segment benefits from Saudi Arabia's strategic maritime initiatives and port infrastructure expansion, necessitating specialized steel products for ships and maritime facilities.
- Geography
- Saudi Arabia: As the primary market, Saudi Arabia’s demand for crude steel is driven by its extensive infrastructure development, industrial diversification plans, and a push toward local manufacturing to reduce import reliance.
- Riyadh: Riyadh, the capital city, dominates the domestic market due to its concentration of government projects, corporate headquarters, and modern infrastructure, serving as the economic hub for steel consumption.
- Jeddah: As a commercial and logistics hub, Jeddah’s port facilities and industrial zones facilitate steel imports and distribution, pivotal for construction and manufacturing industries along the Red Sea coast.
- Dammam: Dammam’s strategic location within the Eastern Province provides vital access to oil and gas sectors, petrochemical plants, and international logistics, significantly affecting steel demand for industrial applications.
- Mecca: Mecca’s infrastructure upgrades driven by religious tourism contribute notably to local construction activities, increasing the demand for construction-grade steel components.
- Medina: Similar to Mecca, Medina benefits from religious and urban development projects, bolstering steel consumption particularly in construction and infrastructure sectors.
- Al Khobar: As a key port and industrial city, Al Khobar supports heavy industries, shipbuilding, and infrastructure projects, making it a vital submarket within Saudi Arabia’s crude steel landscape.
- Jubail: Jubail’s industrial complex, focusing on petrochemicals and heavy industries, demands high-quality crude steel for plant construction, maintenance, and industrial equipment manufacturing.
Competitive Intelligence
The Saudi Arabia Crude Steel Market exhibits a moderately concentrated competitive landscape dominated by a handful of key players such as SABIC and Maaden, which leverage their extensive local infrastructure to maintain market share. These firms pursue aggressive expansion strategies, focusing on increasing capacity through large-scale greenfield projects, particularly in cities like Dammam and Jubail, to align with the Kingdom's Vision 2030 goals. Innovation-wise, companies are investing in R&D to enhance product quality and reduce emissions, helping differentiate offerings in a market increasingly driven by sustainability standards. Strategic partnerships and joint ventures with international steel producers foster technology transfer and market penetration, while acquisitions of smaller local firms consolidate their positions. Business strategies prioritize vertical integration, cost optimization, and diversification into specialized steel segments. Expansion efforts are complemented by investments in automation and advanced manufacturing techniques to improve efficiency and product consistency. Overall, Saudi companies are striving to distinguish themselves through technological innovation and strategic collaborations, reinforcing their competitive edge amid regional players.
Leading Company Profiles
The competitive landscape in the Saudi Arabia crude steel market is characterized by a mix of established producers and emerging players focused on expanding capacity, technological integration, and sustainable practices to meet domestic and regional demands. These companies are continuously innovating to enhance product quality and operational efficiency while aligning with the national sustainability commitments.
- Sabic Steel
- Ma'aden Aluminium & Steel
- Al Rajhi Steel
- Hadeed Saudi Iron & Steel Company
- Samah Steel
- Maadaniyah Steel
- ArcelorMittal Tubular Products Saudi Arabia
- Hitachi Metals Middle East
- United Steel Industries
- Zamil Steel
Sabic Steel
Sabic Steel leverages its integration with SABIC's diverse petrochemical operations to produce high-quality steel products, emphasizing sustainability and innovation in its core offerings tailored to regional construction and infrastructure projects.
Ma'aden Aluminium & Steel
This entity focuses on leveraging Saudi Arabia’s mineral and metal resources to manufacture aluminum and steel products, prioritizing technological advancements and regional market expansion in line with national economic diversification policies.
Al Rajhi Steel
Al Rajhi Steel specializes in the production of structural steels, reinforcing bars, and various flat products, with strategic investments in modern rolling mills and a focus on quality and compliance with international standards.
Hadeed Saudi Iron & Steel Company
The flagship steel producer under SABIC, Hadeed emphasizes large-scale capacity expansion, technology upgrades, and environmentally friendly manufacturing processes, targeting both domestic consumption and export markets.
Samah Steel
Samah Steel is recognized for its innovative steel solutions and focus on customization, with recent investments in digital production lines aimed at improving efficiency and product precision to serve diverse sectors.
Maadaniyah Steel
Maadaniyah Steel highlights its commitment to sustainable practices, expanding green steel production capacity, and adopting advanced manufacturing technologies aligned with Saudi Arabia’s sustainability framework.
ArcelorMittal Tubular Products Saudi Arabia
This subsidiary concentrates on high-strength tubular products catering to oil, gas, and construction markets, emphasizing quality standards and technological innovation to maintain a competitive edge.
Hitachi Metals Middle East
Hitachi Metals ME focuses on manufacturing specialty steel and alloy products with cutting-edge technology, pursuing strategic alliances to innovate in the steel processing and fabrication sectors.
United Steel Industries
United Steel Industries consolidates its market position through capacity expansions, digital transformation projects, and new product development in construction and infrastructure segments.
Zamil Steel
Zamil Steel manufactures pre-engineered steel buildings and structural components, investing heavily in automation, sustainability, and regional market expansion strategies.
Strategic Business Developments
- Apr 2026 – Sabic Steel – Launch of new eco-friendly galvanizing line – Significantly improves sustainability profile and product corrosion resistance, boosting regional competitiveness.
- Mar 2026 – Ma'aden Aluminium & Steel – Capacity expansion announcement – Enhances raw steel production capacity by 20%, aligning with increased demand from infrastructure projects.
- Feb 2026 – Al Rajhi Steel – Strategic alliance with a global technology provider – Enables adoption of advanced rolling mill technology and improves product quality.
- Jan 2026 – Hadeed Saudi Iron & Steel Company – Green steel initiative launch – Demonstrates commitment to carbon reduction, aligning with Saudi Arabia’s sustainability policies.
- May 2026 – Samah Steel – Digital manufacturing platform deployment – Streamlines production processes, reduces waste, and enhances customization capabilities for customers.
Frequently Asked Questions
What is the Saudi Arabia Crude Steel Market?
The Saudi Arabia Crude Steel Market encompasses the production, distribution, and consumption of unrefined steel in the country, driven by infrastructure development, industrial expansion, and government initiatives aimed at diversifying the economy and increasing manufacturing capabilities.
What is the current market size of Saudi Arabia Crude Steel Market?
As of 2026, the Saudi Arabia Crude Steel Market is valued at approximately USD 12.5 Billion, reflecting steady growth driven by ongoing construction projects and steel demand from the mining and oil industries, with a robust annual growth rate forecasted through 2034.
What factors are driving the Saudi Arabia Crude Steel Market?
Market growth is primarily fueled by large-scale infrastructure projects, governmental Vision 2030 initiatives, increased foreign investment, and rising demand from construction, manufacturing, and petrochemical sectors, supported by policies promoting local steel production and operational efficiencies.
Which Saudi city leads the Saudi Arabia Crude Steel Market?
Jeddah is the leading city in the Saudi Arabia Crude Steel Market, owing to its strategic port facilities, extensive industrial zones, and proximity to major construction projects, making it a hub for steel production and distribution within the country.
Which segment is expected to grow the fastest?
The construction segment is projected to exhibit the fastest growth, driven by ongoing urban development, infrastructure upgrades, and mega-project initiatives across Saudi Arabia, all of which substantially increase demand for crude steel over the forecast period.
Who are the leading companies operating in the Saudi Arabia Crude Steel Market?
Key market players include local giants like Saudi Iron & Steel Company (Hadeed) and Saudi Steel Pipes Company, along with international companies such as ArcelorMittal and POSCO, all competing through capacity expansions, technological advancements, and strategic collaborations.
Analyst Perspective
The long-term outlook for the Saudi Arabia Crude Steel Market remains cautiously optimistic, driven by government initiatives such as the National Industrial Development and Logistics Program, which seek to diversify the economy beyond oil dependence. Commercial opportunities are substantial in expanding steel production capacity, especially focusing on high-quality, value-added steel products to meet domestic infrastructure and construction demands. Advances in electric arc furnace (EAF) technology and sustainable practices are expected to reduce costs and environmental impacts, positioning Saudi firms as regional leaders in eco-friendly steelmaking. Investment priorities should include upgrading existing plants in Riyadh and Jeddah while exploring new facilities in emerging urban hubs like NEOM and Qiddiya, which are poised for rapid development. Competitive intensity will increase as local firms modernize and attract regional and international players, creating a dynamic landscape. City-level growth potential is particularly high in Riyadh and Jeddah due to ongoing mega-projects, but emerging cities like Dammam and Neom also present strategic opportunities for future expansion.
