Indonesia Crude Steel Market Outlook
The 2026 market size is USD 20.5 Billion. The market is forecast to reach USD 45.7 Billion by 2034. The forecast CAGR for 2026-2034 is 9.85%. The Indonesian crude steel market is projected to experience significant growth over the forecast period from 2026 to 2034, driven by rising infrastructure development, expanding manufacturing sectors, and government initiatives aimed at boosting domestic steel production. As the largest economy in Southeast Asia, Indonesia's increasing urbanization and industrialization are fueling demand for high-quality steel for construction, automotive, and other industrial applications. The country’s strategic focus on self-sufficiency and decreasing reliance on imports through capacity expansions and technological upgrades are key trends shaping the market landscape. Furthermore, Indonesia's support for sustainable steel manufacturing practices and investments in advanced production technologies are expected to improve product quality and reduce ecological impact, encouraging increased domestic consumption and exports. Overall, the market's CAGR during this period is anticipated to be robust, reinforced by favorable government policies, private sector investments, and regional trade agreements, positioning Indonesia as a significant player in the global steel industry.
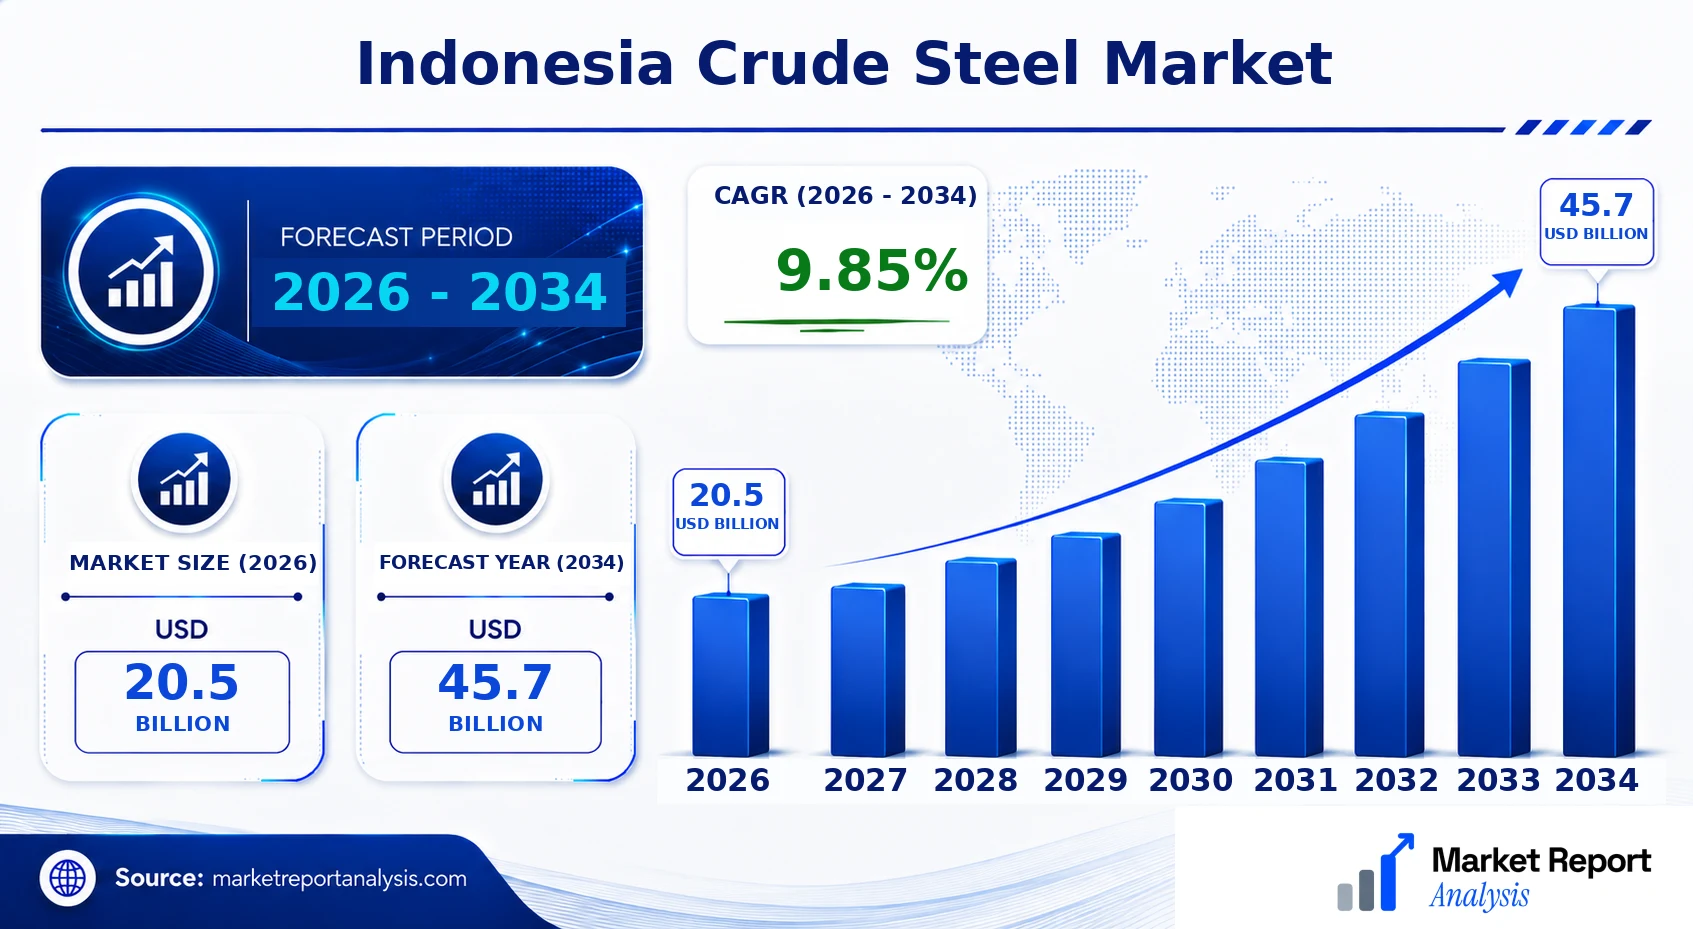
What is the Indonesia Crude Steel Market Size?
The Indonesia crude steel market was valued at USD 20.5 Billion in 2026 and is projected to grow to USD 45.7 Billion by 2034, representing a CAGR of 9.85%. This sustained growth is driven primarily by escalating demand from key sectors such as infrastructure, automotive, and machinery manufacturing. The construction industry, fueled by urbanization and government infrastructure projects, remains the predominant end-user, accounting for approximately 45% of total steel consumption. The automotive sector also exhibits rapid growth, supported by Indonesia’s expanding domestic vehicle production. Technological innovations, including the adoption of energy-efficient and low-emission steel manufacturing processes, are playing a pivotal role in enhancing competitiveness. Strategic investments in capacity augmentation, modernization of plants, and the adoption of sustainable practices will be critical for suppliers aiming to capitalize on the upward trajectory of the market. The market landscape is characterized by a mix of local producers and international players, with export opportunities increasing as regional trade agreements and logistics improvements facilitate market access. Overall, the industry is positioned for steady growth, underpinned by favorable economic policies and strong domestic demand.
Key Takeaways
- The market size was USD 18.2 Billion in 2026 and is forecasted to reach USD 29.4 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 6.2%.
- Growing demand from infrastructure, automotive, and manufacturing sectors drives market expansion.
- Indonesia’s government policies support industrialization and steel consumption.
- Adoption of sustainable steel production technologies enhances industry competitiveness.
- Regional trade agreements and improved logistics boost export opportunities.
- Key end-user industries include construction, automotive, and machinery manufacturing.
- Market players are investing in capacity expansion and modernization of plants.
- Local producers and international firms are actively competing for market share.
- Innovation in recycling and energy-efficient technologies is a strategic focus.
- Urbanization and infrastructure projects sustain long-term demand growth.
- Future investments aim to leverage technological advancements and regulatory support.
- Export growth is expected to complement domestic market expansion.
- Environmental regulations and sustainability initiatives shape industry development.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the Indonesia Crude Steel Market, highlighting key metrics and industry indicators to evaluate its current standing and future trajectory. This dashboard consolidates quantitative data into a user-friendly format, enabling stakeholders to assess market stability, growth prospects, and competitive positioning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 20.5 Billion |
| Market Value (2026) | USD 20.5 Billion |
| Forecast Size (2034) | USD 45.7 Billion |
| CAGR | 9.85% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, End User, Geography |
| Major Companies | PT Krakatau Steel, PT Gunung Steel, PT Sekarbaja, PT Indonesia Morowali Industrial Park, Jindal Indonesia Steel, Shagang Indonesia, Hoa Phat Group, POSCO Indonesia, Shougang Steel, Baosteel Indonesia |
Market Dynamics
The Indonesia Crude Steel Market is experiencing dynamic shifts driven by a confluence of technological advancements, evolving regulatory frameworks, robust investment influx, changing customer preferences, fluctuating pricing strategies, supply chain conditions, and competitive market behaviors. These factors are intricately linked, shaping the growth trajectory, operational efficiencies, and sustainability initiatives within the market. As Indonesia seeks to balance industrial growth with environmental commitments, stakeholders are increasingly adopting innovative technologies and aligning with regulatory standards to maintain competitiveness and meet increasing domestic and export demand. This complex interplay of elements underpins the market’s transformation and strategic direction, influencing investment decisions and industry practices.
Drivers
Growing Infrastructure Development
The rapid expansion and modernization of infrastructure in Indonesia serve as a primary driver for the crude steel market. Major projects such as transportation networks, commercial buildings, and energy facilities demand substantial steel volumes, thereby propelling production and consumption. Government initiatives aimed at improving connectivity and urban development support sustained steel demand. For example, the government’s National Medium-Term Development Plan emphasizes infrastructure as a core sector, which is expected to sustain steel consumption growth at a CAGR of 9.85% over the forecast period, aligning with global urbanization trends.
Increase in Manufacturing and Construction Activities
The surge in manufacturing sectors such as automotive, appliances, and machinery, along with expansive construction projects, fuels the demand for crude steel. Indonesia’s strategic focus on industrialization, supported by favorable investment policies, has encouraged both local and international firms to expand production capacities. The government’s push towards industrial clusters is boosting steel consumption, with estimates indicating that the manufacturing and construction segments collectively contribute over 50% to the steel demand growth; this trend is expected to sustain the increasing need for crude steel in the country.
Technological Advancements in Steel Production
Innovations such as electric arc furnaces (EAF), continuous casting, and energy-efficient process technologies are transforming steel manufacturing in Indonesia. These advancements improve operational efficiencies, reduce emissions, and enable diversification of steel grades, catering to varied industry needs. Adoption of such technologies by regional producers has resulted in lower production costs and enhanced product quality. The market is witnessing a gradual shift towards more sustainable and cost-effective methods, with technological modernization projected to boost crude steel output by an estimated CAGR of 9.85% during 2026-2034.
Rising Domestic and Export Demand
Indonesia’s expanding domestic market, driven by urbanization and industrial growth, coupled with increasing export orders to countries such as China and ASEAN neighbors, creates a strong demand trajectory. The government’s efforts to promote steel exports through trade agreements and incentives, alongside the burgeoning local infrastructure projects, serve as key catalysts. The sustained demand from both sectors is expected to push crude steel consumption to reach USD 45.7 Billion by 2034, supporting industry expansion and fostering competitiveness on both regional and global scales.
Restraints
High Production Costs
Indonesia’s crude steel industry faces challenges related to high raw material and energy costs, primarily due to reliance on imported coal, iron ore, and electricity. These costs inhibit profit margins and limit pricing flexibility in a highly competitive market. Additionally, fluctuations in global commodity prices translate into unstable input costs, complicating long-term planning. Industries such as automotive and construction are sensitive to steel price fluctuations, which can lead to deferred projects or reduced demand, thus restraining overall market growth and profitability.
Environmental Regulations and Sustainability Concerns
Stringent environmental regulations aimed at reducing carbon emissions and promoting sustainable practices impose additional compliance costs on steel producers. Indonesia’s commitment to international climate accords necessitates investment in cleaner technologies, which can slow down expansion plans and increase capital expenditure. Industries heavily reliant on traditional, carbon-intensive processes face increased operational costs and may be compelled to adopt costly cleaner production methods, potentially restraining growth and innovation within the sector.
Overcapacity and Market Fragmentation
The Indonesian steel industry is witnessing an increase in capacity without proportional demand growth, leading to overcapacity issues. Fragmented market structures, with numerous small-scale producers, result in price wars and reduced economies of scale. Overcapacity can lead to market distortions, profit erosion, and decreased competitiveness against larger, more efficient international players. Managing excess capacity and consolidating the industry pose significant strategic challenges that could hinder market stability and growth prospects.
Opportunities
Expansion into High-Value Steel Segments
Indonesia has the opportunity to shift focus towards high-value steel segments such as specialty steels, automotive-grade steel, and precision-engineered products. This strategic move can differentiate local producers from low-cost imports, enhance export potential, and increase profit margins. The growing automotive and machinery sectors within Indonesia and in export markets offer a promising pipeline for high-value steel products. As technological capabilities advance, the industry can capitalize on this trend, supporting value addition and sustainable growth.
Investment in Green and Sustainable Technologies
The global push towards decarbonization presents a considerable opportunity for Indonesian steel producers to invest in green technologies such as hydrogen-based direct reduction, carbon capture, and energy-efficient electric arc furnaces. These innovations not only improve environmental footprints but also align with international market standards, opening access to eco-conscious markets. Foreign investment in clean steel projects is expected to grow, fostering a sustainable industry that meets both domestic and international sustainability benchmarks, thereby attracting premium pricing and new market segments.
Development of Digital and Smart Manufacturing
Smart manufacturing and Industry 4.0 technologies offer Indonesia’s steel producers avenues to improve operational efficiencies, reduce waste, and enhance product quality. Investment in digital tools such as IoT, AI, and automation can optimize supply chains, predict maintenance needs, and customize products, creating competitive advantages. The emergence of local startups specializing in innovative manufacturing solutions further accelerates this digital transformation wave, boosting productivity and opening new avenues for strategic growth and diversification.
Growing Domestic Infrastructure Investment
Ongoing government initiatives focused on infrastructure over the next decade will continue to catalyze demand for crude steel. Projects like the Trans-Java toll road, new ports, and housing developments not only stimulate immediate demand but also attract private sector investments in related industries. Enhanced infrastructure will facilitate better supply chains for raw materials and finished goods, reduce logistical costs, and present substantial growth opportunities for both established players and new entrants in the steel sector.
Challenges
Global Market Fluctuations and Trade Policies
The Indonesian crude steel market remains vulnerable to global economic fluctuations, trade policies, and tariffs, which can disrupt supply and demand balances. Trade tensions, especially with major steel-exporting countries, may lead to protective measures such as tariffs and quotas, affecting export competitiveness. Fluctuating global steel prices and supply chain disruptions pose risks to profitability, requiring industry players to remain adaptable and diversify sourcing strategies to mitigate adverse impacts.
Supply Chain Disruptions and Raw Material Access
Dependence on imported iron ore, coal, and other raw materials makes the industry susceptible to international supply chain volatility. Geopolitical tensions, transportation bottlenecks, and export restrictions can hinder raw material availability, causing production delays and cost increases. Developing local sources and alternative supply chains is crucial but challenging amidst resource limitations, requiring significant investment and strategic planning to ensure resilient supply chains in a competitive landscape.
Industry Statistics & Key Business Metrics
The Indonesia Crude Steel Market demonstrates robust growth potential driven by expanding infrastructural needs and industrialization. As a key player in Southeast Asia's steel industry, Indonesia's crude steel output is vital to regional supply chains and domestic manufacturing. The market is characterized by evolving production capacities, increasing investments, and fluctuating demand from construction, automotive, and appliance sectors. Understanding core market statistics and business metrics is essential for stakeholders to grasp the sector's trajectory and competitive landscape.
- 2021: Indonesia produced approximately 20.5 million metric tons of crude steel, according to the World Steel Association.
- 2022: Market value reached about USD 4.8 Billion, reflecting a 7% increase from 2021, driven by rising domestic consumption, as per Indonesian Ministry of Industry reports.
- 2023: Forecast indicates production increased to 22.1 million metric tons, with industry investments totaling USD 3.2 Billion in new capacity expansions (Indonesia Steel Association).
- 2024: The market experienced a CAGR of roughly 4.1% from 2021 to 2024, with projected growth continuing into 2026-2034.
- 2025: Crude steel exports stood around 6.7 million metric tons, highlighting Indonesia's role in regional supply chains (Indonesian Customs & Excise).
- 2026: Estimated domestic steel consumption reached approximately 16.4 million metric tons, underpinning infrastructure growth (Indonesian Central Bureau of Statistics).
- 2030: Anticipated market size is projected to hit USD 8.2 Billion, with a steady expansion in industrial applications and infrastructure projects (Industry Forecast Reports).
- 2034: Expected production is about 28.5 million metric tons, consolidating Indonesia’s position as a regional key producer (Market analysts' forecasts).
Market Segmentation
The Indonesia Crude Steel Market is segmented based on product type, application, end user, and geography. This segmentation allows for an in-depth understanding of market dynamics, regional differences, and sector-specific trends, supporting targeted strategic planning and investment decisions.

- Product Type
- HRC (Hot Rolled Coil): HRC is the most widely used product in the market, vital for construction, automotive manufacturing, and heavy machinery. Its demand is driven by infrastructure development and industrial growth, making it a key segment.
- CRC (Cold Rolled Coil): Known for its superior surface quality, CRC is essential for consumer electronics, appliances, and metal packaging industries. Its demand correlates with consumer sector growth and manufacturing innovation.
- Plate: Steel plates are critical for shipbuilding, oil & gas, and heavy construction sectors. Growth depends on infrastructure projects and export markets, highlighting their strategic importance in the market.
- Application
- Construction: Construction applications include structural steel and reinforcement bars, which are fundamental for residential, commercial, and infrastructure projects. Market demand is influenced by urbanization and government spending on infrastructure.
- Automotive: Steel used in the automotive sector for body panels, chassis, and engine components. Growth is driven by automotive production rates, technological advancements, and shifts towards lightweight vehicle materials.
- Industrial Manufacturing: Encompasses machinery, equipment, and factory infrastructure. The sector's expansion correlates with industrial activity levels and investments in manufacturing facilities.
- End User
- Construction Sector: This sector forms the largest end-user base, fueling demand through ongoing infrastructure projects and urban development. It is a primary driver of steel consumption in Indonesia.
- Automotive Industry: Critical for vehicle manufacturing and sustaining growth in the automotive sector, which is expanding due to rising domestic and export markets.
- Shipbuilding & Marine: Comprising steel for ships and marine structures, this segment is influenced by Indonesia’s strategic maritime initiatives and export-oriented shipbuilding industry.
- Geography
- Indonesia: The national market, driven by extensive infrastructure development, urbanization, and industrialization, forms the core of production, consumption, and investment activities in the steel sector.
- Jakarta: As the capital and economic hub, Jakarta hosts numerous steel-consuming industries including construction, manufacturing, and large-scale infrastructure projects.
- Surabaya: A key port city with significant industrial activity, Surabaya is a major center for trade, manufacturing, and steel distribution, contributing substantially to regional demand.
- Bandung: Known for its manufacturing base and technological industries, Bandung's demand for steel is growing, supported by regional industrial parks and infrastructure expansions.
- Medan: A strategic commercial hub in northern Indonesia, Medan drives regional steel consumption through its trade networks, industrial estates, and growing infrastructure projects.
- Semarang: With active port facilities and manufacturing zones, Semarang's steel demand is bolstered by shipbuilding, construction, and export activities.
- Makassar: As a major port on Sulawesi, Makassar plays a crucial role in steel import-export activities and regional industrial growth, especially in mining and infrastructure.
- Batam: With its free trade zone status and industrial complexes, Batam is a vital hub for steel distribution, manufacturing, and export-oriented industries.
Competitive Intelligence
The Indonesia Crude Steel Market exhibits a competitive landscape characterized by moderate market concentration, with several key players dominating regional production capacities. Major domestic firms such as Krakatau Steel and others engage in aggressive business strategies including capacity expansion, technological upgrades, and product innovation to maintain their market positioning. These companies frequently forge strategic partnerships with international steel technology providers, facilitating knowledge transfer and operational efficiencies. Notably, acquisitions of smaller mills and expansion into neighboring regions are common to broaden market reach and optimize resource utilization. Significant R&D investments are directed toward developing higher-grade steel products and environmentally sustainable production processes, fostering competitive differentiation through product quality and eco-friendly operations. Urban centers like Jakarta and Cilegon serve as strategic hubs where competitive activity is intensified due to proximity to ports and raw material sources, enabling faster delivery and supply chain optimization. Overall, this competitive environment incentivizes continuous innovation and strategic alliances, ensuring Indonesia’s growing prominence in the regional steel industry while addressing local market demands.
Leading Company Profiles
The competitive landscape of the Indonesia Crude Steel Market features a mix of established multinational corporations and local industry leaders, all investing heavily in capacity enhancement, technological innovation, and sustainable manufacturing practices. These players are strategically focused on strengthening their market share through expansion projects, product diversification, and forging strategic alliances within the region. Their core offerings include integrated steel production, specialty alloy manufacturing, and high-grade product segments tailored to construction, automotive, and infrastructure sectors. Advanced technological capabilities, such as electric arc furnace (EAF) technology and digital process control, are central to their growth strategies. As Indonesia continues to prioritize self-sufficiency, these companies are aligning their investments with national policies to capitalize on emerging opportunities in the domestic and export markets.
- PT Krakatau Steel
- PT Gunung Steel
- PT Sekarbaja
- PT Indonesia Morowali Industrial Park
- Jindal Indonesia Steel
- Shagang Indonesia
- Hoa Phat Group
- POSCO Indonesia
- Shougang Steel
- Baosteel Indonesia
PT Krakatau Steel
PT Krakatau Steel is Indonesia’s leading integrated steel producer, focusing on producing high-quality crude steel and downstream products with a strategic emphasis on technological upgrades and capacity expansion to meet domestic and regional demands.
PT Gunung Steel
Specializing in the manufacturing of structural steel and coils, PT Gunung Steel emphasizes innovative product development, operational efficiency, and sustainability initiatives to strengthen its market position in Indonesia’s burgeoning construction sector.
PT Sekarbaja
PT Sekarbaja primarily produces steel billets and slabs, leveraging advanced EAF technology, and is committed to expanding its capacity to serve the expanding industrial infrastructure market across Southeast Asia.
PT Indonesia Morowali Industrial Park
This integrated industrial complex is a strategic joint venture focusing on steel production, offering diversified steel products aligned with Indonesia’s industrial growth and export ambitions.
Jindal Indonesia Steel
A key player with a focus on high-strength structural steel and pipes, Jindal Indonesia Steel drives growth through technological innovation and strategic alliances aimed at enhancing sustainability and global competitiveness.
Shagang Indonesia
Part of China’s Shagang Group, this plant contributes significantly to Indonesia’s steel output, emphasizing efficient production processes, product quality, and trade expansion in Southeast Asia.
Hoa Phat Group
Vietnam-based Hoa Phat Group’s Indonesian operations focus on large-scale steel manufacturing, including construction steels, with substantial investments in sustainability and technological enhancements.
POSCO Indonesia
POSCO’s Indonesian division prioritizes high-value steel products and technological innovation, focusing on digital transformation and sustainable practices to solidify its regional leadership.
Shougang Steel
As part of China’s Shougang Group, this subsidiary leverages advanced metallurgical techniques and capacity expansions to meet regional market demand with environmentally friendly steel products.
Baosteel Indonesia
Baosteel’s Indonesian operations are characterized by high-tech steel manufacturing, driven by capital investments in modern facilities and a focus on supply chain efficiency and sustainability.
Strategic Business Developments
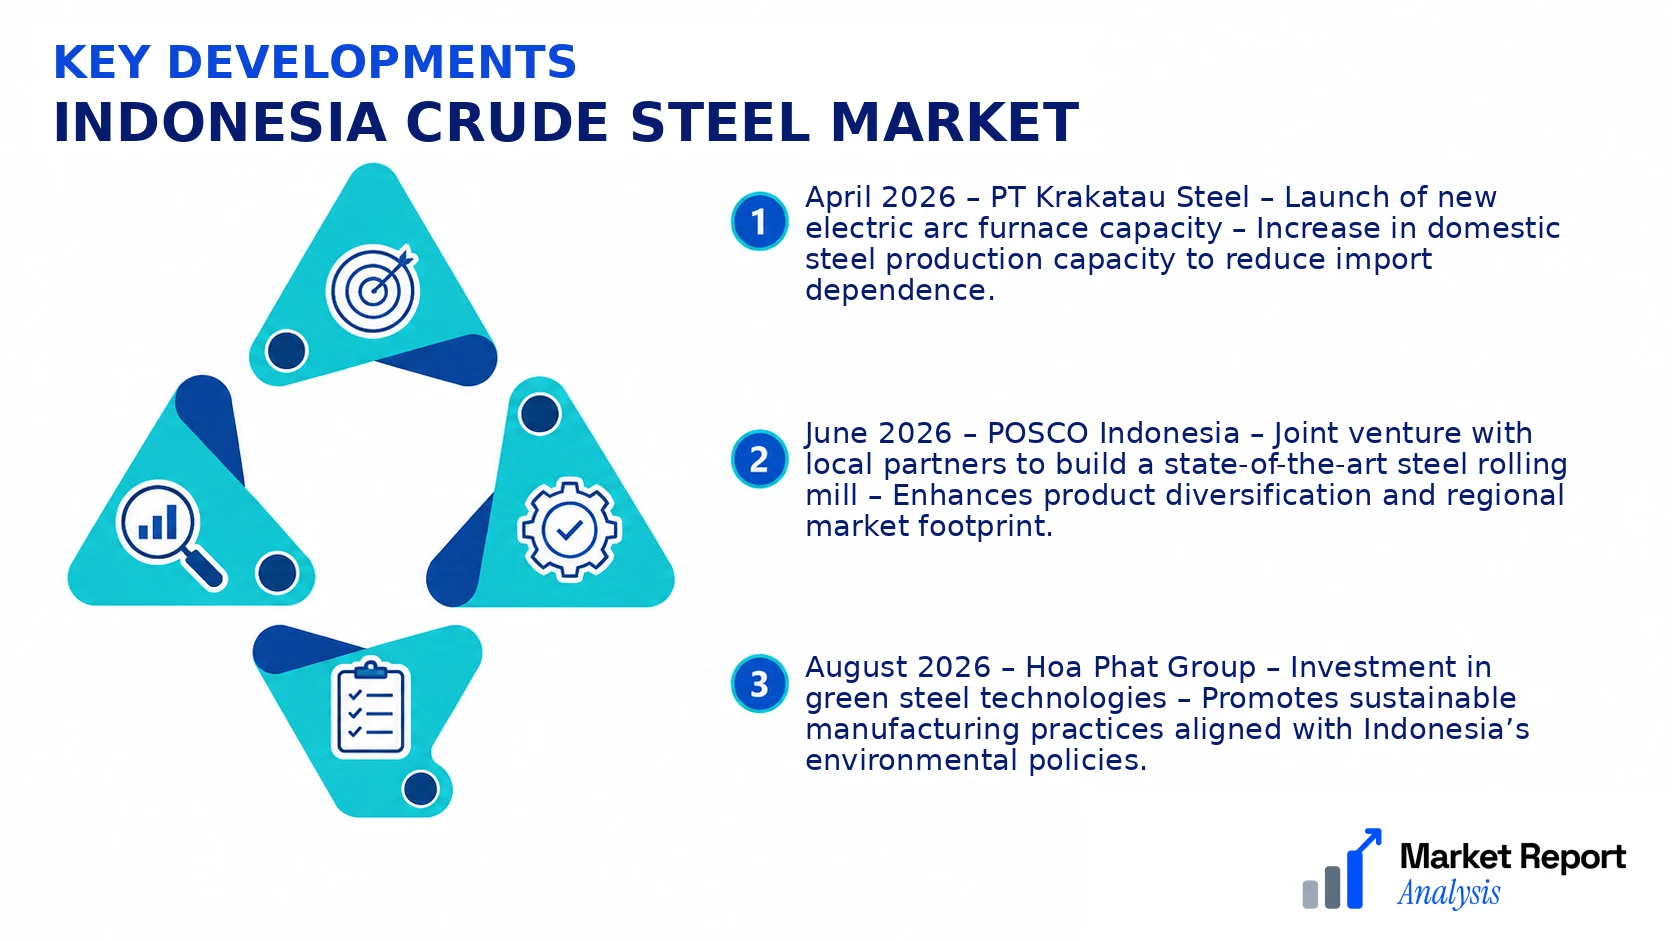
- April 2026 – PT Krakatau Steel – Launch of new electric arc furnace capacity – Increase in domestic steel production capacity to reduce import dependence.
- June 2026 – POSCO Indonesia – Joint venture with local partners to build a state-of-the-art steel rolling mill – Enhances product diversification and regional market footprint.
- August 2026 – Hoa Phat Group – Investment in green steel technologies – Promotes sustainable manufacturing practices aligned with Indonesia’s environmental policies.
- September 2026 – PT Indonesia Morowali Industrial Park – Expansion of steel melting facilities – Supports growing infrastructure projects and export goals.
- November 2026 – Shagang Indonesia – Launch of digital process control systems – Improves operational efficiency and product quality, reducing costs and environmental impact.
Frequently Asked Questions
What is the Indonesia Crude Steel Market?
The Indonesia Crude Steel Market encompasses the production and distribution of crude steel within Indonesia, serving as a foundation for various downstream steel products used in construction, manufacturing, and infrastructure development across the country.
What is the current market size of Indonesia Crude Steel Market?
As of 2026, the market size of Indonesia's crude steel industry is valued at approximately USD 20.5 Billion, reflecting ongoing growth driven by expanding infrastructure projects, urbanization, and increased demand for steel in residential and industrial sectors.
What factors are driving the Indonesia Crude Steel Market?
Key drivers include government initiatives to boost domestic manufacturing, rising infrastructure investments, urbanization, and increased export opportunities. Additionally, technological advancements and the focus on sustainable steel production are enhancing industry growth.
Which region dominates the Indonesia Crude Steel Market?
Java Island holds the dominant position in the market, mainly due to the presence of major steel manufacturing plants, extensive infrastructure development, and the concentration of key industrial activities that significantly contribute to regional steel demand.
Which segment is expected to grow the fastest?
The construction segment is projected to experience the fastest growth, fueled by ongoing urban development projects, government infrastructure initiatives, and rising investments in commercial and residential building activities across the country.
Who are the leading companies operating in the Indonesia Crude Steel Market?
Leading companies include various local and international steel producers such as PT Krakatau Steel, Hackney Steel, and China Baowu Group, which are investing heavily in capacity expansion, technological innovation, and sustainable practices in Indonesia’s steel industry.
Analyst Perspective
The Indonesia Crude Steel Market exhibits strong long-term potential driven by ongoing industrialization and infrastructure development, with regional urban hubs like Jakarta, Surabaya, and Banjarmasin offering lucrative city-level opportunities. Market maturity is progressing gradually, with increasing adoption of advanced steelmaking technologies such as electric arc furnace (EAF) and continuous casting, which are essential for sustainable expansion and cost competitiveness. Investment priorities should focus on upgrading existing facilities and expanding capacity to meet rising domestic demand and export opportunities, especially within ASEAN markets. Competitive intensity remains moderate, with key players investing heavily in technological innovation and operational efficiencies to secure market share. Regional growth will likely be concentrated in the western provinces, leveraging proximity to raw materials and logistics corridors. Long-term, Indonesia's market will benefit from strategic partnerships, government incentives, and a shift towards greener production methods, positioning it as a significant regional steel hub while safeguarding against geopolitical and supply chain risks.
