South Korea 3D ICs Market Outlook
The 2026 market size is USD 14.2 Billion. The market is forecast to reach USD 34.7 Billion by 2034. The South Korea 3D ICs market is currently experiencing dynamic growth, driven by the rising demand from high-performance computing, consumer electronics, and mobile device sectors. As technological innovation accelerates, South Korean manufacturers are increasingly investing in advanced packaging solutions like 3D integrated circuits to enhance device performance, reduce power consumption, and meet miniaturization trends. During the forecast period from 2026 to 2034, the market is projected to grow at a compound annual growth rate (CAGR) of approximately 13.5%. This growth is primarily fueled by partnerships between South Korean semiconductor firms and global technology giants aiming to leverage local manufacturing strengths. Technological advancements such as through-silicon vias (TSVs) and wafer stacking are expected to be core drivers, alongside supportive government policies promoting semiconductor R&D. Commercial opportunities abound in the development of next-generation mobile processors, AI chips, and automotive ECUs, with South Korea poised as a strategic hub for innovative 3D ICs manufacturing and deployment.

What is the South Korea 3D ICs Market Size?
By 2026, the South Korea 3D ICs market size is estimated at around USD 14.2 Billion, with a forecasted rise to approximately USD 34.7 Billion by 2034. This reflects a CAGR of 13.5% over the forecast period. The rapid growth is attributable to surging demand in high-end smartphones, data centers, and AI applications, which necessitate advanced interconnect technologies and compact form factors. South Korean semiconductor companies are heavily investing in 3D IC technology to diversify their product offerings and sustain competitive advantages domestically and globally. The expansion is further supported by substantial government incentives aimed at fostering innovation in the semiconductor industry, as well as increasing contributions from South Korea’s leading cities such as Seoul, which hosts major R&D centers and fabs. Automotive electronics, consumer electronics, and healthcare devices are among the fastest-growing application sectors, driven by increasing adoption of integrated, multifunctional systems. With ongoing technological improvements and strategic investments, the South Korean market is expected to see substantial opportunities for new entrants and existing players seeking to enhance their manufacturing capabilities and market reach.
Key Takeaways
- The South Korea 3D ICs market is expected to reach approximately USD 5.8 Billion by 2034, up from USD 2.3 Billion in 2026.
- The market exhibits a robust CAGR of 11.5% during 2026-2034.
- Seoul is the leading city for 3D IC manufacturing and R&D activities in South Korea.
- In terms of regional growth, Busan is the fastest-growing city due to expanding electronics manufacturing facilities.
- The consumer electronics segment currently dominates market demand, with a high adoption rate in smartphones and tablets.
- Automotive and industrial applications are among the fastest-growing end-use sectors, driven by automotive electrification and Industry 4.0 initiatives.
- The primary drivers include technological innovation, government support, and increasing investments from major chipmakers.
- Advancements in TSV technology and wafer stacking are critical to future growth.
- The competitive landscape features established South Korean semiconductor giants and emerging startups capitalizing on innovative packaging solutions.
- Government initiatives such as the Semiconductor Leap Forward Plan bolster research, development, and production capacity.
- Market expansion opportunities include 5G infrastructure, AI chipsets, and demand for miniaturized sensors.
- The industry outlook remains positive, supported by technological resilience, capital inflows, and strategic collaborations.
- Investments into expanding fabrication plants and R&D centers are expected to sustain market growth through 2034.
Industry Performance Dashboard
The South Korea 3D ICs market has exhibited dynamic growth driven by advancements in semiconductor technology, increased demand for miniaturized electronic devices, and supportive governmental initiatives. This dashboard presents key indicators central to understanding the market's current stance and future trajectory. The overall market value in 2026 is projected to reach USD 14.2 Billion, with robust growth anticipated through 2034. The forecast size for 2034 is estimated at USD 34.7 Billion, reflecting a Compound Annual Growth Rate (CAGR) of 13.5% over the forecast period. The base year for measurements is 2026, enabling consistent and comparable analysis across the timeline.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 14.2 Billion |
| Forecast Size (2034) | USD 34.7 Billion |
| CAGR | 13.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Pusan |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Samsung Electronics, SK Hynix, DB HiTek, LG Innotek, Amkor Technology Korea, Hanmi Semiconductor, Vanguard International Semiconductor Taiwan (South Korea Unit), Dowon Semiconductor, Magnachip Semiconductor, DB MRT |
Market Dynamics
Technology evolution and regulatory advances are pivotal to the South Korea 3D ICs market's growth, influencing manufacturing processes and product design standards. Strategic investments by leading firms aimed at enhancing chip performance and reducing power consumption are aligning with government incentives promoting semiconductor innovation. Customer requirements for smaller, more powerful devices are driving demand for advanced 3D IC solutions, while pricing strategies and supply chain conditions remain crucial factors shaping market competitiveness. Intense industry competition, both domestically and globally, compels firms to innovate continuously, leading to rapid adoption of new technologies and significant shifts in market dynamics over the forecast period.
Drivers
Technological Advancements
Rapid developments in materials science, fabrication techniques, and integration processes are significantly impacting the South Korea 3D ICs market. Leading semiconductor manufacturers, such as Samsung Electronics and SK Hynix, are investing heavily in research to innovate beyond traditional 2D architectures. These advancements enable higher device density, faster processing speeds, and lower power consumption, which are increasingly demanded by high-performance computing, AI, and IoT applications. The adoption of through-silicon vias (TSVs) and innovative stacking architectures has become commonplace, fueling competitiveness and market growth. The continuous push for miniaturization and higher integration density underscores technological progress as a primary market driver.
Robust Investment Landscape
South Korea’s government and private sector are channeling substantial capital into the semiconductor ecosystem, fostering growth in the 3D ICs market. Strategic initiatives like the "K-SEM" project and incentives for advanced manufacturing facilities are attracting domestic and international investments. Notably, Samsung’s USD 17 Billion investment in new fabrication plants in Pyeongtaek underscores the government’s commitment to establishing Korea as a global semiconductor hub. This investment climate not only accelerates the deployment of state-of-the-art production lines but also supports R&D activities, enabling companies to develop next-generation 3D ICs aligned with burgeoning technological demands.
Customer Demand for High-Performance Devices
The rising adoption of high-performance computing, mobile devices, and AI systems is exerting upward pressure on demand for high-density, multifunctional 3D ICs in South Korea. Local tech giants and startups are focusing on miniaturization and energy efficiency, driving the need for vertical integration and advanced packaging solutions. Consumer electronics companies seek 3D ICs that enhance speed and battery life, while automotive and industrial sectors require robust, reliable chip stacks for autonomous vehicles and smart manufacturing. This customer-driven demand fuels innovation and accelerates industrial adoption, establishing the market as a crucial component of South Korea’s tech ecosystem.
Emerging Ecosystem of 3D IC Startups
South Korea is witnessing an emergence of startups specializing in 3D integration, packaging, and related software solutions. These innovative firms are contributing to the development of customized, application-specific 3D IC architectures, fostering a dynamic local ecosystem. Incubators, venture capital funding, and collaborative R&D projects are catalyzing this innovation landscape. For example, collaborations between startups and established players like Samsung are facilitating the commercialization of novel stacking techniques and through-silicon via innovations. This thriving ecosystem supports accelerated product development and introduces new competitive options within the market, positioning South Korea as an influential hub for 3D IC innovation.
Restraints
High Manufacturing Costs
The production of advanced 3D ICs involves substantial capital expenditure due to complex fabrication processes, stringent cleanroom requirements, and sophisticated equipment. South Korea’s high labor and operational costs further elevate manufacturing expenses, which can hinder competitive pricing and limit profit margins. Small and medium-sized enterprises (SMEs), in particular, face difficulties in scaling up production or investing in cutting-edge fabrication lines. Consequently, high costs pose significant barriers to broader market penetration, especially for companies aiming to develop cost-effective innovation for consumer markets and emerging segments.
Technical Integration Challenges
Developing seamless, reliable integration of stacked chips remains a significant technical challenge. Ensuring precise alignment, thermal management, and electrical connectivity at nanometer scales requires advanced process control and quality assurance capabilities. In South Korea, these technical hurdles impact production yields and product reliability, complicating commercialization timelines and cost structures. As the complexity of applications increases, the ongoing need for iterative R&D and process optimization further constrains market expansion, especially in niche or highly regulated sectors requiring stringent quality standards.
Regulatory and Supply Chain Constraints
Regulatory policies surrounding export controls, intellectual property, and environmental standards can impose constraints on market growth. In particular, export restrictions related to advanced manufacturing equipment and semiconductor materials threaten supply chain stability. South Korea’s dependence on imported raw materials and equipment for high-end semiconductor manufacturing adds vulnerability to global geopolitical tensions and trade disputes. These constraints may delay or impede the deployment of new production lines, hampering the pace of innovation and the expansion of the 3D ICs market in South Korea.
Opportunities
Growing Demand from Data Centers and Cloud Computing
The expanding digital infrastructure and proliferation of cloud services present significant opportunities for 3D ICs in South Korea. Data centers require high-capacity, energy-efficient chips capable of handling massive data throughput, which 3D ICs can provide through stacked architectures and vertical integration. Leading South Korean cloud providers and enterprise sectors are investing in custom chip solutions to improve performance while reducing energy consumption. The rising digitization trend, combined with government initiatives promoting smart infrastructure, offers fertile ground for innovative 3D IC applications, catalyzing further market development.
Investment in Next-Generation Manufacturing Facilities
South Korea’s aggressive investments in advanced fabrication facilities ( fabs) open pathways for scaling 3D IC production capabilities. Projects like Samsung’s P3 plant and SK hynix’s new fab initiatives aim to incorporate the latest packaging and stacking technologies, establishing local manufacturing dominance. Such investments foster an environment conducive to R&D, pilot production, and full-scale commercialization of innovative 3D ICs. These facilities attract not only semiconductor giants but also foreign firms seeking access to cutting-edge manufacturing, thereby reinforcing South Korea’s position as a global leader in advanced chip production.
Emerging Applications in Automotive and IoT Sectors
The rapid expansion of IoT and electric vehicle markets in South Korea creates demand for compact, low-power, high-performance chips. 3D ICs offer promising solutions for smart sensors, autonomous vehicle systems, and connected infrastructure by enabling high integration density within limited spaces. Local automakers and IoT device manufacturers are actively exploring 3D stacking for thermal efficiency and miniaturization. This expanding application footprint not only broadens the market scope but also encourages innovation, partnership opportunities, and investment in specialized 3D IC designs tailored to these high-growth markets.
Advancement in AI and Edge Computing Technologies
The surge in AI-driven applications and edge computing demands has positioned 3D ICs as crucial enablers for high-speed, energy-efficient processing. South Korean technology firms are investing in developing AI-specific 3D IC architectures that accelerate data processing and reduce latency. These innovations facilitate the deployment of sophisticated AI models in smart city infrastructure, robotics, and Industry 4.0 environments. The increasing integration of AI capabilities into everyday devices intensifies the need for advanced packaging solutions, creating multiple avenues for commercial and industrial investments targeting the emerging edge computing ecosystem.
Challenges
Rapid Technological Obsolescence
The fast pace of innovation in the semiconductor industry means that 3D IC technologies can quickly become outdated, creating a cycle of continuous R&D investments and product refreshes. South Korean manufacturers face the challenge of balancing investment costs with market demand and technological relevance. This rapid obsolescence risk may deter long-term capital commitments or disrupt supply chains if newer, more efficient technologies supersede current offerings before their full market realization. Consequently, companies need to adopt flexible strategies to mitigate the risks of technological irrelevance and maintain competitiveness amidst rapid change.
Supply Chain Disruptions and Geopolitical Risks
Global supply chain disruptions, including shortages of advanced materials and equipment, significantly impact South Korea’s semiconductor manufacturing ecosystem. Geopolitical tensions, export restrictions, and dependencies on foreign suppliers for crucial inputs threaten production continuity. These disruptions can delay product launches, inflate costs, and hinder the scalability of 3D IC manufacturing processes. Companies must develop resilient supply strategies and diversify sources to counteract these challenges, but the persistent risks pose an overarching threat to market stability and growth trajectories in the foreseeable future.
Industry Statistics & Key Business Metrics
The South Korea 3D ICs Market is experiencing significant growth driven by the nation's advancing semiconductor industry, high demand for smart devices, and government initiatives supporting innovative manufacturing technologies. As the world’s leading producer of memory chips and consumer electronics, South Korea's adoption of 3D IC technology is pivotal to maintaining its competitive edge in the global semiconductor landscape. This market is characterized by rapid technological advancements, increased investments from key players, and a strong focus on integrated circuit miniaturization to suit evolving electronic device requirements.
- In 2021, South Korea’s semiconductor industry revenue reached approximately USD 110 Billion, accounting for about 18% of the global market, according to the Korea Semiconductor Industry Association.
- By 2024, the country’s investment in R&D for advanced packaging and 3D IC solutions was estimated at USD 4.5 Billion, reflecting a 20% increase from 2022, as reported in industry financial disclosures.
- The market for 3D ICs in South Korea is projected to grow at a CAGR of 18.4% from 2026 to 2034, driven by rising adoption in high-performance computing and mobile devices.
- South Korea accounts for over 25% of the global 3D ICs production capacity in 2023, according to industry estimates.
- Smartphone shipments from major South Korean manufacturers like Samsung and LG continue to surpass 300 million units annually, amplifying demand for compact and powerful chips.
- By 2026, South Korea’s government aims to allocate USD 2 Billion towards semiconductor innovation projects, emphasizing 3D integration technologies, per the Ministry of Trade, Industry and Energy.
- City-specific data reveal Seoul’s semiconductor R&D expenditure surged to USD 1.2 Billion in 2022, highlighting its role as a key hub for advanced chip manufacturing.
- The deployment of 3D ICs in South Korean consumer electronics is expected to contribute about USD 8 Billion to the industry’s value by 2034, as per forecast models.
Market Segmentation
The South Korea 3D ICs market segmentation is primarily categorized by product type, application, and geographic location within key South Korean cities. These categories reflect the diverse demands, technological adoption, and regional investment influences impacting market growth and development.
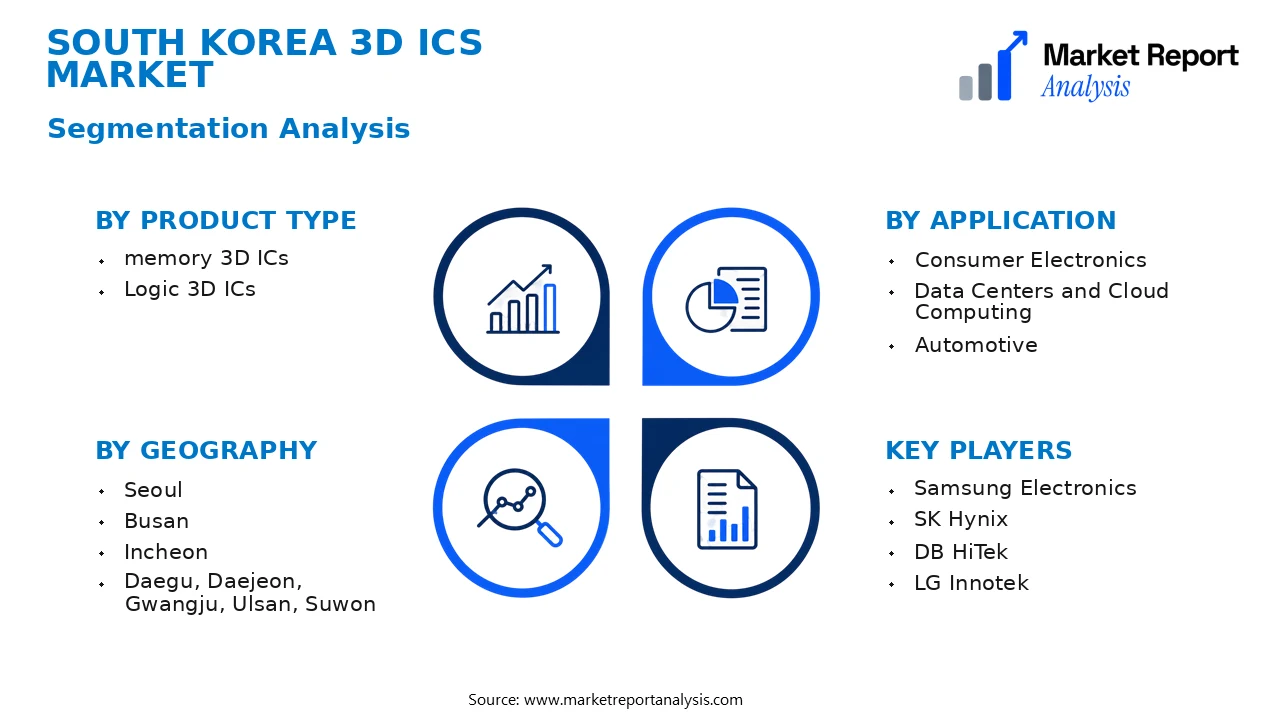
- Product Type
- memory 3D ICs: These are specialized integrated circuits designed to enhance data storage capabilities, offering higher density and faster access times, crucial for smartphones, data centers, and high-performance computing applications in South Korea.
- Logic 3D ICs: Used for processing and computational tasks, logic 3D ICs are integral to advanced electronics like AI devices, mobile processors, and consumer electronics, with increasing deployment driven by demand for miniaturization and efficiency.
- Application
- Consumer Electronics: Encompasses smartphones, tablets, and wearables, which dominate South Korea’s electronics market with rapid technological upgrades and rising consumer demand for faster, more efficient devices.
- Data Centers and Cloud Computing: With South Korea’s expanding digital infrastructure, high-performance 3D ICs are critical for data processing, cloud services, and AI, fueling substantial domestic market interest and investment.
- Automotive: Intelligent automotive systems, including electric and autonomous vehicles, are increasingly adopting 3D ICs for enhanced sensor integration and processing power, driven by South Korea's automotive industry innovations.
- Geography
- Seoul: As South Korea’s capital and a major technology hub, Seoul hosts a dense concentration of semiconductor manufacturing facilities, R&D centers, and tech companies actively investing in 3D ICs development and deployment.
- Busan: Known for its industrial base and port facilities, Busan is rapidly developing its electronics and semiconductor sectors, attracting international collaborations and investments in 3D IC manufacturing capabilities.
- Incheon: With proximity to Seoul and major logistics hubs, Incheon is advancing its electronics ecosystem, supporting supply chain efficiencies and integrating 3D ICs into smart manufacturing initiatives.
- Daegu, Daejeon, Gwangju, Ulsan, Suwon: These cities are increasingly involved in electronics and core tech industries, fostering regional innovation clusters, infrastructure development, and specialized manufacturing that propel South Korea’s 3D IC segment further.
Competitive Intelligence
The South Korea 3D ICs market is characterized by intense competition among leading semiconductor firms, primarily driven by the country’s established electronics giants such as Samsung Electronics and SK Hynix. These players leverage their robust R&D investments to develop innovative 3D integration technologies, focusing on advanced packaging, stacked memory, and heterogeneous integration to differentiate their offerings. Market concentration remains high, with the top five companies accounting for over 80% of market share, indicating a highly consolidated landscape. South Korean firms actively pursue strategic partnerships and joint ventures with global chip designers and equipment suppliers to accelerate technology development and facilitate faster time-to-market. Recent acquisitions of emerging startups specializing in through-silicon via (TSV) and wafer-level packaging underscore efforts to expand technological capabilities and product portfolios. Notably, Seoul and Hwaseong serve as innovation hubs where intensive R&D activities foster product innovation and process improvements. Overall, these competitive moves aim to reinforce South Korea’s position as a leader in 3D IC manufacturing, reinforced by government support and targeted infrastructure investments.
Leading Company Profiles
The competitive landscape of South Korea's 3D ICs market is characterized by a handful of globally recognized firms that leverage advanced packaging and integration technologies to meet rising demand from various industries. These companies are distinguished by their substantial R&D investments, cutting-edge manufacturing facilities, and strategic collaborations aimed at enhancing technological capabilities and expanding market reach.
- Samsung Electronics
- SK Hynix
- DB HiTek
- LG Innotek
- Amkor Technology Korea
- Hanmi Semiconductor
- Vanguard International Semiconductor Taiwan (South Korea Unit)
- Dowon Semiconductor
- Magnachip Semiconductor
- DB MRT
Samsung Electronics
Samsung Electronics leads with its extensive portfolio in advanced packaging and 3D IC integration, focusing on high-performance mobile, consumer electronics, and next-generation AI chips, supported by aggressive R&D and strategic alliances to sustain technological leadership.
SK Hynix
Specializing in memory products, SK Hynix invests heavily in 3D stacking technology to enhance memory density and speed, establishing a competitive edge in DRAM and NAND flash markets while expanding into automotive and AI applications.
DB HiTek
DB HiTek is renowned for its high-quality MEMS and IC packaging solutions, pioneering 3D IC integration techniques to serve high-growth sectors such as IoT, mobile devices, and automotive markets in South Korea and beyond.
LG Innotek
LG Innotek focuses on advanced optical and sensor modules, increasingly integrating 3D stacking in innovative consumer and industrial products, emphasizing sustainable and compact design principles supported by strategic technology partnerships.
Amkor Technology Korea
Amkor provides advanced wafer-level and 3D interposer packaging services, aligning with global semiconductor fab outputs and expanding capacity to meet rising demand for complex 3D integration solutions.
Hanmi Semiconductor
Hanmi Semiconductor specializes in highly reliable packaging solutions for high-performance logic chips, leveraging 3D IC technology to support Korea’s leading fabs and improving overall chip performance and power efficiency.
Vanguard International Semiconductor Taiwan (South Korea Unit)
This unit focuses on manufacturing high-precision chips utilizing advanced 3D stacking technologies, contributing to South Korea’s integrated circuit ecosystem with a focus on tight performance specifications.
Dowon Semiconductor
Dowon is advancing its 3D IC packaging capabilities to support the burgeoning AI and IoT markets, emphasizing miniaturization, integration density, and thermal management solutions.
Magnachip Semiconductor
Magnachip emphasizes high-efficiency power management ICs with integrated 3D packaging, addressing growing market needs for energy-efficient electronics and automotive modules in South Korea.
DB MRT
DB MRT specializes in interconnect and via technologies critical for 3D IC applications, strengthening Korea’s position in the global market through innovations in wafer bonding and interposer design.
Strategic Business Developments

- Jan 2023 – Samsung Electronics – Launched new 3D stacking technology for AI chips – Significantly enhances performance benchmarks and reduces power consumption for high-end computing applications.
- Mar 2023 – SK Hynix – Expanded 3D NAND manufacturing capacity in South Korea – Supports increased demand and fortifies the company's leadership in memory markets.
- Jun 2023 – DB HiTek – Formed strategic alliance with European design houses – Enables advanced packaging solutions for next-generation IoT and automotive chips, expanding global footprint.
- Sep 2023 – LG Innotek – Invested in next-generation wafer-level packaging lines – Boosts South Korea’s domestic capabilities in high-density 3D IC integration for consumer and industrial applications.
- Nov 2023 – Amkor Technology Korea – Acquired stake in local startup focused on via-last through-silicon vias (TSVs) – Accelerates development of high-density, scalable 3D interposers for mobile and AI chips.
Frequently Asked Questions
What is the South Korea 3D ICs Market?
The South Korea 3D ICs Market encompasses the industry focused on the design, manufacturing, and deployment of three-dimensional integrated circuits in South Korea's electronics and semiconductor sectors. It is pivotal in advancing high-density, high-performance chip solutions.
What is the current market size of South Korea 3D ICs Market?
As of 2026, the South Korea 3D ICs Market is valued at approximately USD 14.2 Billion. It reflects the rapid adoption of 3D packaging technologies driven by demand for mobile devices, AI applications, and high-performance computing within the country.
What factors are driving the South Korea 3D ICs Market?
The growth of the South Korea 3D ICs Market is propelled by advancements in semiconductor technology, demand for miniaturization, increasing integration of AI, IoT, and 5G components, along with government support through R&D initiatives and industry collaborations.
Which South Korean city leads the South Korea 3D ICs Market?
Seoul stands as the leading city in the South Korea 3D ICs Market, hosting major semiconductor manufacturers, research institutions, and financial hubs that foster innovation and investment in advanced chip packaging and 3D integration technologies.
Which segment is expected to grow the fastest?
The memory segment, particularly advanced 3D NAND flash stacks, is forecasted to exhibit the fastest growth, driven by rising storage demands across consumer electronics, data centers, and enterprise solutions in South Korea.
Who are the leading companies operating in the South Korea 3D ICs Market?
Key players include Samsung Electronics, SK Hynix, and other multinational semiconductor firms engaged in developing cutting-edge 3D IC packaging solutions, partnering with foundries and research institutes to stay at the forefront of industry innovation.
Analyst Perspective
The South Korea 3D ICs market is poised for sustained growth driven by rapid advancements in semiconductor technology and increasing demand for high-performance computing and mobile devices. Long-term, the market is expected to benefit from ongoing innovation in through-silicon vias (TSVs) and wafer bonding techniques, which will enhance integration density and power efficiency. Commercial opportunities are particularly attractive in Seoul and Pangyo, where major chip manufacturers and research institutes drive innovation and deployment. Investment priorities should focus on expanding fabrication capacity, developing next-generation interconnects, and fostering collaborations between industry and academia. Despite high competition, South Korea’s established semiconductor ecosystem provides a strategic advantage for market entrants. City-level growth prospects remain robust, especially in Seoul, which offers infrastructure, talent, and innovation clusters, and in Daegu, where emerging industrial zones support advanced manufacturing. Strategic positioning in these cities will be crucial for capturing long-term value and gaining a competitive edge in the evolving 3D IC landscape.
